
 Asia Pacific Sugar Confectionery Market | 2026-2036
Asia Pacific Sugar Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Sugar Confectionery Market Insights
Young adult gifting segments are rotating toward premium boxed assortments and seasonal limited editions across urban China and Southeast Asia. Mars Incorporated leverages its manufacturing scale to dominate chocolate-based gifting lines in tier-one Chinese cities. Mondelez International sustains competitive pressure through its deep convenience store penetration across India and ASEAN markets. Ferrero International SA differentiates via hazelnut-chocolate premium positioning that commands shelf space in airport duty-free and hotel retail channels.
Asia Pacific sugar confectionery comprises sweetened, shelf-stable products formulated with sucrose, glucose syrups, and functional additives, manufactured through cooking, depositing, or extrusion processes to achieve defined texture and mouthfeel parameters. The category serves impulse refreshment, emotional indulgence, and social gifting purposes across mass and premium tiers. Hard candy and chocolate segments anchor volume throughput in rural and lower-tier urban outlets where price elasticity remains acute. Chewing gum occupies a mature structural position in Japan and South Korea, while marshmallow formats are gaining traction as bakery inclusions and beverage toppings in Indonesia and the Philippines.
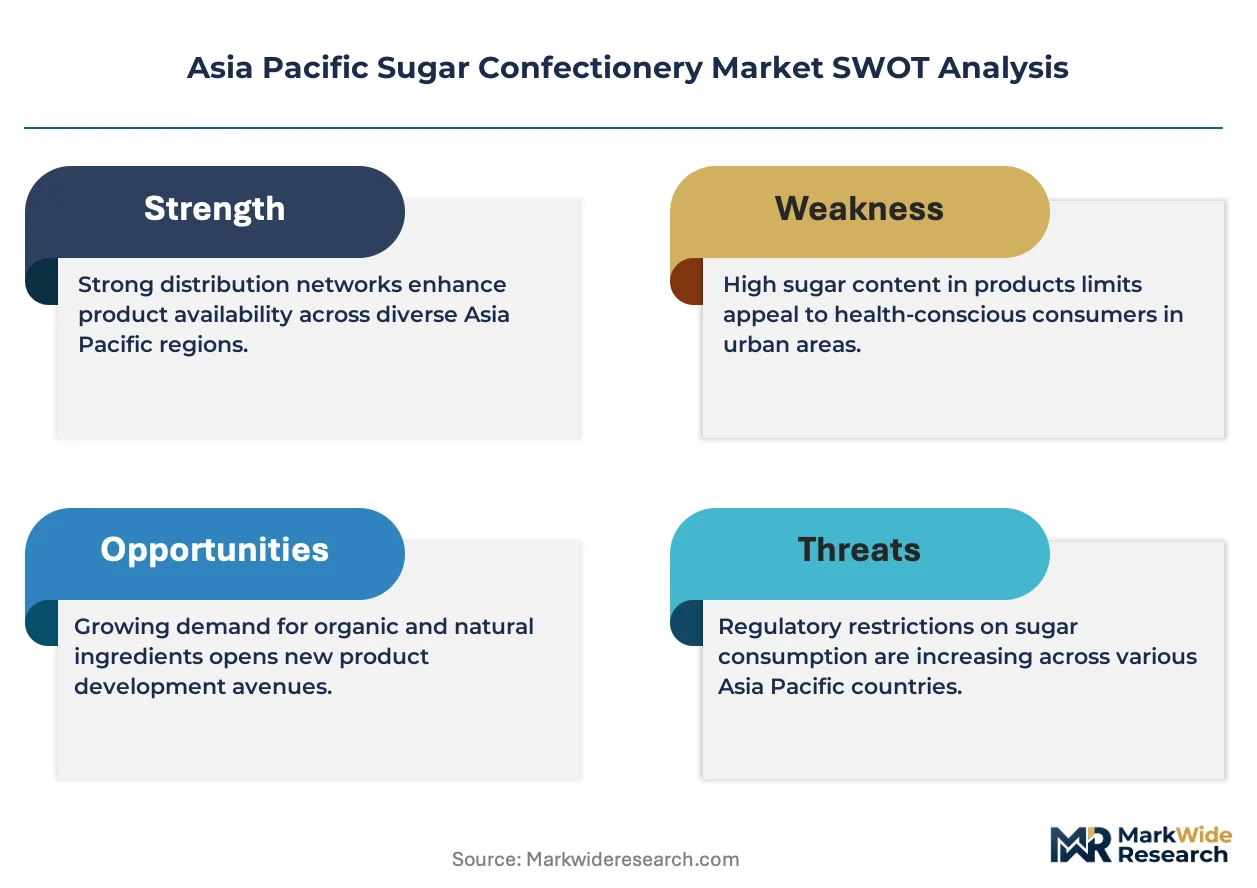
FSSAI in India enforces progressively stricter sugar labeling and front-of-pack warning requirements that force reformulation toward reduced-sucrose recipes. China's SAMR monitors additive compliance and nutritional claims with escalating post-market surveillance that raises compliance costs for imported brands. EFSA-aligned standards through ANZFS influence Australian and New Zealand import protocols, creating divergent technical file demands across the region. Stakeholders must decide whether to pursue unified regional formulations or accept fragmented SKU complexity driven by these diverging regulatory trajectories.
Market Dynamics
FSSAI labeling mandates in India and SAMR additive surveillance in China are forcing simultaneous reformulation and SKU proliferation across Asia Pacific sugar confectionery supply chains. These regulatory pressures compound with working adult gifting demand to reshape competitive investment priorities.
Growth Catalysts
- Premium Gifting Demand:Working adults in urban China and Southeast Asia are purchasing boxed assortments and seasonal limited editions, expanding the addressable market for higher-margin formats.
- Hard Candy Concentration:Indonesia and Vietnam are becoming demand centers for affordable hard candy and chewy formats, anchoring volume throughput in lower-tier retail channels.
- Functional Additive Integration:Glucose syrups and texture-modifying hydrocolloids are enabling manufacturers to meet reduced-sucrose targets without sacrificing mouthfeel parameters.
Market Restraints
- Raw Material Volatility:Sucrose and glucose syrup prices fluctuate with Indian monsoon patterns and Brazilian harvest cycles, compressing margin predictability for regional formulators.
- Regulatory Fragmentation:Divergent FSSAI, SAMR, and ANZFS technical file requirements prevent unified regional formulations, forcing SKU complexity and compliance cost escalation.
- Chewing Gum Saturation:Japan and South Korea exhibit mature structural positions in chewing gum, limiting volume expansion potential in these high-income markets.
Strategic Opportunities
- Marshmallow Format Expansion:Bakery inclusions and beverage topping applications in Indonesia and the Philippines represent underpenetrated usage occasions beyond traditional snacking.
- Front-of-Pack Reformulation:FSSAI warning label requirements create first-mover advantage for brands achieving reduced-sucrose recipes ahead of enforcement deadlines.
- Duty-Free Channel Penetration:Airport and hotel retail formats in tier-one Chinese cities offer premium positioning escape from mass-market price elasticity.
Industry Challenges
- Compliance Timeline Compression:SAMR post-market surveillance escalation demands faster technical file preparation and additive verification cycles for imported brands.
- Legacy Equipment Retrofit Costs:Deposit and extrusion lines require capital-intensive modification to handle reformulated reduced-sucrose and alternative syrup viscosities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Sugar Confectionery Market |
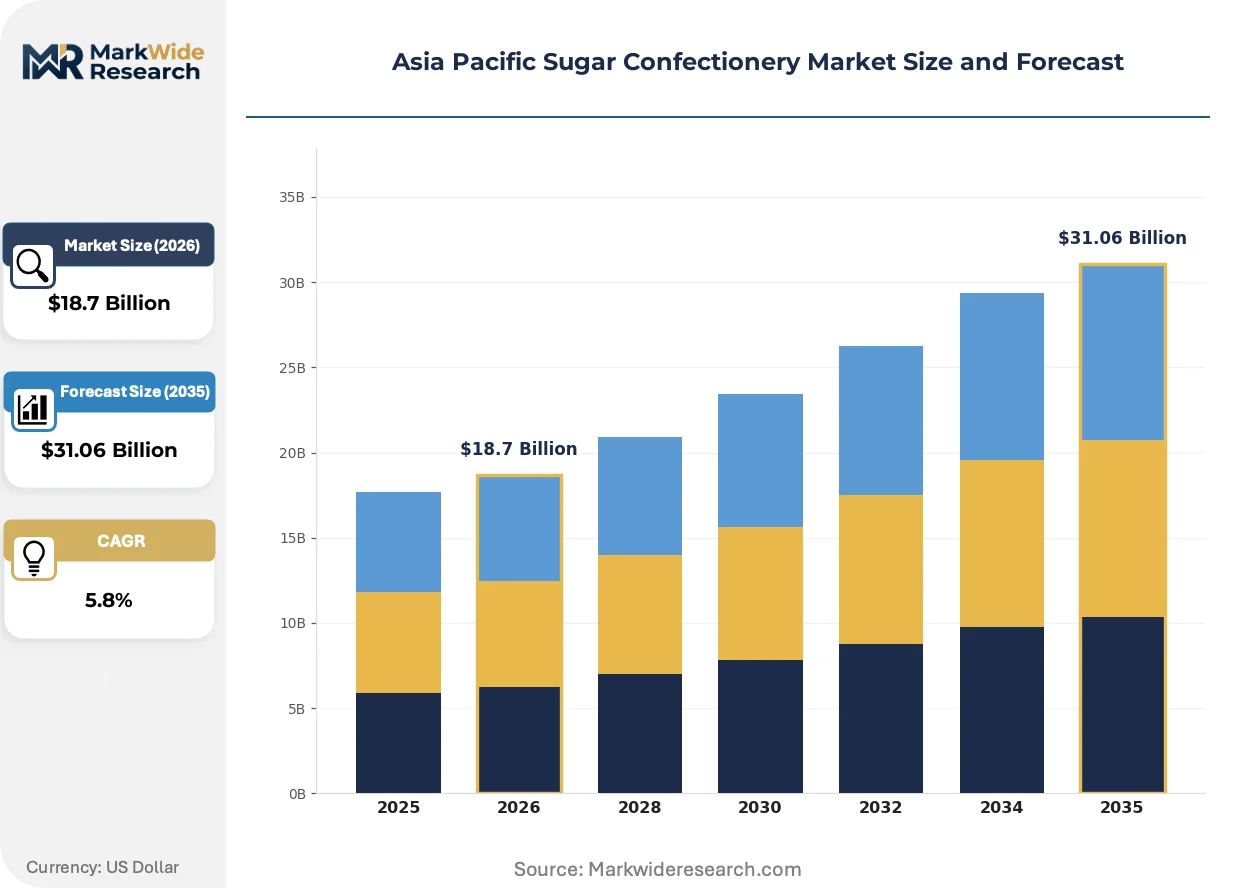
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Candy, Chewing Gum, Chocolate, Marshmallow Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Children, Teenagers, Adults, Seniors Flavor Profile: Fruity, Minty, Chocolatey, Sour |
| Companies Covered | Mars Incorporated, Mondelez International Inc., Ferrero International SA, Perfetti Van Melle Holding B.V., Haribo GmbH & Co. KG, Lotte Confectionery Co. Ltd., Morinaga & Co. Ltd., Meiji Holdings Co. Ltd., Hsu Fu Chi International Holdings Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Sugar Confectionery Market Trends and Innovations
Active reformulation, regulatory surveillance technology, and channel-specific format development are compressing product development cycles across Asia Pacific sugar confectionery. These forces demand simultaneous investment in compliance infrastructure and consumer-facing innovation.
Encapsulation technology for flavor stability and controlled release is miniaturizing batch-scale processes into continuous manufacturing lines. Mid-tier manufacturers in Thailand and Malaysia are adopting these systems to reduce changeover downtime between seasonal SKUs. This compression is enabling faster response to limited-edition gifting windows without dedicated production assets.
FSSAI front-of-pack sugar warning requirements are mandating reformulation investments that favor domestic Indian manufacturers with localized R&D infrastructure. Imported brands face extended compliance timelines and reformulation costs that erode price competitiveness in mass-market channels. The hard candy and chewy segments are most affected, with manufacturers accelerating alternative sweetener trials.
Convenience store chains across India and ASEAN markets are consolidating shelf space decisions through centralized category management functions. This concentration is displacing traditional distributor-led placement models and demanding direct manufacturer relationships with standardized trade terms. The shift is most visible in India, where Mondelez and Mars have built dedicated key account teams for modern trade negotiation.
Asia Pacific Sugar Confectionery Market Segmentation
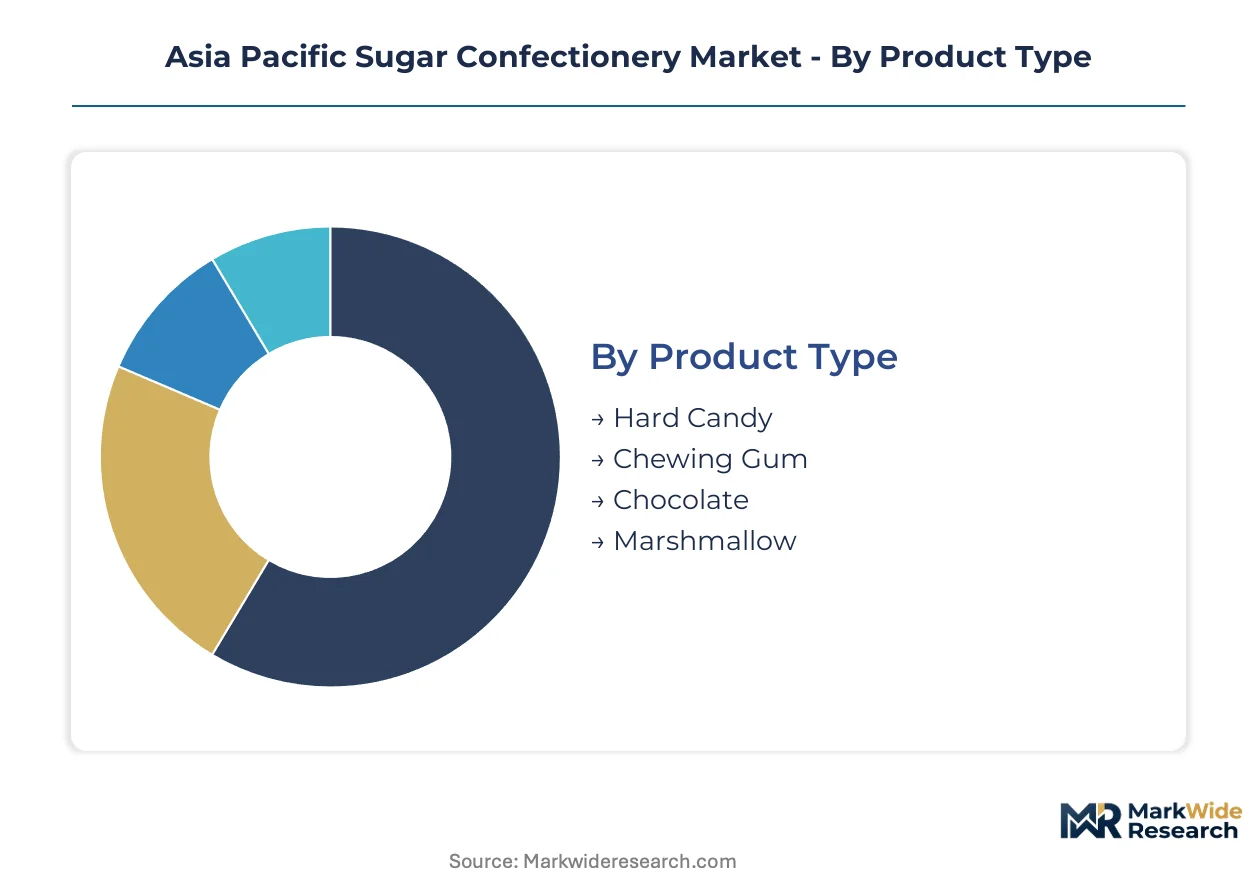
Sugar confectionery segmentation in Asia Pacific reflects divergent consumption occasions across income tiers and regulatory environments. Product format, channel access, and demographic targeting determine margin structures and compliance burdens for manufacturers operating across FSSAI, SAMR, and ANZFS jurisdictions.
Product Type:
Domestic production anchors hard candy and chewing gum volumes across India, Indonesia, and Vietnam, while chocolate and marshmallow formats increasingly serve export-led premium positioning into tier-one Chinese cities and ASEAN duty-free channels.
- Hard Candy:Formulated with sucrose and glucose syrup matrices cooked to glass-phase stability for extended shelf life. Demand concentrates in rural Indonesia and Vietnam where price elasticity dictates single-unit sachet formats; FSSAI sugar warning mandates are accelerating reformulation trials with reduced-sucrose recipes and alternative bulking agents.
- Chocolate:Cocoa butter and cocoa mass suspensions with defined particle size distributions for snap and melt profiles. Premium gifting demand in urban China and Southeast Asian airport retail commands boxed assortments and seasonal limited editions; Mars and Ferrero manufacturing scale dominates tier-one city distribution.
- Chewing Gum:Elastomer gum bases with encapsulated flavor systems for controlled release. Japan and South Korea represent mature structural positions with replacement-driven consumption rather than volume expansion.
- Marshmallow:Aerated glucose-syrup and gelatin matrices with defined density parameters. Bakery inclusions and beverage topping applications in Indonesia and the Philippines extend usage occasions beyond traditional snacking.
Hard candy commands the established base across lower-tier retail channels. The steepest expansion runs through chocolate formats serving premium gifting occasions.
Distribution Channel:
Channel cost tiers stratify between mass-market throughput formats and premium positioning venues, with modern trade consolidation reshaping manufacturer negotiation leverage across India and ASEAN markets.
- Supermarkets:Standardized planogram-driven shelf space with centralized category management functions. Mondelez and Mars have built dedicated key account teams for modern trade negotiation in India.
- Convenience Stores:High-frequency impulse purchase environments with localized assortment optimization. Centralized purchasing decisions are displacing traditional distributor-led placement models across ASEAN markets.
- Online Retail:Direct-to-consumer fulfillment with expanded assortment breadth beyond physical shelf constraints. Premium gifting formats achieve penetration into tier-two and tier-three Chinese cities without brick-and-mortar presence.
- Specialty Stores:Curated premium and import-focused assortments with higher service intensity. Airport duty-free and hotel retail channels in tier-one Chinese cities offer margin escape from mass-market price elasticity.
Supermarkets anchor volume throughput with standardized terms. Specialty stores are climbing the fastest as premium positioning vehicles.
End User:
Demographic targeting aligns formulation intensity and pack sizing with distinct consumption occasions across life stages, from parental-controlled children's portions to self-directed adult indulgence and gifting.
- Children:Portion-controlled single-serve formats with vibrant colorants and licensed character packaging. Parental purchase decisions in India face escalating FSSAI front-of-pack sugar warning visibility.
- Teenagers:Social consumption and peer-sharing occasions driving novelty format trials. Sour flavor profiles and interactive packaging elements gain traction in Indonesia and Philippines convenience channels.
- Adults:Working professional gifting demand for boxed assortments and seasonal limited editions across urban China and Southeast Asia. Premium price acceptance supports higher-margin format development.
- Seniors:Texture-modified formats with softer chew parameters and reduced sweetness intensity. Functional positioning with added ingredients targets health-conscious aging populations in Japan and South Korea.
Adult segments command the established base through gifting volume. Teenager-oriented formats are expanding most quickly via social sharing dynamics.
Flavor Profile:
Flavor application patterns track regional palate preferences and usage occasion temperature, with fruit-derived profiles dominating tropical climates and mint formulations serving refreshment positioning in temperate zones.
- Fruity:Natural and nature-identical flavor systems derived from citrus, berry, and tropical fruit profiles. Hard candy and chewy formats in Indonesia, Vietnam, and Philippines concentrate demand for mango, lychee, and calamansi variants.
- Minty:Menthol and peppermint cooling agents for breath-freshening positioning. Chewing gum saturation in Japan and South Korea anchors this profile's mature structural position.
- Chocolatey:Cocoa-derived flavor compounds across milk, dark, and white chocolate matrices. Premium gifting assortments in urban China combine chocolatey bases with nut inclusions and caramel layers.
- Sour:Acidulant-coated formats with citric or malic acid surface application for initial tartness release. Teenager-targeted innovation in Thailand and Malaysia drives format experimentation with layered sour-sweet transitions.
Fruity profiles command the established base across tropical markets. Sour formulations are gaining share fastest through teenager-targeted innovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand exports hard candy and glucose syrup formulations to Vietnam and Indonesia, anchoring a southbound trade corridor that supplies lower-tier retail channels across Southeast Asia. This flow concentrates manufacturing investment in Thai industrial zones while shaping competitive dynamics in receiving markets.
China
Premium gifting demand from working adults in Shanghai and Beijing drives boxed chocolate assortment sales through airport duty-free and hotel retail channels. SAMR escalates post-market surveillance on additive compliance and nutritional claims, forcing imported brands to accelerate technical file preparation. Yangtze River Delta manufacturing clusters near Suzhou produce reformulated reduced-sucrose lines for domestic distribution.
India
Hard candy and chewy formats dominate rural and lower-tier urban outlets where single-unit sachet pricing prevails. FSSAI front-of-pack sugar warning mandates tighten formulation standards and compress compliance timelines for domestic and imported brands alike. Maharashtra industrial corridors near Pune and Mumbai host concentrated confectionery manufacturing serving both domestic mass markets and export preparation.
Indonesia
Affordable hard candy and marshmallow formats anchor volume throughput in traditional trade channels across Java and Sumatra. The national food and drug regulator enforces progressively stricter halal certification requirements that reshape supply chain sourcing for gelatin and flavor additives. Surabaya manufacturing clusters specialize in tropical fruit-profile hard candy for domestic consumption and regional export.
Japan
Chewing gum occupies a mature structural position with replacement-driven consumption rather than volume expansion in Tokyo and Osaka metropolitan areas. METI monitors food additive standards through alignment with international Codex frameworks. Chubu region manufacturing near Nagoya maintains specialized elastomer gum base production for functional breath-freshening and dental positioning variants.
Vietnam
Hard candy demand concentrates in rural provinces where price elasticity dictates accessible single-serve formats. The Ministry of Health issues circulars on sugar content labeling that follow regional ASEAN harmonization trajectories. Ho Chi Minh City industrial zones host both domestic manufacturers and contract production facilities serving Thai and Indonesian brand owners.
Asia Pacific Sugar Confectionery Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions, producing a tiered structure where scale-driven multinationals face agile regional challengers. The market stratifies into three archetypes: integrated global confectioners with manufacturing depth, specialist premium-positioned houses, and domestic cost-optimized formulators. Capacity expansion and portfolio diversification constitute the dominant competitive moves, with players retrofitting deposit and extrusion lines for reformulated viscosities while extending format ranges into gifting and functional positioning.
Among integrated global confectioners, Mars Incorporated and Mondelez International occupy positions exemplifying manufacturing scale and convenience store penetration archetypes respectively. Ferrero International SA represents the premium-tier specialist model through hazelnut-chocolate positioning that commands differentiated shelf space. These three anchors illustrate how competitive advantage in Asia Pacific sugar confectionery derives from channel-specific execution rather than unified regional formulation strategies.
| Leading Market Players |
|---|
| Mars Incorporated |
| Mondelez International Inc. |
| Ferrero International SA |
| Perfetti Van Melle Holding B.V. |
| Haribo GmbH & Co. KG |
| Lotte Confectionery Co. Ltd. |
| Morinaga & Co. Ltd. |
| Meiji Holdings Co. Ltd. |
| Hsu Fu Chi International Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
FSSAI front-of-pack sugar warning requirements gate both supplier qualification and price tier differentiation across Asia Pacific sugar confectionery, forcing domestic Indian manufacturers with localized R&D infrastructure to capture compliance-first positioning while imported brands absorb extended timelines that erode mass-market competitiveness.
Pricing Analysis
Legacy sucrose-based formulations, reduced-sucrose reformulations, and next-generation alternative-sweetener lines command widening price spreads across the analysis window. Three-tier pricing structure across premium, standard, and economy levels separates airport duty-free boxed assortments from modern trade standard formats and rural single-unit sachets. Price differentiation rests on FSSAI compliance status and manufacturing scale. Cost compression in economy-tier hard candy intensifies because raw material volatility from Brazilian harvest cycles squeezes margin predictability. Rural Indonesian and Vietnamese consumers exhibit acute price sensitivity, while working adults in tier-one Chinese cities accept premium positioning for gifting occasions.
Supply Chain Analysis
Thailand and India anchor glucose syrup and hard candy production for Southeast Asian and domestic Indian markets respectively. Manufacturing draws from sucrose and glucose syrup feedstocks tethered to Indian monsoon patterns and Brazilian agricultural cycles. Single-source vulnerability concentrates in elastomer gum base supply from Japanese Chubu region specialists serving functional chewing gum formats. Distribution runs through centralized category management functions at modern trade chains across India and ASEAN markets, displacing traditional distributor-led placement models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific sugar confectionery rewards manufacturers possessing integrated reformulation capabilities and regulatory compliance infrastructure, with scarcity clustering around FSSAI-ready reduced-sucrose R&D assets that domestic Indian players and Thai export specialists have built ahead of enforcement deadlines.
For Market Incumbents: Compound manufacturing scale advantages through dedicated key account teams for modern trade negotiation in India and ASEAN markets. Accelerate deposit and extrusion line retrofitting to handle reformulated viscosities before SAMR surveillance escalation compresses compliance timelines for imported brands. Channel control through direct retailer relationships defends against distributor displacement. For New Entrants and Emerging Players: Anchor in marshmallow format expansion for bakery inclusions and beverage topping applications across Indonesia and the Philippines, the most penetrable white-space beyond traditional snacking occasions. Target teenager-oriented sour format innovation in Thailand and Malaysia convenience channels. A go-to-market angle through social-sharing packaging design bypasses incumbent shelf space dominance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across reduced-sucrose reformulation infrastructure as FSSAI and SAMR mandates accelerate equipment replacement cycles. Long-term viability over the next decade favors acquisition targets possessing captive glucose syrup supply and localized regulatory affairs capabilities. The signal to watch is front-of-pack warning label enforcement velocity as a margin compression indicator for import-dependent brands.| Strategic Initiative | Industry Significance |
|---|---|
| Reduced-Sucrose Reformulation | FSSAI compliance deadlines force recipe redevelopment ahead of warning label mandates. |
| Modern Trade Direct Negotiation | Centralized category management at Indian and ASEAN chains displaces distributor intermediation. |
| Duty-Free Channel Penetration | Airport and hotel retail in tier-one Chinese cities escape mass-market price elasticity. |
| Marshmallow Format Expansion | Bakery inclusions and beverage toppings in Indonesia and Philippines extend usage occasions. |
| Encapsulation Technology Adoption | Continuous manufacturing lines in Thailand and Malaysia compress seasonal SKU changeover downtime. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FSSAI regulatory filings, SAMR additive surveillance notices, Nielsen retail audit data, and customs trade records. Conversations with brand managers, category buyers at modern trade chains, supply planners, and regulatory affairs directors at confectionery manufacturers informed demand and compliance dynamics. Bottom-up volume modeling triangulates against top-down value estimates derived from production cluster capacity assessments.
Segmentation dimensions modeled span product type, distribution channel, end user demographic, and flavor profile across the projection horizon. CAGRs derive from trend extrapolation calibrated to regulatory enforcement timelines and gifting occasion expansion patterns. Forecast inputs incorporate FSSAI sugar warning phase-in schedules and SAMR post-market surveillance escalation trajectories.
Decision-makers should treat outputs as directional under assumptions of steady regulatory enforcement velocity and raw material price correlation patterns; material deviation would warrant model refresh. Specific risks that could revise forecasts include accelerated FSSAI warning label mandates, Brazilian harvest cycle disruption, and modern trade consolidation pace. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Macarons Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Black Treacle Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Global Chocolate Market
Confectionery
Sugar-Free Gummy Market
Confectionery
Citrus Gummies Market
Confectionery
North America Compound Chocolate Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
Italy Chocolate Market
Confectionery
Low-Fat Candy Market
Confectionery
Salted Caramel Products Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Functional Confectionery Market