
 Rare Sugar Market | 2026-2036
Rare Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Sugar Market Intelligence
EU F-Gas Regulation is decoupling refrigerant-dependent chemical synthesis from cost-competitive rare sugar production, forcing European processors toward enzymatic and fermentation-based pathways. Cargill leverages its corn wet-milling infrastructure to secure feedstock arbitrage for allulose output. Tate & Lyle PLC anchors European supply through its specialty carbohydrate portfolio. Matsutani Chemical Industry Co., Ltd. dominates Asian enzymatic conversion capacity with decades of rare sugar refining expertise.
Rare sugars constitute monosaccharide stereoisomers occurring in minute natural quantities, typically manufactured through enzymatic epimerization or microbial fermentation of common sugars like fructose and galactose, yielding sweeteners with 70-90% sucrose equivalence but negligible glycemic impact. D-Allulose leads product type traction due to its GRAS status and near-zero caloric contribution, while D-Tagatose retains pharmaceutical relevance for prebiotic applications. Enzymatic conversion commands processing technology investment as membrane separation advances reduce downstream purification costs.
FDA allulose labeling guidance, EU REACH chemical registration requirements, and Japan's FOSHU functional food claims framework collectively shape formulation standards and market access protocols across major demand centers. EMA and national European regulators scrutinize rare sugar pharmaceutical applications through Novel Food authorization pathways. Stakeholders must monitor evolving enzymatic patent landscapes and regional clean-label enforcement intensity to calibrate capacity deployment and partnership priorities.
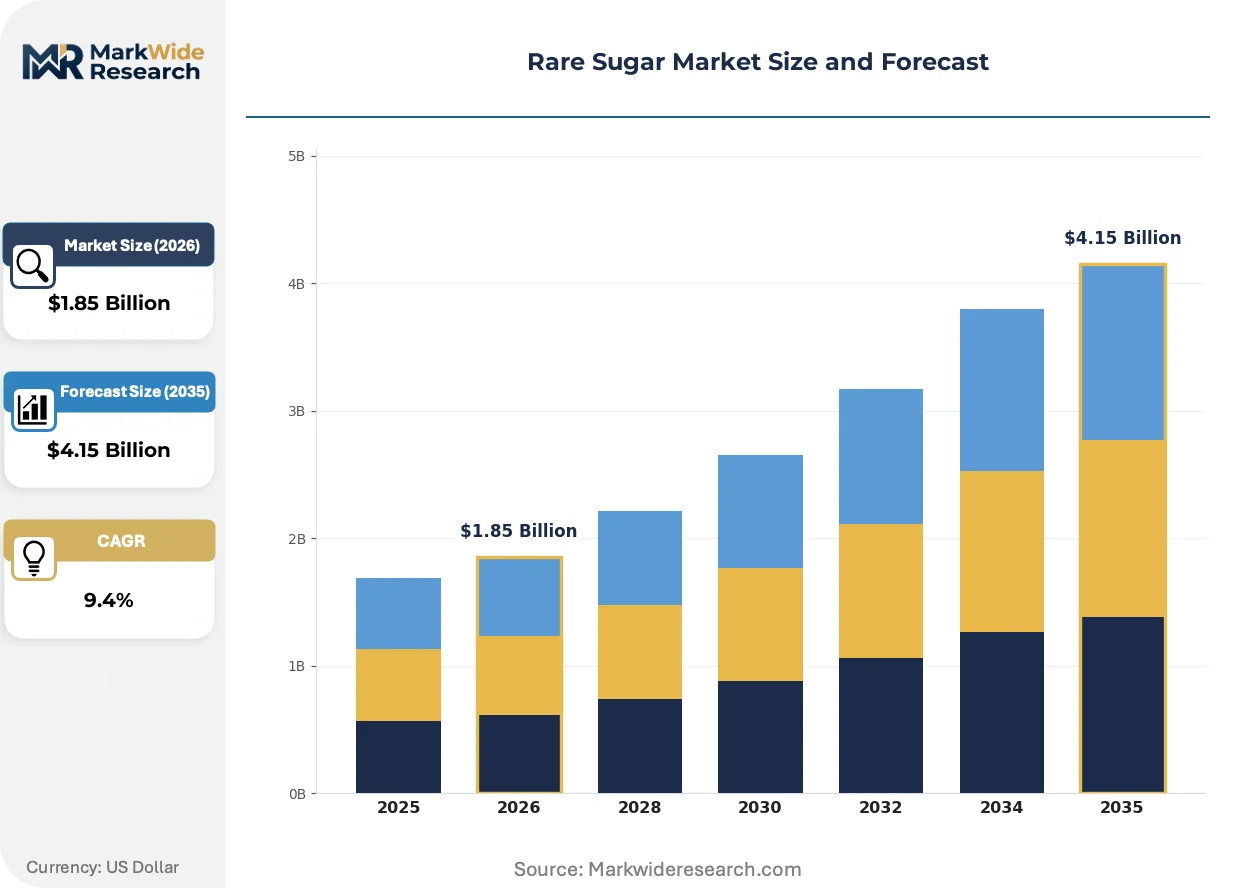
Market Dynamics
Enzymatic conversion technologies are compressing production economics and displacing legacy chemical synthesis routes, while FDA guidance on allulose labeling accelerates formulation adoption across North American beverage and confectionery manufacturers.
Growth Catalysts
- FDA Allulose Labeling Guidance:The United States regulator permits exclusion of allulose from total and added sugars declarations, enabling calorie-reduced product claims that drive reformulation in beverages and confectionery.
- Clean-Label Functional Foods:Manufacturers across bakery and dairy categories substitute rare sugars for high-intensity sweeteners to meet consumer demand for recognizable ingredient panels.
- Enzymatic Epimerization:Advances in immobilized enzyme systems reduce conversion costs and expand commercial viability for D-allulose and D-tagatose production.
Market Restraints
- Corn Feedstock Volatility:Drought conditions in the United States Midwest elevate fructose input costs and compress processor margins.
- EU F-Gas Regulation:The European Union chemical framework decouples refrigerant-dependent synthesis from cost-competitive production, forcing regional processors toward fermentation-based pathways with higher capex requirements.
- High-Intensity Sweetener Substitution:Stevia and monk fruit extracts compete on cost-per-sweetness-equivalent in price-sensitive beverage applications.
Strategic Opportunities
- Japan FOSHU Framework:The country's functional food claims system enables premium positioning for rare sugars with documented glycemic or prebiotic benefits.
- Pharmaceutical Prebiotic Applications:D-tagatose demonstrates therapeutic potential for gut microbiome modulation, opening prescription and nutraceutical channels beyond conventional food use.
- Membrane Separation Convergence:Integration of nanofiltration with continuous enzymatic reactors reduces downstream purification costs and water usage.
Industry Challenges
- Enzyme Engineering Talent Scarcity:Protein design and immobilization chemistry expertise concentrates at specialized biotechnology institutes and contract research organizations.
- Novel Food Authorization Timelines:EMA and national European regulators require extensive toxicology dossiers, delaying market entry for new rare sugar variants by 18-36 months.
- Patent Landscape Complexity:Overlapping intellectual property on epimerase enzymes and bioreactor designs generates licensing disputes between established processors and emerging entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Sugar Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: D-Tagatose, D-Allulose, D-Trehalose, D-Psicose, D-Sorbose Application: Functional Foods, Pharmaceuticals, Cosmetics, Feed Additives End User: Food Manufacturers, Pharmaceutical Companies, Nutraceutical Producers, Personal Care Brands Processing Technology: Enzymatic Conversion, Chemical Synthesis, Microbial Fermentation, Membrane Separation |
| Companies Covered | Cargill, Tate & Lyle PLC, DuPont de Nemours Inc., Daesang Corporation, Samyang Corporation, Matsutani Chemical Industry Co., Ltd., Bonumose, Roquette Frères, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Sugar Market Strategic Shifts & Innovations
Bioprocess intensification and regulatory clarity are converging to transform rare sugar from specialty ingredient to mainstream formulation tool, with downstream purification and clean-label positioning as the primary battlegrounds.
Continuous enzymatic conversion with immobilized D-psicose 3-epimerase is unifying upstream reaction and downstream separation into single-unit operations. Beverage manufacturers in the United States and Japan adopt these systems at pilot scale, compressing capital requirements and enabling distributed production closer to formulation facilities. This technology is unifying process economics previously separated between large centralized refiners and regional compounders.
EU REACH chemical registration requirements now mandate full substance dossiers for rare sugars imported above one tonne annually. The European Chemicals Agency enforcement tightens traceability obligations, pushing importers toward vertically integrated fermentation partnerships with established EU-based carbohydrate processors. Specialty confectionery and clinical nutrition segments bear the highest compliance burden, accelerating supplier consolidation toward entities with in-house regulatory affairs capabilities.
Clean-label procurement criteria now prioritize ingredient provenance and processing transparency over unit cost in premium positioned products. North American natural and organic retailers demand enzymatic conversion disclosure, displacing chemically synthesized rare sugars from their approved supplier lists. This pattern concentrates in United States coastal metropolitan markets and Canadian urban centers, where consumer willingness-to-pay for processing narrative exceeds 15% price premiums.
Rare Sugar Market Segmentation
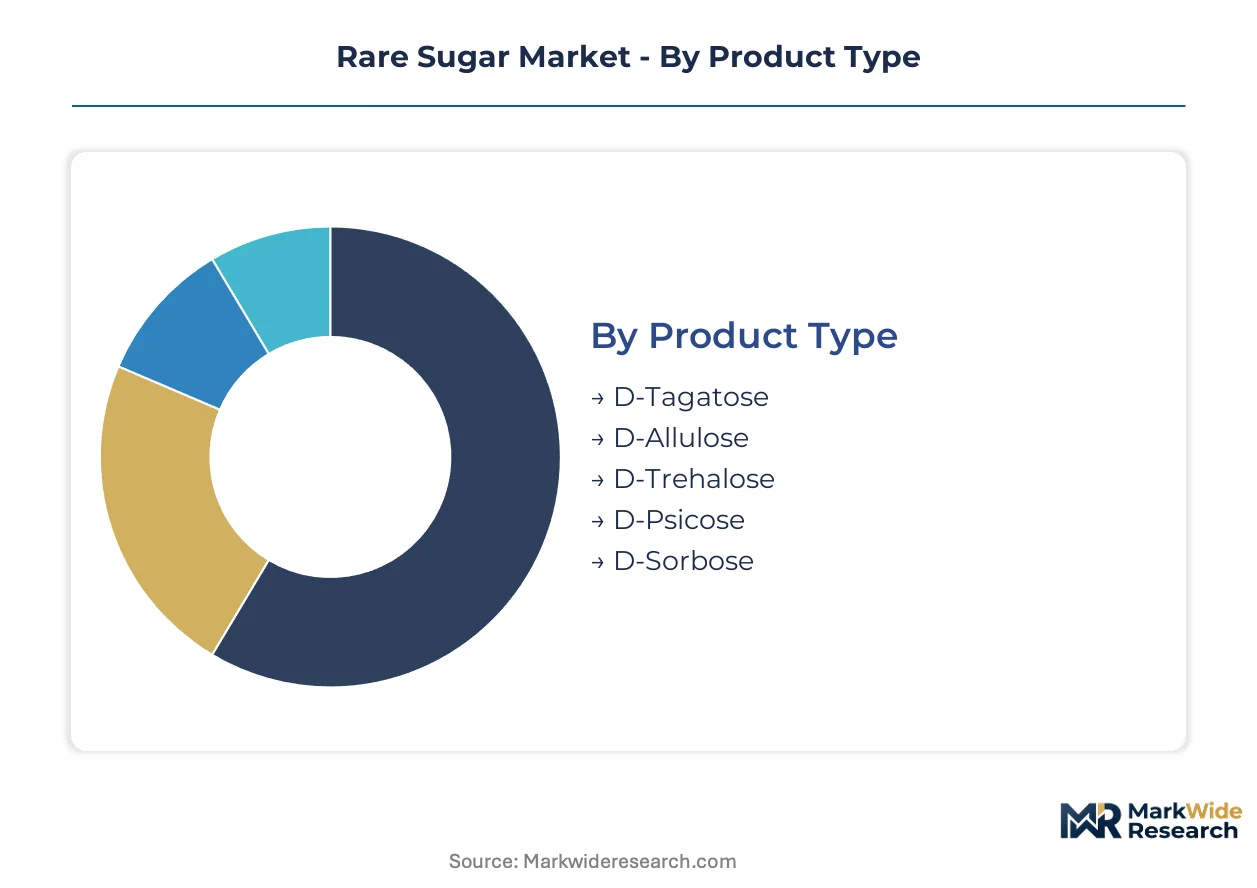
Rare sugar segmentation reflects divergent technical maturity and regulatory clearance timelines across product types and processing pathways. Manufacturers calibrate portfolio mix against enzymatic conversion economics and regional Novel Food authorization status.
Product Type:
Volume concentration sits with GRAS-affirmed variants while premium positioning attaches to prebiotic and pharmaceutical-grade alternatives.
- D-Allulose:Near-zero caloric monosaccharide with 70% sucrose sweetness equivalence. FDA labeling guidance excluding it from added sugars declarations drives reformulation across United States beverage and confectionery manufacturers seeking calorie-reduced claims.
- D-Tagatose:Prebiotic rare sugar with demonstrated gut microbiome modulation properties. Pharmaceutical and nutraceutical channels in Japan's FOSHU framework absorb output as functional food claims command 15-20% price premiums over standard sweeteners.
- D-Trehalose:Cryoprotectant disaccharide stabilizing proteins and lipids in cosmetic and clinical nutrition applications.
- D-Psicose:Stereoisomer of fructose with identical sweetness profile but minimal metabolic impact; enzymatic production scaling lags allulose commercialization.
- D-Sorbose:Precursor for vitamin C synthesis with limited direct food application; pharmaceutical intermediate demand dominates offtake.
Today's leader: D-Allulose. Tomorrow's challenger: D-Tagatose.
Application:
End-use segmentation tracks clean-label enforcement intensity and reimbursement pathway availability across food, pharmaceutical, and adjacent sectors.
- Functional Foods:Bakery, dairy, and beverage reformulation substituting rare sugars for high-intensity sweeteners to meet recognizable ingredient panel demands. North American natural retailers now require enzymatic conversion disclosure, displacing chemically synthesized variants from approved supplier lists in coastal metropolitan markets.
- Pharmaceuticals:D-tagatose prebiotic applications and D-sorbose vitamin C precursors anchor prescription and clinical nutrition demand. EMA Novel Food authorization timelines extend 18-36 months, delaying European market entry for new therapeutic indications.
- Cosmetics:D-trehalose moisture retention and protein stabilization properties support premium skincare formulation.
- Feed Additives:Emerging segment leveraging glycemic control properties for livestock metabolic health management.
Functional foods expand most quickly on clean-label tailwinds; pharmaceuticals retain margin concentration on regulatory moats.
End User:
Customer type segmentation distinguishes between formulation-scale buyers with in-house regulatory affairs capabilities and compounders dependent on supplier documentation.
- Food Manufacturers:Large-scale beverage and confectionery processors with direct FDA engagement capacity. Cargill and Tate & Lyle PLC anchor procurement through integrated corn wet-milling and specialty carbohydrate infrastructure.
- Pharmaceutical Companies:Clinical nutrition and prescription drug developers requiring EMA-toxicology dossiers and batch-specific certificates of analysis.
- Nutraceutical Producers:Japan FOSHU framework participants and North American dietary supplement formulators seeking glycemic or prebiotic positioning claims.
- Personal Care Brands:Premium cosmetic manufacturers sourcing D-trehalose for humectant and stabilizer applications.
Food manufacturers dominate volume offtake; pharmaceutical companies capture value concentration on specification stringency.
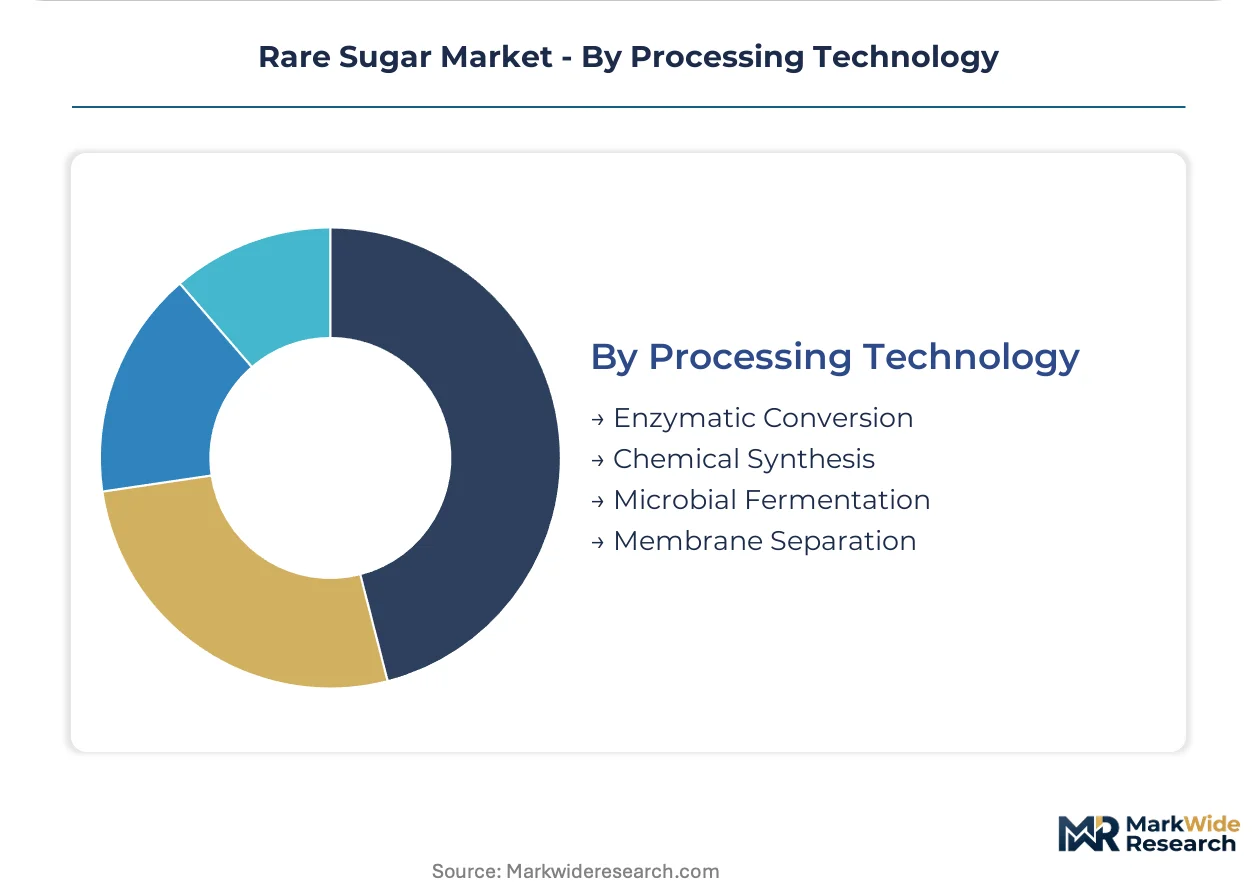
Processing Technology:
Technology choice determines capital intensity, feedstock flexibility, and regulatory compliance burden across production pathways.
- Enzymatic Conversion:Immobilized D-psicose 3-epimerase systems now unify upstream reaction and downstream separation into continuous single-unit operations. United States and Japan beverage manufacturers deploy these at pilot scale, compressing capital requirements and enabling distributed production proximate to formulation facilities.
- Chemical Synthesis:Refrigerant-dependent epimerization routes face EU F-Gas Regulation decoupling from cost-competitive production, forcing European processors toward alternative pathways with higher capex requirements.
- Microbial Fermentation:Yeast and bacterial strain engineering for direct rare sugar production from lignocellulosic feedstocks; enzyme engineering talent scarcity concentrates development at specialized biotechnology institutes.
- Membrane Separation:Nanofiltration integration with continuous enzymatic reactors reduces downstream purification costs and water usage, advancing process intensification economics.
Enzymatic conversion commands investment flows; membrane separation convergence shapes next-generation cost structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Protein design and immobilization chemistry expertise concentrates at specialized biotechnology institutes in the United States, Japan, and Germany, anchoring enzymatic conversion capacity near major formulation demand centers.
United States
Beverage and confectionery manufacturers in Chicago and Atlanta drive reformulation demand for calorie-reduced claims. FDA guidance excluding allulose from added sugars declarations accelerates adoption across national brand portfolios. Corn wet-milling infrastructure in the Midwest secures fructose feedstock arbitrage for domestic enzymatic producers.
Japan
Functional food claims under the FOSHU framework command premium positioning for glycemic and prebiotic benefits. METI and PMDA coordinate on Novel Food authorization pathways for new rare sugar variants. Osaka and Nagoya host decades of rare sugar refining expertise at established enzymatic conversion facilities.
Germany
Specialty carbohydrate processors face EU F-Gas Regulation constraints on refrigerant-dependent synthesis routes. ECHA REACH enforcement tightens traceability obligations for imported rare sugars above one tonne annually. North Rhine-Westphalia anchors European supply through integrated fermentation partnerships with regional compounders.
South Korea
Clinical nutrition developers in Seoul and Busan seek batch-specific certificates of analysis for pharmaceutical-grade rare sugars. MFDS scrutinizes prebiotic applications through extended toxicology dossier requirements. Domestic enzyme engineering programs at national research institutes narrow talent scarcity gaps.
China
SAMR and NMPA coordinate on dual carbon goals affecting fermentation-based pathway energy inputs. Yangtze River Delta chemical processors evaluate membrane separation integration for downstream purification cost reduction. Shanghai and Jiangsu province concentrate pilot-scale continuous enzymatic reactor deployment.
Rare Sugar Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across enzymatic conversion and downstream formulation channels. The vendor base stratifies between corn wet-milling majors with captive feedstock access and biotechnology startups with novel epimerase patents. Three archetypes dominate: integrated agribusiness processors, Asian enzymatic conversion specialists, and European fermentation technology developers. Capacity expansion and strategic licensing partnerships constitute the dominant competitive moves as enzyme engineering talent scarcity intensifies.
Among integrated agribusiness processors, Cargill and Tate & Lyle PLC occupy positions anchored by corn wet-milling infrastructure and specialty carbohydrate portfolios. Matsutani Chemical Industry Co., Ltd. exemplifies the Asian enzymatic conversion specialist archetype with decades of rare sugar refining expertise. These three entities represent distinct geographic and technological positioning strategies across North American, European, and Asian supply corridors.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle PLC |
| DuPont de Nemours Inc. |
| Daesang Corporation |
| Samyang Corporation |
| Matsutani Chemical Industry Co., Ltd. |
| Bonumose |
| Roquette Frères |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
GRAS-certified allulose versus prebiotic-grade tagatose bifurcation manifests in divergent procurement economics and supply chain architectures, with FDA-exempt status commanding contract premiums while EMA Novel Food authorization timelines tether European pharmaceutical-grade output to specialized fermentation partnerships in Germany and the Netherlands.
Pricing Analysis
Bundled regulatory documentation and unbundled commodity supply splits the market into two distinct procurement modes. Three-tier pricing structure across premium pharmaceutical-grade, standard food-grade, and economy feed-grade levels reflects certification burden and batch-specific analytical requirements. Pricing pressure stems from high-intensity sweetener substitution in United States beverage applications, where stevia and monk fruit extracts undercut rare sugars on cost-per-sweetness-equivalent. Food manufacturers exhibit highest price sensitivity due to reformulation volume scale, while pharmaceutical companies absorb premiums for toxicology dossier completeness.
Supply Chain Analysis
Enzyme engineering talent scarcity in United States biotechnology institutes and Japanese national research programs constrains capacity expansion timelines. Supply concentrates in the United States, Japan, and Germany, with corn wet-milling infrastructure anchoring North American feedstock security and Osaka-based enzymatic conversion facilities dominating Asian output. Raw material dependencies center on fructose syrup from Midwest corn processors, immobilized D-psicose 3-epimerase from specialized biotech suppliers, and nanofiltration membranes from German engineering firms. Single-source vulnerability in epimerase enzyme supply generates licensing disputes between established processors and emerging entrants. Distribution runs through integrated agribusiness processors with captive regulatory affairs capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rare sugar market functions as a stable compounder anchored by irreversible clean-label reformulation trends across North American and Japanese food manufacturing.
For Market Incumbents: Deepen backward integration into immobilized enzyme production to secure supply chain control against emerging biotech entrants with novel epimerase patents. Expand fermentation partnerships in North Rhine-Westphalia to preempt EU F-Gas Regulation compliance costs. Prioritize in-house regulatory affairs capabilities to compress EMA Novel Food authorization timelines. For New Entrants and Emerging Players: Novel membrane separation convergence technologies offer entry leverage into distributed production proximate to United States beverage formulation facilities. Target clinical nutrition applications in South Korea and Japan where batch-specific certificates of analysis command 15-20% price premiums over standard food-grade supply. Pursue licensing partnerships with established enzymatic conversion specialists to bypass protein design talent scarcity. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology startups holding patent-protected epimerase variants and continuous reactor designs. The five-to-ten-year viability window favors entities with demonstrated FDA engagement capacity and established EMA toxicology dossier templates. Monitor enzyme engineering talent migration from national research institutes to commercial processors as inflection indicator for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Enzymatic Reactor Deployment | Unifies upstream conversion and downstream separation into single-unit operations, compressing capital requirements for United States beverage manufacturers. |
| Backward Integration into Enzyme Production | Secures captive supply of immobilized D-psicose 3-epimerase against licensing disputes and single-source vulnerability. |
| EMA Novel Food Authorization Investment | Accelerates market entry timelines for D-tagatose pharmaceutical applications through pre-submission toxicology dossier preparation. |
| Membrane Separation Technology Licensing | Reduces downstream purification costs and water usage in Yangtze River Delta processing facilities. |
| FOSHU Framework Partnership Development | Enables premium positioning for prebiotic rare sugars in Japanese functional food claims system. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with enzymatic conversion plant managers, specialty carbohydrate procurement leads at beverage manufacturers, regulatory affairs directors, and membrane separation technology suppliers with secondary validation against FDA GRAS notifications, EMA Novel Food authorization databases, United States customs trade data, and Japanese FOSHU registered product listings. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Comparable-period anchoring tied projection assumptions to historical enzymatic conversion cost curves and regulatory approval velocity across the analysis window. Segmentation modeling spanned product type, application, processing technology, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand functions incorporating clean-label enforcement intensity and corn feedstock price volatility as industry-specific inputs.
The model holds under stable FDA allulose labeling guidance and moderate corn belt precipitation patterns; deviation in EU F-Gas Regulation enforcement intensity or enzyme engineering talent availability would shift capacity expansion timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
High-Fructose Corn Syrup (HFCS) Market
Sweeteners
Sweeteners Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
United States Food Sweetener Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
France Food Sweetener Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
Organic Palm Sugar Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Mannitol Market
Sweeteners
Agave Syrup Market
Sweeteners
Europe Starch Sweetener Market