
 Crunchy Chocolate Market | 2026-2036
Crunchy Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Crunchy Chocolate Market Intelligence
The gap between premium and commodity crunchy chocolate is hardening as ingredient provenance and texture precision separate price tiers. Nestle leverages its vertical integration from cocoa sourcing to finished confectionery to sustain margin control across both segments. Mondelez competes through R&D intensity in crisped-rice and nut-inclusion formulations, while Barry Callebaut anchors industrial supply with specialized chocolate masses for third-party crunchy product manufacturers.
Crunchy chocolate denotes cocoa-based confectionery containing discrete crisp inclusions—typically puffed grains, caramelized nuts, or aerated chocolate fragments at 5-15% inclusion rates by weight—manufactured through controlled tempering and enrobing processes to preserve structural integrity. Its primary commercial purpose is to deliver multi-sensory eating experiences that command price premiums in both impulse and gift categories. Dark chocolate with high-cacao content and single-origin positioning captures the fastest-growing margin pool as health-conscious consumers trade up, while milk chocolate in bag and bar formats remains the volume backbone through supermarket and convenience store channels. Online retailers are gaining share fastest among distribution channels, though specialty stores still dominate premium discovery and trial.
FDA food-labeling requirements and the EU's EFSA nutrition and health claims framework shape permissible marketing language around crunchy chocolate's functional attributes, directly influencing product positioning and packaging design. REACH compliance for food-contact materials and California's Proposition 65 warning requirements add compliance layers for manufacturers selling across multiple jurisdictions. Stakeholders must monitor evolving sugar-tax regimes and clean-label certification standards as these will determine which formulation and packaging investments yield durable returns.
Market Dynamics
Confectionery manufacturers face intensifying pressure from the EU's F-Gas Regulation to retrofit tempering and aeration equipment, while artisanal demand for precision-textured inclusions concentrates purchasing power among industrial chocolate clusters in Germany.
Growth Catalysts
- Clean-label certification frameworks:EFSA nutrition and health claims standards reward reformulation investments with premium shelf positioning, pulling R&D spending toward single-origin dark chocolate lines.
- Controlled-atmosphere processing:Lower-emission tempering technologies satisfy F-Gas compliance timelines while preserving structural integrity of 5-15% inclusion rates.
- Cologne-Hamburg industrial corridor:German chocolate mass producers anchor continental supply for third-party crunchy product manufacturers scaling artisanal output.
Market Restraints
- Cocoa butter price volatility:Input cost swings compress margin buffers for mid-tier producers lacking backward integration into bean sourcing.
- Supply concentration in West African origins:Geopolitical and climate risk in Côte d'Ivoire and Ghana concentrates raw material vulnerability.
- REACH compliance for food-contact materials:ECHA substance restrictions add formulation and packaging redesign costs for multi-jurisdiction sellers.
Strategic Opportunities
- Online retail channel expansion:E-commerce platforms capture the fastest-growing distribution share for impulse and gift-format crunchy chocolate.
- Dual carbon goals in China:SAMR efficiency standards create first-mover advantage for European exporters with verified low-emission processing credentials.
- Crisped-rice and nut-inclusion R&D convergence:Texture precision technologies open white space between commodity and premium price tiers.
Industry Challenges
- California Proposition 65 warning requirements:Heavy metal disclosure obligations force packaging redesign and supply chain documentation for US market access.
- Tempering technician skill scarcity:Precision aeration and enrobing operations require specialized operators that confectionery clusters struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crunchy Chocolate Market |
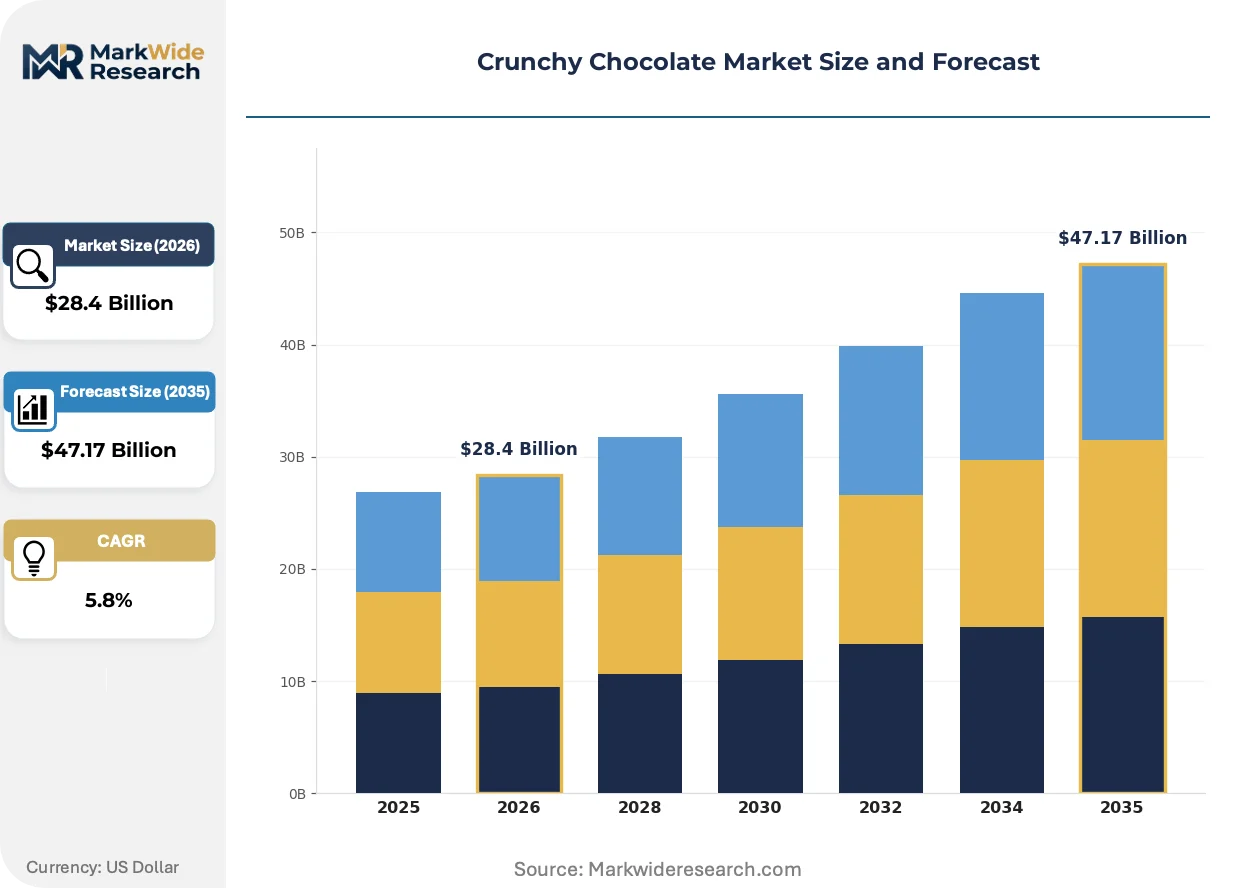
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $47.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Chocolate, Dark Chocolate, White Chocolate, Sugar-Free Chocolate Packaging Type: Bags, Bars, Boxes, Bulk Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores Customer Type: Retail Consumers, Food Service, Manufacturers, Confectionery Makers |
| Companies Covered | Nestle, Mars, Mondelez, Ferrero, Hershey, Barry Callebaut, Cargill, Ezaki Glico, Grupo Arcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crunchy Chocolate Market Strategic Shifts & Innovations
Texture engineering and emissions compliance are converging to reshape competitive differentiation, with digital process control and regulatory disclosure requirements forcing simultaneous investment across production and packaging functions.
Precision aeration technology is electrifying the structural capabilities of industrial tempering lines. Artisanal confectionery producers in Germany and Belgium are retrofitting equipment at accelerated pace. This capability compression is enabling smaller batch sizes with inclusion-rate consistency previously reserved for mass production.
REACH substance restrictions for food-contact materials are tightening permissible migration limits for packaging adhesives and coatings. Industrial chocolate mass suppliers must reformulate or source alternative barrier materials. Dark chocolate with high-cacao content faces the steepest compliance timeline due to fat-soluble contaminant sensitivity.
Specialty stores still dominate premium discovery and trial, though direct-to-consumer subscriptions are displacing traditional gift-channel intermediaries. Convenience store and supermarket volume channels respond with localized assortment strategies. Germany and France exhibit the most pronounced channel bifurcation between impulse and ceremonial purchase occasions.
Crunchy Chocolate Market Segmentation
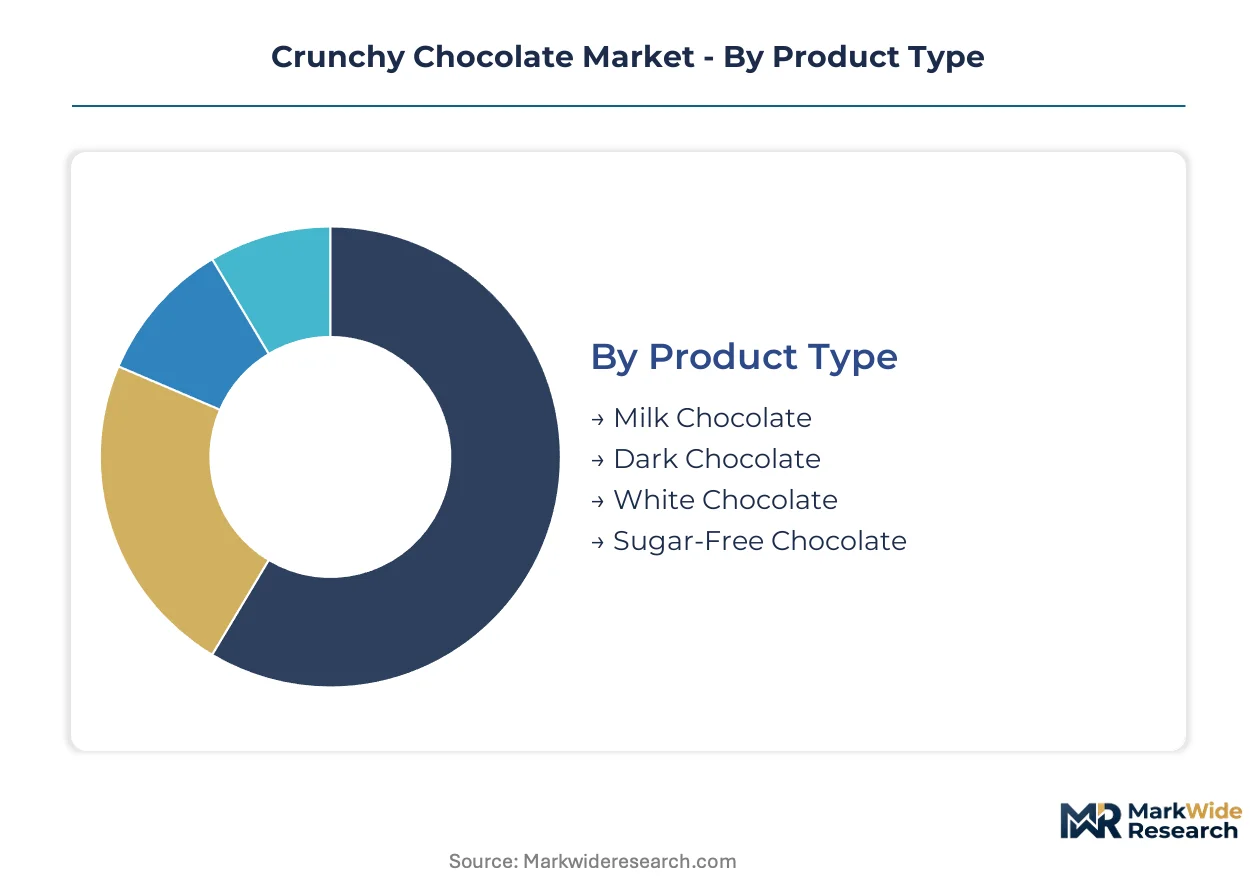
Segmentation in crunchy chocolate markets determines which regulatory pathways manufacturers must navigate. Certification burdens vary sharply across product types and customer channels, directly shaping margin structures and geographic prioritization.
Product Type:
EFSA nutrition and health claims frameworks impose divergent compliance costs across cacao content tiers, with dark chocolate bearing the heaviest substantiation requirements for antioxidant positioning.
- Milk Chocolate:Standard 30-40% cacao mass with dairy solids and 5-15% crisped-rice or nut inclusions. Volume concentrates in German and French supermarket channels where impulse purchase frequency sustains throughput despite thinner per-unit margins.
- Dark Chocolate:High-cacao formulations (60-85%) with single-origin bean sourcing and aerated fragment inclusions. Demand clusters in specialty stores and direct-to-consumer subscriptions across Belgium and Switzerland, pulled by health-conscious trading-up and clean-label certification premiums.
- White Chocolate:Cocoa butter-based confectionery without cacao solids, typically carrying caramelized nut inclusions. FDA labeling requirements for cocoa butter percentage disclosure add formulation complexity for US-bound production.
- Sugar-Free Chocolate:Maltitol or erythritol-sweetened variants with modified tempering protocols to preserve inclusion integrity. REACH compliance for alternative sweetener migration limits constrains packaging material selection.
Milk chocolate sits at the top of the volume ranking, with dark chocolate climbing the fastest.
Packaging Type:
Cost tier stratification separates commodity formats from gift-positioned alternatives, with barrier material specifications driving per-unit economics.
- Bags:Flexible laminate pouches for 100-200g impulse formats with nitrogen flush for inclusion crispness retention. Convenience store channels in France and Italy favor this format for localized assortment flexibility.
- Bars:Molded single-serve or share-size formats with sectional scoring. Supermarket volume in Germany anchors demand, though online retailers are gaining share fastest for premium bar subscriptions.
- Boxes:Rigid gift formats with partitioned trays protecting structural integrity of decorated inclusions. Specialty stores dominate discovery, with ceremonial purchase occasions in Switzerland and Austria sustaining premium pricing.
- Bulk:Industrial totes and pails for food service and confectionery maker input. Cologne-Hamburg chocolate mass clusters anchor continental supply for third-party crunchy product manufacturers.
Bars sit at the top of the volume ranking, with boxes climbing the fastest.
Distribution Channel:
Customer type concentration determines channel investment priority, with procurement patterns diverging between impulse immediacy and premium discovery.
- Supermarkets:High-frequency replenishment channels with planogram-driven assortment. German and UK chains dominate volume, though private-label expansion compresses branded margin buffers.
- Convenience Stores:Grab-and-go positioning for single-serve formats with localized flavor adaptations. French and Italian urban networks exhibit the highest transaction frequency.
- Online Retailers:E-commerce platforms capturing the steepest expansion trajectory for both impulse restocking and gift-format discovery. Direct-to-consumer subscriptions displace traditional intermediaries in premium segments.
- Specialty Stores:Curated assortment with staff-guided trial for single-origin and artisanal lines. Belgian and Swiss chocolate boutiques anchor continental premium positioning.
Supermarkets sit at the top of the volume ranking, with online retailers climbing the fastest.
Customer Type:
Application maturity separates established consumption patterns from emerging industrial demand segments.
- Retail Consumers:End-user purchase for immediate consumption or gifting, spanning impulse and ceremonial occasions. German and French households represent the deepest per-capita penetration.
- Food Service:Dessert garnish and ingredient applications in hotels, restaurants, and cafes. Precision aeration requirements for inclusion stability constrain supplier qualification.
- Manufacturers:Industrial buyers of chocolate masses and inclusion systems for downstream processing. REACH food-contact compliance and F-Gas processing credentials determine vendor selection.
- Confectionery Makers:Artisanal producers scaling output with specialized enrobing and tempering equipment. Cologne and Hamburg industrial corridors concentrate purchasing power for premium inclusion sourcing.
Retail consumers sit at the top of the volume ranking, with confectionery makers climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized tempering technicians and precision aeration engineers concentrate in German industrial corridors, anchoring continental supply for premium inclusion systems. Their expertise underpins the quality differentiation that separates artisanal producers from commodity manufacturers. This workforce distribution shapes where R&D investment and equipment retrofitting accelerate fastest.
Germany
Artisanal demand for precision-textured inclusions drives equipment upgrade cycles in Cologne and Hamburg chocolate mass clusters. The EU's F-Gas Regulation mandates lower-emission tempering retrofits with strict compliance timelines. Cologne-Hamburg corridor producers anchor continental supply for third-party crunchy product manufacturers scaling output.
United States
FDA food-labeling requirements and impulse purchase frequency sustain volume throughput in supermarket and convenience store channels. California's Proposition 65 imposes heavy metal disclosure obligations forcing packaging redesign. Pennsylvania and Illinois manufacturing hubs concentrate mass-market production for domestic distribution.
Switzerland
Single-origin dark chocolate positioning and health-conscious trading-up pull premium demand toward specialty stores and direct-to-consumer subscriptions. Swissmedic food-contact material standards exceed baseline EU requirements. Zurich and Geneva boutique networks anchor continental premium discovery and ceremonial purchase occasions.
Belgium
Staff-guided trial environments in chocolate boutiques sustain premium pricing for high-cacao formulations. EFSA nutrition and health claims frameworks impose substantiation requirements for antioxidant positioning. Brussels and Antwerp artisanal producers retrofit precision aeration equipment at accelerated pace.
China
SAMR efficiency standards create procurement preference for verified low-emission processing credentials among industrial buyers. Dual carbon goals accelerate domestic equipment upgrade cycles. Yangtze River Delta confectionery clusters import European tempering technology for inclusion-rate consistency.
Crunchy Chocolate Market Key Industry Players
Top-tier vendors anchor premium artisanal supply, while mid-scale commodity producers compete on throughput and inclusion cost. The vendor base stratifies across three tiers: integrated cocoa processors with captive bean sourcing, specialized chocolate mass suppliers serving third-party manufacturers, and regional confectionery brands with localized flavor portfolios. Two dominant competitive moves define current positioning: retrofitting tempering lines for F-Gas compliance and acquiring precision aeration capabilities to serve artisanal demand.
Within the integrated processing tier, Nestle and Mondelez occupy positions that exemplify backward integration from bean sourcing through finished confectionery. Barry Callebaut represents the specialized mass supplier archetype, anchoring industrial supply for downstream crunchy product manufacturers. These three companies illustrate how control over cocoa butter input costs and tempering technology credentials determine vendor selection among quality-focused buyers.
| Leading Market Players |
|---|
| Nestle |
| Mars |
| Mondelez |
| Ferrero |
| Hershey |
| Barry Callebaut |
| Cargill |
| Ezaki Glico |
| Grupo Arcor |
| Others |
Cost & Logistics Intelligence
Backward integration from bean sourcing through finished confectionery anchors both supply security and pricing power for Nestle and Mondelez, compressing margin buffers for mid-tier producers lacking captive cocoa butter supply. This integration pattern hardens the premium-commodity divide as inclusion precision and single-origin certification separate price tiers.
Pricing Analysis
Finished-product and industrial-mass pricing splits dominate transaction structures, with three-tier pricing stratification across premium artisanal, standard branded, and economy private-label levels. Price differentiation rests on EFSA clean-label certification and F-Gas compliance credentials as primary tier separators. Pricing pressure intensifies in mid-tier branded segments as German supermarket chains expand private-label crunchy chocolate assortments. Food service buyers exhibit highest price sensitivity due to volume procurement and substitution flexibility, while Swiss specialty store channels sustain lowest sensitivity through ceremonial purchase occasions.
Supply Chain Analysis
EFSA nutrition claims and REACH food-contact certifications gate supplier qualification for European industrial buyers, filtering vendor pools before commercial engagement. Cocoa bean supply concentrates in Côte d'Ivoire, Ghana, and Ecuador, with German and Belgian processing clusters anchoring European mass production. Chocolate mass production draws from cocoa butter, crisped-rice inclusions, and caramelized nut systems as core inputs. Single-source vulnerability in West African origins exposes processors to climate and geopolitical disruption. Distribution runs through Cologne-Hamburg industrial corridors for third-party manufacturers, with direct-to-consumer subscriptions gaining fastest expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU F-Gas compliance costs and Chinese SAMR efficiency procurement preferences rewards European exporters with verified low-emission credentials, exploiting regulatory divergence to capture industrial buyer preference in Yangtze River Delta clusters.
For Market Incumbents: Cement tempering technician retention through apprenticeship pipelines in Cologne and Hamburg corridors, defending against capability scarcity that artisanal competitors exploit. Acquire precision aeration equipment vendors to lock texture-engineering IP before mid-tier producers close capability gaps. Prioritize F-Gas retrofit completion timelines to maintain industrial supply contracts against emerging low-emission entrants. For New Entrants and Emerging Players: Precision aeration technology for small-batch inclusion consistency offers entry wedge into Belgian and Swiss artisanal segments underserved by mass producers. Target direct-to-consumer subscription channels for premium dark chocolate with single-origin positioning, where discovery costs are lowest and margin capture is highest. Lead with carbon-verified processing credentials to qualify for Chinese industrial procurement. For Investors and Strategic Acquirers: Roll-up economics work for specialized chocolate mass suppliers with F-Gas compliance and REACH certification infrastructure already deployed, because regulatory sunk costs create moats against unqualified competitors. Monitor cocoa butter price volatility as inflection indicator for margin compression timing across mid-tier branded portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| F-Gas Compliance Retrofit | Lower-emission tempering equipment preserves inclusion integrity while satisfying EU regulatory timelines. |
| Precision Aeration Acquisition | Texture-engineering capabilities capture artisanal demand for 5-15% inclusion rate consistency. |
| Single-Origin Sourcing Expansion | High-cacao dark chocolate positioning commands premium pricing in health-conscious trading-up segments. |
| Direct-to-Consumer Subscription Launch | E-commerce platforms displace traditional gift-channel intermediaries in Belgian and Swiss premium discovery. |
| Clean-Label Certification Investment | EFSA substantiation requirements reward reformulation spending with premium shelf positioning. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with confectionery R&D directors, tempering equipment engineers, supermarket category buyers, and artisanal chocolate makers with secondary validation. Customs records, EFSA guidance documents, F-Gas implementation reports, and Nielsen retail audit data anchored volume estimates. Bottom-up production capacity assessments and top-down consumption surveys triangulated market sizing across the analysis window.
Comparable historical periods anchored projection modeling, with growth rates derived from segment-level expansion patterns across product type, packaging format, distribution channel, and customer application dimensions. Cacao content tiers, inclusion technology maturity, and regulatory compliance status shaped forecast trajectories. Cocoa butter price volatility indices and equipment retrofit adoption curves fed sensitivity analysis.
The model holds under stable EU regulatory implementation timelines and continued Chinese dual-carbon procurement preference; deviation in West African supply disruption severity or sugar-tax regime expansion would shift volume and value projections. A model refresh is warranted upon material change in F-Gas enforcement intensity or SAMR efficiency standard revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Asia-Pacific Sugar Free Chewing Gum Market
Confectionery
North America Dark Chocolate Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Low Calorie Nutella Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
North America Gummy Market
Confectionery
Durian Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
India Chocolate Market
Confectionery
Europe Confectionery Market
Confectionery
United States and Europe Macarons Market
Confectionery
UK Confectionery Market
Confectionery
Italy Chocolate Market
Confectionery
UK Compound Chocolate Market