
 Middle East and Africa Premium Chocolate Market | 2026-2036
Middle East and Africa Premium Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Premium Chocolate Market Foresight
Buyer concentration in the Middle East and Africa premium chocolate sector is expanding as luxury hotel chains and airline duty-free operators consolidate procurement volumes. Barry Callebaut leverages its bean-to-bar supply infrastructure to serve industrial clients across the Gulf. Lindt & Sprüngli AG sustains brand cachet through dedicated boutique networks in Dubai and Riyadh. Patchi LLC dominates the regional gifting segment with localized flavor profiles and ornate packaging designs.
Premium chocolate denotes cocoa-based confectionery containing elevated cocoa mass percentages, typically above sixty percent for dark variants, manufactured through extended conching processes that refine particle size below twenty microns for smooth mouthfeel. Its commercial purpose centers on delivering sensorial differentiation for gift occasions and affluent self-consumption. Dark chocolate leads product type revenue due to health-positioning and reduced sugar content preferences among Gulf consumers. Specialty stores capture margin-rich distribution as experiential retail environments justify price premiums over supermarket channels. Gift packs concentrate seasonal demand around Ramadan and Eid purchasing cycles.
SFDA in Saudi Arabia and Dubai Municipality's Food Safety Department enforce cocoa content thresholds and allergen labeling that shape import compliance costs for European manufacturers. EFSA-aligned standards increasingly influence Gulf Cooperation Council technical regulations as the region harmonizes food safety protocols. Stakeholders must monitor evolving halal certification requirements and local sourcing mandates that could reshape supply chain configurations across the Middle East and Africa.
Market Dynamics
Luxury hotel chains and airline duty-free operators are consolidating procurement volumes, concentrating buyer power and forcing manufacturers to reconfigure distribution priorities around experiential retail environments rather than traditional wholesale channels.
Growth Catalysts
- Halal certification harmonization:Gulf Cooperation Council technical regulations are converging toward EFSA-aligned standards, reducing compliance duplication for European exporters and accelerating product registration timelines.
- Dubai's luxury retail infrastructure:The emirate's duty-free zones and mall ecosystems anchor regional distribution, creating consolidated entry points for premium confectionery brands seeking Gulf market access.
- Extended conching processes:Advanced refining equipment capable of achieving sub-twenty-micron particle sizes is spreading among regional contract manufacturers, elevating baseline quality expectations for imported dark chocolate.
Market Restraints
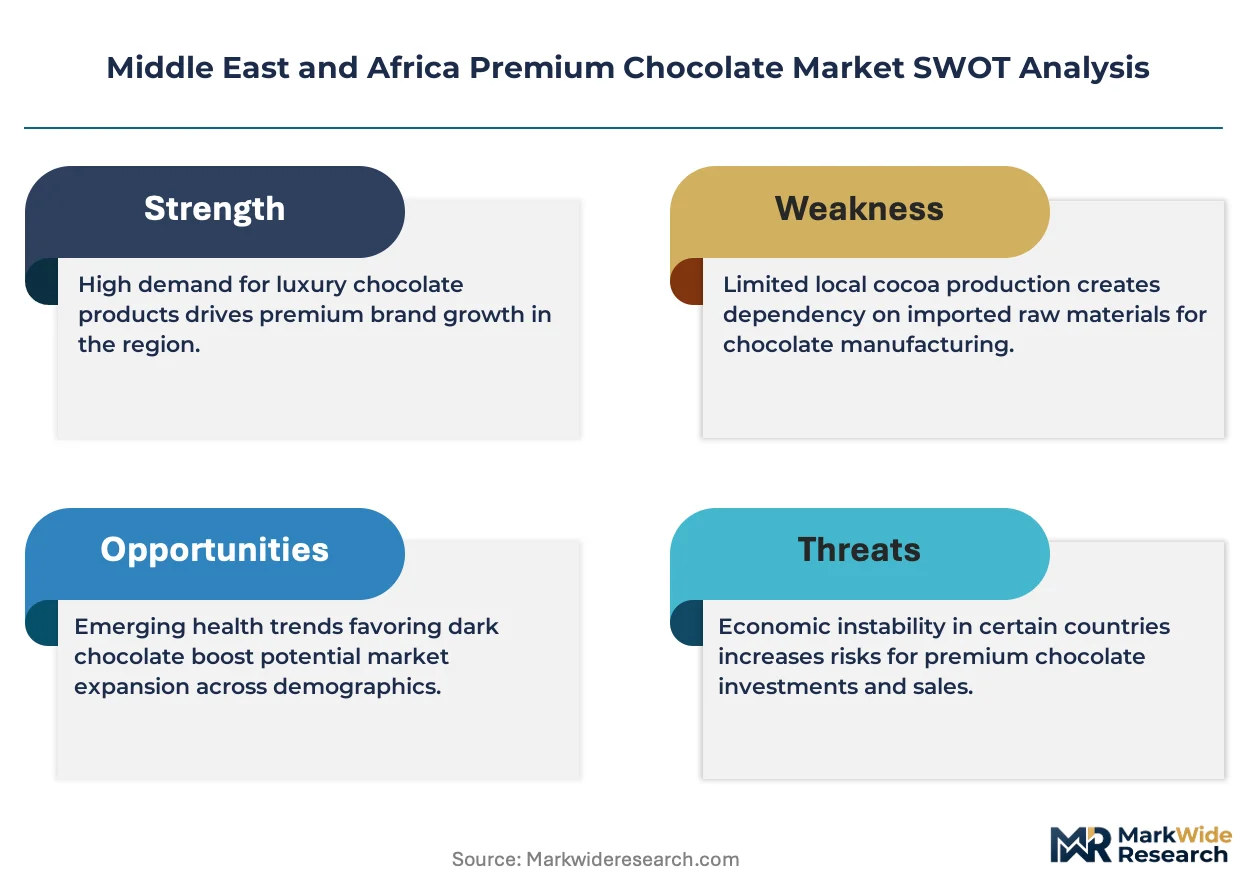
- Cocoa butter price volatility:Input cost swings for this essential fat phase ingredient compress margin predictability for dark chocolate formulations above sixty percent cocoa mass.
- SFDA labeling thresholds:Saudi Arabia's strict cocoa content declarations and allergen disclosure mandates impose translation and reformulation burdens that deter smaller European artisan producers.
- Date palm sugar substitution:Local sweetener alternatives in traditional Middle Eastern confectionery retain price advantages that constrain premium chocolate penetration in rural Saudi and Egyptian markets.
Strategic Opportunities
- Nigeria's urban affluent class:Lagos and Abuja present underdeveloped specialty retail infrastructure where localized flavor partnerships could establish first-mover positioning ahead of European brand saturation.
- Ramadan-Eid gifting digitization:E-commerce platforms with same-day delivery capabilities in the UAE are capturing seasonal demand that physical boutiques cannot fulfill during compressed purchasing windows.
- Dubai Municipality blockchain traceability:The emirate's pilot programs for cocoa origin verification create regulatory tailwinds for brands investing in bean-to-bar transparency documentation.
Industry Challenges
- Temperature-controlled last-mile logistics:Maintaining eighteen-degree Celsius thresholds through Gulf summer months requires specialized fleet investments that strain regional distributor capital allocation.
- Multilingual packaging artwork cycles:Simultaneous Arabic-English-French label compliance for Morocco, UAE, and Francophone African markets extends product launch timelines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Premium Chocolate Market |
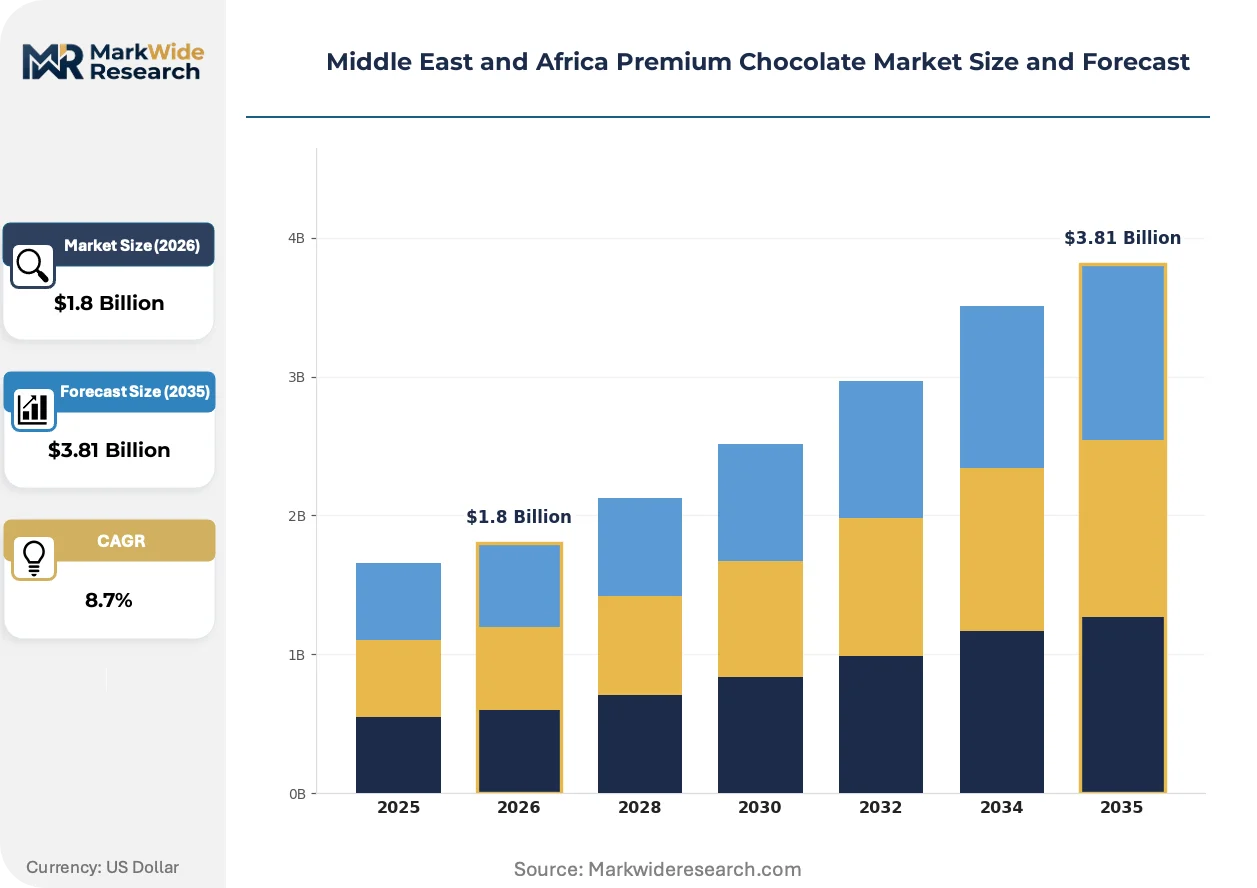
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Filled Chocolate End User: Retail Consumers, Food Service, Bakeries, Cafes Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores Packaging Type: Boxes, Bars, Gift Packs, Pouches |
| Companies Covered | Barry Callebaut, Chocoladefabriken Lindt & Sprüngli AG, Mondelez International Inc., Mirzam, Al Nassma, Mars Incorporated, Nestlé S.A., Patchi LLC, Ferrero Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Premium Chocolate Market Shifts & Advancements
Bean-to-bar traceability systems and localized flavor development are compressing the traditional import-dependent supply model, while regulatory pressure on sugar content and allergen transparency is reshaping formulation priorities across the Gulf.
Precision tempering robotics is absorbing quality control functions previously executed by master chocolatiers in Dubai and Riyadh boutique kitchens. Five-star hotel pastry departments are adopting these systems to ensure consistent gloss and snap in high-volume banquet production. The technology is absorbing artisan labor scarcity while standardizing sensorial outputs that justify premium positioning.
SFDA and Dubai Municipality's Food Safety Department are tightening parallel import restrictions through serialized halal certification requirements. European manufacturers must now register each production facility separately rather than relying on blanket EU approvals. Dark chocolate lines with nut-free claims face the steepest documentation burdens as allergen litigation risk rises across Saudi retail.
Gifting occasion unbundling is fragmenting traditional Ramadan bulk purchasing into year-round micro-occasions. Specialty stores in Jeddah and Manama are responding with single-origin mini-tablet assortments that displace standardized gift boxes. This pattern is most visible among UAE expatriate professionals seeking portable luxury tokens for business relationship maintenance.
Middle East and Africa Premium Chocolate Market Segmentation
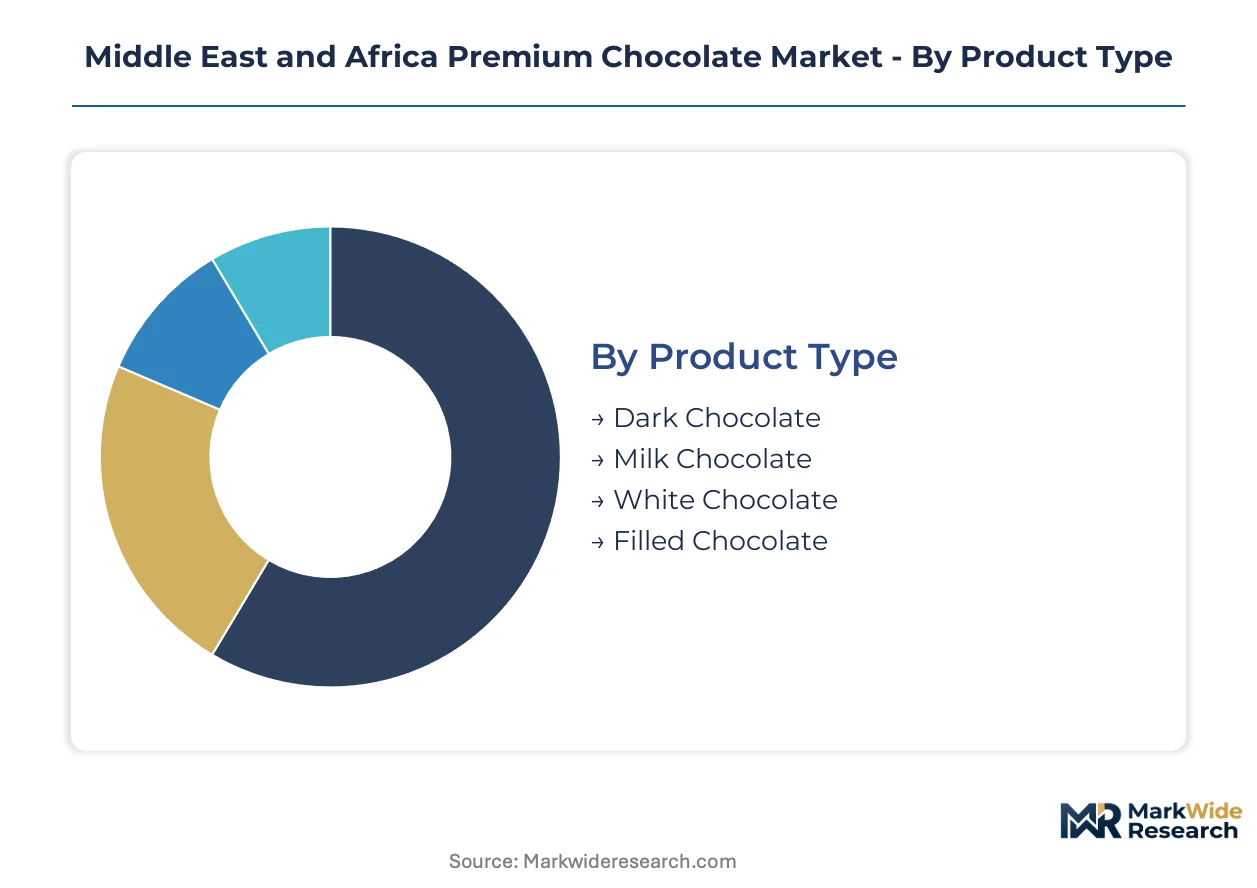
Premium chocolate segmentation in the Middle East and Africa reveals distinct purchasing logic across consumption occasions and channel environments. Gulf consumers differentiate sharply between self-indulgence, corporate gifting, and hospitality procurement, each demanding tailored product specifications and packaging formats.
Product Type:
Buyer differentiation in this category hinges on health-positioning intensity and cocoa intensity tolerance rather than price sensitivity alone.
- Dark Chocolate:Formulations exceeding sixty percent cocoa mass dominate health-conscious consumption in Dubai and Riyadh, where reduced sugar content aligns with wellness positioning among affluent professionals. Saudi Food and Drug Authority labeling thresholds for cocoa content declarations have elevated transparency expectations, compressing margins for imported European artisan brands unable to reformulate quickly.
- Milk Chocolate:Balanced cocoa-butter ratios appeal to family gifting occasions across the UAE, where milder flavor profiles accommodate multi-generational preferences during Eid celebrations. Hotel pastry departments in Jeddah specify milk chocolate couverture for banquet dessert applications requiring consistent tempering behavior.
- White Chocolate:Cocoa butter-based formulations without cocoa solids serve niche dessert decoration demand in Manama's specialty patisseries.
- Filled Chocolate:Date paste and pistachio ganache interiors localize flavor profiles for Ramadan gift assortments in Kuwait and Qatar.
Volume sits with Dark Chocolate; growth tilts toward Filled Chocolate as localization partnerships accelerate.
End User:
Procurement scale and specification rigor separate institutional buyers from individual purchasers across the Gulf.
- Retail Consumers:Affluent expatriates and Gulf nationals drive seasonal surges around Ramadan and Eid, with Dubai's mall ecosystems concentrating high-value transactions in boutique environments. Individual buyers prioritize ornate packaging and origin storytelling over unit economics.
- Food Service:Five-star hotel chains in Abu Dhabi and Riyadh consolidate procurement volumes, demanding batch consistency and halal certification documentation that smaller European producers struggle to supply. Barry Callebaut's regional bean-to-bar infrastructure captures this concentrated demand through dedicated foodservice divisions.
- Bakeries:Artisan patisseries in Casablanca and Tunis source couverture for viennoiserie applications, prioritizing tempering stability over origin provenance.
- Cafes:Third-wave coffee operators in Lagos and Nairobi experiment with single-origin pairings, though volume remains limited by specialty retail infrastructure gaps.
Food Service commands procurement scale; Retail Consumers generate the steepest expansion trajectory through gifting digitization.
Distribution Channel:
Margin capture and experiential value creation diverge sharply between physical and digital touchpoints in Gulf markets.
- Specialty Stores:Dubai Mall and Mall of the Emirates locations justify thirty to fifty percent price premiums through tasting consultations and limited-edition releases. Patchi LLC's ornate boutique environments in Riyadh and Jeddah anchor this channel with localized packaging ateliers.
- Online Retail:Same-day delivery platforms in the UAE capture compressed Ramadan purchasing windows that physical boutiques cannot fulfill, with e-commerce expanding fastest among expatriate professionals seeking portable luxury tokens.
- Supermarkets:Carrefour and Lulu Hypermarket chains stock standard assortments for routine consumption in Saudi Arabia's secondary cities.
- Convenience Stores:Limited premium SKU presence concentrates in airport locations and fuel station convenience formats across the GCC.
Specialty Stores retain margin leadership; Online Retail climbs the fastest as logistics infrastructure matures.
Packaging Type:
Occasion specificity and portability requirements shape format selection across Middle East and Africa markets.
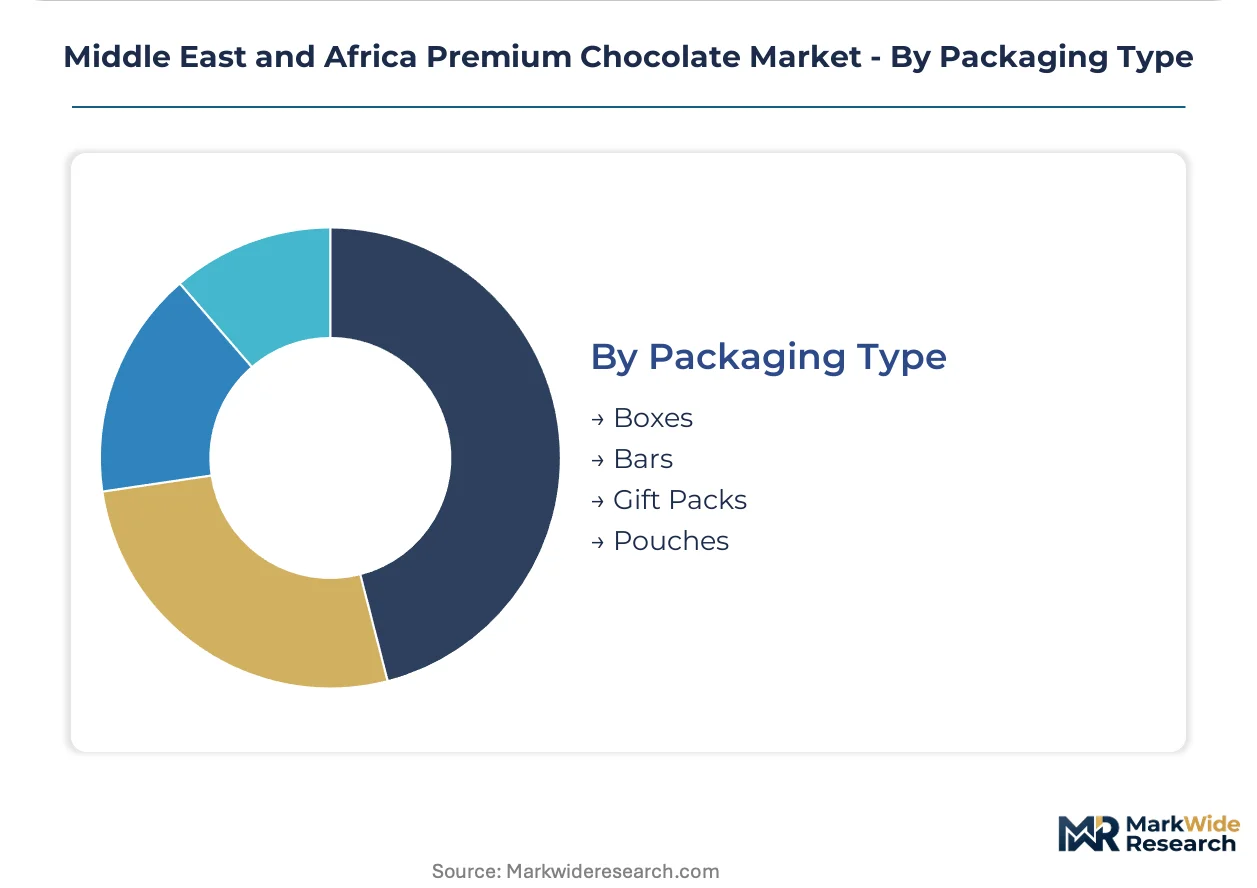
- Gift Packs:Multi-assortment boxes dominate Ramadan and Eid purchasing cycles in the UAE, where unbundling trends are fragmenting traditional bulk buying into curated mini-tablet selections. Ornate metal and lacquered wood finishes justify premium positioning in corporate relationship maintenance.
- Bars:Single-origin tablet formats appeal to self-consumption and daily indulgence occasions among health-positioned buyers in Dubai and Riyadh, with seventy percent-plus cocoa variants leading shelf placement in specialty retail.
- Boxes:Standardized twelve- and twenty-four-piece assortments serve hospitality minibar and airline duty-free applications.
- Pouches:Flexible formats for bite-sized pralines address portability needs in Nigerian and Kenyan urban markets with emerging specialty chocolate exposure.
Gift Packs concentrate seasonal revenue; Bars gain share fastest as self-consumption normalizes outside festive periods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury retail infrastructure and consolidated procurement by hospitality chains concentrate premium chocolate demand across Gulf Cooperation Council states. Nigeria and South Africa present expansion frontiers where specialty retail penetration remains limited.
United Arab Emirates
Dubai Mall and Mall of the Emirates anchor regional distribution through experiential boutique environments that justify thirty to fifty percent price premiums. Dubai Municipality's Food Safety Department enforces serialized halal certification requirements that reshape import compliance for European manufacturers. The emirate's duty-free zones and blockchain traceability pilot programs create consolidated entry points for premium confectionery brands.
Saudi Arabia
Riyadh and Jeddah concentrate seasonal gifting demand around compressed Ramadan-Eid purchasing windows that strain physical retail capacity. SFDA labeling thresholds for cocoa content declarations and allergen disclosures impose translation burdens that deter smaller European artisan producers. Western Region hotel chains consolidate procurement volumes, demanding batch consistency documentation that favors suppliers with dedicated foodservice divisions.
Nigeria
Lagos and Abuja's urban affluent class presents underdeveloped specialty retail infrastructure where localized flavor partnerships could establish first-mover positioning. The country's national food safety regulator maintains evolving standards for imported confectionery that require careful navigation. Third-wave coffee operators in Lagos experiment with single-origin pairings, though volume remains constrained by cold chain logistics gaps.
South Africa
Cape Town and Johannesburg sustain established specialty chocolate consumption among affluent professionals seeking health-positioned dark variants. National consumer protection regulations govern allergen labeling and origin claims for cocoa-based products. Gauteng's retail infrastructure supports year-round demand outside the seasonal patterns dominating Gulf markets.
Morocco
Casablanca and Rabat blend Francophone confectionery traditions with emerging demand for premium cocoa experiences among urban consumers. The country's food safety authority aligns technical regulations with EFSA standards while maintaining distinct multilingual packaging requirements. Artisan patisseries in Casablanca source couverture for viennoiserie applications, prioritizing tempering stability over origin provenance.
Middle East and Africa Premium Chocolate Market Competitive Landscape
Swiss and Belgian producers anchor the premium-tier supply base; Gulf-based specialists hold the localized gifting segment. Market structure tilts toward consolidation as industrial chocolate manufacturers capture foodservice procurement volumes through dedicated regional divisions. Three archetypes dominate: bean-to-bar integrated suppliers, boutique gifting specialists with ornate packaging ateliers, and multinational confectionery houses with diversified premium portfolios. Capacity expansion and halal certification harmonization represent the dominant competitive moves reshaping market access.
Within the integrated supply tier, Barry Callebaut exemplifies the bean-to-bar infrastructure model serving industrial clients across Gulf markets. Among boutique specialists, Patchi LLC occupies a position defined by localized flavor profiles and ornate packaging designs that dominate regional gifting occasions. Chocoladefabriken Lindt & Sprüngli AG represents the European premium house archetype, sustaining brand cachet through dedicated boutique networks in Dubai and Riyadh.
| Leading Market Players |
|---|
| Barry Callebaut |
| Chocoladefabriken Lindt & Sprüngli AG |
| Mondelez International Inc. |
| Mirzam |
| Al Nassma |
| Mars Incorporated |
| Nestlé S.A. |
| Patchi LLC |
| Ferrero Group |
| Others |
Supply & Pricing Matrix
Backward integration into cocoa origin sourcing anchors pricing power for Gulf market leaders, as bean-to-bar traceability documentation commands premium positioning in Dubai's duty-free zones and Riyadh's boutique networks. This captive supply structure compresses margin volatility for integrated operators while forcing import-dependent artisan brands to absorb SFDA compliance costs and cocoa butter price swings.
Pricing Analysis
Volume concentrates in foodservice procurement contracts, while margin capture tilts toward specialty retail and gifting segments. Three-tier pricing structure across premium boutique, standard retail, and economy supermarket levels separates origin-provenance dark chocolate from mass-market formulations. Pricing pressure stems from cocoa butter input cost volatility compressing margins on sixty-percent-plus cocoa mass lines. Foodservice buyers demonstrate lowest price sensitivity due to consolidated procurement scale, whereas Nigerian and Kenyan retail consumers exhibit highest sensitivity to unit price differentials.
Supply Chain Analysis
Serialized halal certification requirements from Dubai Municipality and Saudi Food and Drug Authority gate market access, forcing European manufacturers to register production facilities individually rather than relying on blanket approvals. Cocoa bean sourcing concentrates in Côte d'Ivoire, Ghana, and Ecuador, with processing infrastructure anchored in Belgium and Switzerland. Supply chain risk centers on temperature-controlled last-mile logistics through Gulf summer months, where eighteen-degree Celsius thresholds require specialized fleet investments. Distribution runs through Dubai's consolidated duty-free zones and mall ecosystems, with regional contract manufacturers absorbing quality refinement functions previously executed by European master chocolatiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in certified cocoa origin documentation and temperature-controlled logistics infrastructure prop pricing power for integrated operators across the Middle East and Africa premium chocolate sector.
For Market Incumbents: Anticipate regulatory tightening on allergen disclosure and blockchain traceability mandates by deepening halal certification harmonization across Gulf Cooperation Council states. Secure batch consistency documentation for hotel chain procurement consolidation, as five-star properties in Abu Dhabi and Riyadh demand standardized sensorial outputs that justify premium positioning. Vertical integration into Nigerian and South African cold chain logistics represents the critical defensive lever against emerging regional contract manufacturers. For New Entrants and Emerging Players: Begin with Lagos and Abuja's underdeveloped specialty retail infrastructure, where localized flavor partnerships with date paste and pistachio suppliers could establish first-mover positioning ahead of European brand saturation. Target Ramadan-Eid gifting digitization through same-day delivery platform partnerships in the UAE, capturing compressed seasonal purchasing windows that physical boutiques cannot fulfill. A direct-to-consumer launch anchored in origin storytelling and mini-tablet assortments offers the most penetrable go-to-market angle for expatriate professional segments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational confectionery houses seeking Gulf market access through halal-certified production assets. Long-term viability across the five-to-ten-year window hinges on regulatory alignment with EFSA-influenced technical standards and blockchain traceability infrastructure investment. The signal to monitor is Dubai Municipality's expansion of serialized certification requirements to Francophone African markets, which would trigger consolidation pressure on artisan producers lacking documentation scale.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Harmonization | Reduces compliance duplication for European exporters seeking SFDA and Dubai Municipality registration. |
| Blockchain Traceability Infrastructure | Dubai's pilot programs for cocoa origin verification create regulatory tailwinds for transparency investment. |
| Localized Flavor Development | Date paste and pistachio ganache partnerships capture Ramadan gifting demand in Kuwait and Qatar. |
| Temperature-Controlled Logistics Expansion | Specialized fleet investments address eighteen-degree Celsius thresholds through Gulf summer months. |
| Precision Tempering Robotics Deployment | Five-star hotel pastry departments adopt systems to ensure consistent gloss and snap in banquet production. |
Research Methodology
Trade databases, customs records, and Gulf Cooperation Council regulatory filings formed the secondary backbone, supplemented by primary interviews with cocoa procurement managers, halal certification consultants, hotel pastry directors, specialty retail buyers, and cold chain logistics operators. Bottom-up volume modeling across product type, end user, distribution channel, and packaging format segments was cross-validated against top-down trade flow analysis. Triangulation between primary fieldwork and secondary validation ensured segmentation integrity.
Historical trendline analysis of cocoa butter price volatility, seasonal gifting patterns, and regulatory registration timelines informed projection frameworks across the analysis window. Segmentation dimensions modeled include cocoa mass percentage tiers, institutional versus individual procurement channels, and halal certification status. CAGRs were derived from regression analysis of volume trajectories, with inputs weighted toward SFDA compliance cost trajectories and Dubai duty-free transaction velocity.
Cocoa butter price spikes, regulatory registration delays, and cold chain infrastructure gaps are the dominant revision risks to forecast assumptions. A model refresh is warranted upon material change in Gulf Cooperation Council technical regulation harmonization pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Real and Compound Chocolate Market
Confectionery
Global Compound Chocolate Market
Confectionery
Canada Chocolate Market
Confectionery
India Industrial Chocolate Market
Confectionery
Low Calorie Sweets Market
Confectionery
Green Tea Chocolate Market
Confectionery
Bangladesh Candy Market
Confectionery
Sugarless Chocolate Market
Confectionery
India Chocolate Market
Confectionery
Low Calorie Treats Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Fruit Jellies Market
Confectionery
Global Confectionery Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
Global Sugar Free Chewing Gums Market