
 Low-Calorie Dark Chocolate Market | 2026-2036
Low-Calorie Dark Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Dark Chocolate Market Analytics
Subscription-based replenishment services is consolidating as a core revenue layer in low-calorie dark chocolate, converting occasional buyers into recurring revenue streams. Mondelez International leverages its direct-to-consumer infrastructure to sustain repeat purchase rates. Barry Callebaut AG anchors supply security through captive cocoa processing networks. Lindt & Sprungli differentiates via boutique subscription tiers targeting gift-oriented segments.
Low-calorie dark chocolate denotes cocoa-based confectionery with reduced sugar and fat content, typically achieved through alternative sweeteners such as erythritol or stevia and higher cocoa mass percentages exceeding seventy percent. Manufacturers employ conching and tempering processes optimized for lower viscosity formulations to preserve snap and mouthfeel in finished bars. Bars dominate product type revenue due to portion-controlled positioning and premium pricing elasticity, while online retailers represent the fastest-growing distribution channel as algorithm-driven personalization funnels fitness enthusiasts toward subscription models. Health food stores retain margin concentration through curated assortments and dietitian endorsement programs.
FDA nutrition labeling requirements and EFSA health claims regulations govern permissible calorie reduction claims and alternative sweetener safety thresholds across the United States and European markets. The EU Green Deal's deforestation-free supply chain mandates compel traceability investments from bean origin through retail shelf. Stakeholders must monitor evolving sweetener approval timelines and carbon disclosure rules to preempt compliance cost escalation.
Market Dynamics
Clean-label formulation mandates under FDA and EFSA guidance are compressing ingredient flexibility and forcing reformulation investments across the low-calorie dark chocolate supply chain. Manufacturers must now validate every sweetener and cocoa sourcing claim through third-party certification to retain shelf placement in premium retail channels.
Growth Catalysts
- EU Green Deal deforestation-free mandates:Traceability requirements are accelerating investment in bean-to-bar verification systems, creating competitive differentiation for compliant suppliers in European retail.
- Fitness enthusiast subscription adoption:Algorithm-driven personalization on e-commerce platforms is converting occasional indulgence purchases into predictable recurring revenue streams.
- Erythritol-stevia blending protocols:Optimized conching processes for alternative sweetener viscosity are enabling texture parity with conventional dark chocolate at reduced caloric density.
Market Restraints
- Cocoa butter price volatility:Input cost swings in West African supply regions compress margin predictability for manufacturers dependent on single-origin positioning.
- EFSA novel food approval timelines:Regulatory friction for emerging sweetener candidates delays product pipeline expansion by 18-36 months versus conventional formulations.
- High-intensity sweetener aftertaste limitations:Technical constraints in masking bitter notes restrict achievable cocoa mass percentages in mass-market price tiers.
Strategic Opportunities
- Japanese functional food convergence:Underpenetrated demand for cocoa polyphenol health claims creates white space for positioning low-calorie dark chocolate as nutraceutical-adjacent snacking.
- US Inflation Reduction Act clean manufacturing incentives:Tax credits for carbon-reduced processing equipment lower barrier to entry for domestic bean-to-bar retrofit investments.
- Direct-to-consumer gifting tier expansion:Boutique subscription services targeting corporate wellness programs represent an emerging channel with premium pricing elasticity.
Industry Challenges
- Confectionery technologist talent scarcity:Specialized expertise in low-viscosity tempering protocols commands premium compensation, constraining mid-tier manufacturer R&D scaling.
- Multi-jurisdiction sweetener approval synchronization:Divergent safety thresholds between FDA GRAS designations and EFSA novel food classifications fragment global product platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Dark Chocolate Market |
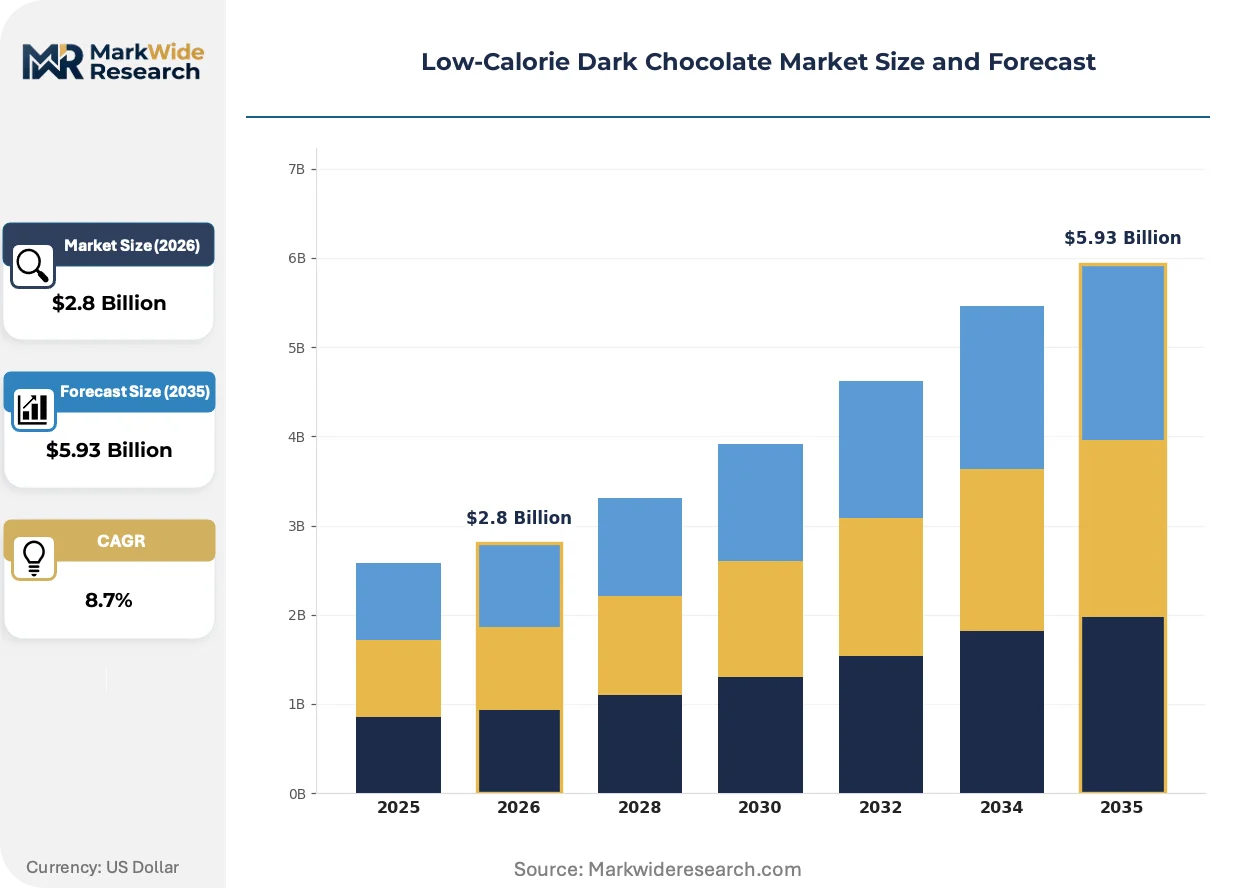
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Coated Nuts, Baking Chocolate, Snacks Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores Packaging Type: Bags, Boxes, Wrappers, Pouches End User: Health-Conscious Consumers, Diabetics, Fitness Enthusiasts, Gourmet Chefs |
| Companies Covered | Nestle S.A., The Hershey Company, Mondelez International, Barry Callebaut AG, Lindt & Sprungli, Ferrero SpA, Mars Incorporated, Godiva Chocolatier, Alter Eco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Dark Chocolate Market Evolving Landscape
Formulation science and supply chain transparency technologies are compressing development cycles and reshaping competitive differentiation in reduced-calorie cocoa confectionery. Three convergent forces are restructuring how manufacturers capture value.
Precision fermentation-derived cocoa butter alternatives are consolidating as a viable pathway to decouple finished product costs from commodity cocoa price cycles. Specialty chocolate manufacturers in Germany and Switzerland are piloting these lipids at commercial scale, with initial sensory panel results achieving mouthfeel parity in blind testing. This biotechnology is compressing the traditional bean-sourcing moat that historically protected vertically integrated incumbents.
REACH-compliant deforestation due diligence obligations are mandating geospatial traceability from farm cooperative through processing facility. European manufacturers must now submit satellite-verified chain-of-custody documentation to retain market access, with enforcement ramping through competent authorities in member states. Mid-tier suppliers without captive plantation networks are responding through blockchain-anchored certification partnerships with West African cooperatives.
Boutique health food retailers are unbundling after-sales dietitian endorsement programs from product placement fees, creating a new gatekeeper layer between manufacturers and wellness-oriented consumers. This service model shift concentrates purchase influence in curated assortments at specialty chains in the United States and Japan. Subscription algorithm personalization funnels fitness enthusiasts toward specific cocoa percentage tiers based on macronutrient logging integration.
Low-Calorie Dark Chocolate Market Segmentation
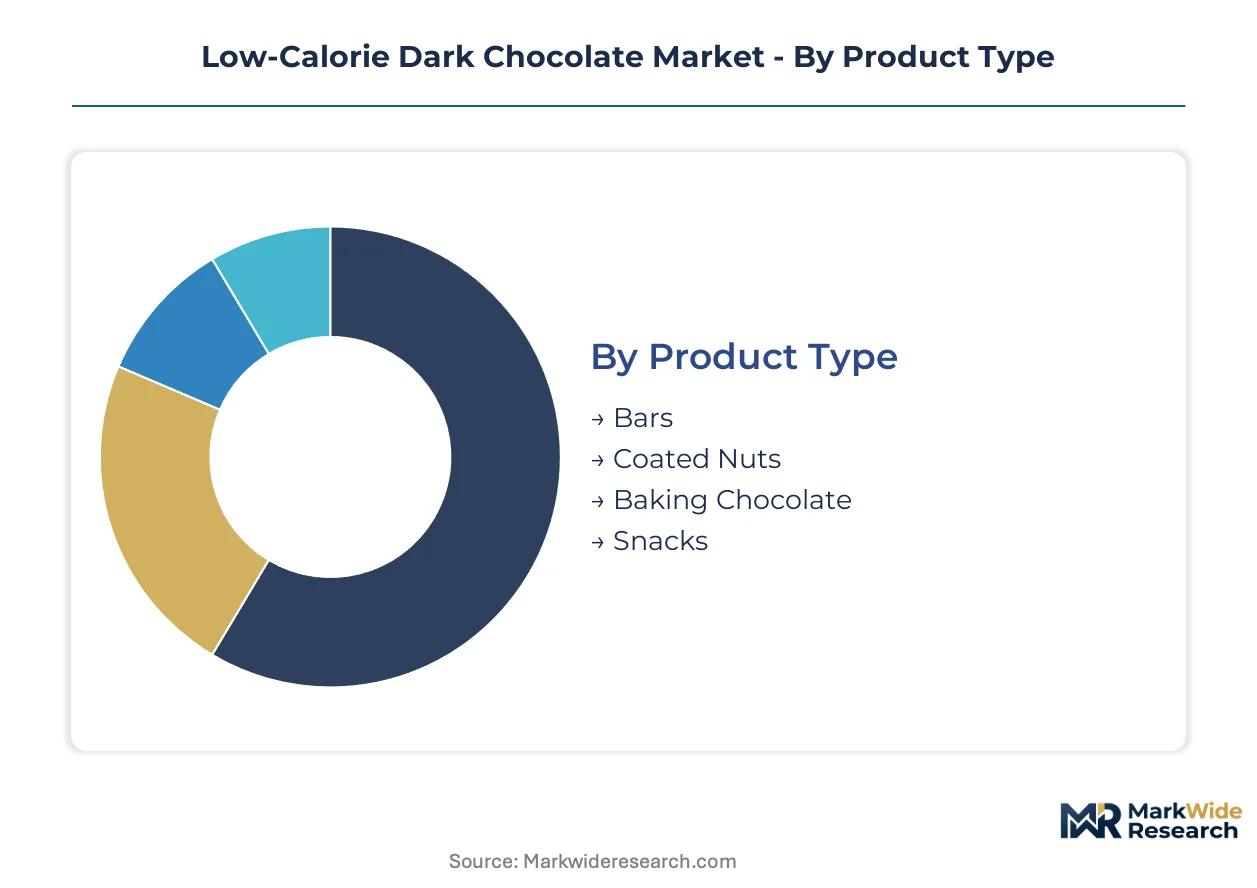
Segmentation in low-calorie dark chocolate reveals how formulation constraints and channel economics fragment buyer access. Each dimension exposes distinct margin structures and loyalty mechanics that manufacturers must navigate.
Product Type:
Portion control and usage occasion drive purchase frequency more than cocoa percentage alone.
- Bars:Standardized 25-40 gram formats with calibrated snap profiles dominate premium shelf placement. Demand concentrates in United States urban markets where calorie-counting apps integrate with retail loyalty programs, though single-origin positioning limits mass-market price elasticity.
- Snacks:Bite-sized clusters and enrobed formats optimize for on-the-go consumption with higher permissible sweetener loads. Fitness enthusiasts in Germany and Japan sustain repeat purchase through gym-adjacent vending and subscription replenishment.
- Coated Nuts:Almond and hazelnut centers with thin cocoa shells balance protein claims with indulgence positioning.
- Baking Chocolate:Higher cocoa mass percentages above eighty percent target home bakers seeking sugar reduction in dessert applications.
Volume sits with Bars; growth tilts toward Snacks.
Distribution Channel:
Channel selection determines which regulatory claims manufacturers can deploy and which sweetener blends pass shelf review.
- Online Retailers:Algorithm-driven personalization funnels repeat buyers toward subscription tiers with macronutrient transparency. United States platforms leverage FDA-permitted structure-function claims that health food stores cannot replicate without dietitian staffing.
- Health Food Stores:Curated assortments with third-party certification requirements command margin premiums through exclusive access. Japanese specialty chains integrate METI-registered functional food labeling for cocoa polyphenol positioning.
- Supermarkets:Mass-market placement demands EFSA-compliant calorie reduction thresholds and clean-label ingredient decks.
- Convenience Stores:Impulse-oriented smaller formats sacrifice cocoa percentage for price accessibility and extended shelf stability.
Margin concentrates in Health Food Stores; transaction velocity peaks at Online Retailers.
Packaging Type:
Packaging mechanics influence perceived freshness and portion discipline without altering formulation.
- Wrappers:Individual foil-and-paper laminates preserve temper integrity through temperature fluctuation. German manufacturers favor this format for bean-to-bar lines requiring moisture barrier performance.
- Boxes:Rigid gift-oriented formats with partitioned inserts target corporate wellness programs and seasonal purchasing in United States metropolitan markets.
- Pouches:Resealable flexible films accommodate multi-serve snacking with oxygen scavenger integration for extended shelf life.
- Bags:Stand-up configurations with clear windows balance visibility with light protection for retail display.
Premium positioning clusters around Boxes; operational efficiency favors Wrappers.
End User:
User-specific health goals dictate acceptable sweetener portfolios and cocoa mass thresholds.
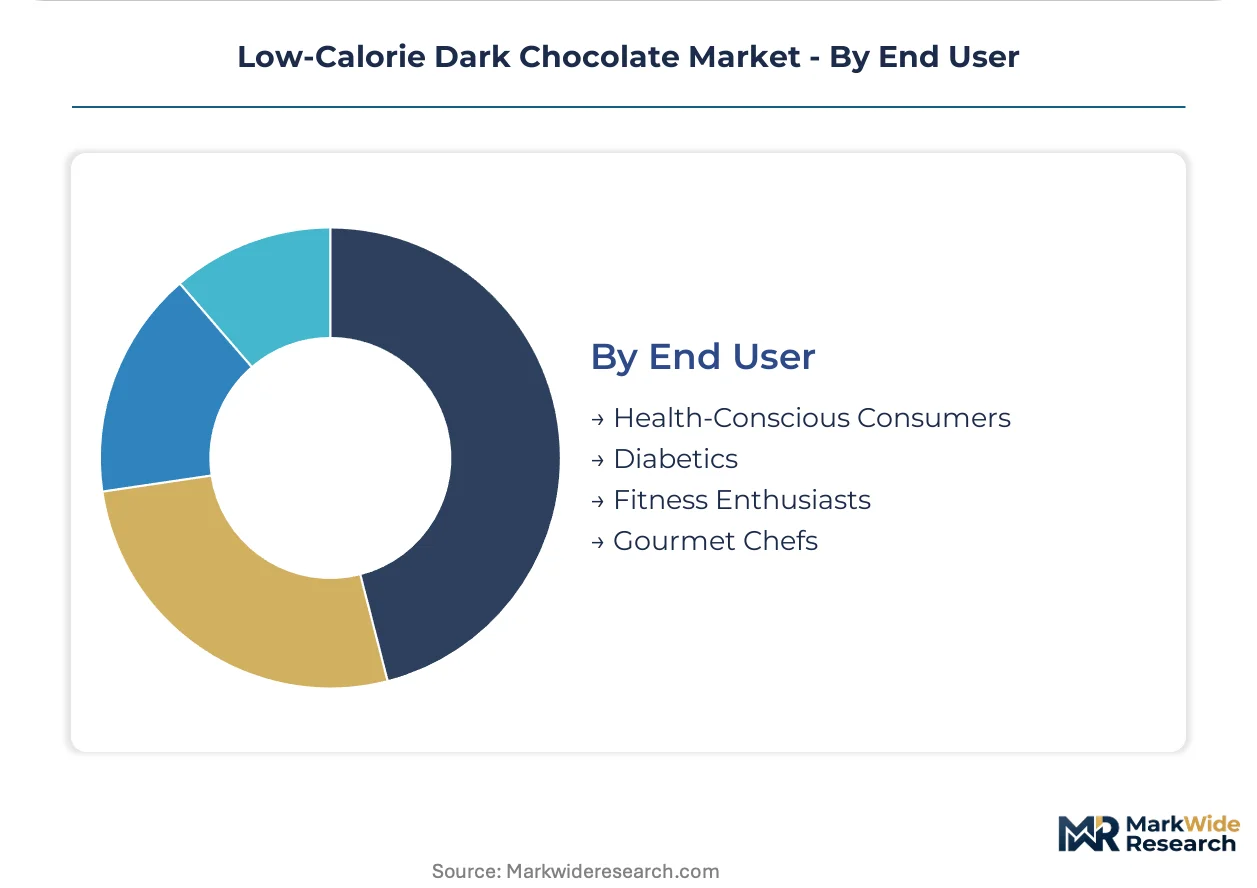
- Health-Conscious Consumers:Broad demographic seeking sugar reduction without sacrificing sensory satisfaction. United States demand centers on erythritol-stevia blends with FDA GRAS status, though aftertaste sensitivity limits achievable cocoa percentages.
- Fitness Enthusiasts:Macro-tracking integration and protein-paired formats drive platform loyalty. Japanese consumers in this segment respond to METI-approved functional claims linking cocoa flavanols to vascular health markers.
- Diabetics:Glycemic index certification requirements restrict formulation to specific polyol classes with digestive tolerance constraints.
- Gourmet Chefs:Professional kitchen applications demand precise melting profiles and batch consistency for pastry integration.
Health-Conscious Consumers anchor volume; Fitness Enthusiasts expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bean sourcing concentrates in West African cooperatives while consumption clusters in wealthy urban markets with wellness-oriented retail infrastructure. Manufacturing capability distributes across Swiss and German processing hubs, Japanese functional food laboratories, and North American direct-to-consumer fulfillment centers. Regulatory divergence between FDA GRAS pathways and EFSA novel food classifications fragments product platform strategies by destination market.
United States
Fitness enthusiasts drive subscription adoption through algorithm-driven personalization on e-commerce platforms. FDA nutrition labeling requirements govern permissible calorie reduction claims and structure-function positioning for cocoa polyphenol benefits. Bean-to-bar manufacturers in Brooklyn and San Francisco retrofit facilities to capture IRA clean manufacturing tax credits for carbon-reduced processing equipment.
Germany
Health food store chains command margin premiums through curated assortments and third-party certification requirements. REACH-compliant deforestation due diligence obligations mandate geospatial traceability documentation for European retail access. Precision fermentation pilots in Cologne and Hamburg test cocoa butter alternatives to decouple finished costs from commodity price cycles.
Japan
Functional food convergence creates demand for METI-registered cocoa flavanol health claims linking consumption to vascular markers. METI standards govern functional food labeling and substantiation requirements for polyphenol positioning. Specialty retailers in Tokyo and Osaka integrate dietitian endorsement programs that concentrate purchase influence in curated wellness assortments.
Switzerland
Confectionery heritage anchors premium positioning through optimized conching protocols for low-viscosity alternative sweetener formulations. Swissmedic oversight applies to nutraceutical-adjacent products crossing into regulated health claim territory. Lindt & Sprungli and Barry Callebaut processing clusters around Zurich and Vevey sustain captive supply networks and boutique subscription tier development.
United Kingdom
Clean-label formulation mandates compress ingredient flexibility for manufacturers seeking premium supermarket placement. EFSA health claims regulations and post-Brexit retained EU law govern permissible sweetener safety thresholds and calorie reduction substantiation. London-based direct-to-consumer brands leverage gifting-oriented packaging formats targeting corporate wellness program procurement.
Low-Calorie Dark Chocolate Market Competitive Landscape
Top-tier vendors anchor consolidated premium positioning, while mid-tier specialists and private-label manufacturers occupy fragmented volume tiers. Market structure reflects three strategic archetypes: vertically integrated cocoa processors with captive bean sourcing, direct-to-consumer wellness brands with subscription infrastructure, and multinational confectionery conglomerates with mass-market distribution leverage. Dominant competitive moves include M&A to secure deforestation-compliant supply chains and portfolio diversification into functional food positioning.
Within the vertically integrated processing tier, Barry Callebaut AG and Lindt & Sprungli represent archetypes of supply security through captive networks and boutique subscription differentiation respectively. Mondelez International exemplifies multinational scale leverage through direct-to-consumer infrastructure and repeat purchase rate optimization. Among diversified conglomerates, Nestle S.A. and Mars Incorporated occupy positions spanning conventional confectionery and wellness-adjacent portfolio extensions.
| Leading Market Players |
|---|
| Nestle S.A. |
| The Hershey Company |
| Mondelez International |
| Barry Callebaut AG |
| Lindt & Sprungli |
| Ferrero SpA |
| Mars Incorporated |
| Godiva Chocolatier |
| Alter Eco |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Swiss and German processing clusters anchor supply discipline through generational capital allocation that resists short-term margin compression. Their captive bean-sourcing networks in West Africa insulate premium pricing tiers from commodity volatility while forcing contract manufacturers into cost-down races for supermarket placement.
Pricing Analysis
Margin tightening in mass-market tiers traces to erythritol-stevia blend cost escalation and supermarket slotting fee inflation. Three-tier pricing structure across premium, standard, and economy levels separates bean-to-bar subscription services from private-label supermarket lines and impulse-oriented convenience formats. Price differentiation rests on certification grade and cocoa mass percentage. Fitness enthusiasts in subscription channels show lowest price sensitivity; convenience store impulse buyers face highest elasticity.
Supply Chain Analysis
EU Green Deal deforestation-free certification gates European retail access and fragments supplier tiers between compliant and excluded origins. Cocoa bean supply concentrates in Côte d'Ivoire, Ghana, and Ecuador; processing capability clusters in Switzerland, Germany, and the United States. Raw material dependencies span cocoa butter, alternative sweetener feedstocks, and premium packaging substrates. Single-source vulnerability in West African cooperative networks threatens bean-to-bar traceability claims. Distribution runs through health food store chains in Germany, algorithm-driven e-commerce platforms in the United States, and METI-registered specialty retailers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label formulation mandates and EU Green Deal traceability requirements are consolidating market position around capital-intensive incumbents with compliant supply networks, forcing mid-tier contract manufacturers toward distressed exits or acquisition.
For Market Incumbents: Deploy captive plantation network expansion to preempt bean-to-bar verification bottlenecks as EU enforcement ramps through competent authorities. Accelerate precision fermentation pilot scale-up to decouple finished product costs from cocoa butter price cycles. Defend against subscription-platform disintermediation by integrating direct-to-consumer algorithm infrastructure with macronutrient logging partnerships. For New Entrants and Emerging Players: Capture Japanese functional food convergence by securing METI-registered cocoa flavanol health claims before incumbent portfolio extensions saturate the channel. Target corporate wellness program procurement through boutique gifting-tier subscription services with partitioned box formats. Pursue white-label manufacturing partnerships with distressed mid-tier processors lacking deforestation-compliant supply chains. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated bean-to-bar specialists with captive West African cooperative networks and existing blockchain-anchored certification infrastructure. Long-term viability concentrates in manufacturers with dual FDA-EFSA sweetener approval pathways and carbon-reduced processing equipment qualifying for IRA tax credits. Watch EFSA novel food approval timelines for emerging sweetener candidates as pipeline expansion inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Deforestation-Free Supply Chain Certification | EU Green Deal enforcement through member state competent authorities mandates geospatial traceability documentation for retail access. |
| Precision Fermentation Scale-Up | Cologne and Hamburg pilots test cocoa butter alternatives achieving sensory parity while decoupling costs from commodity cycles. |
| Direct-to-Consumer Subscription Infrastructure | Algorithm-driven personalization on United States platforms converts fitness enthusiasts into recurring revenue with macronutrient transparency. |
| METI-Registered Functional Food Positioning | Japanese specialty chains integrate dietitian endorsement programs concentrating purchase influence in curated wellness assortments. |
| Carbon-Reduced Processing Retrofit | Brooklyn and San Francisco bean-to-bar facilities capture IRA clean manufacturing tax credits for domestic equipment investment. |
Research Methodology
Independent corroboration across confectionery technologists, health food store category buyers, cocoa cooperative agronomists, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with supply chain directors at Swiss and German processing clusters, subscription platform operators in the United States, and METI registration consultants in Japan combined with secondary validation from FDA GRAS notifications, EFSA novel food opinions, EU Green Deal implementation guidance, and customs trade data. Bottom-up volume modeling and top-down value triangulation anchored the segmentation outputs.
Rate-of-change decomposition across the analysis window isolated volume drivers from pricing dynamics and mix shifts. Segmentation dimensions modeled include product format, distribution channel, packaging type, and end-user health goal. CAGRs derived from historical trajectory analysis and forward-looking regulatory enforcement calendars. Industry-specific forecast inputs incorporated sweetener approval pipeline timelines and deforestation compliance investment cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA novel food approval delays and West African cooperative network disruptions. Projections reflect assumptions on clean-label formulation standardization and carbon disclosure rule evolution. A model refresh is warranted upon material change in EU Green Deal enforcement intensity or precision fermentation commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Cocoa and Chocolate Market
Confectionery
India Chocolate Market
Confectionery
Low-Fat Candy Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Sugar Free Mints Market
Confectionery
UK Confectionery Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Global Confectionery Market
Confectionery
Diet Candy Market
Confectionery
Low Calorie Treats Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
North America Chocolate Market
Confectionery
Germany Chocolate Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
South Korea Chocolate Market
Confectionery
Infused Fruits Jellies Market