
 North-American Industrial Chocolate Market | 2026-2036
North-American Industrial Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
North-American Industrial Chocolate Market Analytics
Precision tempering and alkalization automation is reshaping how industrial chocolate achieves consistent viscosity and snap profiles for enrobing applications. Barry Callebaut leverages vertical integration from bean sourcing to liquid chocolate delivery to sustain margin control across North American confectionery accounts. Cargill Incorporated anchors its position through R&D intensity in reduced-sugar cocoa liquor formulations. Blommer Chocolate Company specializes in custom compound coatings for bakery and ice cream manufacturers.
North-American Industrial Chocolate comprises cocoa mass, cocoa butter, sugar, and emulsifiers processed through conching, refining, and tempering to achieve defined particle sizes below 30 microns and stable polymorphic crystal structures for industrial coating, molding, and filling operations. Milk chocolate retains the largest volume share across confectionery end users due to its balanced flavor profile and cost efficiency in enrobing lines. Dark chocolate segments are gaining fastest within premium and organic grade tiers as foodservice channels reformulate dessert menus with higher cocoa solid percentages. Compound chocolate occupies the economy tier where vegetable fat substitutions reduce raw material exposure to cocoa butter price swings.
FDA food safety standards, USDA organic certification requirements, and CFIA import regulations for cocoa bean traceability collectively govern ingredient sourcing, allergen labeling, and cross-border supply chain access across the United States and Canada. These frameworks elevate compliance costs for smaller processors while reinforcing the advantage of integrated manufacturers with in-house laboratory and audit capabilities. Stakeholders must monitor evolving clean-label mandates and carbon disclosure expectations from downstream retail and foodservice buyers.
Market Dynamics
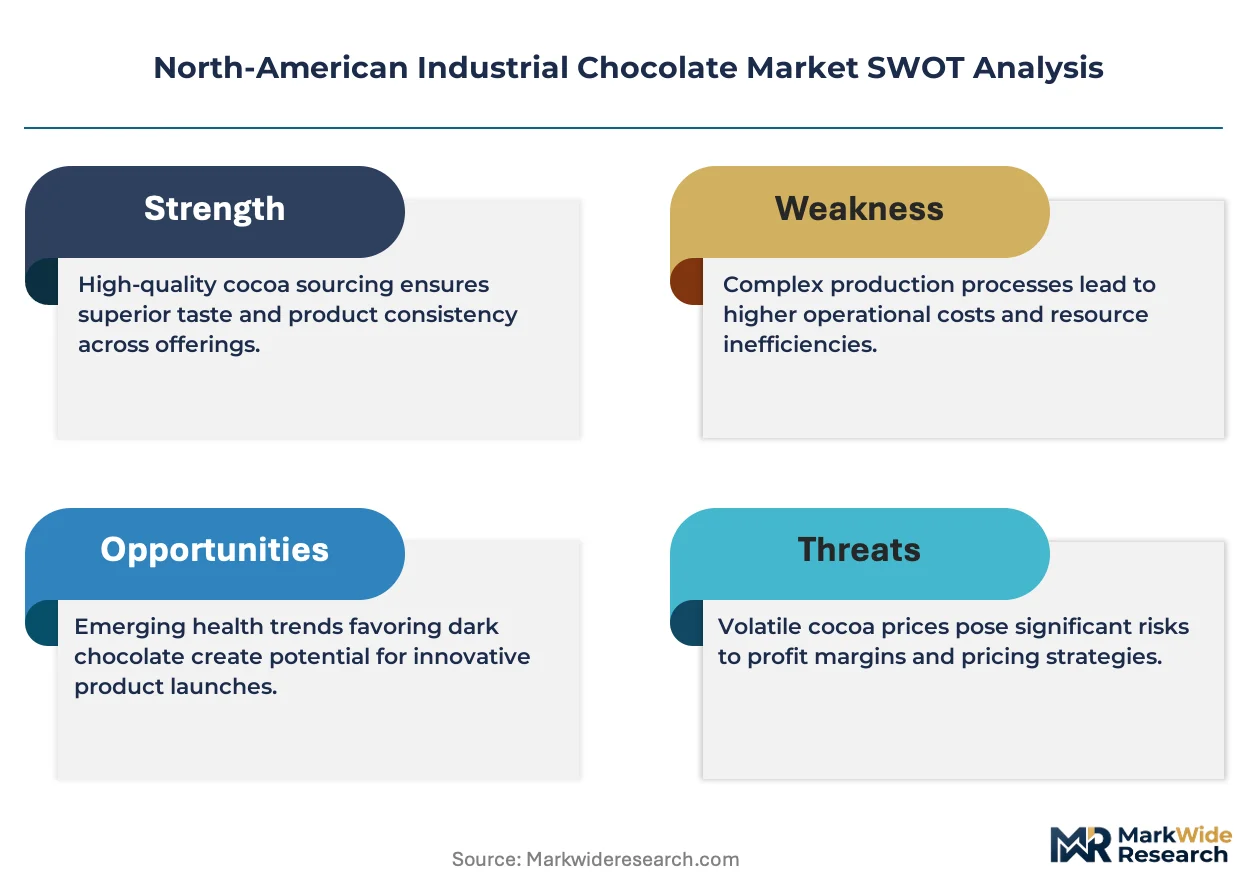
Precision tempering automation and FDA traceability mandates are compressing margins for small-batch processors while rewarding integrated manufacturers with captive laboratory and audit infrastructure across the U.S. and Canadian supply chain.
Growth Catalysts
- Clean-label reformulation:Foodservice channels in the U.S. Great Lakes corridor are scaling higher-cocoa-solid dessert coatings to meet evolving buyer specifications for ingredient transparency.
- FDA Food Safety Modernization Act:Traceability mandates for cocoa bean sourcing are accelerating consolidation toward processors with in-house laboratory capabilities and documented supply chain controls.
- Alkalization automation:Continuous pH-controlled processing systems are enabling consistent flavor profiles and reduced batch-to-batch variation for industrial enrobing applications.
Market Restraints
- Cocoa butter price volatility:London and New York futures market swings expose compound chocolate manufacturers to margin compression when vegetable fat substitutions face clean-label scrutiny.
- West African supply concentration:Ivory Coast and Ghana bean sourcing dominance creates geographic risk concentration that disrupts North American processing schedules during regional instability.
- Polymorphic crystal stability:Technical limitations in achieving consistent Form V crystal structures without precision tempering equipment restrict small-scale processors from industrial coating contracts.
Strategic Opportunities
- Canadian organic certification expansion:USDA organic equivalence agreements with CFIA import protocols create white space for certified-cocoa compound coatings in cross-border bakery and ice cream manufacturing.
- Reduced-sugar cocoa liquor formulations:Convergence of enzymatic debittering and alternative sweetener blending technologies opens premium positioning in health-positioned confectionery segments.
- Direct liquid chocolate delivery:Tanker-truck distribution channels bypass traditional block-and-pellet handling, reducing labor and melting energy costs for high-volume confectionery accounts.
Industry Challenges
- Conching operator skill scarcity:Specialized expertise in particle size reduction below 30 microns and rheology control is retiring faster than apprenticeship programs replenish qualified technicians.
- Dual certification timelines:Simultaneous FDA food safety audits and USDA organic inspections create compliance calendar conflicts that delay new product launches by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North-American Industrial Chocolate Market |
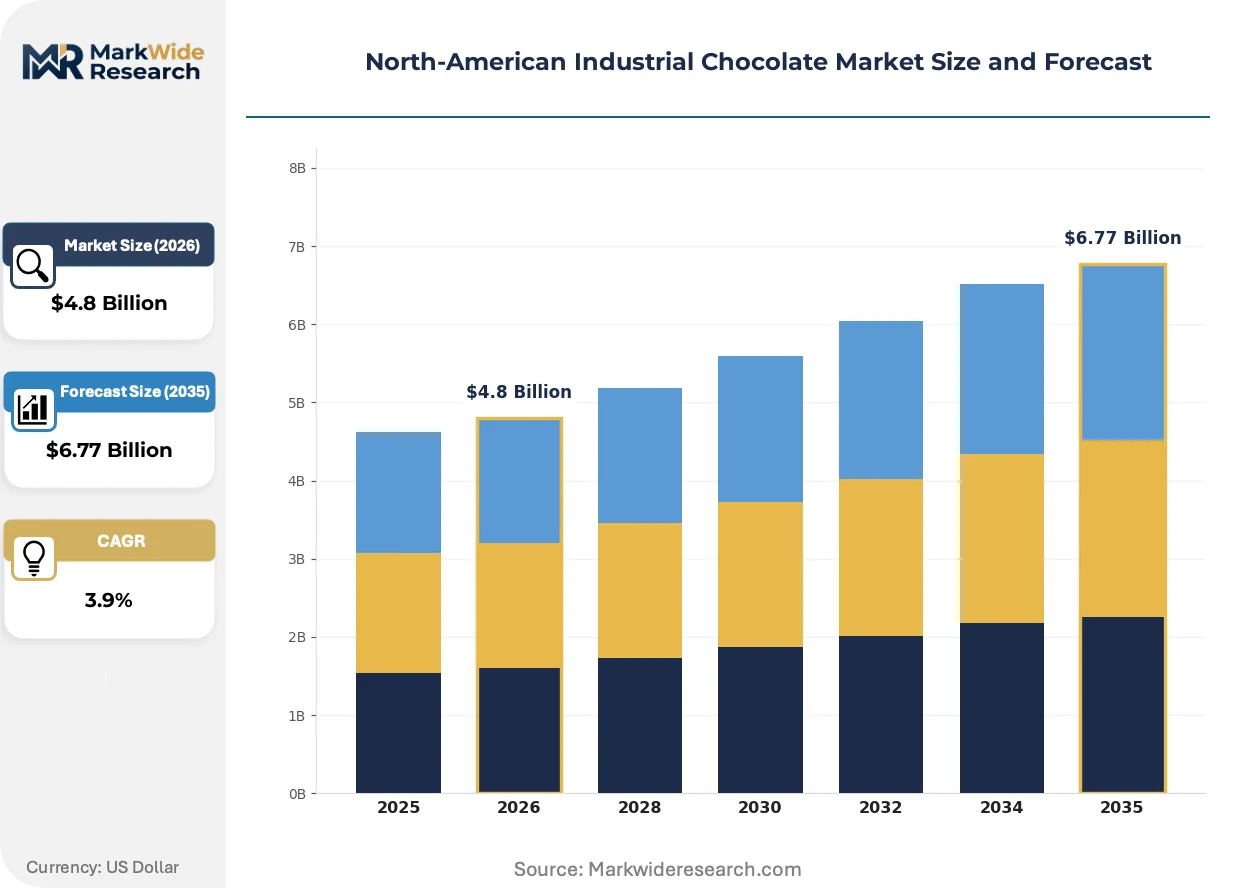
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Compound Chocolate End User: Confectionery, Bakery, Dairy Products, Foodservice Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores Grade: Premium, Standard, Organic, Fair Trade |
| Companies Covered | Barry Callebaut, Cargill Incorporated, Blommer Chocolate Company, Puratos Group, Fuji Oil Holdings Inc., AAK AB, Mars Incorporated, Mondelez International Inc., Nestlé Professional, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North-American Industrial Chocolate Market Evolving Landscape
Automation in particle size control and polymorphic crystal management is compressing the capability gap between artisan and industrial scale, while regulatory traceability requirements reshape competitive positioning around audit infrastructure rather than formulation alone.
Continuous conching systems with inline laser diffraction particle sizing are collapsing the traditional batch-to-batch quality variation that previously required skilled operator intervention. High-volume confectionery manufacturers in the U.S. Midwest are adopting these systems at replacement cycle pace. This technology compression is enabling smaller production runs with industrial-grade consistency, eroding the minimum-efficient-scale advantage that previously protected large processors.
CFIA import regulations for cocoa bean traceability and USDA organic certification requirements are tightening documentary burden across the U.S.-Canada border. Industrial chocolate processors must now maintain chain-of-custody records from farm gate to finished product. The organic segment faces the steepest compliance cost escalation, driving consolidation toward integrated manufacturers with dedicated regulatory affairs staff.
Foodservice procurement is consolidating toward single-source liquid chocolate contracts with guaranteed viscosity specifications and just-in-time tanker delivery. Large bakery and frozen dessert manufacturers are displacing multi-supplier pellet purchasing with captive storage tank installations at plant sites. This pattern is most visible in the U.S. Great Lakes manufacturing corridor where confectionery clusters anchor regional processing capacity and distribution economics favor direct delivery models.
North-American Industrial Chocolate Market Segmentation
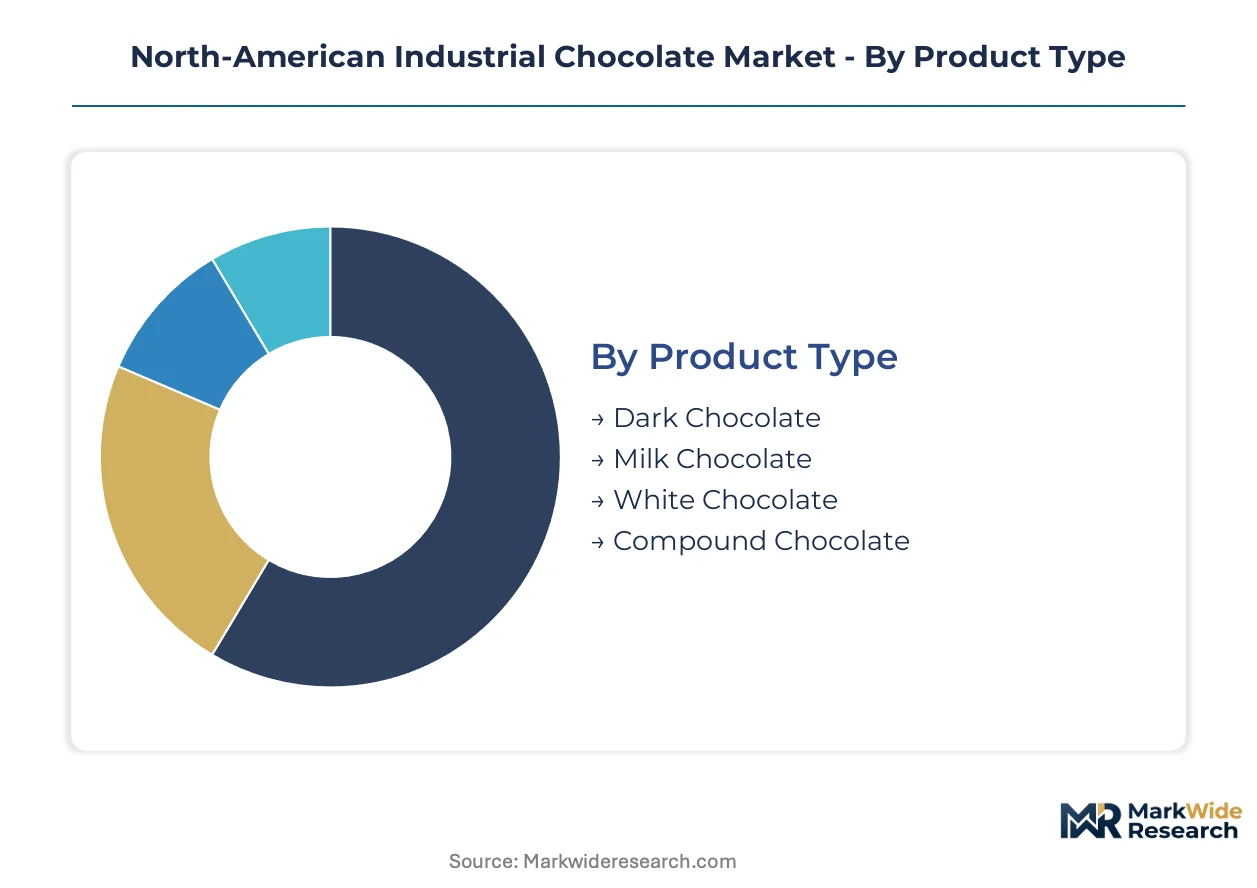
Industrial chocolate segmentation in North America tracks distinct specification requirements across confectionery coating, bakery inclusion, and foodservice enrobing applications. Each segment carries unique viscosity, particle size, and tempering demands that dictate supplier qualification timelines and contract structures.
Product Type:
Reformulation cycles vary from six months for compound coatings to eighteen months for premium dark chocolate as clean-label specifications tighten across the U.S. and Canada.
- Milk Chocolate:Balanced cocoa solid and milk powder formulations deliver optimal enrobing viscosity at 45-50°C working temperatures. Demand concentrates in high-volume Midwest confectionery operations where cost efficiency and snap consistency drive procurement decisions.
- Dark Chocolate:Higher cocoa mass percentages (50-70%) require precision tempering to achieve stable Form V polymorphism for industrial molding. Foodservice channels in the U.S. Great Lakes corridor are scaling dark chocolate dessert coatings to meet elevated cocoa solid specifications from premium menu positioning.
- Compound Chocolate:Vegetable fat substitutions reduce cocoa butter exposure for economy-tier bakery and ice cream applications.
- White Chocolate:Cocoa butter-dominated formulations without cocoa solids serve niche confectionery and decorative coating segments.
Milk chocolate anchors the volume base while dark chocolate gains share at the steepest rate.
End User:
Application-specific rheology requirements separate high-shear bakery inclusions from low-temperature frozen dessert coatings.
- Confectionery:Enrobing and molding operations demand particle sizes below 30 microns with precise tempering curves for snap and bloom resistance. Major clusters in Chicago and Toronto metropolitan areas sustain contract volumes through integrated liquid chocolate delivery systems.
- Foodservice:Dessert menu reformulation drives demand for higher cocoa solid percentages and certified organic grades. Canadian and U.S. bakery chains are consolidating procurement toward single-source tanker contracts with guaranteed viscosity specifications.
- Bakery:Chip and chunk inclusions require controlled fat bloom resistance through baking thermal profiles.
- Dairy Products:Ice cream coating applications prioritize quick-set properties and snap at freezer temperatures.
Confectionery anchors the volume base while foodservice expands most quickly.
Distribution Channel:
Logistics intensity varies from capital-heavy tanker infrastructure to lightweight e-commerce sample fulfillment.
- Direct Sales:Tanker-truck liquid chocolate delivery eliminates block handling and melting energy costs for high-volume accounts. The U.S. Great Lakes manufacturing corridor favors this model where regional processing capacity supports just-in-time distribution economics.
- Wholesale:Pellet and block formats serve mid-tier confectionery and bakery manufacturers without captive storage infrastructure.
- Online Retail:Sample and small-batch specialty ingredients reach artisan producers and R&D laboratories.
- Specialty Stores:Niche organic and fair-trade certified products target premium positioning segments.
Direct sales anchors the volume base while online retail climbs the fastest.
Grade:
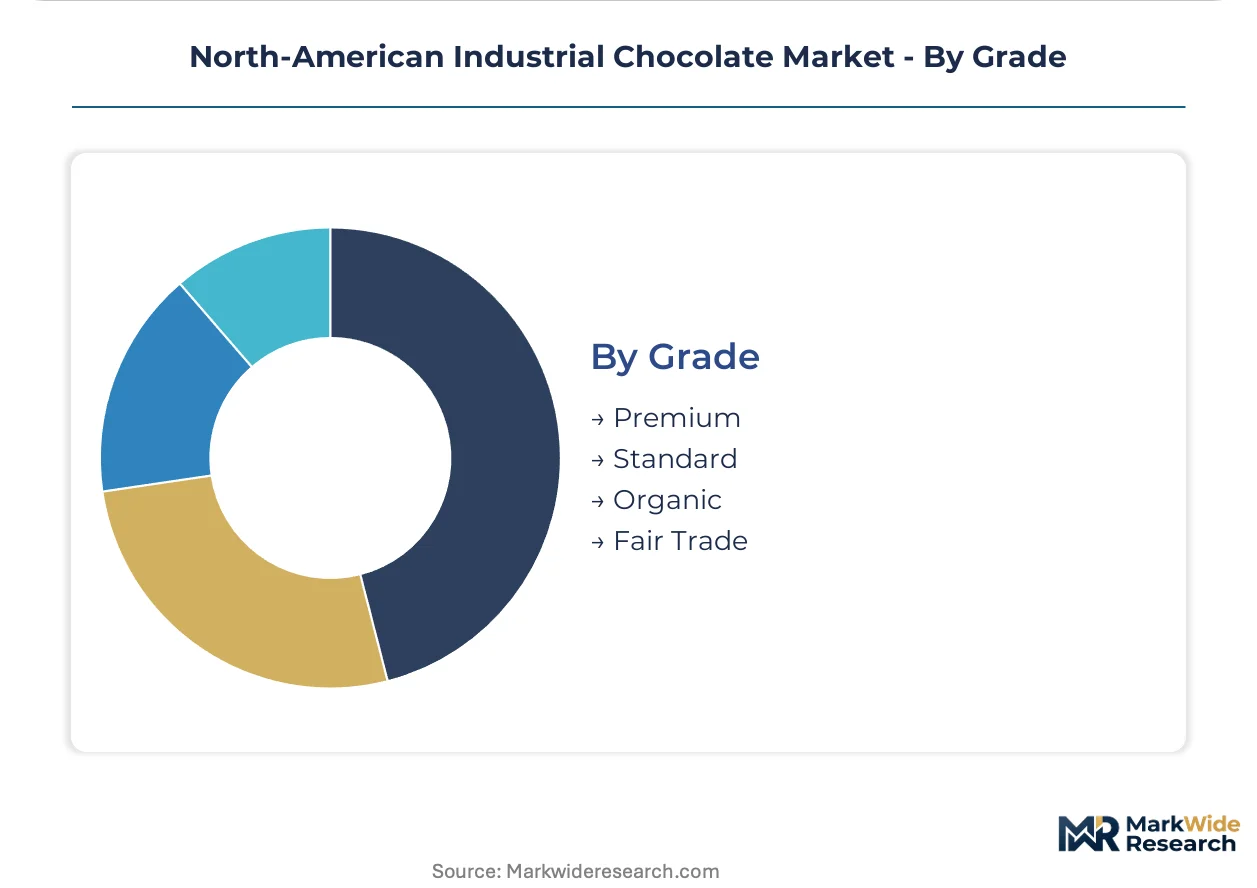
Certification burden and price positioning stratify procurement across mass-market and premium tiers.
- Standard:Conventional cocoa sourcing with FDA food safety compliance serves high-volume industrial applications where cost efficiency dominates supplier selection. Major U.S. confectionery manufacturers prioritize this grade for enrobing line consistency.
- Organic:USDA certification with CFIA import protocol alignment creates cross-border supply chain complexity. Canadian and U.S. organic equivalence agreements open white space for certified-cocoa compound coatings, though documentary burden drives consolidation toward integrated processors.
- Premium:Single-origin and high-cocoa-mass specifications target premium confectionery and foodservice positioning.
- Fair Trade:Certified sourcing documentation addresses downstream retail and foodservice buyer sustainability mandates.
Standard grade anchors the volume base while organic certification shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian cocoa butter exports flow primarily to U.S. confectionery manufacturers in the Great Lakes corridor, creating a tightly integrated North American supply chain governed by CFIA-USDA organic equivalence protocols and FDA traceability mandates.
United States
Midwest confectionery clusters in Chicago and Milwaukee drive bulk liquid chocolate demand through direct tanker delivery contracts. FDA Food Safety Modernization Act traceability requirements favor processors with captive laboratory infrastructure. The Great Lakes manufacturing corridor anchors regional processing capacity where just-in-time distribution economics dominate procurement patterns.
Canada
Toronto metropolitan area bakeries and frozen dessert manufacturers scale certified organic compound coatings under CFIA import protocols aligned with USDA equivalence agreements. Health Canada and PMRA oversight on food additive approvals shapes formulation choices. Quebec processing facilities specialize in cross-border supply to New England confectionery accounts.
Mexico
Coatzacoalcos and Tabasco cocoa processing zones supply semi-finished mass to U.S. compound chocolate manufacturers seeking cost-advantaged feedstock. COFEPRIS food safety standards and evolving organic certification frameworks create compliance complexity. Mexican processors concentrate in southeastern states with port access to Gulf Coast U.S. destinations.
North-American Industrial Chocolate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where scale advantages in liquid chocolate delivery systems separate tier-one suppliers from mid-volume competitors. Three archetypes dominate: integrated bean-to-liquid processors with captive sourcing infrastructure, regional compound coating specialists serving bakery and ice cream verticals, and diversified agricultural conglomerates leveraging commodity trading capabilities. Capacity expansion in continuous conching systems and strategic partnerships for organic certification compliance represent the dominant competitive moves reshaping supplier relationships.
Among North American integrated processors, Barry Callebaut, Cargill Incorporated, and Blommer Chocolate Company occupy positions exemplifying the scale-driven archetype. Barry Callebaut represents the vertically integrated model spanning bean sourcing through liquid delivery. Cargill Incorporated anchors the agricultural-conglomerate tier with commodity trading infrastructure. Blommer Chocolate Company exemplifies the regional specialist position with concentration in custom compound formulations for industrial bakery and frozen dessert accounts.
| Leading Market Players |
|---|
| Barry Callebaut |
| Cargill Incorporated |
| Blommer Chocolate Company |
| Puratos Group |
| Fuji Oil Holdings Inc. |
| AAK AB |
| Mars Incorporated |
| Mondelez International Inc. |
| Nestlé Professional |
| Others |
Value Network & Pricing Analysis
Chicago-Milwaukee confectionery clusters concentrate liquid chocolate processing capacity, concentrating pricing power among integrated manufacturers with captive tanker-truck distribution networks while squeezing compound coating specialists exposed to cocoa butter futures volatility.
Pricing Analysis
Cost-plus contracts indexed to London and New York cocoa butter futures dominate procurement between U.S. Great Lakes processors and high-volume confectionery accounts. Three-tier pricing structure across premium dark chocolate, standard milk chocolate, and economy compound coatings separates organic-certified formulations from conventional grades. Pricing pressure stems from clean-label reformulation mandates that disqualify vegetable fat substitutions previously used to hedge cocoa butter exposure. Foodservice channels show lowest price sensitivity due to menu-positioning premiums, while bakery manufacturers face acute margin compression from ingredient cost pass-through limitations.
Supply Chain Analysis
Export-control documentation requirements under FDA Food Safety Modernization Act traceability rules constrain cross-border flows of semi-finished cocoa mass from Ivory Coast, Ghana, and Ecuador into North American processing facilities. West African bean sourcing dominance draws from concentrated harvesting calendars and port logistics at Abidjan and Tema, creating single-source vulnerability during regional political instability. Supply chain risk centers on geographic concentration of fermentary and drying operations within 200 kilometers of coastal export zones. Distribution runs through direct liquid chocolate tanker delivery to captive storage installations at major confectionery plant sites, displacing traditional block-and-pellet wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in foodservice dark chocolate adoption and organic certification penetration creates runway for capacity investments ahead of regulatory compliance consolidation.
For Market Incumbents: Entrench laboratory and audit infrastructure to defend against FDA traceability mandate acceleration that disadvantages smaller processors without in-house capabilities. Prioritize backward integration into West African fermentary partnerships to secure documented supply chain controls. Expand continuous conching capacity in the U.S. Midwest to capture foodservice liquid chocolate contract consolidation. For New Entrants and Emerging Players: Canadian organic compound coating manufacturing under CFIA-USDA equivalence agreements offers underpenetrated white space with lower competitive density than U.S. Great Lakes corridor. Target cross-border bakery and frozen dessert accounts seeking certified-cocoa formulations without integrated processor minimum order requirements. Lead with enzymatic debittering technology partnerships to differentiate reduced-sugar cocoa liquor positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated processors with captive sourcing infrastructure over regional compound specialists facing margin compression. Long-term viability hinges on regulatory compliance scalability rather than formulation differentiation alone. Monitor CFIA import protocol tightening as inflection indicator for accelerated consolidation toward audit-capable manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Conching System Deployment | Inline laser diffraction particle sizing collapses batch-to-batch variation for industrial-grade consistency at smaller scale. |
| West African Fermentary Partnership | Documented supply chain controls satisfy FDA traceability mandates while securing preferential bean access. |
| Organic Certification Investment | USDA-CFIA equivalence alignment opens cross-border Canadian market access for compound coating formulations. |
| Liquid Chocolate Tanker Infrastructure | Direct delivery bypasses block handling costs and locks in foodservice procurement consolidation. |
| Reduced-Sugar Formulation R&D | Enzymatic debittering technology enables premium positioning in health-oriented confectionery segments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers, procurement leads at downstream confectionery manufacturers, distribution channel partners, and regulatory affairs directors; and secondary validation through FDA food safety filings, USDA organic certification databases, CFIA import records, and customs trade data. Bottom-up volume triangulation across product grades and end-use segments converged with top-down market sizing from processor capacity disclosures.
Forecast inputs span milk chocolate, dark chocolate, compound chocolate, and white chocolate product types across confectionery, foodservice, bakery, and dairy end-use applications. Modeled dimensions include viscosity specifications, particle size tiers, and certification grades. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion across the projection horizon. Cocoa butter futures price trajectories and clean-label reformulation adoption curves inform scenario boundaries.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated bean-to-liquid processors would shift outcomes through accelerated contract consolidation. Material shifts in FDA traceability enforcement timelines or West African supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Sugar-Free Sweets Market
Confectionery
Ruby Chocolate Market
Confectionery
Canada Chocolate Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Crunchy Chocolate Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Xylitol Lollipops Market
Confectionery
Germany Chocolate Market
Confectionery
Vegan Candies Market
Confectionery
Jellies and Gummies Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Chocolate Couverture Market
Confectionery
Europe Chocolate Market
Confectionery
Non-Chocolate Candy Market
Confectionery
Asia Pacific Sugar Confectionery Market