
 UK Compound Chocolate Market | 2026-2036
UK Compound Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
UK Compound Chocolate Market Analytics
UK manufacturing capacity in compound chocolate is rewriting supply dynamics for British confectionery and bakery channels. Cargill leverages its integrated oilseed processing network to secure consistent cocoa butter equivalent supplies. Barry Callebaut sustains extensive technical service operations that anchor relationships with industrial bakery clients. AAK specializes in shea-based fat solutions that differentiate its portfolio from palm-centric competitors.
Compound chocolate substitutes cocoa butter with vegetable fats such as palm kernel oil, shea stearin, or coconut oil, achieving melting profiles between 34°C and 37°C while reducing raw material costs by roughly one-third versus true chocolate. Manufacturers formulate these products for enrobing, moulding, and panning applications where snap and gloss requirements are moderate. Milk compound dominates volume flows into British bakeries and ice cream manufacturers, where cost sensitivity and process tolerance outweigh premium positioning. Dark compound occupies the fastest-expanding margin pool as clean-label and vegan claims drive reformulation among snack producers and specialty confectioneries.
The UK Food Standards Agency enforces strict vegetable fat disclosure under retained EU chocolate regulations, while the Food Standards Scotland coordinates enforcement across the devolved administration. BSI standards for cocoa and chocolate products define compositional thresholds that determine whether products qualify as chocolate or must carry compound labeling. The Health and Safety Executive governs allergen control in manufacturing facilities, particularly for milk and soy lecithin handling. Stakeholders must monitor evolving DEFRA consultations on palm oil sustainability mandates and their downstream impact on fat sourcing strategies.
Market Dynamics
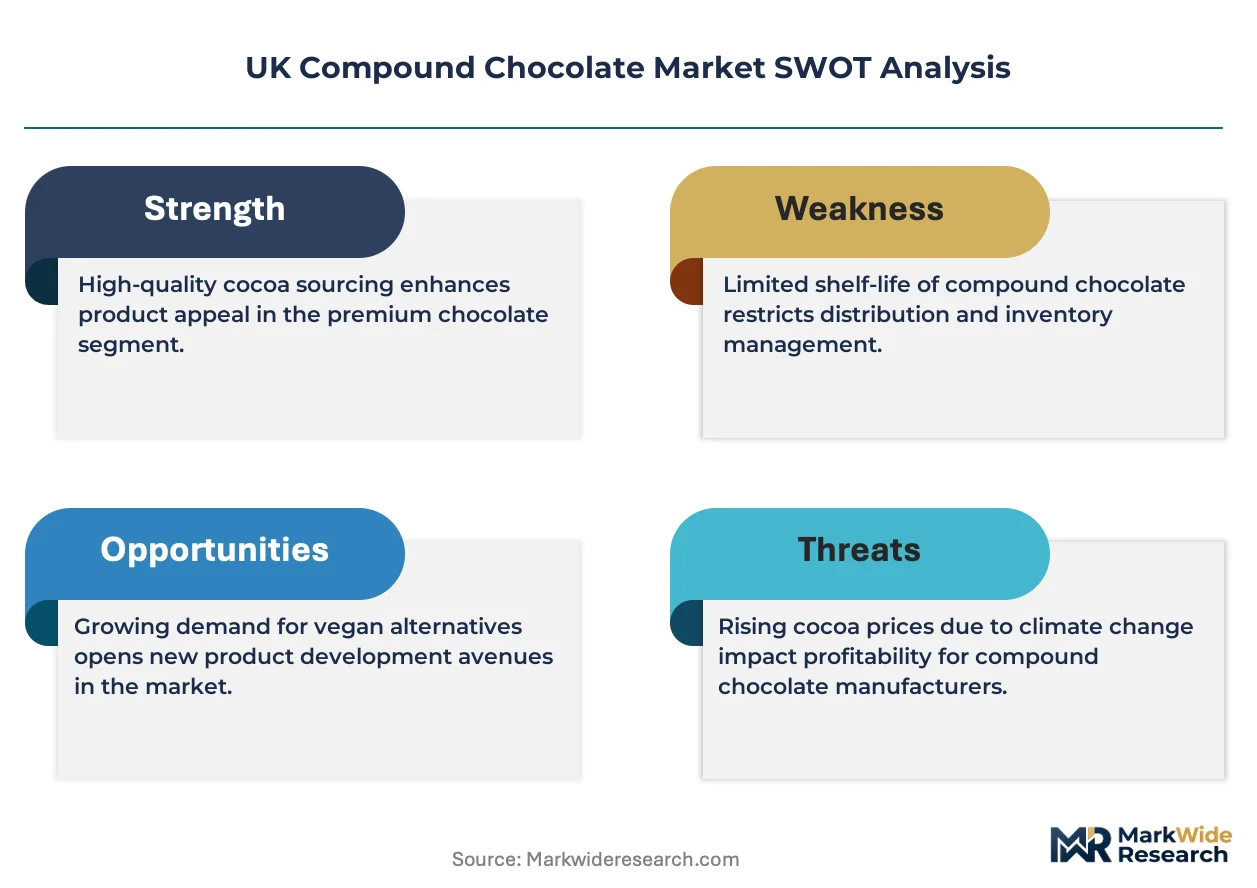
The UK Food Standards Agency's retained EU chocolate regulations are forcing manufacturers to reformulate around stricter vegetable fat disclosure thresholds, compressing margins for compound producers while redirecting R&D spend toward shea and palm kernel oil alternatives that meet sensory benchmarks.
Growth Catalysts
- Clean-label reformulation:Vegan and plant-based claims among British snack producers are accelerating dark compound adoption as cocoa butter alternatives achieve improved mouthfeel profiles without dairy solids.
- Industrial bakery expansion:Greater Manchester's baking corridor is consolidating procurement volumes, creating dedicated compound chocolate supply contracts with technical service requirements.
- DEFRA sustainability consultations:Pending palm oil mandates are shepherding manufacturers toward shea stearin and coconut oil sourcing, diversifying fat supply bases ahead of compliance deadlines.
Market Restraints
- Cocoa butter price volatility:True chocolate price spreads constrain compound pricing power, squeezing margins when cocoa futures spike on West African supply disruptions.
- Shea supply concentration:West African shea nut processing bottlenecks create raw material vulnerability for AAK and similar shea-specialist formulators.
- Labelling friction:BSI compositional thresholds force "compound chocolate" disclosure that disadvantages positioning against true chocolate in premium retail channels.
Strategic Opportunities
- Scottish ice cream manufacturing:Food Standards Scotland enforcement harmonization creates formulation standardization opportunities across the devolved administration's dairy-alternative dessert segment.
- West Midlands confectionery cluster:Underpenetrated specialty snack producers present white space for dark compound with certified sustainable palm-free claims.
- Shea-coconut fat blending:Converging fractionation technologies enable custom melting point formulations for enrobing applications previously locked to cocoa butter.
Industry Challenges
- Fat technologist scarcity:Formulation chemistry expertise for cocoa butter equivalent optimization is concentrating at Barry Callebaut and Cargill, limiting mid-tier manufacturer access.
- Allergen line segregation:Health and Safety Executive milk and soy lecithin protocols demand capital-intensive dedicated processing infrastructure for clean-label product runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Compound Chocolate Market |
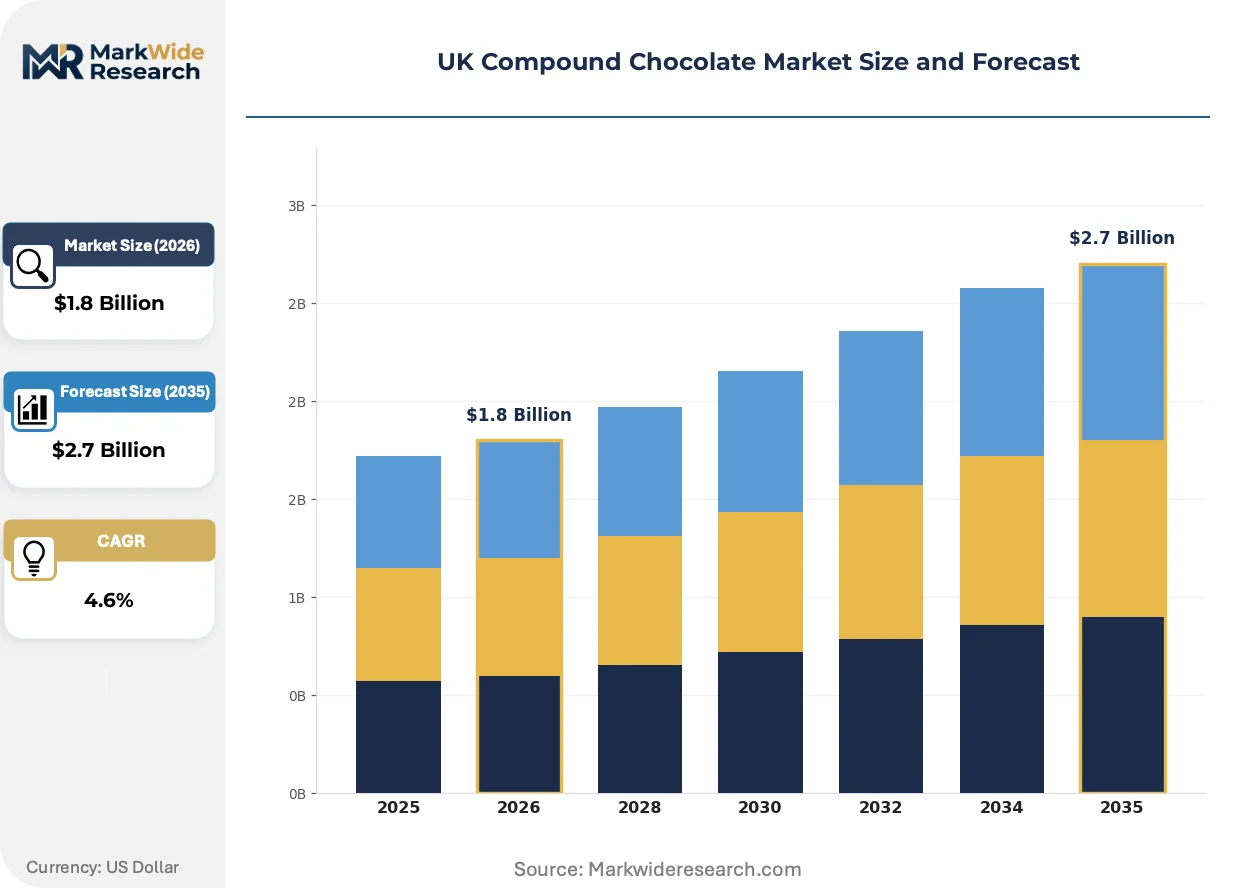
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Compound, Milk Compound, White Compound, Flavored Compound End User: Bakeries, Confectioneries, Ice Cream Manufacturers, Snack Producers Packaging Type: Bags, Bars, Pouches, Bulk Containers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service |
| Companies Covered | Cargill, AAK, Fuji Oil Holdings Inc, Puratos, Barry Callebaut, Natra, Pecan Deluxe Candy Europe Ltd, Ingredients UK Ltd, Sephra, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Compound Chocolate Market Evolving Landscape
Fractionation and enzymatic interesterification technologies are compressing the sensory gap between compound and true chocolate, while regulatory pressure on palm sourcing is redirecting formulation roadmaps toward shea-dominated fat architectures.
Enzymatic interesterification of shea stearin and palm kernel olein is rendering obsolete traditional chemical interesterification for mid-range melting profile compounds. West Midlands industrial bakeries are adopting these enzymatic grades for enrobing operations where gloss retention requirements are tightening. The technology is rendering obsolete legacy compound formulations that relied on trans-fatty acid fractions now excluded under FSA nutritional profiling guidance.
DEFRA's evolving palm oil sustainability mandates are tightening due diligence requirements across UK confectionery supply chains. Manufacturers must now document certified sustainable palm kernel oil provenance or switch to shea-based alternatives to maintain retailer listings. Dark compound producers targeting Sainsbury's and Waitrose supply chains are accelerating reformulation timelines to meet 2025 procurement specifications.
British bakery procurement teams are consolidating supplier relationships around technical service capabilities rather than spot-price purchasing. Industrial accounts in Greater Manchester now require on-site fat bloom troubleshooting and tempering protocol optimization as standard contract terms. This behavioral shift is most pronounced among frozen dessert manufacturers where process tolerance windows have narrowed to match true chocolate handling parameters.
UK Compound Chocolate Market Segmentation
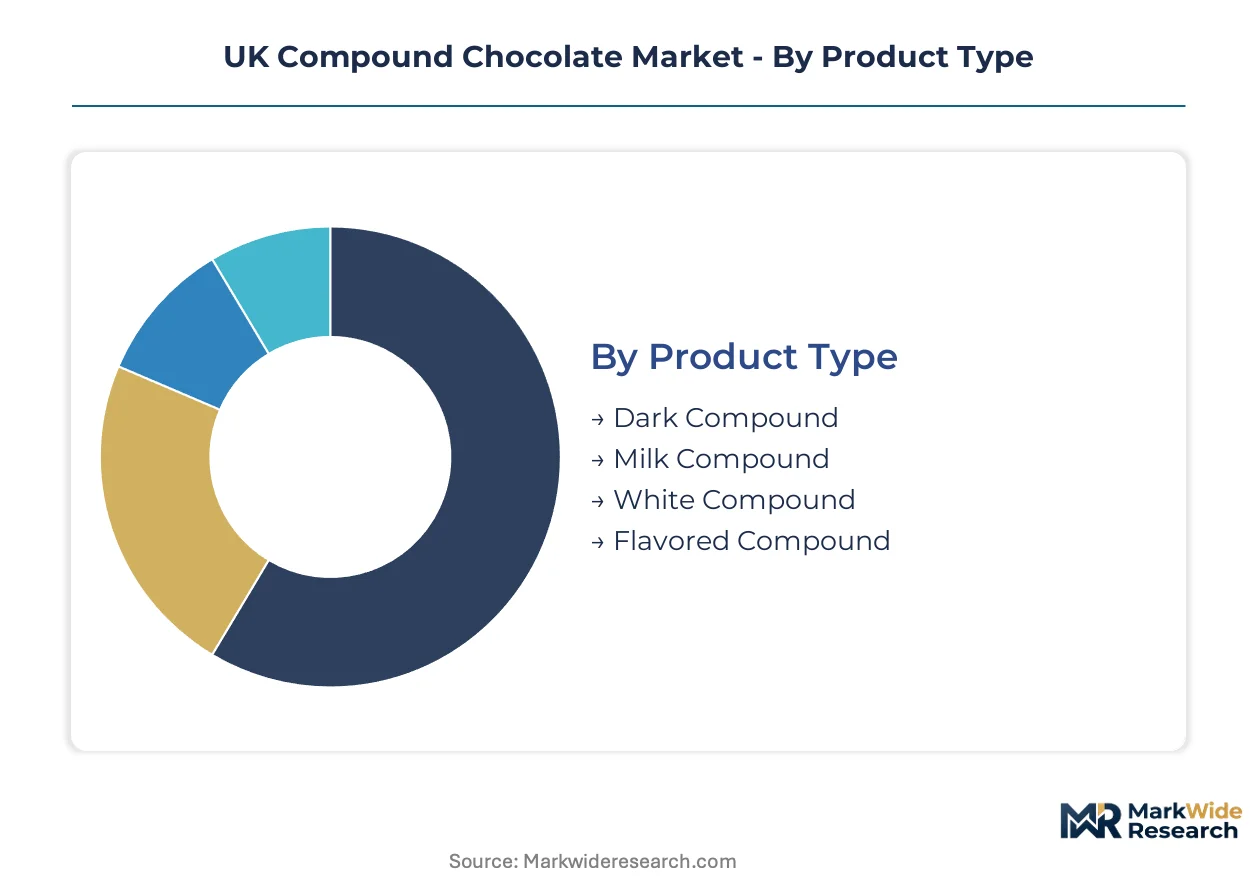
UK compound chocolate procurement patterns diverge sharply across product chemistry, end-use process requirements, and packaging formats. Understanding these fault lines reveals where formulation investments concentrate and which customer relationships command premium technical service resources.
Product Type:
Cost tier segmentation separates commodity volume plays from margin-accretive specialty formulations, with fat architecture and cocoa solids content driving price positioning.
- Dark Compound:Cocoa mass dominates at 35-50% content with shea stearin or palm kernel oil replacing cocoa butter, delivering clean-label vegan positioning without dairy solids. Snack producers in the West Midlands are rotating into this segment as Sainsbury's and Waitrose procurement specifications harden around sustainable palm-free claims.
- Milk Compound:Milk powder or whey solids constitute 12-20% of formulation alongside vegetable fat architectures, achieving cost structures roughly one-third below true milk chocolate. Industrial bakeries across Greater Manchester's baking corridor source this grade in bulk container volumes where process tolerance and enrobing efficiency outweigh premium positioning.
- White Compound:Cocoa butter-free formulations rely entirely on deodorized vegetable fats and dairy solids for mouthfeel, occupying a narrow niche in seasonal confectionery.
- Flavored Compound:Inclusions of mint, orange, or hazelnut extracts target limited-edition bakery and ice cream applications.
Milk compound holds installed capacity. Dark compound is rotating up the share rankings.
End User:
Application-specific process requirements dictate fat melting profiles and technical service intensity across British manufacturing clusters.
- Bakeries:Enrobing and moulding operations demand 34-37°C melting point compounds with snap characteristics mimicking true chocolate. Greater Manchester's frozen dessert manufacturers now require on-site fat bloom troubleshooting as standard contract terms.
- Confectioneries:Panning and shell-moulding applications prioritize gloss retention and tempering stability, driving adoption of enzymatically interesterified shea-palm kernel blends.
- Ice Cream Manufacturers:Coatings for stick novelties and inclusions require low viscosity at 45°C dipping temperatures with rapid fat crystallization.
- Snack Producers:Compound coatings for cereal bars and protein snacks emphasize clean-label vegan claims and rapid setting on high-speed enrobing lines.
Bakeries anchor volume procurement. Snack producers are climbing the fastest as reformulation timelines compress.
Packaging Type:
Volume scale and handling automation requirements segment procurement relationships between spot purchasing and integrated supply contracts.
- Bulk Containers:1000kg tote systems dominate industrial bakery procurement in the West Midlands, with heated discharge mechanisms maintaining 45-50°C fluidity for direct pipeline feeding.
- Bars:10-25kg blocks serve mid-tier confectioneries with manual tempering operations and lower throughput requirements.
- Bags:25kg valve sacks target smaller bakeries with intermittent production schedules.
- Pouches:1-5kg formats address craft chocolate makers and specialty dessert producers with limited storage infrastructure.
Bulk containers concentrate procurement leverage. Pouches are gaining share fastest among clean-label specialty entrants.
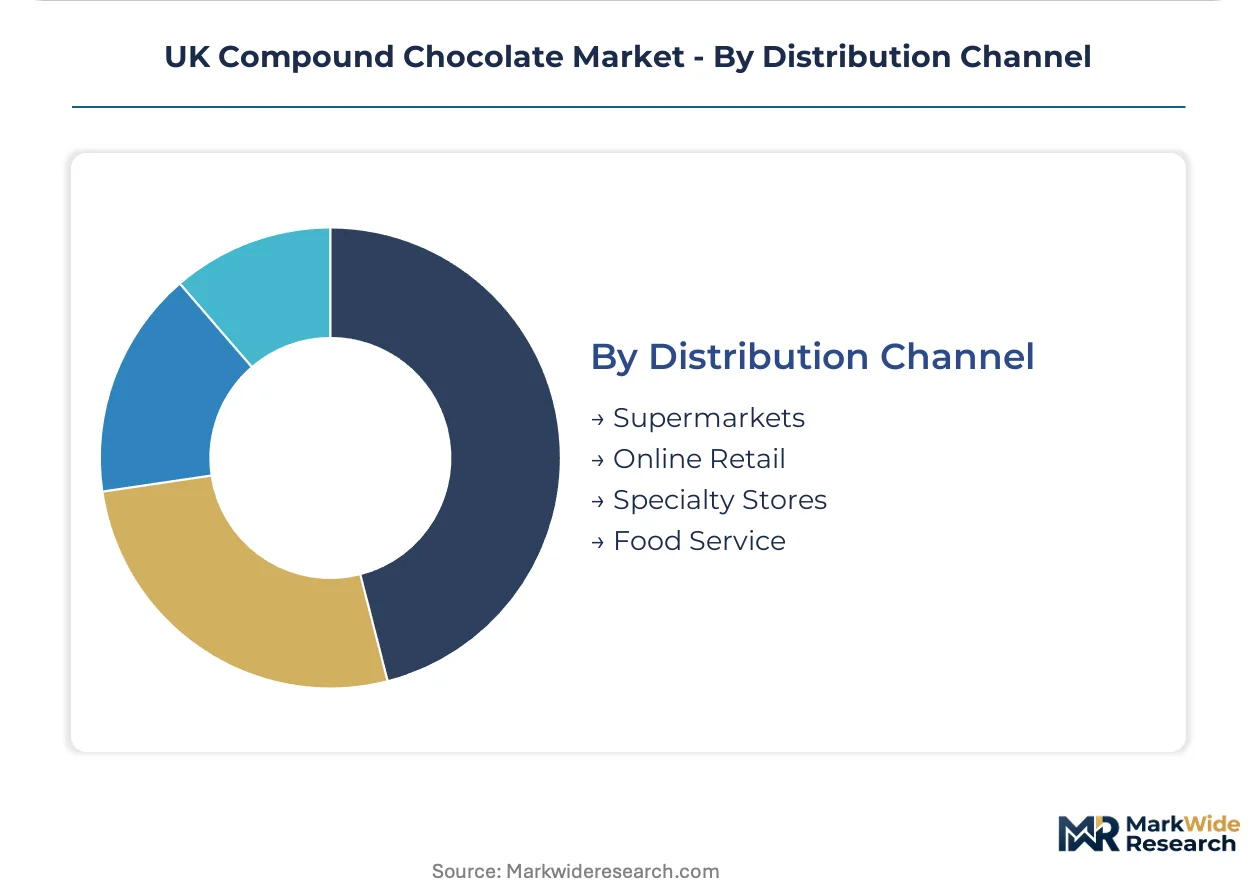
Distribution Channel:
Customer type and order fragmentation shape margin structures, with technical service bundling separating industrial contracts from transactional retail sales.
- Food Service:Direct manufacturer relationships with industrial bakeries and ice cream producers include formulation customization and on-site process optimization, capturing the highest service-embedded margins.
- Supermarkets:Retail compound chocolate for home baking occupies declining shelf space as own-label suppliers consolidate.
- Specialty Stores:Craft bakery supply shops and confectionery ingredient distributors serve small-batch producers with technical consultation.
- Online Retail:E-commerce penetration remains limited for industrial-grade compounds due to temperature-controlled logistics requirements.
Food service holds relationship density. Specialty stores are rotating up the share rankings as craft bakery formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK Food Standards Agency anchors regulatory oversight across England, Scotland, Wales and Northern Ireland, with retained EU chocolate regulations governing vegetable fat disclosure thresholds that reshape procurement patterns in each devolved administration.
England
Greater Manchester's industrial baking corridor drives bulk compound chocolate procurement for frozen dessert manufacturers requiring on-site fat bloom troubleshooting. The Food Standards Agency enforces strict BSI compositional thresholds that determine chocolate versus compound labeling. West Midlands confectionery clusters are rotating into dark compound formulations as Sainsbury's and Waitrose procurement specifications harden around sustainable palm-free claims.
Scotland
Food Standards Scotland coordinates enforcement harmonization that creates formulation standardization opportunities across dairy-alternative dessert segments. DEFRA sustainability consultations on palm oil mandates are shepherding Scottish ice cream manufacturers toward shea stearin sourcing. Edinburgh-Glasgow manufacturing corridors are consolidating supply contracts around technical service capabilities rather than spot-price purchasing.
Wales
Health and Safety Executive allergen control protocols govern milk and soy lecithin handling in Welsh manufacturing facilities. Welsh specialty bakery formation is accelerating demand for pouch-format clean-label compounds. Cardiff-Newport industrial zones present underpenetrated white space for dark compound with certified sustainable palm-free positioning.
Northern Ireland
The Windsor Framework shapes cross-border supply chain configurations for compound chocolate moving between Northern Ireland and the Republic of Ireland. Belfast-area food manufacturers are navigating dual regulatory compliance under UK and retained EU chocolate regulations. Local procurement teams are consolidating supplier relationships around enzymatic interesterification capabilities for improved gloss retention.
UK Compound Chocolate Market Competitive Landscape
Integrated oilseed processors and specialized fat formulators split the market between commodity volume plays and margin-accretive technical service contracts. The vendor base concentrates around three strategic archetypes: multinational agribusiness conglomerates with captive supply chains, shea-specialist formulators with fractionation expertise, and regional confectionery ingredient distributors with embedded bakery relationships. Dominant competitive moves include backward integration into oilseed crushing assets and technology licensing agreements for enzymatic interesterification capabilities.
Within the integrated agribusiness tier, Cargill and Barry Callebaut exemplify scale-driven positions anchored by extensive technical service operations. AAK occupies a specialist position focused on shea-based fat solutions that differentiate from palm-centric competitors. These three entities represent the primary competitive anchors shaping procurement relationships with industrial bakery and ice cream manufacturing clients across British manufacturing corridors.
| Leading Market Players |
|---|
| Cargill |
| AAK |
| Fuji Oil Holdings Inc |
| Puratos |
| Barry Callebaut |
| Natra |
| Pecan Deluxe Candy Europe Ltd |
| Ingredients UK Ltd |
| Sephra |
| Others |
Value Network & Pricing Analysis
Greater Manchester's industrial baking corridor concentrates UK compound chocolate procurement leverage, with bulk container volumes from Cargill and Barry Callebaut creating pricing power asymmetries that favor multi-year contract holders over spot purchasers. The Food Standards Agency's retained EU labeling rules add compliance premiums that compound producers pass through to frozen dessert manufacturers demanding technical service bundling.
Pricing Analysis
Geographic price spreads between England's industrial corridors and Scottish ice cream manufacturing clusters reflect delivery cost differentials and DEFRA sustainability mandate readiness. Three-tier pricing structure across enzymatic interesterified premium grades, standard chemical interesterification mid-tiers, and commodity palm-based economy compounds dominates procurement negotiations. Price differentiation hinges on shea stearin certification grade and on-site fat bloom troubleshooting service inclusion. Pricing pressure stems from cocoa butter price volatility compressing compound-to-true-chocolate spreads during West African supply disruptions. Industrial bakeries in Greater Manchester exhibit highest price sensitivity, while West Midlands specialty snack producers absorbing palm-free certification premiums show lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Cargill's integrated oilseed processing network and Barry Callebaut's technical service operations anchoring UK capacity. Geographic supply concentration draws from West African shea nut processing, Malaysian and Indonesian palm kernel oil fractionation, and European enzymatic interesterification facilities. Raw material dependencies center on shea stearin, palm kernel olein, and coconut oil fractions. Supply chain risk concentrates in West African shea nut processing bottlenecks creating single-source vulnerability for AAK and similar shea-specialist formulators. Distribution runs through direct manufacturer relationships with industrial bakeries and ice cream producers, bypassing traditional distributor markups for bulk container volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
British bakery procurement consolidation around technical service capabilities is shifting buyer power toward Greater Manchester's frozen dessert manufacturers and West Midlands snack producers, fragmenting spot-price purchasing behavior.
For Market Incumbents: Harden enzymatic interesterification capabilities against shea supply concentration risks by securing multi-origin shea stearin offtake agreements with West African processors. Deepen backward integration into palm kernel oil fractionation assets to defend margin position against cocoa butter price volatility spikes. Anchor relationships with industrial bakery clients through embedded fat bloom troubleshooting teams that raise switching costs. For New Entrants and Emerging Players: Establish a beachhead in Welsh specialty bakery formation accelerating demand for pouch-format clean-label compounds with certified sustainable palm-free positioning. Target Cardiff-Newport industrial zones as underpenetrated white space where Sainsbury's and Waitrose procurement specifications are hardening fastest. Lead with shea-coconut fat blending expertise as a technical differentiation wedge against incumbent palm-centric portfolios. For Investors and Strategic Acquirers: Long-term, this sits as a formulation chemistry consolidation play because fat technologist scarcity is concentrating at Cargill and Barry Callebaut while mid-tier manufacturers lack access. Acquisition targets should screen for shea fractionation expertise and existing Food Standards Scotland enforcement relationships. Monitor DEFRA palm oil sustainability mandate compliance deadlines as the critical inflection signal for shea-dominated fat architecture adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Scale-Up | Barry Callebaut's technical service operations anchor industrial bakery relationships through gloss retention improvements. |
| Shea Supply Base Diversification | AAK's West African processing partnerships reduce palm kernel oil dependency ahead of DEFRA mandate deadlines. |
| Clean-Label Certification Investment | Palm-free claims unlock Sainsbury's and Waitrose listings for West Midlands dark compound producers. |
| Technical Service Team Embedding | On-site fat bloom troubleshooting raises switching costs for Greater Manchester frozen dessert manufacturers. |
| Regional Distribution Consolidation | Bulk container heated discharge systems lock in pipeline-fed industrial bakery procurement contracts. |
Research Methodology
Operator-level perspectives from bakery procurement directors, ice cream manufacturing technologists, fat formulation chemists at Cargill and Barry Callebaut, and Food Standards Agency enforcement officers anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation against BSI standards documentation, DEFRA sustainability consultation records, Health and Safety Executive allergen control protocols, and retained EU chocolate regulation filings. Customs data on vegetable fat imports and cocoa butter equivalent trade flows provided quantitative grounding. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing framed analytical approaches across the projection horizon, with baseline, accelerated clean-label adoption, and cocoa butter price spike scenarios bounding uncertainty ranges. Segmentation dimensions modeled included product chemistry tier, end-use application process requirements, packaging format automation compatibility, and distribution channel relationship intensity. CAGRs derived from trend extrapolation of bakery and ice cream manufacturing output, adjusted for compound chocolate penetration rates and reformulation timelines. Industry-specific forecast inputs incorporated DEFRA palm oil mandate compliance schedules and enzymatic interesterification technology diffusion curves.
Stress conditions across West African shea nut harvest variability, Malaysian palm kernel oil export policy shifts, and Food Standards Agency labeling enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on clean-label claim adoption velocity and industrial bakery consolidation trajectories. Quarterly review of DEFRA consultation progress, cocoa futures volatility indicators, and Sainsbury's procurement specification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
North America Gummy Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Caramel Market
Confectionery
Low Calorie Nutella Market
Confectionery
Italy Chocolate Market
Confectionery
Asia-Pacific Sugar Free Chewing Gum Market
Confectionery
Black Treacle Market
Confectionery
Macarons Market
Confectionery
Low-Calorie Candy Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
South Korea Chocolate Market
Confectionery
Carob Chocolate Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
United States Caramel Chocolate Market
Confectionery
India Industrial Chocolate Market
Confectionery
Vegan Chocolate Confectionery Market