
 Saudi Arabia Chocolate Market | 2026-2036
Saudi Arabia Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Chocolate Market Insights
SFDA nutritional labeling mandates for confectionery is pivoting Saudi chocolate makers toward cleaner ingredient decks. Mars Incorporated leverages its Gulf distribution infrastructure to sustain shelf dominance in hypermarket channels. Patchi LLC anchors the luxury gifting segment through controlled boutique networks in Riyadh and Jeddah. Ferrero International SA differentiates via hazelnut supply chain integration and premium positioning.
Chocolate comprises cocoa mass, cocoa butter, sugar, and emulsifiers formed through conching, tempering, and molding processes to achieve defined viscosity, snap, and fat bloom resistance for confectionery consumption. Milk Chocolate occupies the volume core due to palate familiarity across Saudi demographics, while Dark Chocolate captures margin expansion from health-conscious consumers seeking elevated cocoa solids. Specialty Shops command premium pricing through experiential retail, though Online Retail accelerates fastest among distribution channels as digital payment penetration deepens.
SFDA standards govern product safety, ingredient disclosure, and nutritional claims, while SASO technical regulations enforce packaging and import compliance for chocolate entering Saudi borders. The EU-Saudi trade framework indirectly shapes premium chocolate imports through CE-marked processing equipment standards. Stakeholders must monitor how VAT adjustments and localization incentives under Vision 2030 reshape import dependency versus domestic manufacturing scale.
Market Dynamics
SFDA nutritional labeling mandates are compressing formulation timelines across Saudi Arabia's chocolate sector, forcing manufacturers to revalidate ingredient decks while maintaining fat bloom stability and viscosity profiles.
Growth Catalysts
- Gifting Culture Formalization:Ramadan and Eid consumption cycles in Riyadh and Jeddah normalize premium chocolate as standardized hospitality currency, expanding per-capita spend.
- SFDA Ingredient Transparency Rules:Mandatory disclosure of cocoa origin percentages and emulsifier specifications is accelerating clean-label product line development.
- Western Province Retail Density:Jeddah's hypermarket corridor concentrates foot traffic and impulse purchase velocity for confectionery categories.
Market Restraints
- Cocoa Butter Price Volatility:West African supply disruptions transmit directly to Saudi manufacturing cost structures through import dependency.
- Single-Source Equipment Concentration:European conching and tempering machinery suppliers create procurement bottlenecks for capacity expansion.
- SASO Import Certification Friction:Extended laboratory testing timelines for novel ingredients delay product launch windows.
Strategic Opportunities
- Qassim and Eastern Province Underpenetration:Dammam and Al-Khobar retail corridors offer whitespace for boutique chocolate format entry.
- Vision 2030 Localization Incentives:Domestic manufacturing tax holidays and subsidized industrial land reduce import dependency ratios.
- Online-Dark Store Convergence:Quick-commerce platforms in Riyadh enable 30-minute delivery windows for impulse gifting occasions.
Industry Challenges
- Confectionery Technologist Scarcity:Specialized expertise in tempering curve optimization and fat polymorphism control remains concentrated in European training pipelines.
- Legacy ERP Integration:Batch traceability systems for SFDA compliance require retrofitting into existing manufacturing execution software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Chocolate Market |
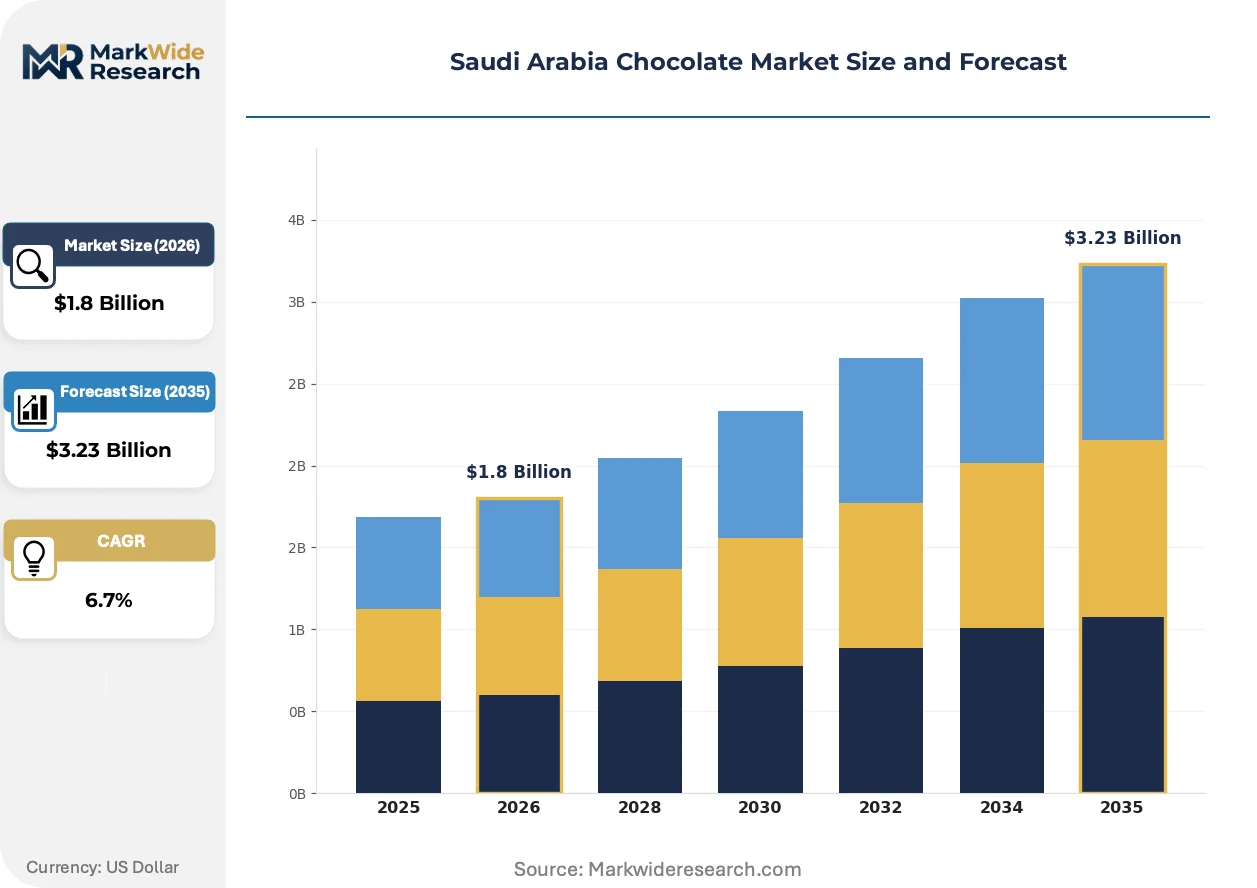
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Consumer Type: Adults, Children, Gift Buyers, Health-Conscious Consumers Packaging Type: Bags, Boxes, Bars, Flexible Packaging |
| Companies Covered | Ferrero International SA, Mars Incorporated, Nestlé SA, Mondelēz International Inc., Patchi LLC, The Hershey Company, Bateel International LLC, Barry Callebaut, Lindt & Sprüngli, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Chocolate Market Trends and Innovations
Digital payment infrastructure and regulatory disclosure requirements are compressing traditional retail cycles while elevating ingredient provenance as a competitive variable.
Precision conching technology is integrating real-time particle size monitoring and automated viscosity adjustment to reduce batch-to-batch variation. Mid-scale Saudi manufacturers are adopting these systems to meet SFDA consistency requirements without European technical staffing. This convergence is integrating quality control directly into production flow, collapsing separate laboratory validation steps.
SFDA's 2025 nutritional labeling amendments mandate front-of-pack calorie disclosure and added-sugar callouts for all confectionery. Chocolate makers must redesign packaging artwork and reformulate recipes to maintain palatability under reduced sugar thresholds. Dark chocolate segments with naturally lower sugar content absorb this compliance burden most favorably.
Gifting procurement is fragmenting from seasonal bulk purchases toward occasion-based micro-orders through mobile platforms. Quick-commerce channels in Riyadh and Jeddah are replacing traditional souk visits for last-minute hospitality needs. This behavioral pivot is most pronounced among dual-income households in Riyadh's northern districts.
Saudi Arabia Chocolate Market Segmentation
Segmentation in the Saudi chocolate sector reveals how formulation choices, channel strategies, and occasion-based purchasing fragment revenue concentration across distinct value pools. Understanding these divides helps manufacturers allocate R&D and distribution resources against shifting regulatory and behavioral pressures.
Product Type:
Cocoa butter concentration and solids percentage determine manufacturing cost structures and margin profiles across Saudi production facilities.
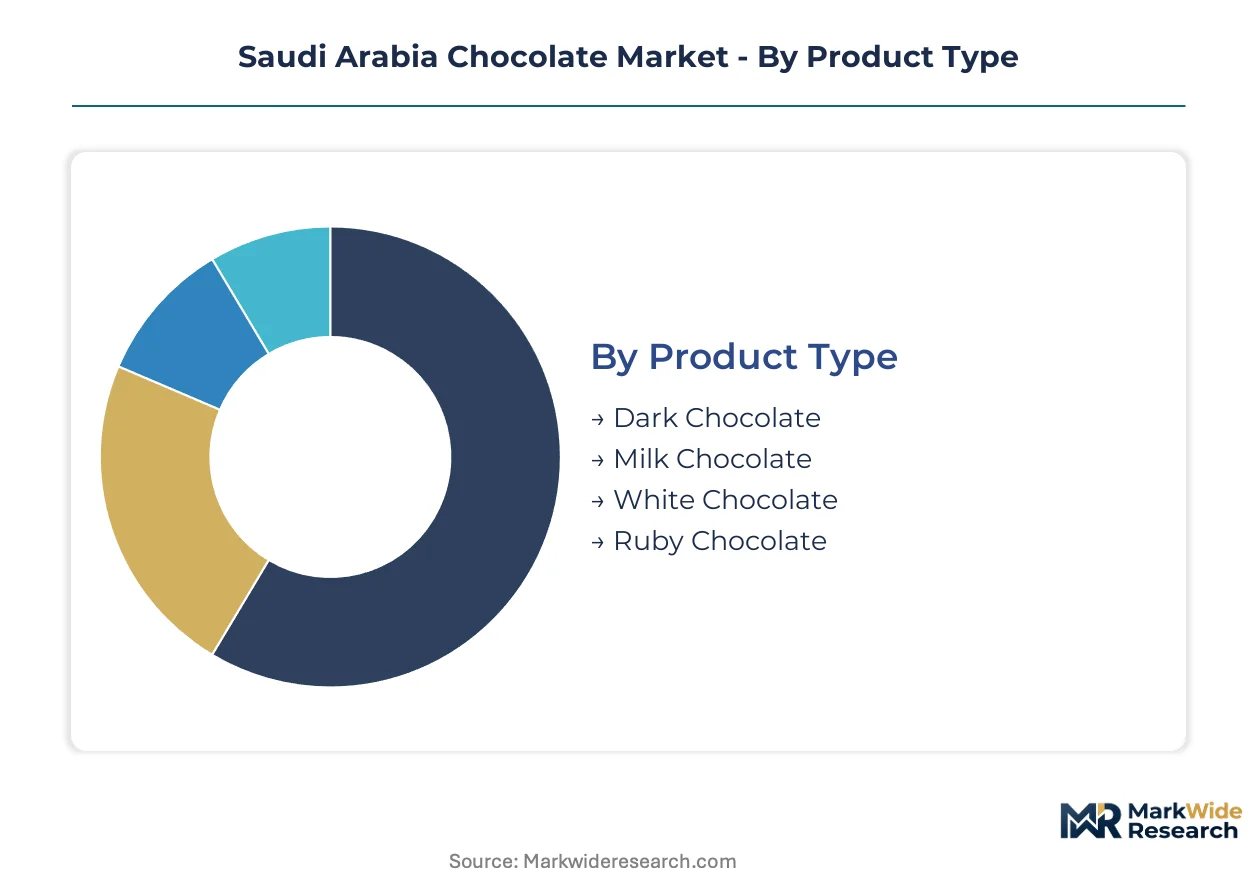
- Milk Chocolate:Combines cocoa solids with milk powder and higher sugar ratios to achieve the creamy texture preferred across Saudi demographics. Volume concentrates in Riyadh hypermarket channels where family bulk purchasing dominates Ramadan preparation cycles.
- Dark Chocolate:Elevated cocoa mass percentages (70% and above) deliver bitter flavor profiles aligned with health-conscious positioning. Demand clusters in Jeddah's Western Province retail corridor among affluent consumers responding to SFDA sugar disclosure mandates.
- White Chocolate:Cocoa butter base without cocoa solids, relying on milk solids and vanilla for flavor identity. Patchi and boutique manufacturers deploy this format for premium gifting assortments targeting Eid hospitality exchanges.
- Ruby Chocolate:Pink-hued variant from specific cocoa bean processing, offering berry notes without added flavoring. Limited production runs serve experimental product lines in Riyadh specialty retail as consumer education lags.
Milk chocolate absorbs the bulk of installed capacity; dark chocolate is expanding most quickly.
Distribution Channel:
Channel selection determines pricing power, inventory velocity, and exposure to SFDA labeling compliance costs.
- Supermarkets:Hypermarket chains in Jeddah and Riyadh anchor volume throughput with centralized procurement and promotional calendar coordination. Mars and Ferrero leverage existing Gulf distribution infrastructure to defend shelf positioning.
- Online Retail:Quick-commerce platforms enable 30-minute delivery windows for impulse gifting occasions. Digital payment penetration in Riyadh's northern districts accelerates this channel's expansion trajectory.
- Convenience Stores:Neighborhood formats capture grab-and-go consumption with smaller pack sizes. Limited refrigeration capacity constrains premium product placement.
- Specialty Shops:Controlled boutique networks in Riyadh and Jeddah command experiential retail premiums. Patchi's direct-to-consumer model avoids margin compression from third-party retail negotiations.
Supermarkets retain the dominant share of transaction volume; online retail is climbing the fastest.
Consumer Type:
Purchasing motivation—self-consumption versus social obligation—shapes product format and price point selection.
- Gift Buyers:Formalized Ramadan and Eid hospitality protocols standardize premium chocolate as obligatory exchange currency. Riyadh and Jeddah dual-income households drive per-capita spend elevation through boutique channel preference.
- Health-Conscious Consumers:Sugar reduction priorities and cocoa origin traceability demands concentrate in Jeddah's affluent districts. SFDA front-of-pack labeling mandates accelerate migration toward dark chocolate segments.
- Adults:Personal consumption spans daily indulgence and workplace hospitality contexts. Price sensitivity varies sharply by income bracket and urban density.
- Children:Palate familiarity with milk chocolate sweetness drives parental purchasing in family-oriented retail formats. School nutrition guidelines indirectly constrain marketing approaches.
Gift buyers command the highest per-transaction value; health-conscious consumers are gaining share fastest.
Packaging Type:
Format engineering balances shelf appeal, portion control, and logistics efficiency across Saudi distribution networks.
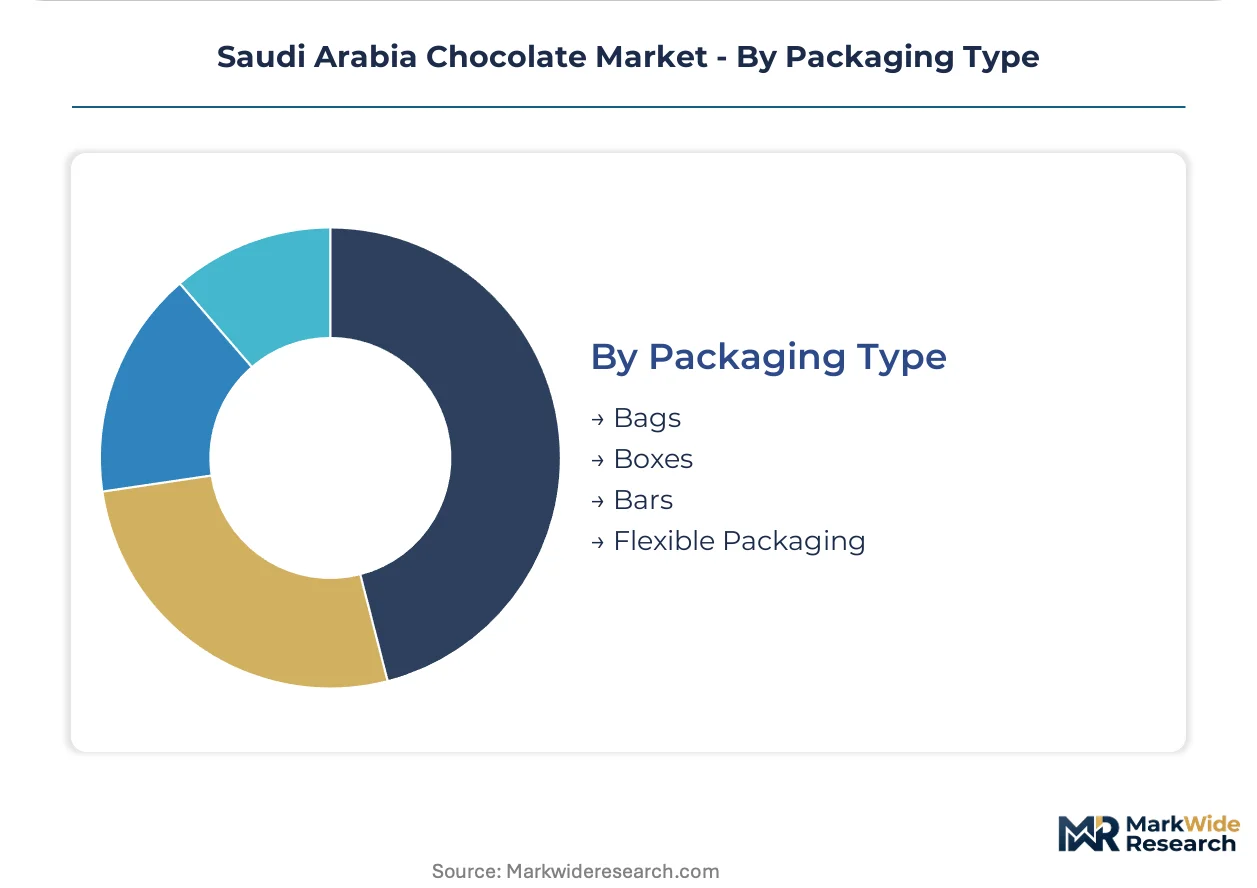
- Boxes:Rigid formats with partitioned inserts dominate premium gifting assortments. Structural integrity requirements for summer temperature exposure elevate corrugated and tin specifications.
- Bars:Standardized unit sizes optimize manufacturing line efficiency and retail planogram compliance. Single-origin and craft positioning differentiates through wrapper design and cocoa percentage callouts.
- Bags:Flexible pouches serve bite-sized sharing formats for hospitality trays. Resealability features address humidity concerns in coastal Jeddah storage conditions.
- Flexible Packaging:Flow-wrapped formats minimize material cost and shipping cube for mass-market distribution. Barrier properties against fat bloom and odor transmission determine supplier selection.
Boxes capture the premium revenue concentration; flexible packaging is scaling most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jeddah's retail corridor concentrates Saudi Arabia's chocolate demand through hypermarket chains and boutique networks serving Western Province affluence. Riyadh's northern districts anchor quick-commerce growth as digital payment penetration reshapes gifting procurement patterns. SFDA labeling mandates and Vision 2030 localization incentives are redistributing manufacturing investment across sub-regional industrial zones.
Riyadh
Dual-income households in Riyadh's northern districts drive premium gifting velocity through boutique channels and mobile ordering platforms. SFDA nutritional disclosure requirements accelerate clean-label product line development among domestic manufacturers. The KAFD and Diriyah Gate developments concentrate experiential retail investment for luxury chocolate positioning.
Eastern Province
Dammam and Al-Khobar retail corridors present whitespace opportunity for boutique format entry with underpenetrated premium positioning. Vision 2030 industrial zone incentives in Jubail attract domestic manufacturing investment to reduce import dependency. The Dammam-Riyadh logistics corridor enables distribution reach into central Saudi markets.
Western Province
Jeddah's hypermarket density and coastal affluence sustain volume leadership for milk chocolate family purchasing and dark chocolate health-positioned segments. SASO import certification requirements shape procurement timelines for European equipment and ingredient sourcing. The Jeddah Islamic Port facilitates cocoa butter and specialty ingredient throughput for regional manufacturing.
NEOM Northwest
The NEOM development zone targets food-tech manufacturing clusters including precision fermentation and alternative protein integration for confectionery applications. Regulatory sandbox provisions may accelerate novel ingredient approval pathways distinct from standard SFDA timelines. Trojena and Oxagon industrial planning includes specialty food production infrastructure.
Saudi Arabia Chocolate Market Competitive Landscape
The competitive structure tilts toward multinational conglomerates with Gulf distribution infrastructure defending shelf positioning against boutique specialists commanding experiential retail premiums. Mars Incorporated and Ferrero International SA anchor hypermarket throughput through existing logistics networks, while Patchi LLC occupies controlled boutique channels. Strategic moves concentrate on quick-commerce platform partnerships and domestic manufacturing localization under Vision 2030 tax incentives.
Among the multinational tier, Ferrero International SA and Mars Incorporated represent scale-driven archetypes leveraging regional distribution density. Patchi LLC exemplifies the controlled-boutique model with direct-to-consumer positioning in Riyadh and Jeddah. Nestlé SA and Mondelēz International Inc. occupy diversified portfolio positions spanning mass-market and premium segments. Lindt & Sprüngli and The Hershey Company anchor import-dependent premium positioning, while Bateel International LLC represents regional origin-based gifting specialization. Barry Callebaut occupies upstream supply chain positioning as industrial chocolate and ingredient supplier to Saudi manufacturers.
| Leading Market Players |
|---|
| Ferrero International SA |
| Mars Incorporated |
| Nestlé SA |
| Mondelēz International Inc. |
| Patchi LLC |
| The Hershey Company |
| Bateel International LLC |
| Barry Callebaut |
| Lindt & Sprüngli |
| Others |
Pricing and Supply Chain Analysis
ICCO cocoa futures price volatility cascades through Saudi Arabia's chocolate supply chain, compressing margins at import-dependent manufacturing tiers while amplifying premium pricing power for boutique producers with backward-integrated sourcing. This commodity-driven cost structure fragments the market into distinct value tiers anchored by ingredient provenance and distribution control.
Pricing Analysis
Value-based pricing anchored to cocoa origin certification and fat bloom stability outcomes stratifies Saudi chocolate tiers. Premium-mid-economy pricing differentiation separates Patchi's controlled-boutique positioning from Mars and Ferrero's hypermarket volume plays, with quality grade and brand heritage as primary drivers. Pricing pressure stems from West African cocoa butter supply disruptions transmitting directly to manufacturing cost structures. Family bulk purchasers in Riyadh hypermarkets exhibit highest price sensitivity; gift buyers in Jeddah boutiques demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-manufacturer channels from Côte d'Ivoire and Ghana handle raw cocoa bean procurement for Saudi processing facilities. Cocoa mass, cocoa butter, and milk powder feedstock dependencies draw from West African origins and European dairy suppliers. Single-source vulnerability concentrates in European conching and tempering machinery suppliers, creating procurement bottlenecks for capacity expansion. Distribution runs through Jeddah Islamic Port for ingredient throughput, with Riyadh and Jeddah retail corridors as downstream anchors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's chocolate market is consolidating around regulatory compliance capabilities and Gulf distribution infrastructure, with SFDA labeling mandates forcing sub-scale domestic manufacturers toward acquisition or exit.
For Market Incumbents: To counter quick-commerce platform disintermediation of traditional retail relationships, Mars and Ferrero should deepen controlled-boutique partnerships in Riyadh's northern districts while retrofitting batch traceability systems into legacy ERP infrastructure for SFDA compliance. Vertical integration into domestic manufacturing through Vision 2030 industrial zone incentives reduces import dependency exposure. For New Entrants and Emerging Players: Capture whitespace in Dammam and Al-Khobar retail corridors through experiential boutique formats targeting underpenetrated Eastern Province affluence. Specialty dark chocolate with elevated cocoa solids percentages offers the most penetrable segment given health-conscious consumer migration and SFDA sugar disclosure mandates. A direct-to-consumer mobile-first go-to-market angle bypasses hypermarket slotting fee barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale domestic manufacturers with existing SFDA compliance infrastructure and Jeddah or Riyadh distribution relationships. Long-term viability hinges on localization scale under Vision 2030 incentives rather than import-dependent models. The signal to watch is quick-commerce platform exclusivity agreements with boutique chocolate brands as channel control inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Localization | Vision 2030 tax holidays and subsidized industrial land in Jubail reduce cocoa import dependency ratios for Saudi producers. |
| Quick-Commerce Platform Partnership | Thirty-minute delivery windows through Riyadh digital platforms capture impulse gifting occasion fragmentation from traditional retail. |
| SFDA Compliance Infrastructure Investment | Front-of-pack calorie disclosure mandates force packaging artwork redesign and recipe reformulation for market access retention. |
| Backward Integration into Cocoa Sourcing | Direct West African supplier relationships bypass commodity futures volatility and secure origin-certified feedstock for premium positioning. |
| Experiential Boutique Network Expansion | Controlled retail formats in Jeddah and Riyadh command margin premiums unavailable through hypermarket third-party negotiations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across chocolate manufacturing executives, SFDA compliance officers, hypermarket category buyers, and quick-commerce platform operators. Secondary sources included SFDA nutritional labeling amendments, SASO technical regulations, EU-Saudi trade framework documentation, and Vision 2030 industrial incentive disclosures. Bottom-up production capacity modeling and top-down retail audit data triangulated volume estimates across the analysis window.
Segment-level granularity modeled product type, distribution channel, consumer motivation, and packaging format dimensions across the projection horizon, with regional splits at Western Province, Riyadh, Eastern Province, and NEOM sub-market levels. CAGRs derived from trend extrapolation against regulatory milestone timing and digital payment penetration curves. Cocoa butter price elasticity and conching equipment lead time assumptions fed manufacturing cost structure projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to West African supply disruptions, VAT adjustment timing, and Vision 2030 localization incentive continuity. Periodic stress-testing of base assumptions around cocoa futures volatility and quick-commerce platform market share trajectories is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Global Compound Chocolate Market
Confectionery
Sugar Free Mints Market
Confectionery
Africa Compound Chocolate Market
Confectionery
UK Chocolate Market
Confectionery
Caramel Market
Confectionery
US Confectionery Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
North America Marshmallow Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
UK Compound Chocolate Market
Confectionery
Carob Chocolate Market
Confectionery
Mooncake Market
Confectionery
China Chocolate Market
Confectionery
Ice Cream Coating Market