
 Asia-Pacific Sugar Free Chewing Gum Market | 2026-2036
Asia-Pacific Sugar Free Chewing Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sugar Free Chewing Gum Market Outlook
India's FSSAI mandatory sugar disclosure norms is pivoting the cost-of-entry calculus for new entrants, forcing upfront compliance investment in reformulation labs and label redesign. Mondelez International, Inc. leverages its established R&D footprint across Indian manufacturing zones to sustain portfolio transition speed. Lotte Corporation anchors its position through deep channel control in South Korean convenience retail. Perfetti Van Melle Group B.V. differentiates via specialized mint-flavored lines that dominate pharmacy-led distribution in Southeast Asian markets.
Sugar free chewing gum comprises elastomer bases, polyol sweeteners such as xylitol or sorbitol, softeners, and flavoring agents, manufactured through sequential mixing, rolling, and coating processes to deliver sustained flavor release and dental benefits including plaque reduction. The product serves commercial purposes spanning oral hygiene adjuncts, nicotine cessation support, and functional breath-freshening applications across consumer and professional settings. Mint flavored products occupy the largest volume share due to established therapeutic positioning, while online retail channels represent the fastest-growing distribution pathway as direct-to-consumer subscription models expand across Australian and Japanese markets. Blister packs command premium shelf positioning in drugstore channels where unit-dose hygiene claims resonate with adult buyers.
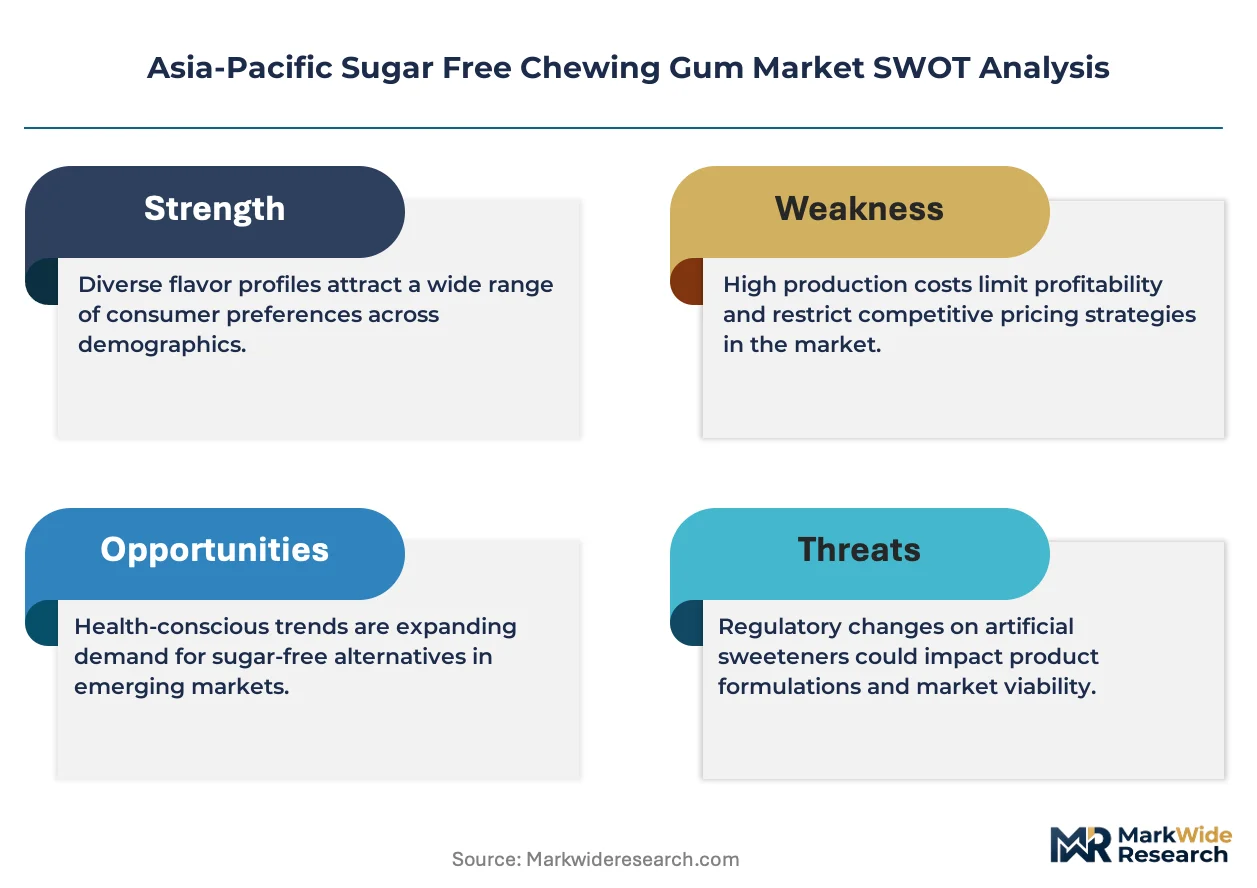
Japan's PMDA oversees functional food claims including gum-based oral health assertions, while Australia's TGA monitors therapeutic goods classifications affecting nicotine-replacement gums. China's SAMR enforces GB standards on food additive thresholds that constrain polyol sourcing strategies for regional producers. India's FSSAI front-of-pack labeling rules reshape retail merchandising priorities. Stakeholders must monitor evolving classification boundaries between confectionery and therapeutic products as regulators tighten evidentiary requirements for health-positioned formulations.
Market Dynamics
India's FSSAI front-of-pack sugar disclosure mandates are forcing rapid reformulation across domestic portfolios, compressing product development cycles and elevating compliance costs for entrants lacking established R&D infrastructure.
Growth Catalysts
- Oral health positioning:Rising plaque-reduction claims in pharmacy channels across Japan and South Korea are expanding the functional gum category beyond breath-freshening into preventive dental care adjuncts.
- FSSAI labeling mandates:India's mandatory sugar disclosure rules are accelerating consumer migration toward sugar-free alternatives in modern trade formats.
- Xylitol sourcing:Corn-based polyol supply clusters in China's Shandong province are reducing input costs for regional manufacturers serving Southeast Asian export markets.
Market Restraints
- Polyol price volatility:Sorbitol and xylitol costs fluctuate with corn and birch bark supply conditions, squeezing margin stability for mid-tier producers.
- Base polymer concentration:Synthetic elastomer supply for gum bases concentrates among a limited set of Southeast Asian petrochemical processors, creating single-source vulnerability.
- PMDA evidentiary thresholds:Japan's functional food claim requirements demand clinical substantiation that smaller regional brands cannot fund, blocking market access.
Strategic Opportunities
- Tier-two Chinese cities:Premium functional gums remain underdistributed in Chengdu, Hangzhou, and Wuhan relative to saturation in Beijing and Shanghai.
- Nicotine cessation applications:Australia's TGA therapeutic goods pathway offers regulatory precedent for positioning sugar-free gum as smoking-cessation support across Asia-Pacific markets.
- Subscription direct-to-consumer:Japanese and Australian consumers are adopting auto-replenishment models for functional oral care products, bypassing traditional convenience retail markups.
Industry Challenges
- Reformulation talent scarcity:Food technologists with polyol sweetener stability expertise command premium compensation in India's competitive hiring environment.
- SAMR additive compliance:China's GB standards on food additive thresholds require batch-level testing documentation that extends product registration timelines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sugar Free Chewing Gum Market |
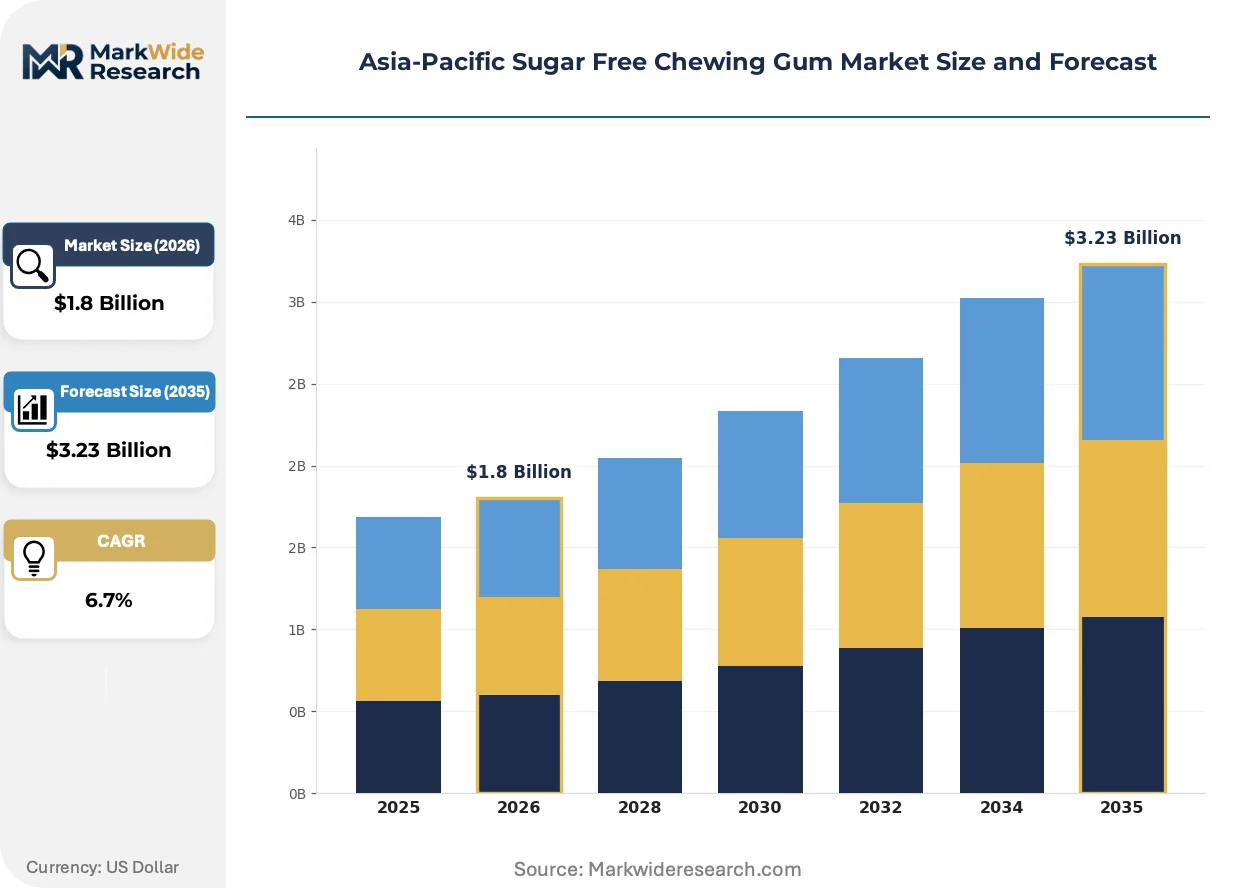
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bubble Gum, Mint Flavored, Fruit Flavored, Herbal Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Drugstores Customer Type: Children, Teenagers, Adults, Seniors Packaging Type: Stick Packs, Bottles, Blister Packs, Boxes |
| Companies Covered | Perfetti Van Melle Group B.V., Mondelez International, Inc., Mars, Incorporated, The Hershey Company, Lotte Corporation, Mars Wrigley, Wrigley Confectionery (China) Ltd, Perfetti Van Melle, Glee Gum, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sugar Free Chewing Gum Market Strategic Shifts
Microencapsulation technologies and sustained-release flavor systems are redefining product differentiation in functional chewing gum, while regulatory classification debates between confectionery and therapeutic categories reshape competitive boundaries.
Microencapsulation of active ingredients is integrating layered polymer coatings that protect heat-sensitive compounds through manufacturing while enabling staged release during chewing. Japanese pharmaceutical-grade gum manufacturers are adopting these systems for probiotic and vitamin delivery formats. The technology is integrating oral care positioning with broader wellness applications, compressing the boundary between confectionery and supplement categories.
PMDA's evolving guidance on functional food claims is tightening evidentiary requirements for plaque-reduction and caries-prevention assertions in gum-based products. Manufacturers must now submit clinical trial data rather than in-vitro studies to support therapeutic positioning. Japanese and South Korean brands with existing pharmaceutical partnerships are accelerating dossier preparation while smaller confectionery-focused competitors retreat to generic breath-freshening claims.
Urban Chinese consumers are migrating from impulse convenience purchases toward planned subscription acquisition for premium functional oral care products. Direct-to-consumer platforms in Shanghai and Shenzhen are displacing traditional hypermarket distribution for specialized mint and herbal formulations. This pattern is most visible among young professionals in tier-one cities who prioritize unit-dose hygiene packaging over bulk economy formats.
Asia-Pacific Sugar Free Chewing Gum Market Segmentation
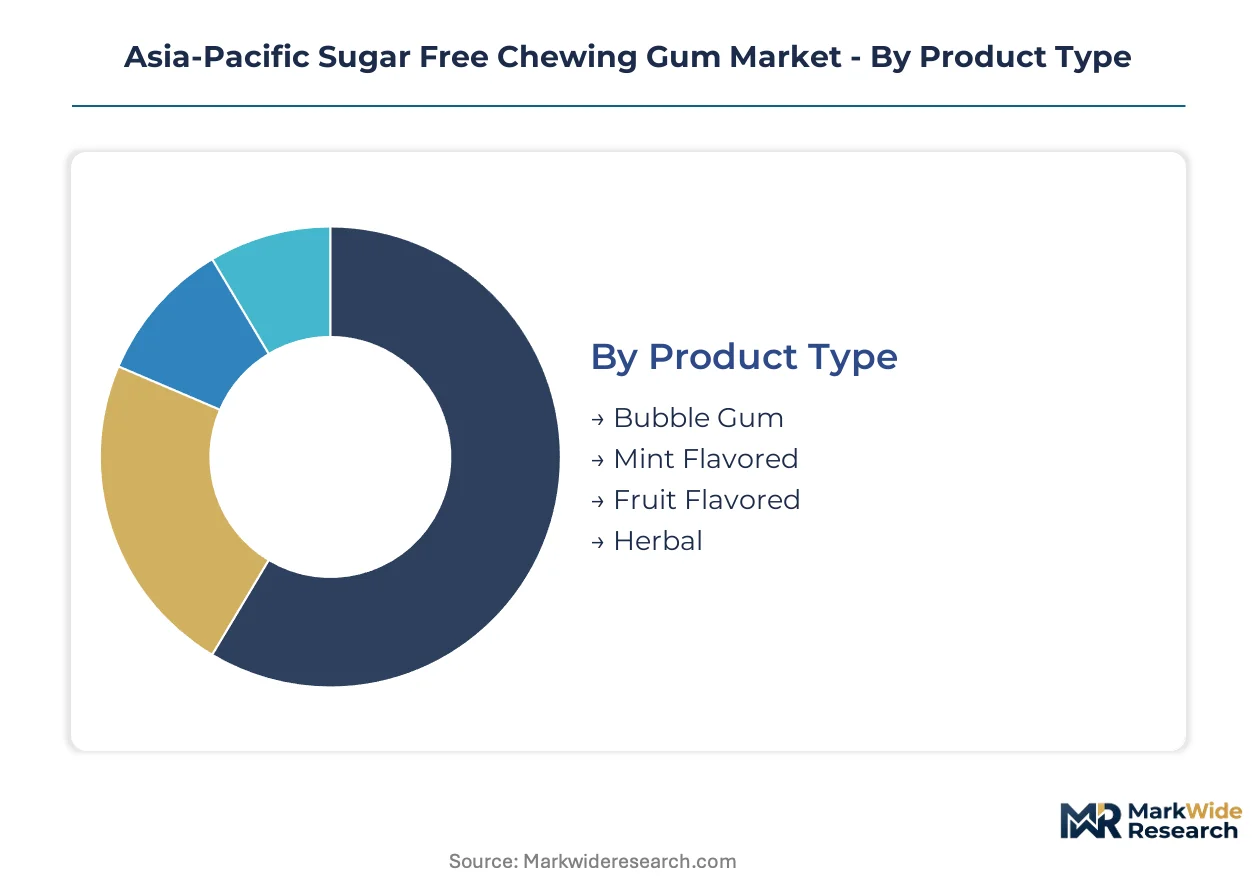
Asia-Pacific sugar free chewing gum segmentation reveals divergent margin profiles across functional positioning and channel economics. Product type and packaging format drive the widest price spreads, while distribution channel selection determines regulatory exposure and working capital intensity.
Product Type:
Flavor positioning determines whether brands compete on impulse refreshment or therapeutic credibility, with formulation complexity and claim substantiation requirements widening the R&D investment gap between segments.
- Mint Flavored:Xylitol-dominant formulations with menthol derivatives deliver sustained cooling and plaque-reduction positioning. Pharmacy channels in Japan and South Korea stock these as oral hygiene adjuncts, with PMDA functional food claim pathways requiring clinical dossiers that favor established pharmaceutical partnerships.
- Bubble Gum:High-elasticity gum bases with sorbitol sweetening target children and teenagers through novelty positioning. India's FSSAI sugar disclosure mandates are compressing this segment's traditional sugar-heavy formulations, forcing rapid reformulation toward polyol alternatives.
- Fruit Flavored:Citric acid-buffered systems with berry and citrus profiles appeal to younger adults seeking variety beyond therapeutic positioning. Convenience stores in Thailand and Indonesia move volume here through impulse placement near checkout counters.
- Herbal:Botanical extracts including green tea polyphenols and licorice root target wellness-positioned consumers in Chinese tier-one cities. SAMR's evolving supplement-confectionery boundary creates classification uncertainty that delays product registration.
Volume sits with mint formulations; growth tilts toward herbal variants as wellness positioning gains shelf space in Shanghai and Shenzhen premium channels.
Distribution Channel:
Channel selection dictates margin capture versus volume velocity, with regulatory classification requirements fragmenting operational models across pharmacy, grocery, and direct-to-consumer pathways.
- Drugstores:Unit-dose blister packs with therapeutic claims command premium positioning. Japan's PMDA and Australia's TGA oversight creates compliance moats that filter out confectionery-only competitors, concentrating margin with pharmaceutical-affiliated brands.
- Online Retail:Subscription auto-replenishment models bypass traditional retail markups in Australian and Japanese urban markets. Direct-to-consumer platforms capture customer data that enables personalized flavor rotation and loyalty program economics.
- Convenience Stores:Impulse-driven stick pack formats dominate South Korean CU and 7-Eleven networks, where Lotte's channel control secures prime shelf positioning. High turnover velocity compensates for compressed per-unit margins.
- Supermarkets:Family-size bottle formats in China's RT-Mart and India's Big Bazaar emphasize economy positioning. FSSAI front-of-pack labeling rules are reshaping merchandising priorities toward sugar-free alternatives in modern trade formats.
Supermarkets still move the bulk of tonnage; online retail is climbing the fastest as subscription mechanics displace convenience store dependence among young professionals.
Customer Type:
Age-based targeting determines formulation intensity, with adults driving functional claim investment while teenagers and children segments face tightening regulatory scrutiny on sweetener profiles and marketing practices.
- Adults:Workplace breath-freshening and oral hygiene maintenance drive planned purchase behavior. China's tier-one cities concentrate demand for premium functional gums with probiotic and vitamin delivery claims.
- Teenagers:Social consumption occasions and flavor experimentation dominate, with bubble and fruit variants preferred. India's FSSAI sugar disclosure norms are accelerating migration toward sugar-free alternatives in this price-sensitive cohort.
- Children:Parental gatekeeping around dental health limits market access, with xylitol positioning required to secure purchase approval. Formulation constraints on choking hazards and sweetener types narrow product development flexibility.
- Seniors:Dry mouth alleviation and denture-compatible textures represent emerging positioning opportunities. Japan's aging demographic concentrates demand in pharmacy channels where PMDA-regulated functional claims carry credibility weight.
Adults anchor current revenue; seniors offer the steepest expansion trajectory as aging demographics across Japan and South Korea enlarge the addressable base.
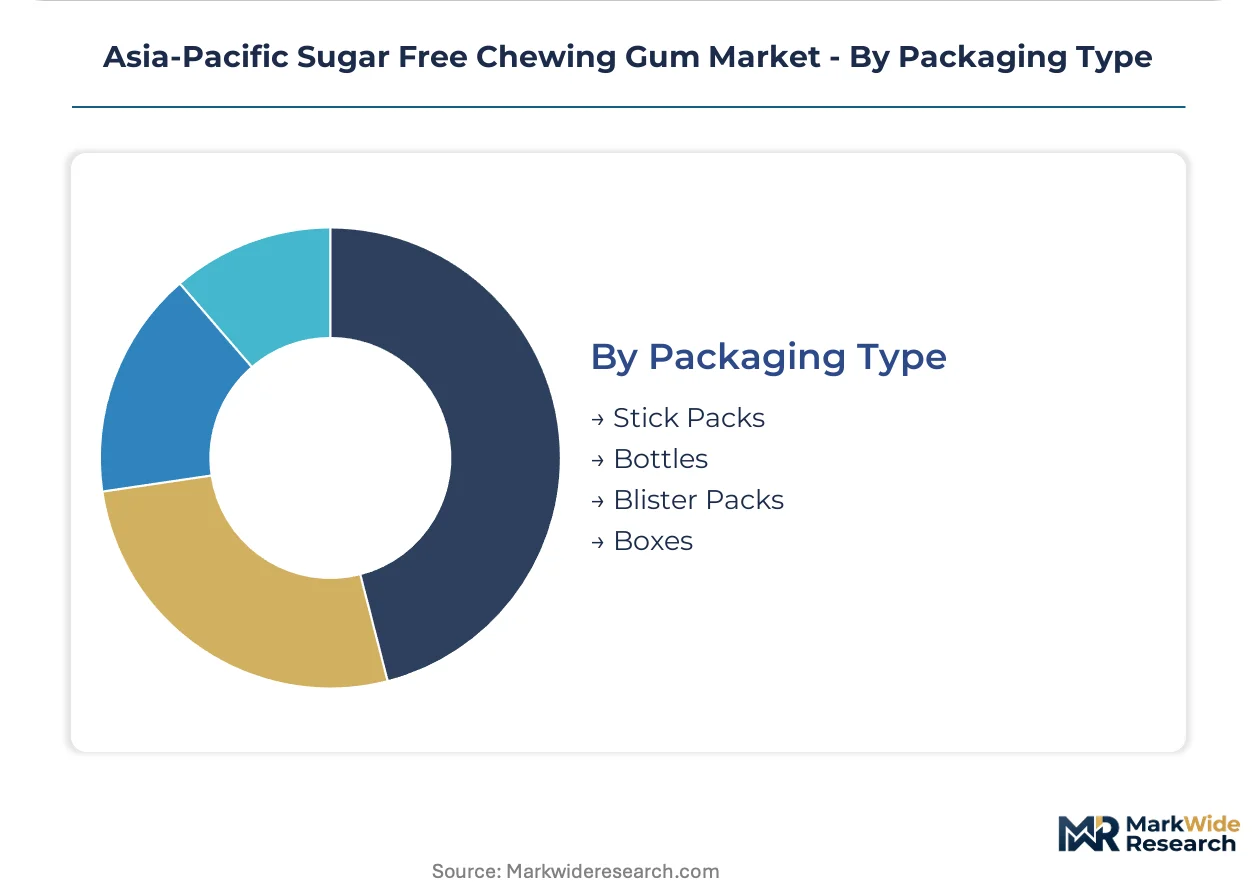
Packaging Type:
Format economics determine shelf life, portability, and premium extraction capability, with single-serve hygiene positioning commanding price multiples over bulk economy formats.
- Blister Packs:Individually sealed unit-dose formats with tamper-evident features dominate pharmacy channels. Australia's TGA therapeutic goods classification pathway favors this format for nicotine-replacement and oral care positioning.
- Stick Packs:Paper-foil laminate wraps enable impulse purchase economics at low price points. Convenience store distribution across South Korea and Thailand depends on this format's checkout-counter compatibility.
- Bottles:Multi-serve PET containers with desiccant inserts target family and office pantry replenishment. China's RT-Mart and India's Big Bazaar hypermarkets emphasize economy positioning through volume formats.
- Boxes:Rigid paperboard with window displays supports gift and premium positioning in Japanese department stores. Higher per-unit packaging costs require margin structures that limit distribution to affluent urban corridors.
Bottles capture the greatest shipment volume; blister packs are gaining share fastest as hygiene-conscious consumers in Australian and Japanese markets prioritize unit-dose assurance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shandong Free Trade Zone concentrates corn-based polyol processing infrastructure that supplies xylitol feedstock across the region. This cluster anchors regional supply chains while tier-one city demand pulls premium functional formulations northward.
China
Shanghai and Shenzhen consumers drive subscription adoption for probiotic gum formats. SAMR enforces GB standards on food additive thresholds that constrain polyol sourcing flexibility. Manufacturing concentrates in Shandong province where corn-derived xylitol production serves Southeast Asian export markets.
Japan
Tokyo's aging demographic expands pharmacy-channel demand for dry-mouth alleviating formulations. PMDA functional food claim requirements demand clinical dossiers that filter out smaller competitors. Kanto region pharmaceutical-grade manufacturers deploy microencapsulation for vitamin delivery applications.
India
Mumbai and Delhi modern trade formats accelerate sugar-free migration under FSSAI front-of-pack labeling mandates. FSSAI disclosure rules compress product development cycles for domestic portfolios. Maharashtra-based reformulation labs command premium talent compensation as compliance deadlines tighten.
South Korea
Seoul convenience retail networks sustain high-velocity impulse purchasing for breath-freshening formats. MFDS alignment with functional food standards supports pharmacy-channel therapeutic positioning. Busan-Ulsan petrochemical corridors supply synthetic elastomer bases to regional gum manufacturers.
Australia
Sydney and Melbourne professionals adopt auto-replenishment models for nicotine-cessation gum formats. TGA therapeutic goods classification creates compliance moats favoring pharmaceutical-affiliated brands. Direct-to-consumer platforms bypass traditional retail markups through customer data capture.
Asia-Pacific Sugar Free Chewing Gum Market Competitive Environment
Japanese and South Korean producers anchor one tier; European-headquartered multinationals and domestic Chinese specialists hold differentiated positions. The market structure fragments across pharmaceutical-affiliated functional players, confectionery-scale manufacturers, and regional niche formulators. Three archetypes dominate: clinical-dossier holders with PMDA partnerships, convenience-channel controllers with deep retail integration, and wellness-positioned entrants with herbal formulation specialization. Competitive moves concentrate on portfolio reformulation speed under tightening labeling regimes and subscription platform development to capture direct consumer relationships.
Among multinational confectionery conglomerates, Mondelez International, Inc. and Perfetti Van Melle Group B.V. represent the scale-driven tier with established R&D footprints across Indian manufacturing zones and Southeast Asian pharmacy distribution respectively. Lotte Corporation anchors the convenience-channel archetype through its position in South Korean retail networks. These three entities exemplify divergent strategic postures: reformulation agility under FSSAI pressure, specialized mint-flavored therapeutic positioning, and deep point-of-sale control in high-velocity urban formats.
| Leading Market Players |
|---|
| Perfetti Van Melle Group B.V. |
| Mondelez International, Inc. |
| Mars, Incorporated |
| The Hershey Company |
| Lotte Corporation |
| Mars Wrigley |
| Wrigley Confectionery (China) Ltd |
| Perfetti Van Melle |
| Glee Gum |
| Others |
Value Chain & Pricing Dynamics
Microencapsulation technology adoption in Japanese pharmaceutical-grade manufacturing is compressing unit economics while concentrating production capability among PMDA-certified facilities. This dual effect elevates cost barriers for reformulation-heavy entrants and tightens premium extraction for clinical-dossier holders in pharmacy channels across Tokyo and Osaka.
Pricing Analysis
Short lead-time premiums dominate contract structures, with blister-pack unit-dose formats commanding price multiples over bulk bottle formats in Australian TGA-regulated pharmacy channels. Three-tier pricing structure across premium functional, standard breath-freshening, and economy impulse tiers separates PMDA-affiliated brands from confectionery-scale competitors. Pricing pressure stems from FSSAI compliance investment in Indian reformulation labs, compressing margins for domestic portfolios lacking established R&D infrastructure. Teenage consumers in India's modern trade formats exhibit highest price sensitivity, while aging professionals in Japan's pharmacy channels demonstrate lowest elasticity for dry-mouth alleviating formulations.
Supply Chain Analysis
PMDA and TGA certification gating filters supplier qualification, limiting elastomer base sourcing to Southeast Asian petrochemical processors with documented batch-level testing protocols. China's Shandong province, South Korea's Busan-Ulsan corridor, and Thailand's industrial zones anchor regional polyol and gum base manufacturing. Corn-derived xylitol from Shandong and synthetic elastomers from Korean petrochemical complexes constitute critical input dependencies. Single-source vulnerability concentrates in Southeast Asian elastomer processing, where limited qualified suppliers create chokepoint exposure. Distribution runs through convenience retail networks in Seoul, pharmacy chains in Tokyo, and direct-to-consumer platforms in Sydney and Melbourne.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as FSSAI labeling mandates and PMDA evidentiary thresholds force smaller confectionery-focused competitors toward generic positioning, eliminating players lacking pharmaceutical partnerships or reformulation infrastructure.
For Market Incumbents: Anchor portfolio transition speed through captive reformulation labs in Maharashtra and Tamil Nadu manufacturing zones. Deepen channel control in South Korean convenience retail to defend against subscription-model displacement. PMDA clinical dossier investment serves as the primary moat against emerging wellness-positioned entrants with herbal specialization. For New Entrants and Emerging Players: Seniors in Japan's aging demographic represent the most underserved buyer archetype with dry-mouth alleviating and denture-compatible texture demands unmet by current breath-freshening portfolios. Tier-two Chinese cities including Chengdu and Wuhan offer underdistributed premium functional gum white space relative to Beijing saturation. Direct-to-consumer subscription platforms in Australian urban markets provide the most penetrable go-to-market angle bypassing traditional retail markups. For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-affiliated functional players with existing PMDA partnerships and clinical dossier libraries. Long-term viability across the analysis window favors entities with backward integration into Shandong polyol sourcing or Busan elastomer supply. Acquisition targets should demonstrate reformulation agility under tightening labeling regimes. The signal to watch is FSSAI enforcement acceleration compressing domestic portfolio transition timelines beyond smaller competitors' capital deployment capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Lab Investment | FSSAI compliance deadlines in India compress product development cycles for domestic portfolios lacking R&D infrastructure. |
| PMDA Clinical Dossier Preparation | Functional food claim substantiation filters out confectionery-only competitors in Japanese pharmacy channels. |
| Direct-to-Consumer Platform Launch | Subscription auto-replenishment in Sydney and Melbourne captures customer data enabling personalized flavor rotation. |
| Herbal Formulation Specialization | Green tea polyphenol and licorice root positioning targets wellness consumers in Shanghai and Shenzhen premium channels. |
| Channel Control Deepening | Prime shelf positioning in South Korean CU and 7-Eleven networks sustains high-velocity impulse purchasing economics. |
Study Parameters
Document review covered FSSAI regulatory filings, PMDA functional food guidance updates, and SAMR GB standard amendments, complemented by interviews with brand managers at multinational confectionery conglomerates, category buyers at Indian modern trade retailers, pharmacy procurement leads in Tokyo, and supply planners at Shandong polyol processors. Secondary validation drew from customs trade data on xylitol and sorbitol flows, retail audit data from Australian and Japanese direct-to-consumer platforms, and SEC filings of listed parent entities. Bottom-up segment sizing triangulated against top-down market aggregation.
Cross-referencing historical volume trajectories with expert panel input on regulatory enforcement timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include flavor positioning, distribution channel, customer age cohort, and packaging format. CAGRs derived from regression analysis of premium functional versus economy impulse tier growth differentials, incorporating polyol price volatility assumptions and subscription adoption curves in Australian and Japanese urban markets.
Revisions become necessary when FSSAI enforcement acceleration, PMDA evidentiary threshold tightening, or SAMR supplement-confectionery boundary reclassification materializes beyond current regulatory guidance. Forecasts reflect assumptions on labeling mandate compliance costs and clinical trial funding accessibility for therapeutic claim substantiation. A model refresh is warranted upon material change in corn and birch bark supply conditions affecting polyol input economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Chocolate Spread Market
Confectionery
Sugar-Free Gummy Market
Confectionery
Low Calorie Hard Candy Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Truffle Chocolate Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Europe Confectionery Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
Crunchy Chocolate Market
Confectionery
Cocoa and Chocolate Market
Confectionery
North America Gummy Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
North America Premium Chocolate Market
Confectionery
Gum Base Candy Market