
 Truffle Chocolate Market | 2026-2036
Truffle Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Truffle Chocolate Market Outlook
Subscription-based chocolate curation and replenishment services is realigning how truffle brands build recurring revenue beyond seasonal peaks. Lindt & Sprüngli leverages its direct-to-consumer platform to sustain year-round engagement with premium subscribers. Ferrero anchors its European manufacturing base while competing aggressively in North American truffle assortments through retail partnerships. Godiva Chocolatier extends its physical boutique network to control the experiential purchase moment in airports and luxury malls.
Truffle chocolate denotes a ganache-centered confection with a soft, creamy interior enrobed in a tempered chocolate shell, typically containing 30-40% cocoa butter and requiring controlled tempering at 31-32°C to achieve snap and gloss. The product serves both indulgent self-treat and premium gift occasions across retail and foodservice channels. Dark Truffles command the highest margin pool as health-positioned consumers accept elevated price points for elevated cocoa content and reduced sugar positioning. Milk Truffles still dominate absolute volume through mass retail distribution, though growth is decelerating relative to flavor-differentiated alternatives. Raspberry and Sea Salt flavor profiles are capturing the fastest expansion as experiential taste exploration displaces conventional single-note offerings.
FDA food labeling requirements and the EU's EUDR traceability mandates are reshaping how manufacturers document cocoa origin and allergen cross-contamination protocols across multi-country supply chains. BIS standards in India and FSSAI ingredient disclosure rules are opening formal retail channels for imported truffle brands while constraining local formulation flexibility. Stakeholders must monitor how evolving deforestation-linked supply chain audits intersect with consumer-facing clean-label expectations to determine where compliance investment converts to pricing power versus margin erosion.
Market Dynamics
The EU's deforestation regulation (EUDR) is forcing manufacturers to rebuild cocoa traceability infrastructure from farm to finished product, reshaping procurement relationships and compliance costs across the entire value chain.
Growth Catalysts
- Corporate premium gifting:Belgian and Swiss heritage confectionery traditions sustain elevated willingness-to-pay among institutional buyers seeking differentiated gift formats.
- EUDR traceability mandates:The EU's regulatory framework accelerates investment in verified supply chains, creating competitive separation for compliant operators.
- Dark chocolate health positioning:Cocoa butter concentration above 30% and reduced sugar formulations attract functional food consumers into premium tiers.
Market Restraints
- Cocoa butter input volatility:Price swings in cocoa butter, comprising 30-40% of truffle mass, compress margin predictability for mid-tier producers.
- West African supply concentration:Dependence on Côte d'Ivoire and Ghana origins creates deforestation-linked regulatory exposure under EUDR audit protocols.
- Tempering equipment capex:Precision temperature control at 31-32°C demands specialized capital investment that blocks artisanal scale-up.
Strategic Opportunities
- Subscription curation services:Direct-to-consumer replenishment models bypass seasonal demand peaks and build recurring revenue streams.
- India formal retail opening:BIS standards and FSSAI disclosure rules create compliant pathways for imported truffle brands into organized distribution.
- Experiential flavor profiles:Raspberry and sea salt variants capture taste-exploration demand displacing conventional single-note offerings.
Industry Challenges
- Cross-contamination protocol complexity:Allergen documentation across multi-country supply chains strains quality assurance staffing and system integration.
- Tempering skill scarcity:Controlled shell formation requiring precise snap and gloss specifications limits production throughput expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truffle Chocolate Market |
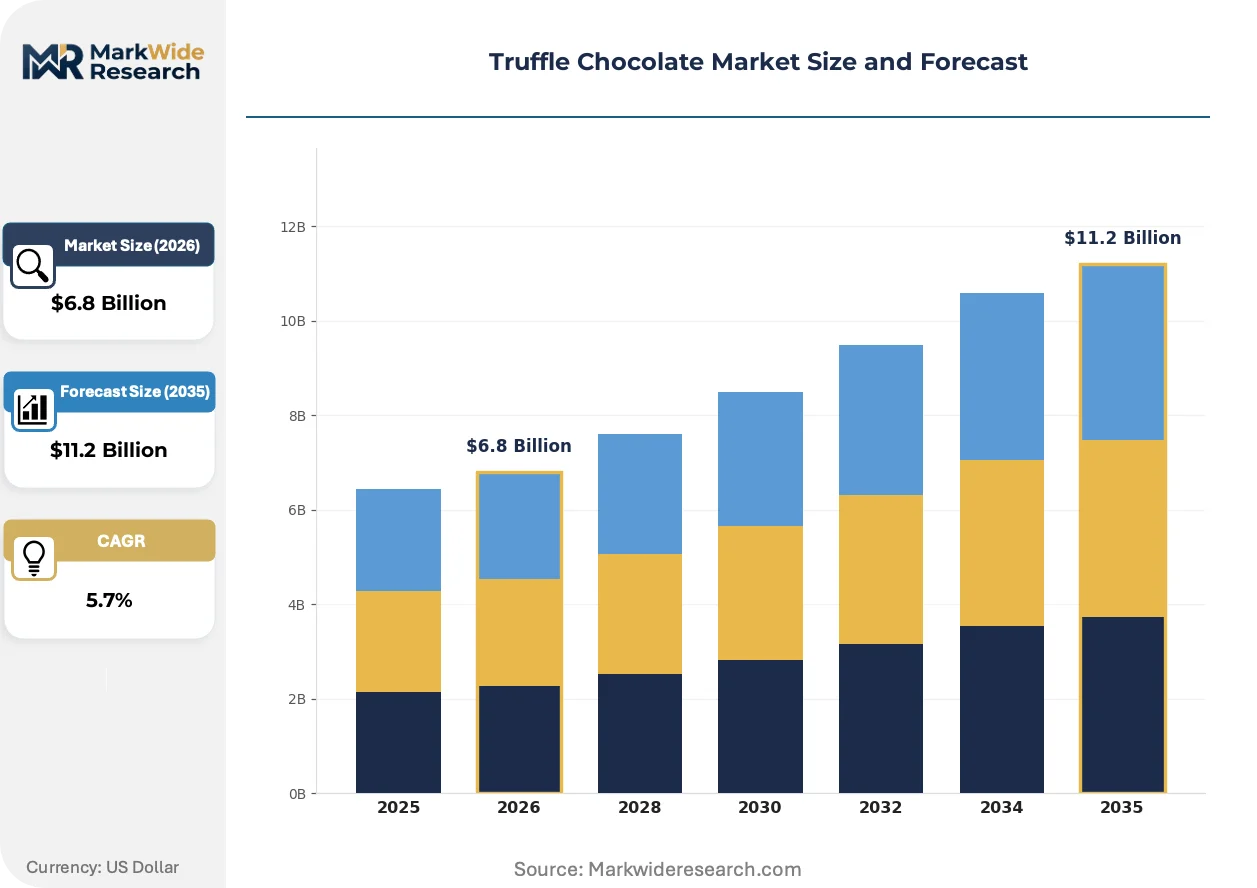
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Truffles, Milk Truffles, White Truffles, Sugar-Free Truffles Packaging Type: Boxed, Bagged, Bulk, Individual Wrappers End User: Retail Consumers, Restaurants, Cafés, Gift Shops Flavor Profile: Hazelnut, Raspberry, Sea Salt, Coffee |
| Companies Covered | Lindt & Sprüngli, Ferrero, Mondelez International, Nestlé, Mars, The Hershey Company, Godiva Chocolatier, Ghirardelli Chocolate Company, Neuhaus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truffle Chocolate Market Strategic Shifts
Confectionery production is fragmenting into specialized capability layers as brands seek flexibility without capital intensity, while regulatory and consumer pressures simultaneously demand more transparency and more personalization.
Precision tempering automation is modularizing small-batch production. Artisanal manufacturers in Belgium and Switzerland are adopting plug-and-play temperature control units that replicate master chocolatier consistency without dedicated line investment. This technology is modularizing entry barriers, enabling regional specialists to compete against integrated mass producers on quality parity.
REACH chemical safety protocols and EUDR deforestation audits are converging into unified supply chain documentation requirements. European manufacturers must now map cocoa origin through geolocation verification and chemical residue testing simultaneously. Dark truffle segments face the steepest compliance burden due to higher cocoa mass content and associated traceability depth.
Airport and luxury mall boutique expansion is capturing experiential purchase moments away from traditional retail. Godiva's physical network strategy exemplifies how controlled environment selling justifies price premiums through service and presentation. This channel rotation is most visible in Asia-Pacific transit hubs where duty-free confectionery serves dual indulgence and gifting functions.
Truffle Chocolate Market Segmentation
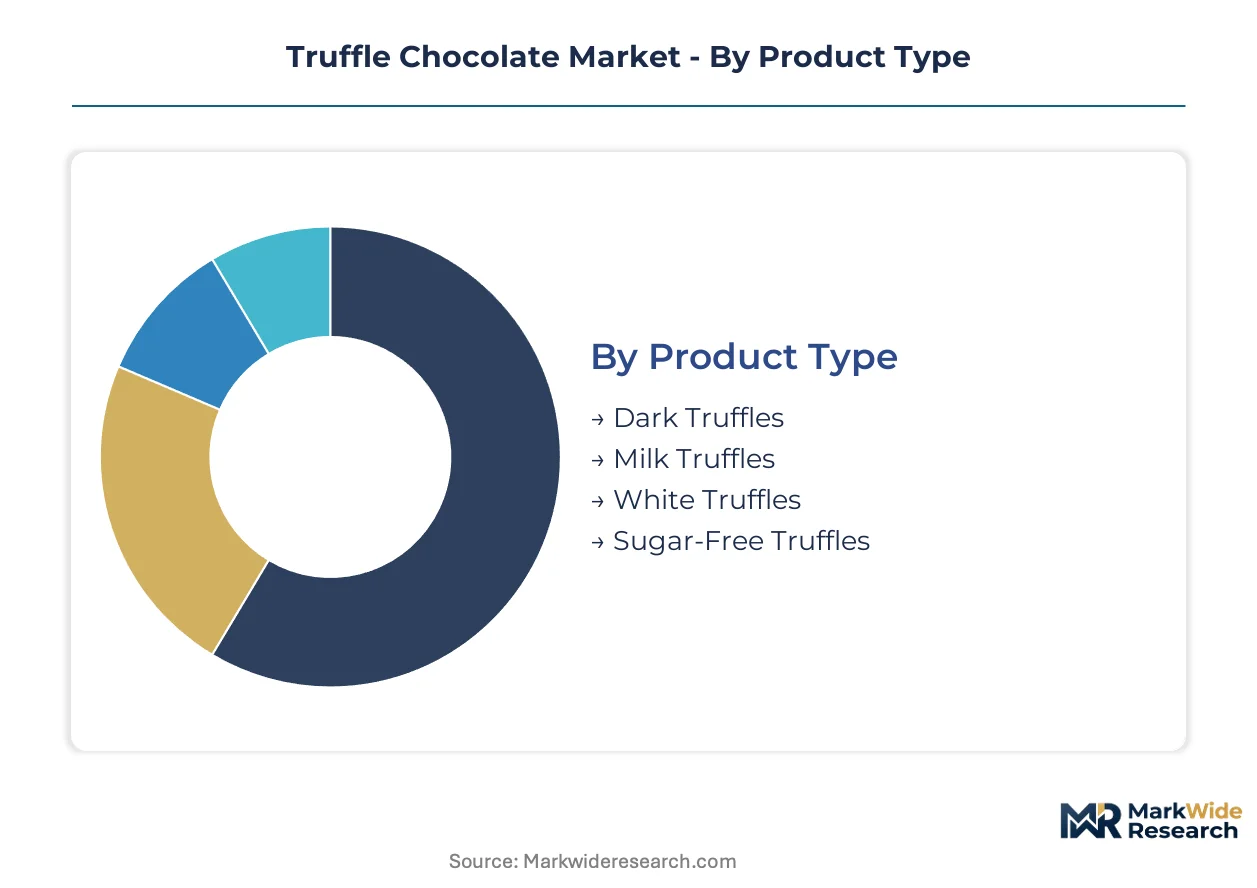
Truffle chocolate segmentation reveals how manufacturers balance heritage craft positioning against mass-market accessibility. Product type and flavor profile decisions determine cocoa butter sourcing intensity, while packaging and channel choices shape margin capture across impulse versus planned purchase occasions.
Product Type:
Consumer upgrade cycles from milk to dark formulations are shortening as health-positioned messaging accelerates trial conversion.
- Dark Truffles:These formulations carry 30-40% cocoa butter content with reduced sugar positioning that commands elevated price acceptance. Demand concentrates in Belgium and Switzerland where heritage chocolate traditions sustain premium willingness-to-pay among corporate gifting buyers navigating EUDR traceability requirements.
- Milk Truffles:The category retains absolute volume leadership through mass retail distribution networks. Growth is decelerating relative to flavor-differentiated alternatives as experiential taste exploration displaces conventional single-note offerings in Western European markets.
- White Truffles:Cocoa butter-dominant formulations without cocoa solids attract novelty-seeking segments in airport and luxury mall boutiques.
- Sugar-Free Truffles:Alternative sweetener formulations open compliant pathways for diabetic and low-glycemic dietary requirements under FSSAI disclosure rules in India.
Milk Truffles sits at the top of the volume ranking, with Dark Truffles climbing the fastest.
Packaging Type:
Cost tier stratification separates ceremonial gift formats from everyday indulgence access points.
- Boxed:Rigid presentation formats anchor premium gifting occasions with controlled environmental protection for temper-sensitive shells. Corporate procurement in Swiss and Belgian heritage markets drives concentration here.
- Bagged:Flexible pouches serve self-treat replenishment through subscription curation services. Lindt's direct-to-consumer platform leverages this format for year-round subscriber retention beyond seasonal peaks.
- Bulk:Foodservice-scale formats supply restaurant and café dessert plating requirements with portion-controlled cost management.
- Individual Wrappers:Single-unit protection enables impulse placement at transit hub retail with extended shelf stability for temperature-variable distribution.
Boxed formats dominate revenue per unit, while Bagged configurations are gaining share fastest through channel rotation into direct-to-consumer.
End User:
Application concentration determines service intensity and formulation flexibility requirements across controlled versus open-environment selling.
- Retail Consumers:The segment spans self-treat and gift purchase motivations with divergent price elasticity profiles. Supermarket and hypermarket distribution in Western Europe sustains baseline volume.
- Restaurants:Plated dessert applications demand consistent ganache texture for kitchen finishing with minimal handling skill requirements.
- Cafés:Coffee pairing occasions drive flavor profile coordination, particularly hazelnut and coffee variants for complementary taste architecture.
- Gift Shops:Curated assortments in airport and luxury mall locations capture experiential purchase moments with presentation-driven price premiums.
Retail Consumers anchor absolute volume, with Gift Shops expanding most quickly through boutique network strategies in Asia-Pacific transit hubs.
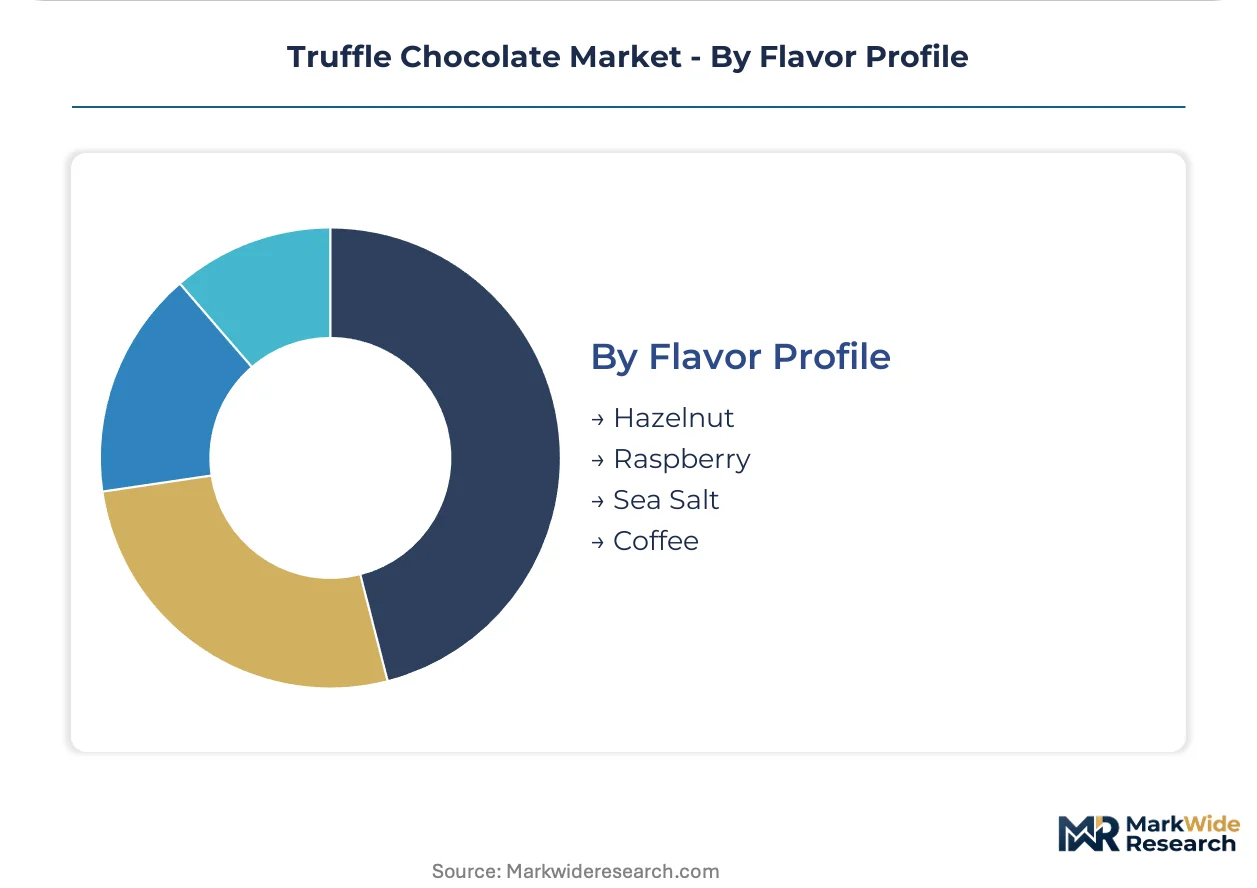
Flavor Profile:
Maturity gradients separate established heritage combinations from experimental taste exploration capturing younger demographic trial.
- Hazelnut:The classic pairing leverages regional sourcing from Turkish and Italian orchards with established consumer recognition. Belgian manufacturers anchor volume here through gianduja-derived heritage positioning.
- Raspberry:Fruit-acid contrast formulations attract experiential taste exploration demand. The profile captures fastest expansion as consumers displace conventional single-note offerings in premium tier trial.
- Sea Salt:Savory-sweet balance positioning targets functional food consumers seeking complexity without elevated cocoa bitterness. Swiss artisanal producers lead formulation refinement here.
- Coffee:Caffeine-adjacent indulgence occasions align with café channel concentration and morning consumption rituals.
Hazelnut maintains volume leadership from heritage positioning, with Raspberry showing the steepest expansion trajectory through taste exploration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland commands premium pricing power through heritage ganache craftsmanship, while Belgium's corporate gifting concentration drives institutional volume. The regulatory divergence between EU traceability mandates and emerging market disclosure rules creates distinct competitive terrain across national boundaries.
Belgium
Corporate procurement offices in Brussels and Antwerp sustain institutional gifting volume for boxed truffle assortments. The EU's EUDR deforestation regulation mandates geolocation verification for all cocoa imports entering Belgian manufacturing facilities. The Flanders region hosts concentrated artisanal production clusters where heritage confectioners temper ganache at precise 31-32°C specifications.
Switzerland
Private banking and luxury hospitality sectors in Zurich and Geneva generate sustained demand for premium dark truffle formats. Swissmedic food safety protocols intersect with EUDR traceability requirements to create dual compliance layers for cocoa butter sourcing. The Lake Geneva corridor maintains traditional atelier production methods alongside automated tempering installations.
Germany
Discounter retail penetration in Bavaria and North Rhine-Westphalia sustains mass-market milk truffle distribution. Germany's national implementation of REACH chemical safety standards requires residue documentation alongside EUDR origin tracking. The Cologne-Düsseldorf corridor hosts centralized distribution hubs serving cross-border EU retail networks.
United States
Direct-to-consumer subscription models in California and New York Metro areas accelerate flavor-differentiated trial beyond seasonal peaks. FDA food labeling requirements mandate allergen cross-contamination disclosure across multi-state supply chains. The Pacific Northwest cluster specializes in small-batch sea salt and raspberry profile development for experiential taste segments.
India
Organized retail expansion in Maharashtra and Karnataka opens compliant pathways for imported truffle brands. FSSAI ingredient disclosure rules and BIS standards constrain local formulation flexibility while enabling formal channel access. The Mumbai-Pune corridor concentrates duty-free airport retail where gifting occasions intersect with transit hub traffic.
Truffle Chocolate Market Competitive Environment
Top-tier vendors anchor heritage positioning and direct-to-consumer platforms, while mid-tier operators compete through retail partnership density. The vendor base stratifies across Swiss-Belgian artisanal specialists, integrated European conglomerates, and North American mass-market distributors. Three archetypes dominate: heritage atelier producers tempering small-batch ganache, vertically integrated cocoa processors controlling butter supply, and platform-native brands bypassing traditional retail. Competitive moves concentrate on subscription infrastructure buildout and EUDR-compliant supply chain certification.
Within the heritage atelier tier, Lindt & Sprüngli and Godiva Chocolatier exemplify divergent channel strategies. The Swiss GmbH structure of Lindt & Sprüngli occupies a position emphasizing direct-to-consumer replenishment platforms, while the Belgian heritage positioning of Godiva Chocolatier represents boutique network expansion in transit hubs and luxury malls. Ferrero anchors the integrated processing archetype through its Italian S.p.A. structure.
| Leading Market Players |
|---|
| Lindt & Sprüngli |
| Ferrero |
| Mondelez International |
| Nestlé |
| Mars |
| The Hershey Company |
| Godiva Chocolatier |
| Ghirardelli Chocolate Company |
| Neuhaus |
| Others |
Value Chain & Pricing Dynamics
Corporate gifting procurement offices in Brussels and Zurich anchor premium pricing power through heritage-format demand concentration, while mass-market retail channels compress margins through volume-scale negotiation leverage.
Pricing Analysis
Capacity additions in Switzerland and Belgium are reshaping price floors for artisanal-tier truffles as automated tempering installations replicate master chocolatier consistency without dedicated line investment. Three-tier pricing structure across premium, standard, and economy levels stratifies by cocoa butter concentration and EUDR certification status. Pricing pressure stems from cocoa butter input volatility as Côte d'Ivoire and Ghana supply concentration exposes mid-tier producers to commodity swings. Corporate buyers in heritage markets exhibit lowest price sensitivity while supermarket private-label shoppers drive cost compression.
Supply Chain Analysis
Direct-to-consumer subscription channels handle recurring replenishment demand while airport boutique networks capture experiential purchase premiums. Cocoa butter sourcing concentrates in Côte d'Ivoire, Ghana, and Indonesia with secondary processing in Belgium, Switzerland, and Germany. Ganache formulation draws from cocoa mass, dairy cream, and flavor adjunct dependencies with tempering equipment feeding from specialized European manufacturers. Single-source vulnerability in West African bean supply creates deforestation-linked regulatory exposure under EUDR audit protocols. Distribution runs through heritage atelier direct sales, organized retail partnerships, and transit hub duty-free networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in truffle chocolate hinges on subscription infrastructure monetization and dark-tier health positioning that commands elevated price acceptance with minimal input cost escalation.
For Market Incumbents: Lock in EUDR-compliant supply chain certification ahead of regulatory enforcement deadlines to create competitive separation from non-compliant operators. Deepen backward integration into cocoa butter processing to defend against commodity volatility while controlling tempering capacity expansion in Belgian and Swiss production clusters. For New Entrants and Emerging Players: Direct-to-consumer curation platforms offer the most penetrable entry vector for bypassing established retail gatekeepers. Target Indian formal retail channels under FSSAI disclosure compliance as import pathways open for heritage-positioned brands. Lead with raspberry and sea salt flavor differentiation to capture experiential taste exploration demand displacing conventional single-note offerings. For Investors and Strategic Acquirers: Vertically integrated European confectionery conglomerates are the most active acquirer in this space as they seek subscription infrastructure and boutique network assets. Long-term viability favors operators with dual heritage positioning and direct-to-consumer platform scale. Monitor EUDR compliance certification rates as the inflection indicator for supply chain competitive separation.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Launch | Direct-to-consumer replenishment builds recurring revenue beyond seasonal gifting peaks for Lindt-style operators. |
| EUDR Supply Chain Certification | Geolocation verification creates compliant market access for Belgian and Swiss heritage manufacturers under EU deforestation rules. |
| Experiential Flavor Portfolio Expansion | Raspberry and sea salt variants capture taste-exploration demand in airport and luxury mall boutique channels. |
| Automated Tempering Installation | Modular temperature control units enable artisanal scale-up without master chocolatier throughput constraints. |
| India Formal Retail Entry | BIS standards and FSSAI compliance open organized distribution pathways for imported premium brands in Maharashtra. |
Study Parameters
Bottom-up retail channel modeling reconciled against top-down cocoa butter supply tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at duty-free operators, supply planners at heritage ateliers, and channel sales heads at confectionery distributors combined with secondary validation from customs records, Nielsen retail audit data, and EUDR compliance filings. Cocoa origin documentation from Côte d'Ivoire and Ghana trade statistics, Swissmedic food safety protocols, and FSSAI disclosure registers anchored supply-side triangulation.
Input-output matrices mapped ganache formulation inputs through tempering equipment utilization to finished product channel placement across the projection horizon. Segmentation dimensions modeled include product type, flavor profile, packaging format, and end-use application with regional regulatory cluster overlays. CAGRs were derived from volume trajectory analysis against pricing tier elasticity. Forecast inputs incorporated cocoa butter price volatility indices and EUDR implementation timeline assumptions.
The model assumes a particular technology adoption path for precision tempering automation; alternative pathways for artisanal manual production retention would alter the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and consumer health-positioning acceptance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Brain Mint Market
Confectionery
Sugar Free Mints Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
North America Premium Chocolate Market
Confectionery
Middle East and Africa Confectionery Market
Confectionery
Dark Chocolate Market
Confectionery
Chocolate Confectionery Market
Confectionery
Italy Chocolate Market
Confectionery
Green Tea Chocolate Market
Confectionery
Bangladesh Candy Market
Confectionery
South America Chocolate Market
Confectionery
Brazil Chocolate Market
Confectionery
Low Calorie Nutella Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Buttercream Frosting Market
Confectionery
South America Compound Chocolate Market