
 Vegan Gummy Candy Market | 2026-2036
Vegan Gummy Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Gummy Candy Market Insights
Ingredient sourcing from animal-based gelatin to plant-derived hydrocolloids is reshaping margin distribution across the vegan gummy value chain. Katjes leverages its German manufacturing heritage to sustain pectin-based production at scale. SmartSweets differentiates through clean-label positioning and reduced-sugar formulations that occupy prime placement in North American health retailers. YumEarth anchors its competitive stance through certified organic supply chains and controls distribution across natural grocery channels in the United States.
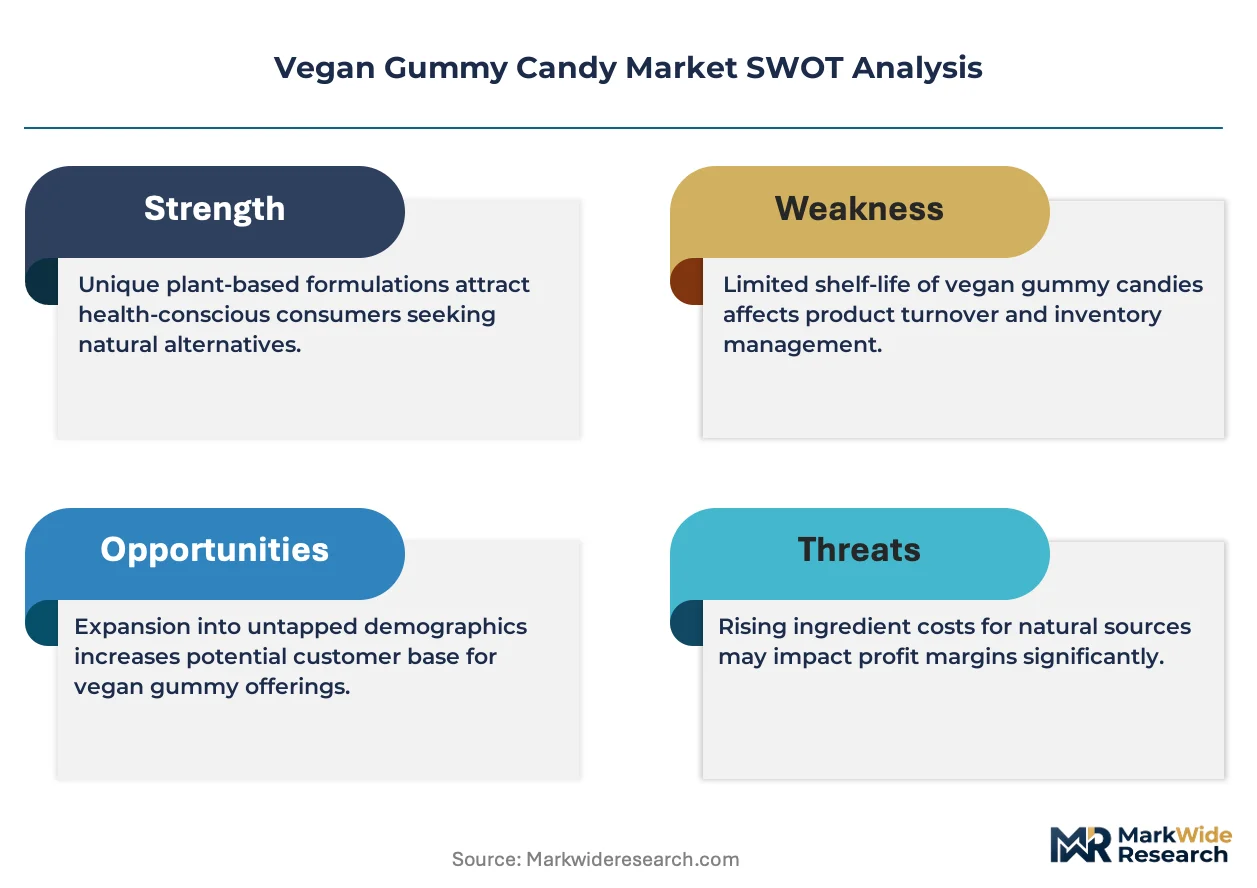
Vegan gummy candy denotes confectionery products formulated without animal-derived gelatin, utilizing pectin, agar, or starch as gelling agents, typically containing fruit juices, natural colorants, and sweeteners to achieve chewable texture profiles. These products serve consumers seeking plant-based indulgence, dietary supplement delivery vehicles, and allergen-free alternatives in mainstream confectionery and functional nutrition applications. The functional product type segment leads margin capture as brands infuse adaptogens, vitamins, and probiotics into gummy formats. Pectin dominates ingredient preferences among manufacturers prioritizing clean-label transparency and thermal stability during processing. Online retail channels represent the fastest-growing distribution pathway, driven by direct-to-consumer subscription models and influencer-driven discovery.
The FDA enforces food labeling accuracy for vegan claims under the Federal Food, Drug, and Cosmetic Act, while USDA organic certification shapes premium positioning for plant-based confections. The EU's EFSA guidelines on novel food ingredients and REACH compliance for food contact materials create additional compliance layers for exporters serving European markets. Stakeholders must monitor evolving clean-label certification requirements and hydrocolloid supply volatility as pectin demand outstarts citrus peel sourcing capacity.
Market Dynamics
Pectin supply concentration in citrus-growing belts is forcing manufacturers to renegotiate long-term contracts as clean-label demand outstrips peel-derived hydrocolloid availability. FDA labeling scrutiny on vegan claims compounds procurement pressure by mandating third-party certification documentation.
Growth Catalysts
- Clean-label mandates:USDA organic certification requirements push conventional brands toward plant-derived gelling agents. Retailers in natural grocery channels now demand certified vegan positioning for shelf placement.
- Functional nutrition pivot:Vitamin and adaptogen infusion into gummy formats expands addressable demand beyond confectionery into wellness applications. Supplement brands prioritize pectin-based delivery vehicles for thermal stability during processing.
- Millennial and Gen Z purchasing power:Health-conscious younger consumers command premium positioning for allergen-free indulgence. Social media-driven discovery accelerates trial rates for novel plant-based formulations.
Market Restraints
- Pectin input volatility:Citrus peel sourcing concentration in Brazil and Mexico exposes margins to climate-driven supply shocks. Alternative hydrocolloids like agar require reformulation investment with uncertain texture outcomes.
- Technical texture limitations:Plant-derived gelling agents achieve softer chew profiles than animal-based gelatin, constraining applications in certain confectionery formats. Manufacturers face shelf-stability trade-offs when reducing sugar content.
- Substitution threat from conventional candy:Price-sensitive consumers in mass retail channels continue purchasing gelatin-based alternatives. Private-label conventional gummies capture volume in dollar-store and convenience segments.
Strategic Opportunities
- Underpenetrated functional segments:Probiotic and nootropic gummy formats remain nascent relative to vitamin applications. Brands investing in clinical substantiation capture margin in cognitive health positioning.
- Direct-to-channel innovation:Subscription-based replenishment models bypass traditional retail slotting fees. Influencer-curated discovery on social platforms reduces customer acquisition costs versus conventional advertising.
- EU regulatory tailwind:EFSA novel food ingredient pathways create first-mover advantage for brands achieving compliance. REACH-compliant packaging materials open premium positioning in German and French natural channels.
Industry Challenges
- Formulation talent scarcity:Food scientists with dual expertise in hydrocolloid chemistry and clean-label stability command premium compensation. Mid-size manufacturers struggle to recruit against larger confectionery conglomerates.
- Certification timeline compression:Third-party vegan verification processes extend product development cycles by four to six months. Concurrent USDA organic and non-GMO project documentation strains regulatory affairs capacity.
- Legacy equipment retrofitting:Gelatin-optimized production lines require capital expenditure for temperature and shear-rate modifications. Depreciation schedules on existing assets delay pectin-scale investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Gummy Candy Market |
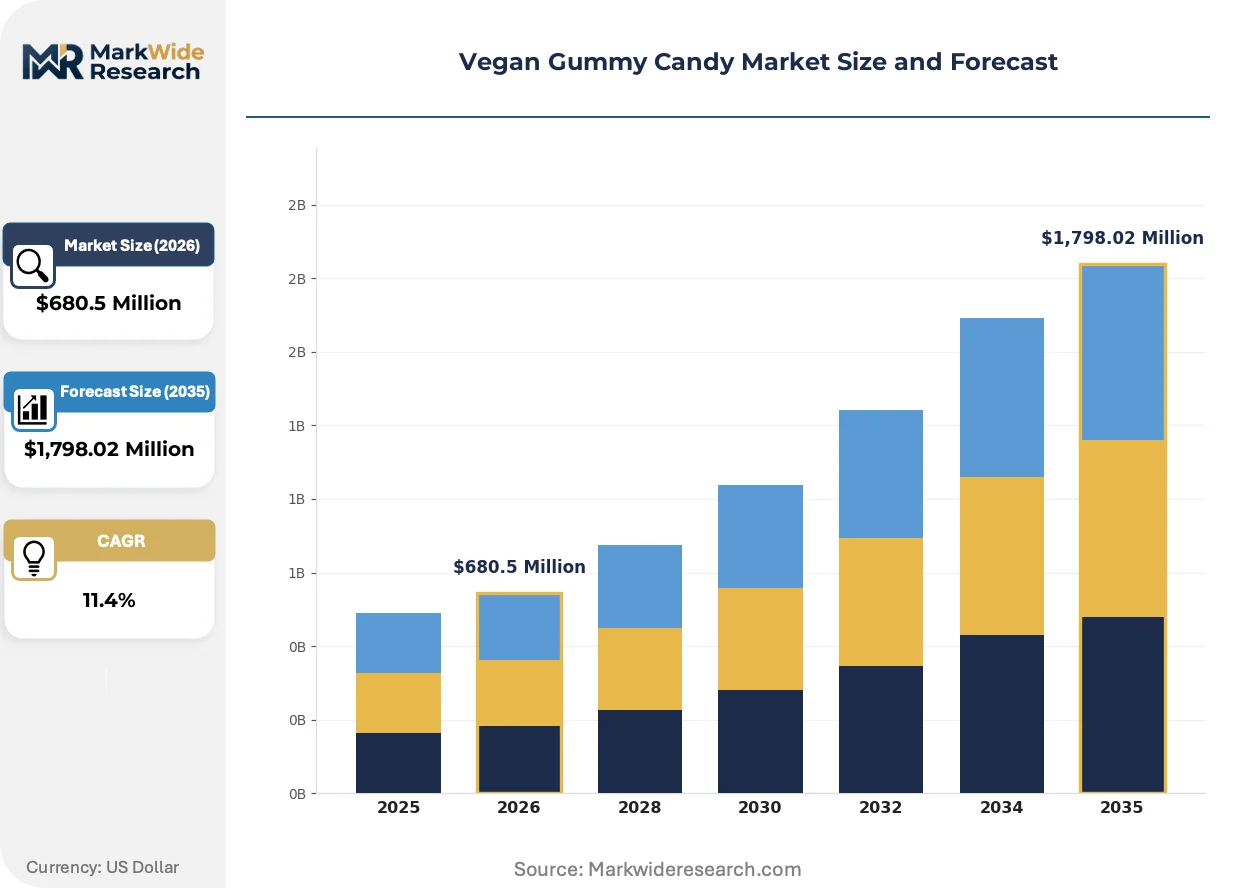
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $1,798.02 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Flavored, Sour, Sugar-Free, Functional Ingredient Type: Natural Colors, Pectin, Agar, Starch Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Consumer Age Group: Children, Teens, Adults, Seniors |
| Companies Covered | LeChao Candy, YourGummyVitamins, Katjes, Sweetdreams Ltd, Virc Nutritionals, SmartSweets, Vitafusion, GW Gummies, YumEarth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Gummy Candy Market Trends and Innovations
Texture engineering breakthroughs and regulatory transparency mandates are compressing development timelines while fragmenting competitive advantage sources. Manufacturers now compete on formulation speed rather than scale economies alone.
Modified pectin with enhanced thermal stability is collapsing the performance gap between plant-derived and animal-based gelling systems. Functional nutrition brands in North America and Western Europe are adopting these grades at accelerated procurement rates. The technology is collapsing premium pricing power for legacy gelatin suppliers in vitamin gummy applications.
EFSA's tightened novel food ingredient evaluation protocols are extending approval timelines for emerging hydrocolloids like konjac and tara gum. European manufacturers face reformulation freezes pending safety dossier completion. Functional gummy startups are responding by prioritizing grandfathered pectin formulations over innovative gelling systems.
Consumer verification behaviors now center on blockchain-traceable ingredient sourcing rather than front-of-package claims alone. Natural grocery channels in the United States and Germany are displacing conventional retail as the primary discovery environment. This shift concentrates brand-building investment in influencer partnerships and subscription infrastructure rather than trade promotion.
Vegan Gummy Candy Market Segmentation
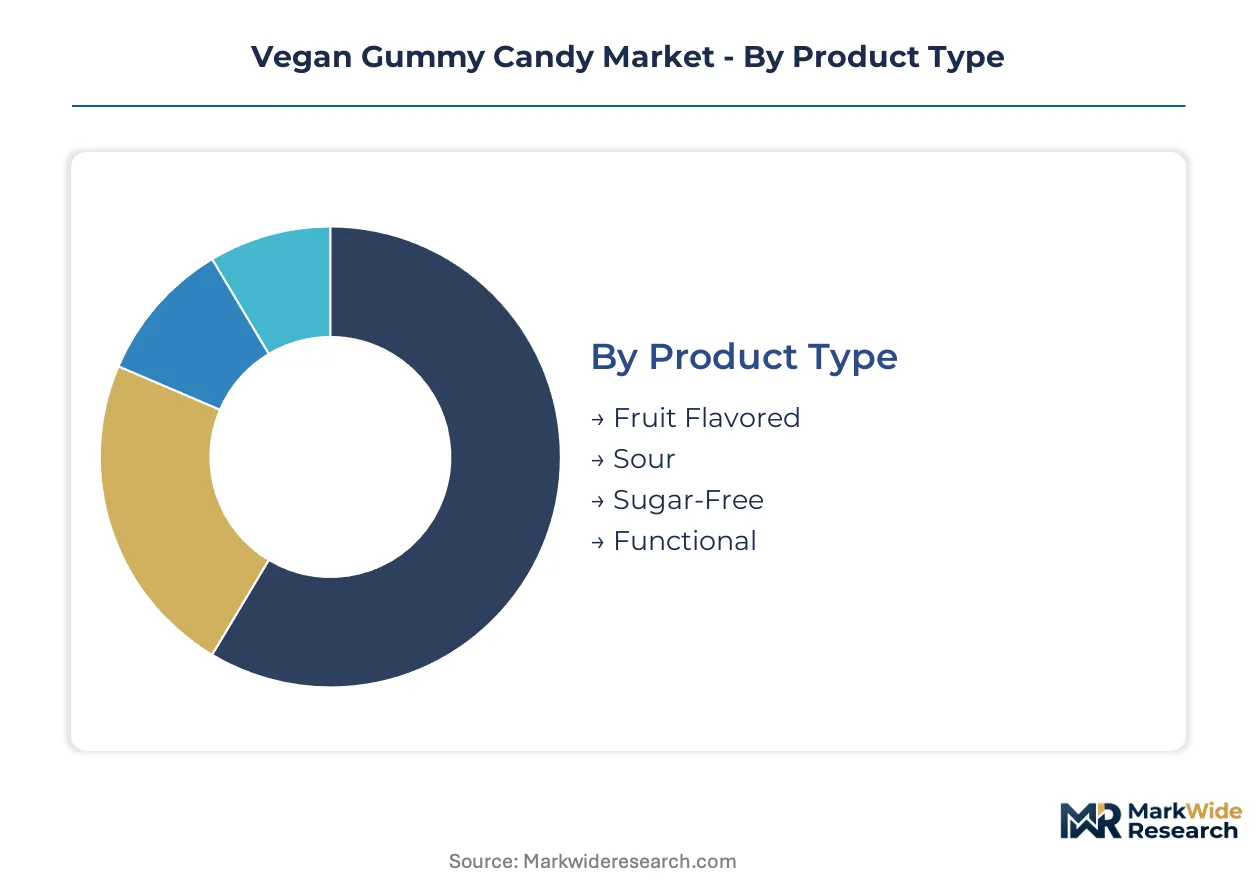
Vegan gummy candy segmentation reveals distinct margin profiles across formulation sophistication and channel access. Product type and ingredient selections determine thermal stability requirements and certification complexity, while distribution channels dictate packaging formats and shelf-life specifications.
Product Type:
Mature formats dominate current throughput, though functional variants are emerging as the highest-margin expansion frontier.
- Functional:These gummies incorporate vitamins, adaptogens, probiotics, or nootropics into pectin-based matrices. North American wellness retailers and direct-to-consumer subscription services concentrate demand for clinically substantiated formulations. FDA labeling scrutiny on structure-function claims elevates documentation burdens for entrants.
- Fruit Flavored:Standard formulations using fruit juices and natural colorants represent the volume foundation. Clean-label mandates from USDA organic certification programs and natural grocery channel buyers sustain pectin procurement priority. Texture engineering investments focus on matching gelatin chew profiles.
- Sour:Acidulated coatings on pectin bases require modified stability testing for shelf-life validation. German and French natural channels show concentrated preference for this sensory profile.
- Sugar-Free:Polyol-sweetened formulations targeting diabetic and low-glycemic consumers. Technical constraints around cooling effects and laxation thresholds limit formulation flexibility.
Functional handles the majority of throughput; sugar-free is the fastest mover on share.
Ingredient Type:
Cost tier differentiation separates premium-positioned hydrocolloids from commodity starch alternatives.
- Pectin:Citrus peel-derived gelling agent offering thermal stability and clean-label transparency. Brazilian and Mexican sourcing concentration exposes margins to climate volatility. Manufacturers prioritize long-term contracts with peel processors.
- Agar:Seaweed-extracted hydrocolloid with firmer set characteristics. Japanese and South Korean supply chains dominate extraction capacity. Reformulation investment requirements constrain mid-size manufacturer adoption.
- Natural Colors:Beet, turmeric, and spirulina-derived pigments replacing synthetic alternatives. EU EFSA novel food evaluations extend approval timelines for emerging sources.
- Starch:Modified corn and tapioca derivatives serving economy-tier positioning. Texture limitations relative to pectin and agar relegate applications to private-label and mass retail channels.
Pectin handles the majority of throughput; agar is expanding most quickly among clean-label specialists.
Distribution Channel:
Customer type stratification separates impulse purchasers from planned replenishment behaviors.
- Online Retail:Direct-to-consumer platforms and subscription models bypass slotting fees. Influencer-curated discovery on social platforms reduces customer acquisition costs relative to conventional advertising. Packaging formats optimize for shipping durability.
- Health Stores:Natural grocery channels in the United States and Germany demand certified organic and non-GMO documentation. Prime shelf placement commands premium positioning.
- Supermarkets:Mass retail penetration requires price competitiveness against gelatin-based alternatives. Private-label competition intensifies margin pressure.
- Specialty Shops:Curated assortments in confectionery boutiques and airport retail. Limited throughput but highest per-unit margins.
Supermarkets handle the majority of throughput; online retail is gaining share fastest.
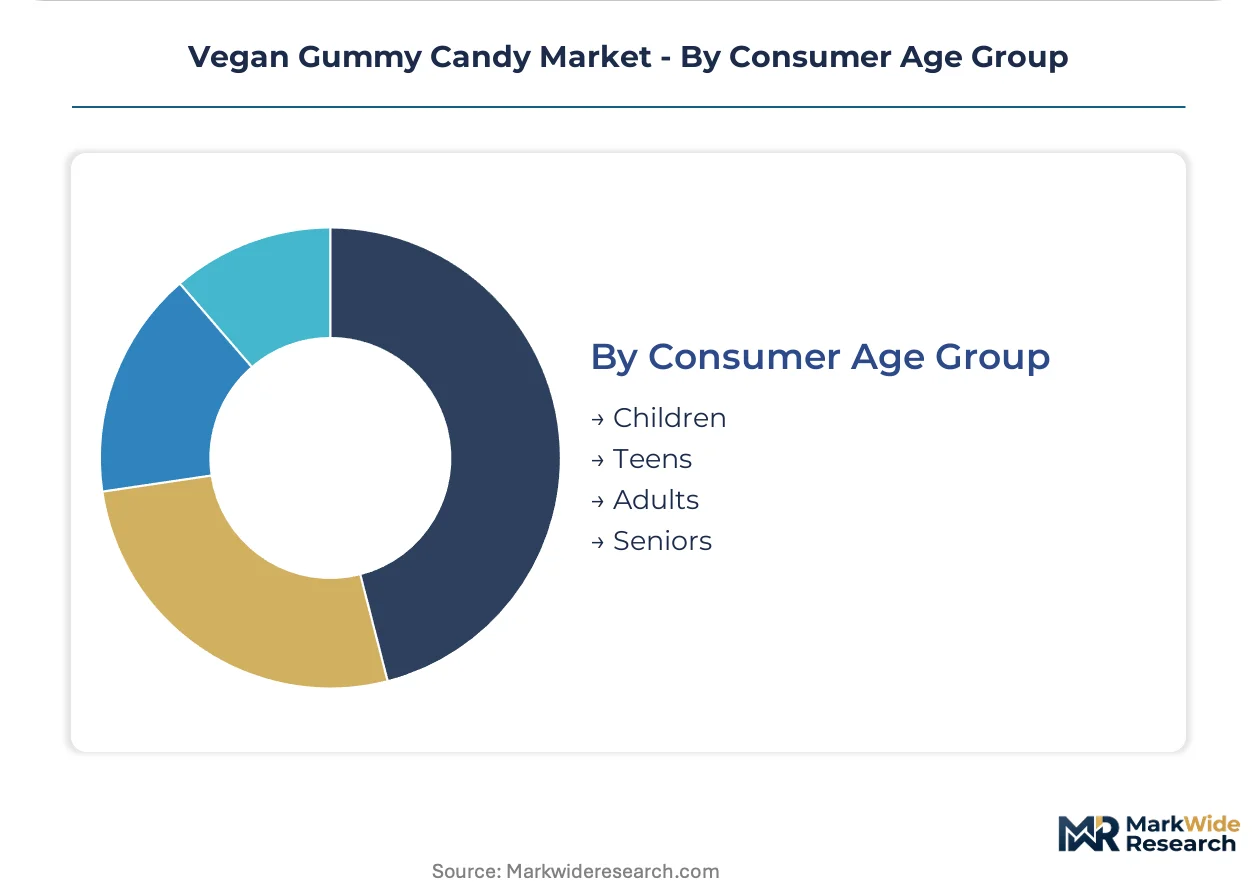
Consumer Age Group:
Application focus varies across life-stage nutritional requirements and permissibility preferences.
- Adults:Functional gummy consumption concentrates in millennial and Gen Z demographics seeking wellness-oriented indulgence. Vitamin and adaptogen formulations dominate.
- Children:Allergen-free and organic claims drive parental purchasing decisions. School lunchbox compatibility shapes portion sizing.
- Teens:Social media discovery accelerates trial rates for novel flavor profiles. Sour and extreme flavor variants show concentrated preference.
- Seniors:Joint health and cognitive support functional claims align with supplement routines. Swallowing ease relative to tablets drives format preference.
Adults handle the majority of throughput; seniors show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. German and French consumers absorb premium positioning for certified organic pectin formulations, while mass retail channels in Brazil and Mexico remain dominated by price-sensitive purchasing.
United States
Millennial and Gen Z wellness spending concentrates demand for functional gummy vitamins with adaptogen infusion. FDA labeling scrutiny under the Federal Food, Drug, and Cosmetic Act mandates third-party vegan certification documentation. California-based clean-label startups command prime shelf placement in natural grocery channels across Los Angeles and San Francisco metropolitan clusters.
Germany
EFSA novel food ingredient pathways shape competitive entry strategies for pectin-based formulations. REACH compliance for food contact materials creates additional certification layers for domestic manufacturers. Bavarian confectionery heritage clusters around Munich sustain scaled pectin production infrastructure serving export markets.
Brazil
Citrus peel sourcing concentration in São Paulo and Minas Gerais states exposes margins to climate-driven supply volatility. ANVISA food additive regulations govern hydrocolloid approval timelines for reformulated products. Southeast industrial zones around Campinas anchor peel processing capacity for regional pectin supply.
Japan
Agar-derived gummy formats retain concentrated preference in traditional confectionery applications. METI standards on food manufacturing hygiene shape facility certification requirements. Kansai region processors around Osaka maintain seaweed extraction expertise for premium hydrocolloid supply.
United Kingdom
Post-Brexit regulatory divergence from EU EFSA frameworks creates parallel compliance pathways for novel ingredients. FSA allergen labeling mandates elevate documentation burdens for plant-based claims. London metropolitan retail clusters drive direct-to-consumer subscription model adoption.
Vegan Gummy Candy Market Competitive Landscape
Capability concentration sits with heritage pectin specialists; scale advantage sits with diversified confectionery conglomerates. The vendor base stratifies across three tiers: German manufacturing heritage players, North American clean-label disruptors, and Asian contract manufacturers. Strategic moves center on backward integration into citrus peel sourcing and influencer-curated direct-to-consumer channel construction.
Within the heritage manufacturing tier, Katjes exemplifies scaled pectin-based production sustained through European supply chain control. Among North American clean-label specialists, SmartSweets and YumEarth occupy positions defined by certified organic documentation and natural grocery channel penetration. These three anchors represent divergent competitive archetypes: continental European scale, insurgent clean-label positioning, and supply chain transparency leadership.
| Leading Market Players |
|---|
| LeChao Candy |
| YourGummyVitamins |
| Katjes |
| Sweetdreams Ltd |
| Virc Nutritionals |
| SmartSweets |
| Vitafusion |
| GW Gummies |
| YumEarth |
| Others |
Pricing and Supply Chain Analysis
Citrus peel sourcing concentration in Brazilian and Mexican growing belts exposes margin tiers to climate-driven supply shocks, compressing pricing spreads between certified organic pectin formulations and conventional alternatives while forcing manufacturers toward long-term contract renegotiation. FDA labeling scrutiny on vegan claims compounds procurement pressure by mandating third-party certification documentation that separates premium-positioned brands from economy-tier competitors.
Pricing Analysis
Subscription-based replenishment revenue drives lifetime value for direct-to-consumer functional gummy brands. Three-tier pricing structure across premium organic-certified, standard clean-label, and economy private-label levels separates market positions. Price differentiation hinges on USDA organic certification tier and influencer-curated brand equity. Cost compression in the economy tier intensifies because starch-based alternatives undercut pectin formulations in mass retail channels. Dollar-store and convenience segment buyers exhibit highest price sensitivity, while natural grocery channel consumers absorb premium positioning for blockchain-traceable ingredient sourcing.
Supply Chain Analysis
Tariff exposure between Brazil and the United States dominates supply chain risk calculus for North American manufacturers dependent on citrus peel imports. Pectin extraction capacity concentrates in São Paulo state, Campinas industrial zones, and Mexican Veracruz processing clusters. Raw material dependencies rest on citrus peel supply, seaweed-derived agar from Japanese and South Korean extractors, and modified starch from corn belt processors. Single-source vulnerability in Brazilian peel supply creates margin volatility during harvest disruptions. Distribution runs through natural grocery channel consolidation, direct-to-consumer subscription platforms, and mass retail slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan gummy candy market sits at a regulatory inflection where FDA and EFSA labeling transparency mandates are accelerating competitive consolidation around certified pectin supply chains. Modified pectin thermal stability breakthroughs are collapsing the performance gap with gelatin, enabling functional nutrition brands to capture wellness-oriented consumer spending.
For Market Incumbents: Entrench pectin supply chain control through backward integration into Brazilian citrus peel processing or exclusive long-term contracts with São Paulo extractors. Katjes and heritage European manufacturers should defend against North American clean-label insurgents by accelerating EFSA novel food ingredient dossier completion for modified pectin grades, locking in regulatory first-mover advantage before subscription-based challengers scale. For New Entrants and Emerging Players: Probiotic and nootropic functional gummy segments in German and French natural channels represent the most penetrable entry point given underinvestment by established vitamin brands. Direct-to-consumer subscription models with influencer-curated discovery on social platforms offer lower customer acquisition costs than conventional retail slotting fee competition against incumbent shelf presence. For Investors and Strategic Acquirers: The market sits at a growth-phase inflection that favors mid-size manufacturers with captive pectin supply and dual expertise in hydrocolloid chemistry and clean-label stability. Long-term viability over the next decade hinges on clinical substantiation capabilities for structure-function claims and certification documentation infrastructure. Watch for FDA enforcement actions on vegan claim accuracy as the signal indicating regulatory timeline compression and accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Peel Processing | Captive pectin supply from Brazilian São Paulo extractors insulates margins from climate-driven volatility. |
| EFSA Novel Food Ingredient Dossier Completion | Regulatory first-mover advantage in German and French natural channels blocks competitor reformulation. |
| Direct-to-Consumer Subscription Launch | Influencer-curated discovery on social platforms reduces customer acquisition costs versus retail slotting fees. |
| Clinical Substantiation Investment for Functional Claims | FDA-compliant structure-function documentation elevates barrier to entry for vitamin and adaptogen entrants. |
| Blockchain-Traceable Ingredient Sourcing | Verification infrastructure satisfies natural grocery channel demands beyond front-of-package claims. |
Research Methodology
The analysis maps functional nutrition, fruit-flavored confectionery, sour variants, and sugar-free formulations, each validated through formulation scientists at pectin manufacturers, procurement leads at natural grocery retailers, regulatory affairs specialists at supplement brands, and hydrocolloid chemistry researchers. Primary interviews with these stakeholders combined with secondary validation from FDA labeling guidance documents, EFSA novel food ingredient safety opinions, USDA organic certification databases, and customs records on citrus peel trade flows. Bottom-up segmentation sizing triangulates against top-down market aggregation.
Forecast assumptions held fixed the current regulatory enforcement posture on vegan claims while varying pectin supply availability and clean-label certification adoption curves across the projection horizon. The analytical framework models product type sophistication, ingredient grade tier, distribution channel access, and consumer age group life-stage requirements. CAGRs derive from segment-level growth rate blending weighted by throughput contribution. Forecast inputs include hydrocolloid procurement contract tenor patterns and natural grocery channel shelf space allocation trends.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on wellness categories, citrus commodity price volatility, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on certification timeline compression and supply concentration stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
North America Dark Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
United States and Europe Macarons Market
Confectionery
UK Compound Chocolate Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
UK Chocolate Market
Confectionery
Dark Chocolate Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Ice Cream Coating Market
Confectionery
Asia-Pacific Confectionery Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Low Calorie Nutella Market
Confectionery
Crunchy Chocolate Market
Confectionery
Milk Chocolate Market
Confectionery
Mooncake Market
Confectionery
Sugar-Free Gumballs Market