
 Sugar-Free Gumballs Market | 2026-2036
Sugar-Free Gumballs Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar-Free Gumballs Market Analytics
Bulk-to-individual pack configuration is shifting buyer choice in the sugar-free gumballs market, as single-serve formats penetrate pharmacy counters and vending channels. Wrigley Company leverages its retail shelf-space dominance to sustain visibility in convenience-store checkout zones. Perfetti Van Melle anchors European distribution through pharmacy and health-channel partnerships. Mondelez International competes on flavor-innovation velocity, while Lotte dominates sugar-alcohol sourcing relationships in Northeast Asian supply chains.
Sugar-free gumballs are spherical confectionery pieces formulated with non-nutritive sweeteners—typically sorbitol, xylitol, or maltitol—rather than sucrose, manufactured through extrusion and pan-coating processes to achieve controlled dissolution rates and extended chew texture. Their primary commercial purpose centers on oral stimulation without glycemic impact, serving diabetic consumers, dental-health protocols, and calorie-controlled regimens. Natural sweetener formulations now lead product-type growth as clean-label preferences intensify, while vending-machine distribution channels represent the fastest-expanding margin pool due to higher per-unit pricing and lower labor overhead. Functional gumballs incorporating xylitol for caries prevention command the strongest premium positioning across pharmacy and dental-clinic channels.
FDA nutrition-labeling mandates for polyol content disclosure shape formulation decisions and packaging redesign cycles for US market participants. EFSA health-claim frameworks govern xylitol-related dental-benefit messaging across European markets, with BIS standards in India constraining sweetener purity thresholds for import clearance. Stakeholders must monitor evolving sweetener approval lists and front-of-pack labeling mandates to anticipate reformulation costs and channel-access requirements.
Market Dynamics
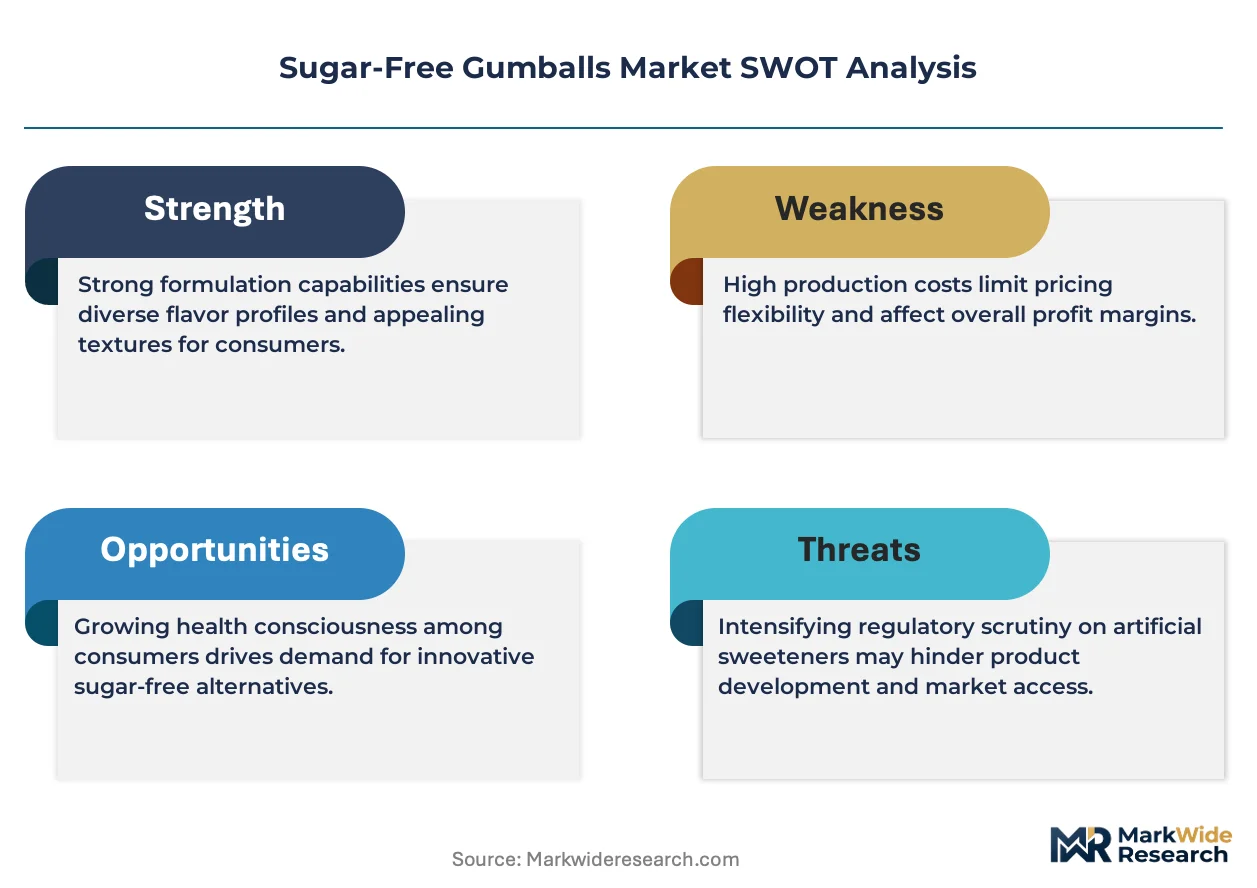
FDA polyol disclosure mandates are forcing packaging redesign cycles across US sugar-free gumball portfolios, while EFSA xylitol health-claim frameworks compress marketing latitude in European pharmacy channels.
Growth Catalysts
- Dental-clinic channel penetration:Xylitol-functional gumballs now occupy pharmacy counters in Germany as patient-compliant confectionery alternatives, with clinicians prescribing them for caries-prevention protocols.
- Clean-label formulation shift:Natural sweetener variants are displacing synthetic polyol bases as consumer scrutiny of ingredient panels intensifies across North American retail.
- Vending-machine margin expansion:Single-serve formats in automated retail channels capture premium per-unit pricing with minimal labor overhead, rewriting distribution economics for impulse confectionery.
Market Restraints
- Sugar-alcohol input volatility:Xylitol supply concentrates in Chinese and Finnish birch-processing facilities, exposing formulations to feedstock price swings and currency fluctuation.
- Digestive tolerance thresholds:Sorbitol and maltitol carry mandatory laxative warnings above threshold dosages, limiting portion sizes and repeat-consumption frequency in regulatory-sensitive markets.
- Chewing-gum substitution pressure:Functional mints and dissolvable oral strips compete for identical use-cases with superior portability and no disposal friction.
Strategic Opportunities
- Pediatric dental protocols:Sugar-free gumballs formulated for child-appropriate texture and flavor profiles remain underpenetrated in US school-based preventive dentistry programs.
- Biodegradable gum-base innovation:Convergence of enzymatic degradation chemistry with traditional polyol sweetening opens landfill-diversion claims for sustainability-positioned brands.
- Pharmacy-chain exclusive SKUs:Private-label xylitol gumballs with EFSA-aligned dental-benefit messaging command shelf-space premiums in European health-channel retail.
Industry Challenges
- Polyol purity certification timelines:BIS import-clearance standards in India require third-party sweetener assay documentation, extending product-registration cycles by four to six months.
- Extrusion equipment retooling costs:Clean-label natural sweeteners demand modified temperature-control parameters in pan-coating lines, forcing capital deployment in legacy manufacturing assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar-Free Gumballs Market |
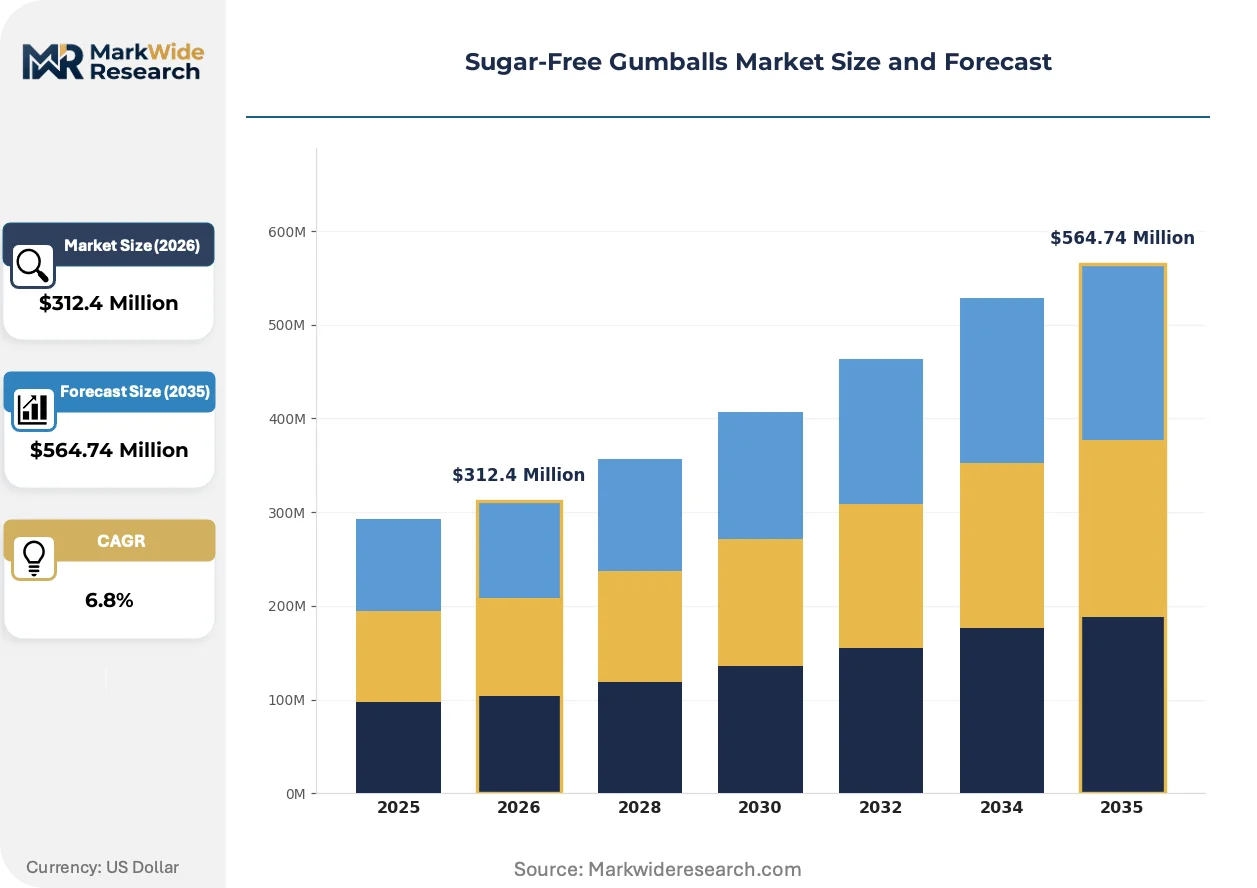
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Sweeteners, Natural Sweeteners, Flavored Gumballs, Functional Gumballs Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Vending Machines End User: Kids, Adults, Health-Conscious Consumers, Diabetics Packaging Type: Bags, Boxes, Bulk Packaging, Individual Packs |
| Companies Covered | Perfetti Van Melle, Wrigley Company, Mondelez International, Lotte, The Hershey Company, Mars Incorporated, Cadbury Trebor Bassett, Dubble Bubble, Roquette, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar-Free Gumballs Market Evolving Landscape
Reformulation transparency and channel-specific positioning are compressing product-development cycles, with manufacturers racing to align ingredient narratives with jurisdiction-specific disclosure mandates.
Enzymatically modified stevia glycosides are rewriting sweetness delivery in sugar-free gumball formulations, enabling deeper calorie reduction without the cooling aftertaste associated with bulk polyols. Dental-clinic buyers in Germany and Switzerland are adopting these variants for pediatric patient compliance. The technology is compressing the performance gap between natural and synthetic sweetener systems.
EFSA health-claim enforcement on xylitol dental benefits is narrowing permissible marketing language across EU member states, forcing pack-copy revision and clinical-submission investments. Manufacturers must now substantiate caries-prevention claims with trial data meeting MDR-level evidence standards. Pharmacy-channel SKUs face the steepest compliance burden as health-professional endorsement requirements tighten.
Single-serve blister and stick-pack formats are displacing traditional jar and bulk configurations in pharmacy and vending channels, with buyers prioritizing portion control and hygiene assurance. Convenience-store operators in Japan and South Korea are reallocating checkout-zone space toward individually wrapped functional confectionery. This rotation is most visible in urban transit-hub retail where consumption occasion fragmentation drives format miniaturization.
Sugar-Free Gumballs Market Segmentation
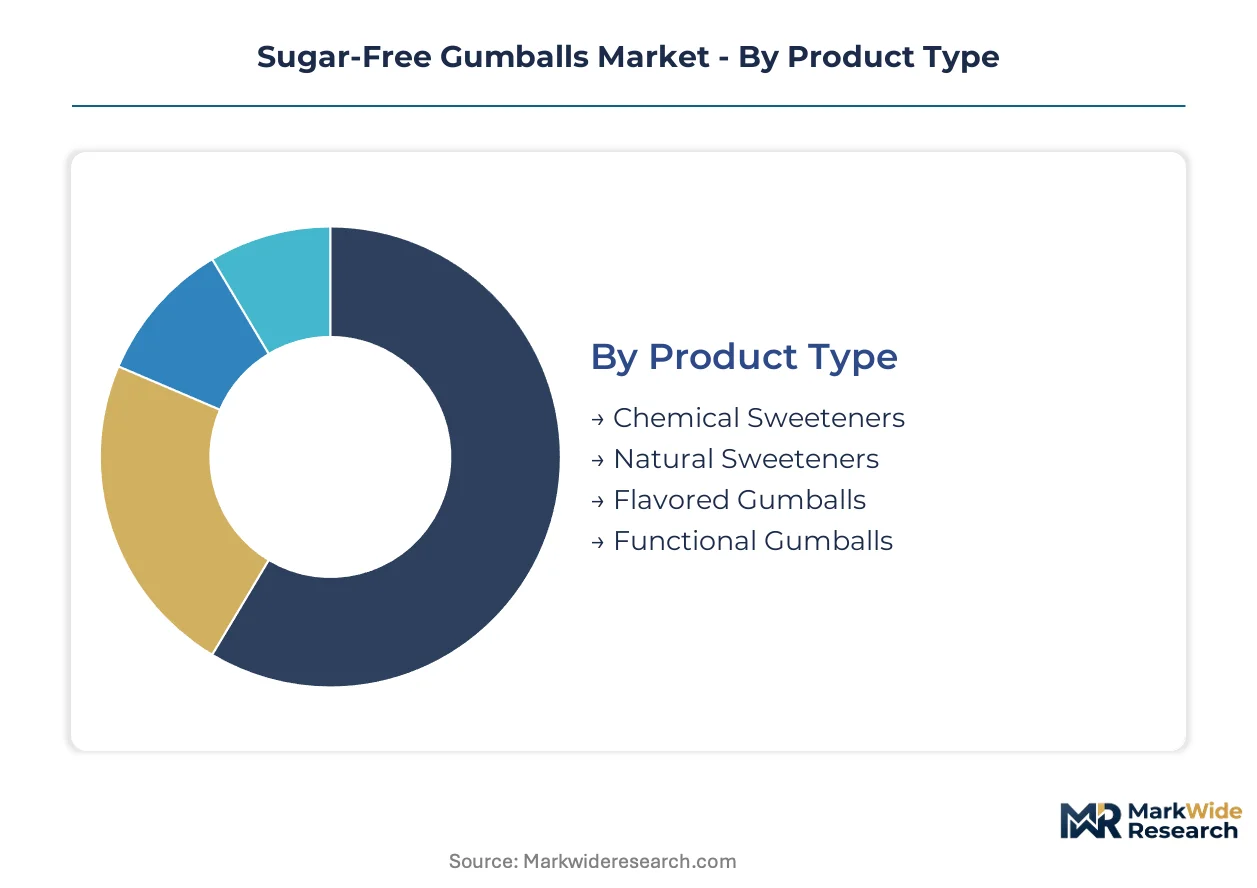
Sugar-free gumball manufacturers configure portfolios across four distinct axes to capture margin pools with divergent technical requirements and channel economics. Each segmentation dimension carries unique formulation, packaging, and regulatory compliance burdens that reshape competitive positioning.
Product Type:
Sweetener chemistry determines dissolution kinetics, cooling aftertaste intensity, and regulatory claim eligibility across pharmacy and retail channels.
- Natural Sweeteners:Stevia glycosides and monk fruit extracts enable clean-label positioning with zero glycemic impact. Demand concentrates in German pharmacy chains where EFSA-aligned dental-benefit messaging commands shelf-space premiums and clinician endorsement protocols.
- Functional Gumballs:Xylitol-dominant formulations engineered for caries-prevention protocols carry therapeutic positioning in dental-clinic dispensing. Japanese pediatric dentistry programs are adopting these variants for school-based preventive care compliance.
- Chemical Sweeteners:Sorbitol and maltitol bases deliver cost-efficient sweetness with established manufacturing infrastructure.
- Flavored Gumballs:Fruit and mint variants prioritize sensory novelty over functional claims in impulse retail channels.
Mature deployment sits with Chemical Sweeteners. Newer deployment is concentrated in Natural Sweeteners.
Distribution Channel:
Channel selection dictates pack-size economics, labor overhead, and per-unit pricing power with minimal negotiation leverage.
- Vending Machines:Automated retail captures premium per-unit pricing with near-zero labor overhead. Urban transit hubs in Japan and South Korea are reallocating checkout-zone space toward individually wrapped functional formats as consumption occasion fragmentation accelerates.
- Convenience Stores:Impulse-oriented placement at checkout zones drives high-velocity turnover with limited SKU breadth. Korean operators favor single-serve blister packs for hygiene assurance in high-traffic locations.
- Supermarkets:Multi-pack configurations dominate shelf sets with price-promotion dependency.
- Online Retail:Subscription and bulk formats penetrate diabetic and health-conscious consumer segments with direct-to-door logistics.
Established volume flows through Supermarkets. Channel investment is shifting fastest into Vending Machines.
End User:
Demographic targeting shapes texture engineering, flavor intensity calibration, and health-claim substantiation requirements.
- Health-Conscious Consumers:Calorie-tracking and ingredient-panel scrutiny drive clean-label procurement with willingness-to-pay premiums. North American retail buyers prioritize enzymatically modified stevia systems that eliminate polyol cooling aftertaste.
- Diabetics:Zero-glycemic-impact formulations require rigorous glucose-response documentation. German pharmacy chains stock these variants alongside glucose-monitoring supplies as lifestyle-management adjuncts.
- Adults:Stress-relief and oral-fixation use cases favor extended chew texture and moderate sweetness intensity.
- Kids:Pediatric-appropriate texture and flavor profiles remain underpenetrated in preventive dentistry protocols.
Volume concentration rests with Adults. Segment expansion is climbing the fastest among Health-Conscious Consumers.
Packaging Type:
Format selection governs portion-control compliance, shelf-life extension, and channel-specific hygiene standards.
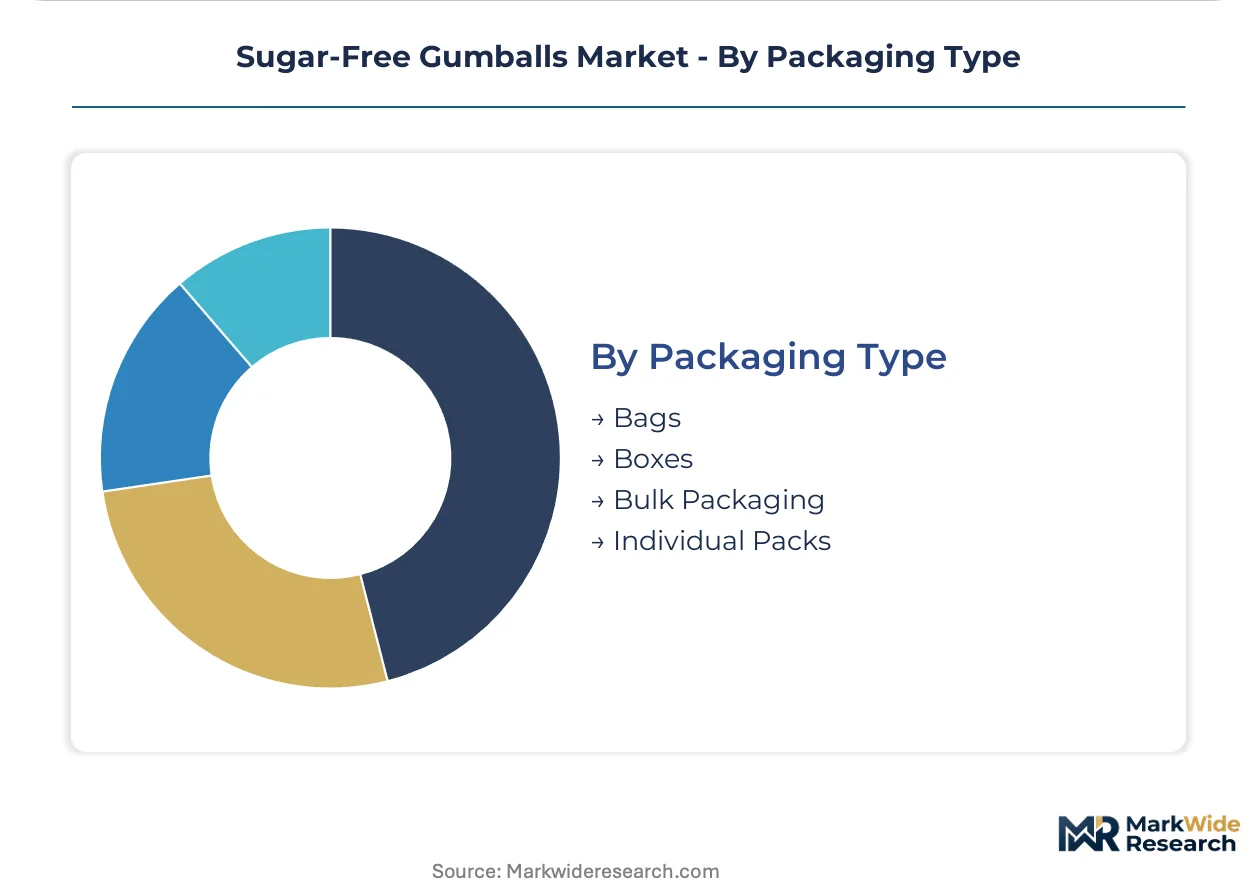
- Individual Packs:Single-serve blister and stick-pack configurations satisfy pharmacy and vending-channel hygiene requirements. Japanese convenience operators prioritize these formats for urban transit-hub retail where consumption occasion fragmentation drives miniaturization.
- Bulk Packaging:Jar and multi-pound configurations serve food-service and institutional procurement with lowest per-ounce cost.
- Bags:Flexible resealable formats balance portion flexibility with shelf-life protection in supermarket channels.
- Boxes:Rigid secondary packaging supports gift-set and premium positioning in seasonal retail.
Traditional procurement favors Bulk Packaging. Format innovation is gaining share fastest in Individual Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai Free Trade Zone incentives concentrate sugar-free confectionery R&D facilities for Asia-Pacific market access. German pharmacy chains anchor European demand for xylitol-functional formats. Japanese vending-machine operators drive single-serve packaging innovation.
United States
FDA polyol disclosure mandates force packaging redesign cycles across domestic sugar-free gumball portfolios. Convenience-store checkout zones in Chicago and Los Angeles prioritize individually wrapped functional formats for impulse procurement. Dental-clinic dispensing in Boston and Minneapolis adopts xylitol variants for pediatric caries-prevention protocols.
Germany
EFSA xylitol health-claim frameworks compress marketing latitude in pharmacy channels. Munich and Hamburg pharmacy chains stock EFSA-aligned dental-benefit SKUs as clinician-endorsed confectionery alternatives. Clean-label stevia formulations command shelf-space premiums in Berlin health-channel retail.
Japan
Urban transit-hub vending operators in Tokyo and Osaka reallocate checkout-zone space toward individually wrapped functional gumballs. METI standards govern food-contact materials in automated retail channels. Nagoya manufacturing clusters supply enzymatically modified stevia systems for regional formulation needs.
India
BIS sweetener purity thresholds constrain import clearance timelines for polyol-based formulations. Mumbai and Delhi-NCR pharmacy retailers stock diabetic-compliant variants alongside glucose-monitoring supplies. Gujarat processing facilities concentrate xylitol feedstock refining for domestic formulation use.
South Korea
MFDS labeling mandates shape portion-control packaging requirements for sugar-alcohol confectionery. Seoul convenience operators favor single-serve blister packs for hygiene assurance in high-traffic locations. Busan-Ulsan industrial zones supply modified pan-coating equipment for clean-label natural sweetener production.
Sugar-Free Gumballs Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered channel access. Market structure shows moderate consolidation with multinational CPG groups controlling pharmacy and supermarket shelf space while regional specialists capture vending-machine margins. Two strategic archetypes dominate: scale-driven portfolio conglomerates leveraging retail relationships, and sweetener-technology specialists controlling upstream polyol supply. Competitive moves center on pharmacy-chain exclusive SKU development and enzymatic sweetener licensing partnerships.
Within the diversified conglomerate tier, Perfetti Van Melle and Wrigley Company exemplify channel-dominance strategies through pharmacy and convenience-store partnerships. Mondelez International occupies a position emphasizing flavor-innovation velocity across retail formats. Lotte represents the supply-chain-anchored archetype through Northeast Asian sugar-alcohol sourcing relationships. These three players illustrate divergent paths to margin defense: retail shelf-space capture, product-development cadence, and upstream feedstock control.
| Leading Market Players |
|---|
| Perfetti Van Melle |
| Wrigley Company |
| Mondelez International |
| Lotte |
| The Hershey Company |
| Mars Incorporated |
| Cadbury Trebor Bassett |
| Dubble Bubble |
| Roquette |
| Others |
Value Network & Pricing Analysis
Captive xylitol sourcing from Chinese and Finnish birch-processing facilities anchors both supply security and premium pricing power for functional gumball portfolios. This upstream control insulates EFSA-aligned dental-benefit SKUs from polyol price volatility while compressing margins for spot-market-dependent competitors.
Pricing Analysis
Short-lead-time premiums command shelf-space allocation in German pharmacy chains where clinician endorsement protocols require rapid SKU replenishment. Three-tier pricing structure across premium, standard, and economy levels stratifies by sweetener certification grade and EFSA health-claim alignment. Price differentiation stems from xylitol purity tiers and enzymatic stevia glycoside sourcing. Cost compression in chemical sweetener tiers is intensifying because of sorbitol oversupply from expanded Chinese capacity. Pediatric dental protocols exhibit lowest price sensitivity; vending-machine impulse buyers show highest elasticity.
Supply Chain Analysis
Xylitol feedstock supply rests on Chinese corn-cob processing clusters and Finnish birch-refining facilities with limited alternative sourcing. Birch bark and corn-cob extraction form the primary raw material dependencies alongside enzymatically modified stevia glycosides from Nagoya manufacturing clusters. Single-source vulnerability concentrates in Finnish winter harvest disruptions and Chinese environmental regulation enforcement. Distribution runs through pharmacy-chain direct accounts, vending-machine operator networks, and convenience-store wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as players pursue captive control over xylitol feedstock and enzymatic stevia glycoside production to defend margin pools.
For Market Incumbents: Deepen pharmacy-chain exclusive SKU development with EFSA-aligned dental-benefit messaging to lock clinician endorsement protocols against functional mint substitution. Secure long-term offtake agreements with Finnish and Chinese xylitol refiners to insulate formulations from feedstock price swings. Add pan-coating capacity in Busan-Ulsan industrial zones to capture clean-label natural sweetener demand.
For New Entrants and Emerging Players: Enter via pediatric dental protocols in US school-based preventive care programs where texture-engineered child-appropriate formulations remain underpenetrated. Target biodegradable gum-base innovation partnerships with enzymatic degradation chemistry specialists to unlock sustainability-positioned landfill-diversion claims. Deploy direct-to-clinic sampling programs bypassing retail shelf-space barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified confectionery conglomerates seeking pharmacy-channel access and xylitol supply-chain control. Sweetener-technology specialists with enzymatic stevia glycoside patents and EFSA clinical-submission capabilities offer strongest long-term viability through the projection horizon. Watch for FDA polyol disclosure mandate enforcement tightening as the inflection signal triggering packaging redesign cycle demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy-Chain Exclusive SKU Development | Locks clinician endorsement protocols in Munich and Hamburg pharmacy networks against functional mint competitors. |
| Enzymatic Stevia Glycoside Licensing Partnership | Compresses performance gap with synthetic polyols while satisfying clean-label preferences in Berlin health-channel retail. |
| Biodegradable Gum-Base R&D Investment | Opens landfill-diversion claims for sustainability-positioned brands targeting EU Green Deal alignment. |
| Xylitol Feedstock Backward Integration | Captures upstream margin pools in Finnish birch-processing and Chinese corn-cob refining facilities. |
| Single-Serve Blister Pack Format Expansion | Captures premium per-unit pricing in Tokyo and Osaka urban transit-hub vending channels. |
Research Methodology
Trade databases, regulatory filing repositories, and pharmaceutical procurement records formed the secondary backbone of this analysis. Primary interviews with dental-clinic procurement managers, pharmacy-chain category buyers, sugar-alcohol refinery operations directors, and vending-machine channel operators combined with secondary validation across BIS import-clearance documentation, EFSA health-claim submissions, and FDA nutrition-labeling guidance. Bottom-up SKU-level volume aggregation and top-down macroeconomic factor calibration enabled triangulation.
Historical trendline analysis tracked segment-level growth trajectories across sweetener chemistry, distribution channel, end-user demographic, and packaging format dimensions over the projection horizon. CAGRs derived from regression-based modeling incorporating polyol price indices, pharmacy-channel expansion rates, and vending-machine installation growth. Industry-specific inputs included EFSA clinical-submission timelines, BIS third-party assay documentation cycles, and METI food-contact material compliance costs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden xylitol feedstock disruption or accelerated FDA enforcement timelines. Forecasts reflect documented assumptions regarding regulatory approval continuity and supply-chain logistics stability. A small set of named triggers warrants ongoing watch: EFSA MDR-level evidence standard tightening, Chinese environmental regulation enforcement spikes, and enzymatic stevia glycoside patent expiration schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Infused Fruits Jellies Market
Confectionery
Macarons Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Chocolate Spread Market
Confectionery
Ice Cream Coating Market
Confectionery
Crunchy Chocolate Market
Confectionery
Europe Dark Chocolate Market
Confectionery
Asia-Pacific Confectionery Market
Confectionery
Salted Caramel Products Market
Confectionery
South America Confectionery Market
Confectionery
Black Treacle Market
Confectionery
Japan Chocolate Market
Confectionery
Diet Candy Market
Confectionery
Sugarless Chocolate Market
Confectionery
Dark Chocolate Market
Confectionery
Confectionery Fillings Market