
 Dark Chocolate Market | 2026-2036
Dark Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Dark Chocolate Market Intelligence
Foodservice demand is hardening as bakeries and high-end restaurants expand dark chocolate applications beyond traditional confectionery. Barry Callebaut leverages its integrated cocoa processing network to secure bean supply across West African origins. Lindt & Sprüngli sustains premium positioning through controlled retail channels and flagship manufacturing in Switzerland. Mondelez International competes across mass-market and premium tiers with distributed production footprints.
Dark chocolate contains cocoa solids above fifty percent, with the balance composed of cocoa butter, sugar, and minimal emulsifiers, produced through conching and tempering processes that develop flavor complexity and stable crystalline structure for industrial and artisanal use. Organic and single origin varieties command premium shelf space as consumers prioritize traceability and terroir-specific flavor profiles. Conventional segments still dominate volume but face margin compression from volatile cocoa futures and escalating input costs. Bars and chips lead form-based demand, though coatings are gaining traction in bakery and ice cream manufacturing for clean-label applications.
EFSA cadmium thresholds and EU Green Deal due diligence rules are reshaping sourcing requirements, forcing processors to map supply chains and test soil-heavy-metal levels in Latin American and African growing regions. FDA standards in the United States govern labeling and allergen declarations, while ISO 22000 certification increasingly gates access to retail and foodservice procurement channels. Stakeholders must monitor evolving heavy-metal standards and carbon-footprint disclosure mandates to preserve market access and premium pricing power.
Market Dynamics
EFSA cadmium thresholds and EU Green Deal due diligence rules are forcing processors to remap West African and Latin American supply chains, testing soil-heavy-metal levels and renegotiating bean contracts to preserve European market access.
Growth Catalysts
- Foodservice channel expansion:Artisan bakeries and high-end restaurants in Belgium and Switzerland are incorporating dark chocolate into plated desserts and viennoiserie, creating pull-through for couverture-grade products with elevated cocoa solids.
- REACH-aligned traceability mandates:EU processors are investing in blockchain-backed provenance systems to satisfy retailer due diligence requirements, accelerating adoption of single-origin sourcing protocols that command shelf-space premiums.
- Clean-label coating applications:Ice cream manufacturers are reformulating compound coatings to high-cocoa-butter dark chocolate bases, eliminating hydrogenated oils and tapping parent-brand health positioning.
Market Restraints
- Cocoa futures volatility:London and New York exchange prices for fermented beans swing on West African harvest estimates, compressing margins for processors without backward integration into grinding operations.
- Soil-heavy-metal concentration:Volcanic-soil growing regions in Ecuador and Peru exhibit naturally elevated cadmium uptake, forcing costly lot segregation and blending strategies to meet EFSA thresholds.
- Substitution by carob and malt extracts:Mass-market confectioners facing input-cost pressure are reformulating with cocoa extenders in compound applications, particularly in price-sensitive Eastern European retail channels.
Strategic Opportunities
- Swissmedic-aligned functional positioning:Swiss processors can leverage the country's pharmaceutical-grade manufacturing reputation to develop cocoa-flavanol supplements and cosmeceutical applications with verified polyphenol content.
- Direct-to-consumer subscription channels:Bean-to-bar makers in Brooklyn and Copenhagen are bypassing retail slotting fees through monthly tasting clubs, capturing full margin and building terroir literacy among enthusiasts.
- EU Green Deal carbon-footprint labeling:Early adopters of lifecycle-assessment disclosure are securing preferred-supplier status with Nordic retail banners that have mandated scope-three emissions reporting by 2027.
Industry Challenges
- Conching technician scarcity:The bean-to-bar revival has outpaced vocational training programs in Germany and Austria, creating bidding wars for operators who can manage longitudinal flavor development across origin lots.
- ISO 22000 certification backlog:African cooperatives seeking European retail access face 18-month queue times at accredited bodies, delaying revenue recognition and forcing bridge financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dark Chocolate Market |
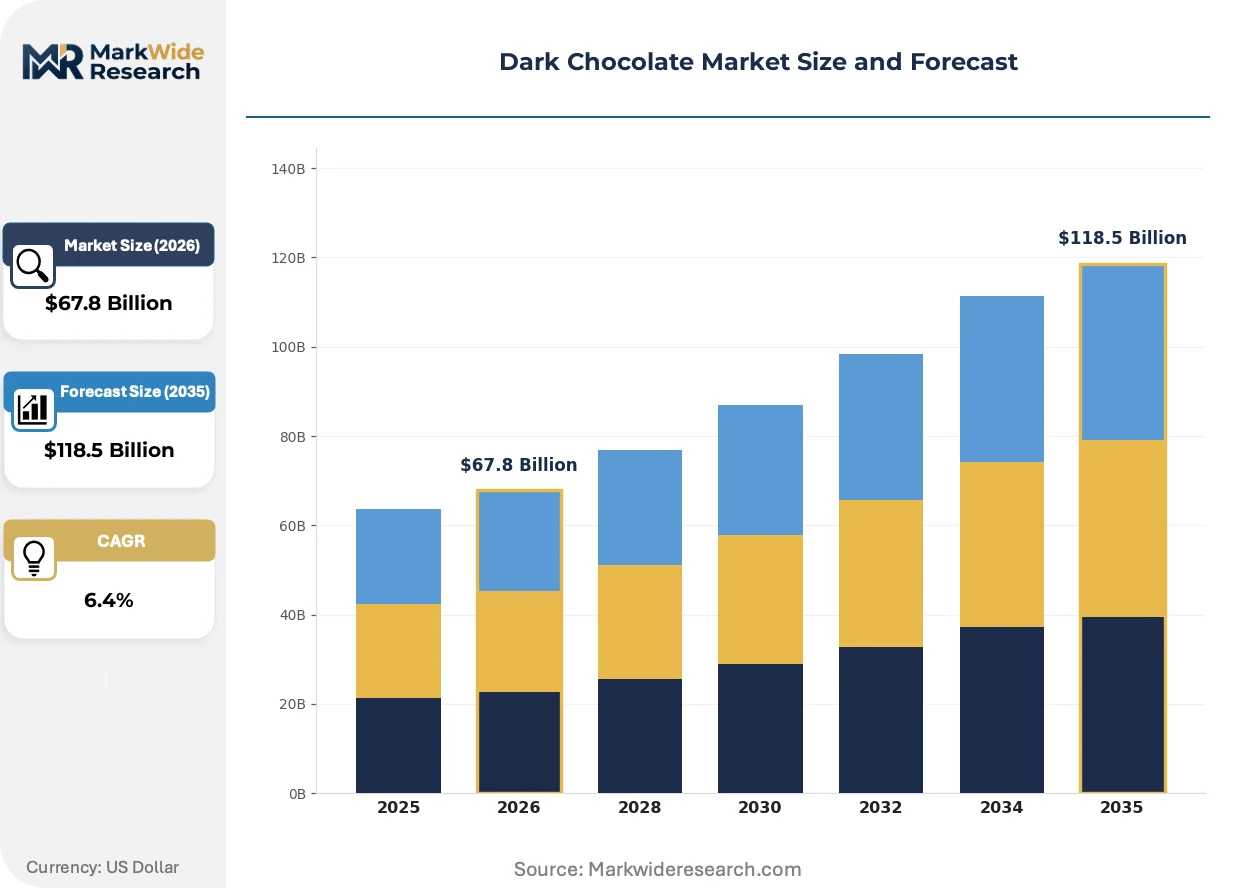
| Market Size in 2026 | $67.8 Billion |
| Market Size in 2035 | $118.5 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Sugar-Free, Single Origin Form: Bars, Chips, Coatings, Powder End User: Retail Consumers, Bakeries, Foodservice, Confectioneries Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Mars, Incorporated, Ferrero Group, Barry Callebaut, Lindt & Sprüngli, The Hershey Company, Cargill, Mondelez International, Ghirardelli Chocolate Company, Nestlé SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dark Chocolate Market Strategic Shifts & Innovations
Processing technology and sourcing protocols are converging to address heavy-metal compliance while preserving the flavor complexity that defines premium positioning. These developments are reshaping capital allocation and competitive differentiation.
Precision fermentation of cocoa butter alternatives is integrating into industrial chocolate formulations. Large confectioners in the Netherlands are piloting microbial-derived lipids to reduce exposure to volatile cocoa butter futures. This technology is integrating cost predictability with clean-label claims, though flavor-matching remains incomplete for high-percentage dark applications.
EFSA's 2023 revised cadmium exposure assessment has tightened maximum levels for cocoa powders and dark chocolate categories. Swiss and Belgian processors are now requiring pre-harvest soil testing from Ecuadorian and Peruvian cooperatives as a contract condition. Mid-tier manufacturers without origin-country technical assistance partnerships are facing exclusion from Carrefour and Albert Heijn supply bases.
Connoisseur buyers are rotating toward harvest-date-specific releases rather than standardized year-round SKUs. Specialty retailers in Paris and Tokyo are merchandising limited lots with provenance storytelling that emphasizes post-harvest processing variations. This pattern concentrates volume with makers who control fermentation and drying infrastructure rather than those sourcing commodity-grade liquor.
Dark Chocolate Market Segmentation
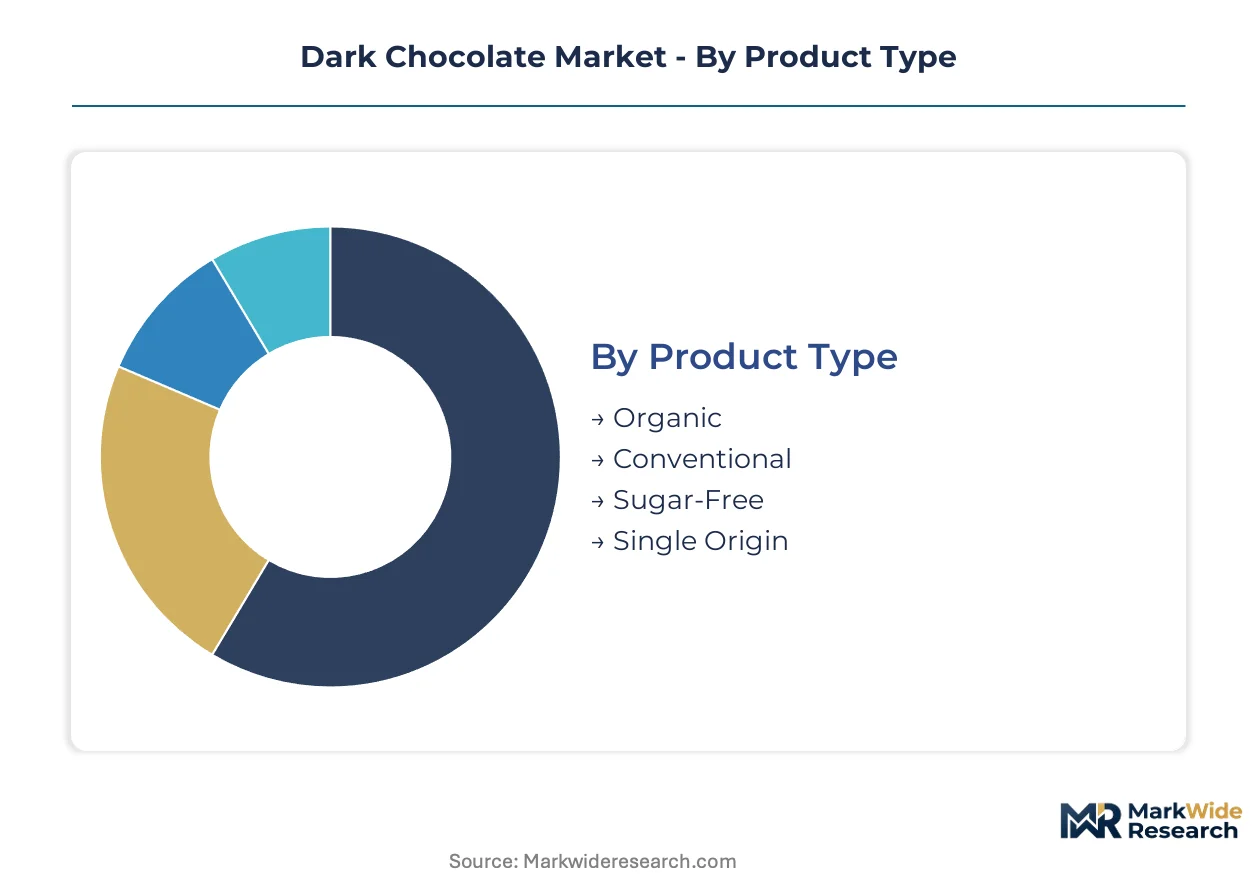
Dark chocolate segmentation reveals divergent margin profiles across purity tiers and application formats. Bean-to-bar makers capture premium positioning through origin-controlled supply chains, while industrial processors optimize for scale in compound and coating applications.
Product Type:
Standalone consumption segments command direct retail premiums, while embedded varieties integrate into foodservice and manufacturing workflows with specification-driven procurement.
- Organic:Certified cocoa grown without synthetic pesticides or fertilizers, with full traceability documentation required for EU organic labeling. Demand concentrates in German and French specialty retail channels where consumers pay premiums for soil-health verification and cooperative sourcing transparency.
- Single Origin:Chocolate produced from beans of one geographic region, preserving terroir-specific flavor profiles through controlled fermentation protocols. Belgian and Swiss artisan makers dominate this tier, leveraging direct relationships with Ecuadorian and Peruvian cooperatives to secure harvest-specific lots with documented cadmium testing.
- Conventional:Blended-origin chocolate using commodity-grade cocoa liquor from West African processors, optimized for cost efficiency in mass-market applications.
- Sugar-Free:Formulations replacing sucrose with maltitol, erythritol, or stevia extracts, targeting diabetic and ketogenic diet segments through pharmacy and health-food retail placement.
Volume placements concentrate in Conventional; the faster expansion belongs to Single Origin.
Form:
Physical format determines equipment compatibility and melting behavior, with foodservice buyers prioritizing tempering stability over shelf aesthetics.
- Bars:Finished consumer products with defined snap and gloss characteristics, ranging from artisan tablets to molded single-serve portions. Swiss and Belgian flagship stores drive premium bar demand through controlled retail environments that emphasize provenance storytelling and vintage-dated releases.
- Chips:Calibrated drops designed for baking applications, with stable cocoa butter crystallization preventing bloom during oven exposure. Artisan bakeries in Copenhagen and Brooklyn specify chip size and cocoa percentage for viennoiserie and cookie applications, creating pull-through for couverture-grade supply.
- Coatings:High-cocoa-butter formulations for enrobing and dipping, requiring precise viscosity control for industrial production lines.
- Powder:Defatted cocoa solids for beverage and dairy applications, with alkalization levels adjusted for color and solubility specifications.
Industrial procurement favors Coatings for operational flexibility; Powder is climbing the fastest among ingredient formats.
End User:
Customer type segmentation separates direct consumption from transformation economics, with margin capture varying sharply across value-chain position.
- Retail Consumers:Individual purchasers selecting finished chocolate through grocery, specialty, or direct channels, with decision criteria weighted toward ethical certification and flavor intensity. Swiss and Belgian domestic markets sustain the highest per-capita dark chocolate consumption, with local consumers demonstrating willingness to pay for bean-to-bar provenance.
- Foodservice:Restaurants and hotels incorporating dark chocolate into plated desserts and tasting menus, requiring consistent tempering behavior and reliable supply for menu planning. Parisian and Tokyo fine-dining establishments specify harvest-date chocolate for limited-menu items, creating demand for small-batch production with documented post-harvest processing.
- Bakeries:Artisan and industrial producers using chocolate as ingredient or decoration in viennoiserie, pastry, and bread applications.
- Confectioneries:Manufacturers of filled chocolates, pralines, and enrobed products, balancing cocoa percentage with shelf-life requirements and machinery compatibility.
Shipment volumes skew toward Retail Consumers; Foodservice is gaining share fastest as experiential dining recovers.
Distribution Channel:
Channel structure determines margin retention and brand control, with direct formats capturing full value at the cost of customer acquisition investment.
- Specialty Stores:Curated retail environments emphasizing origin storytelling and staff expertise, common in Swiss and Belgian city centers. These channels sustain premium pricing through sensory sampling and educational engagement that justifies price multiples over mass retail.
- Online:Direct-to-consumer platforms and subscription services enabling bean-to-bar makers to bypass slotting fees and capture customer data. Brooklyn and Copenhagen producers leverage monthly tasting clubs to build terroir literacy and secure recurring revenue without retail intermediaries.
- Supermarkets:Mass retail placement requiring promotional investment and standardized packaging for shelf-ready logistics.
- Wholesale:Bulk supply to food manufacturers and foodservice distributors, with pricing indexed to cocoa futures and contract volumes.
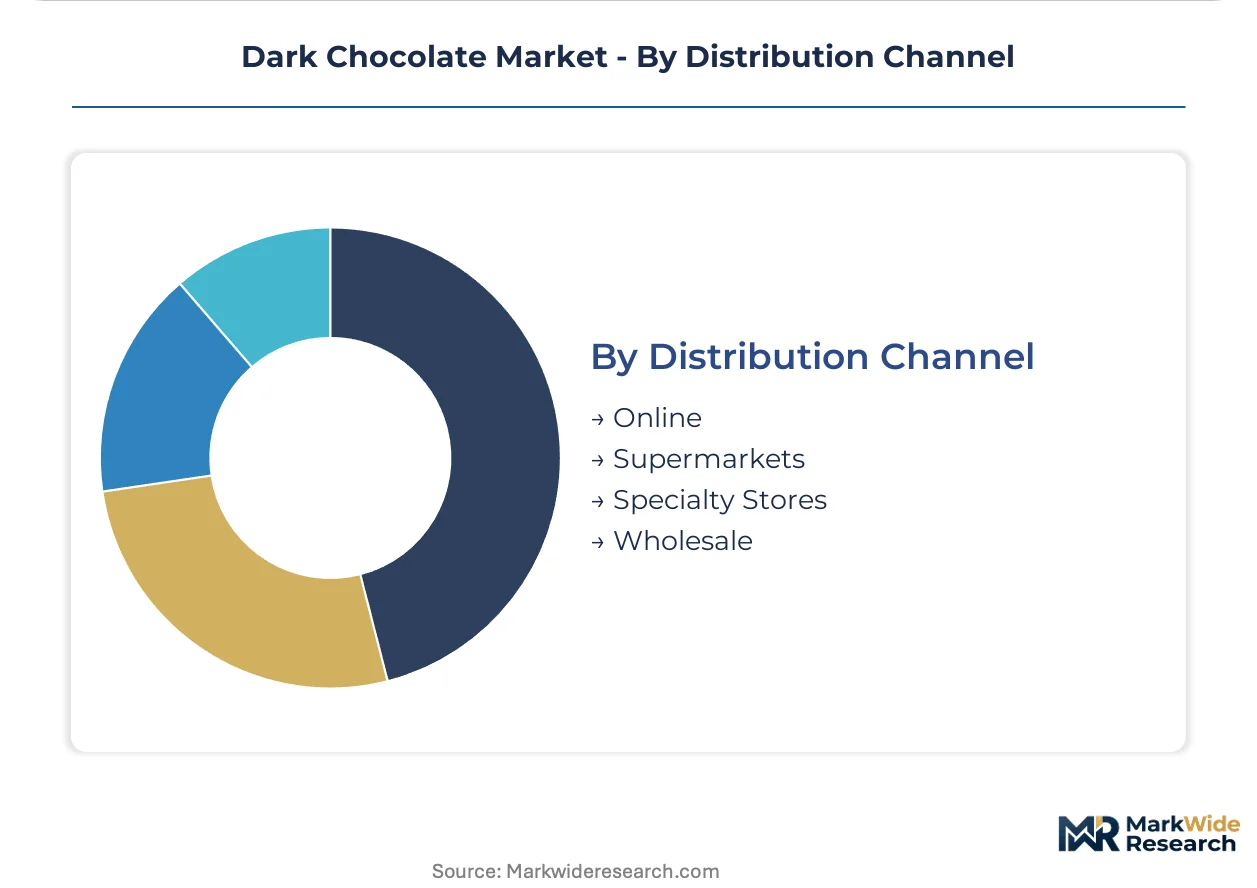
Transaction volume concentrates in Supermarkets; Online shows the steepest expansion trajectory among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in West African and Latin American growing regions, while consumption gravity sits in Western European processing hubs and North American retail channels. This geographic split shapes logistics costs, regulatory exposure, and margin capture across the value chain.
Switzerland
Swiss consumers sustain the highest per-capita dark chocolate consumption globally, with domestic demand pulling couverture-grade supply through controlled retail channels. Swissmedic's pharmaceutical-grade manufacturing standards enable functional cocoa-flavanol positioning for cosmeutical applications. The Zurich-Geneva corridor hosts flagship manufacturing facilities where bean-to-bar makers control fermentation and drying infrastructure for harvest-date-specific releases.
Belgium
Belgian artisan chocolatiers anchor premium positioning through direct relationships with Ecuadorian and Peruvian cooperatives, securing documented cadmium-tested lots. EFSA's revised cadmium exposure assessment has tightened maximum levels, compelling Brussels-based processors to require pre-harvest soil testing as contract conditions. The Flanders region concentrates industrial grinding capacity that supplies foodservice channels across Northern Europe.
United States
American foodservice demand is hardening as Brooklyn and Copenhagen-style bean-to-bar makers expand direct-to-consumer subscription channels, bypassing retail slotting fees. FDA standards govern labeling and allergen declarations, while ISO 22000 certification gates access to procurement channels. The Brooklyn artisan cluster exemplifies terroir-literacy building through monthly tasting clubs that capture full margin.
Germany
German specialty retail channels concentrate demand for organic-certified dark chocolate with full traceability documentation required for EU organic labeling. REACH-aligned traceability mandates are accelerating blockchain-backed provenance system adoption among processors serving Carrefour and Albert Heijn supply bases. The Cologne-Düsseldorf industrial corridor hosts vocational training programs that are struggling to keep pace with conching technician demand.
France
French fine-dining establishments in Paris specify harvest-date chocolate for limited-menu items, creating pull-through for small-batch production with documented post-harvest processing. EFSA cadmium thresholds are reshaping sourcing requirements for processors mapping Latin American supply chains. The Île-de-France region anchors specialty retail merchandising of limited lots with provenance storytelling emphasizing processing variations.
Dark Chocolate Market Key Industry Players
Top-tier vendors anchor integrated cocoa processing networks, while mid-tier bean-to-bar specialists occupy premium niche positions. The competitive set fragments across three archetypes: mass-market confectioners with distributed production footprints, Swiss and Belgian artisan makers with controlled retail channels, and industrial processors with backward integration into grinding operations. Dominant competitive moves include strategic partnerships with Ecuadorian and Peruvian cooperatives for cadmium-compliant supply, and portfolio diversification into functional cocoa-flavanol applications.
Within the integrated-processor tier, Barry Callebaut exemplifies scale-driven supply security across West African origins, while Lindt & Sprüngli occupies the premium-tier position through Swiss-controlled retail channels and flagship manufacturing. Mondelez International represents the mass-market and premium dual-tier strategy with distributed production footprints. These three anchors illustrate how competitive positioning diverges across integration depth, geographic concentration, and channel control.
| Leading Market Players |
|---|
| Mars, Incorporated |
| Ferrero Group |
| Barry Callebaut |
| Lindt & Sprüngli |
| The Hershey Company |
| Cargill |
| Mondelez International |
| Ghirardelli Chocolate Company |
| Nestlé SA |
| Others |
Cost & Logistics Intelligence
Cocoa butter futures volatility transmits through grinding margins to finished chocolate pricing tiers, with West African harvest uncertainty compressing processor spreads and forcing tiered pricing stratification across premium couverture, standard industrial, and economy compound grades.
Pricing Analysis
Margin tightening in mid-tier industrial chocolate reflects cocoa futures swings on London and New York exchanges, with backward-integrated processors capturing spread stability that commodity buyers forfeit. Three-tier pricing structure across premium, standard, and economy levels separates bean-to-bar artisan products from mass-market bars and compound coatings. Price differentiation hinges on certification grade—ISO 22000 and organic seals command shelf-space premiums—and volume scale, with foodservice contract buyers extracting logistical discounts. Cost-down pressure on economy compound tiers accelerates because carob and malt extract substitution threatens volume retention in Eastern European retail channels. Bakeries and artisan chocolatiers demonstrate lowest price sensitivity; mass-market confectioners facing input-cost pressure exhibit highest.
Supply Chain Analysis
Returns and lot rejection flows from EFSA cadmium testing reshape procurement protocols, with non-compliant Ecuadorian and Peruvian shipments diverted to less regulated markets or destroyed. Supply concentrates in Côte d'Ivoire, Ghana, and Ecuador for bean origins, with Belgian and Swiss grinding capacity dominating European processing. Raw material dependencies rest on fermented cocoa beans, cocoa butter, and lecithin emulsifiers. Single-source vulnerability in West African harvests—where political instability and climate variability threaten output—creates structural exposure for processors without diversified origin portfolios. Distribution runs through integrated processor networks supplying retail, foodservice, and industrial channels with specification-matched products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over fermentation infrastructure and downstream capture of direct-to-consumer channels determine margin retention against commodity volatility.
For Market Incumbents: Deploy blockchain-backed provenance systems to satisfy EFSA and EU Green Deal traceability mandates, insulating Carrefour and Albert Heijn supply relationships from exclusion risk. Deepen upstream control over Ecuadorian and Peruvian cooperative drying infrastructure to secure cadmium-compliant harvest lots before competitors. Carob and malt extract substitution in Eastern European mass market represents immediate volume threat requiring premium-tier brand extension to offset. For New Entrants and Emerging Players: Begin with direct-to-consumer subscription channels in Brooklyn and Copenhagen, bypassing retail slotting fees while building terroir literacy that justifies price premiums. Target foodservice plating applications in Paris and Tokyo fine-dining establishments, where harvest-date specificity commands menu placement unavailable to standardized year-round SKUs. Bean-to-bar positioning with documented post-harvest processing variations offers clearest white-space entry angle. For Investors and Strategic Acquirers: ISO 22000 certification queue times extending eighteen months for African cooperatives is the leading indicator that bridge financing and technical assistance partnerships will capture preferred-supplier status with European retail banners. Five-to-ten year viability favors processors with backward integration into grinding operations and origin-country soil-testing capabilities. Acquisition target archetype: mid-tier bean-to-bar makers controlling fermentation infrastructure in Latin America with underdeveloped European distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Implementation | EFSA traceability mandates gate Carrefour and Albert Heijn procurement access for compliant processors. |
| Direct-to-Consumer Subscription Launch | Brooklyn and Copenhagen makers capture full margin while bypassing retail intermediary slotting fees. |
| Fermentation Infrastructure Control | Origin-country drying and fermentation ownership secures harvest-date-specific releases for premium positioning. |
| Functional Cocoa-Flavanol Extension | Swissmedic pharmaceutical-grade standards enable verified polyphenol supplements and cosmeceutical applications. |
| Cadmium-Compliant Sourcing Partnership | Pre-harvest soil testing contracts with Ecuadorian and Peruvian cooperatives preserve European market access under tightened EFSA thresholds. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across cocoa processors, artisan chocolatiers, foodservice procurement directors, and retail category buyers. Secondary validation drew from EFSA exposure assessments, EU Green Deal due diligence guidance, FDA labeling standards, and ISO 22000 certification body disclosures. Bottom-up volume modeling across product types, forms, and end users triangulated against top-down cocoa grindings data and regional consumption estimates.
Granularity-level modeling operated at purity-tier and application-format resolution, with organic, single-origin, conventional, and sugar-free categories tracked separately across bars, chips, coatings, and powder forms. End-user segmentation captured retail consumer, foodservice, bakery, and confectionery demand patterns across the analysis window. CAGRs derived from trend extrapolation of cocoa butter futures correlation, foodservice channel recovery trajectories, and regulatory compliance cost absorption rates. Forecast inputs included EFSA cadmium threshold enforcement timelines and EU Green Deal scope-three emissions disclosure mandates.
Underlying measurement precision varies by segment; single-origin and organic categories carry tighter precision than conventional volume placements due to cooperative-level traceability documentation. Forecasts reflect documented assumptions regarding cocoa harvest stability, regulatory enforcement intensity, and foodservice recovery pace. Material deviation in West African political conditions, EFSA threshold revisions, or precision-fermentation technology maturation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
North America Sugar Confectionery Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market
Confectionery
Confectionery Fillings Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
South Africa Confectionery Market
Confectionery
Salted Caramel Products Market
Confectionery
South Korea Chocolate Market
Confectionery
Global Chocolate Market
Confectionery
Chocolate Spread Market
Confectionery
Fat Free Candy Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Confectionery Coating Market
Confectionery
Global Compound Chocolate Market
Confectionery
North America Confectionery Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Caramel Market