
 Chocolate Couverture Market | 2026-2036
Chocolate Couverture Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Couverture Market Analysis
EU Deforestation Regulation is rebalancing the cost-of-entry calculus for new couverture suppliers by mandating geolocated proof of origin for all cocoa bean shipments. Barry Callebaut AG leverages its vertically integrated African sourcing network to sustain compliance advantages at scale. Valrhona anchors its premium positioning through controlled-origin supply chains in Latin America and Madagascar. Lindt & Sprüngli competes on manufacturing scale across European and North American processing facilities.
Chocolate couverture denotes a high-cocoa-butter coating chocolate containing minimum 31 percent cocoa butter, engineered for tempering stability, fluid viscosity, and snap in finished confectionery applications. Dark couverture dominates industrial volume due to its functional versatility in enrobing and molding across artisan and mass-production settings. Milk couverture occupies the fastest-growing quality tier as bakeries upgrade formulations for caramel and praline applications. Premium grade commands the deepest margin pools, though organic and Fair Trade certifications now shape procurement decisions for European and North American buyers.
FDA standards for chocolate identity in the United States, EFSA purity criteria under EU food law, and ISO 2451 for cocoa bean grading collectively define product specifications and market access thresholds. EUDR traceability mandates now extend liability upstream to couverture manufacturers, reshaping supplier qualification protocols. Stakeholders must monitor evolving cocoa butter equivalence regulations and origin-verification technology investments to preserve supply continuity.
Market Dynamics
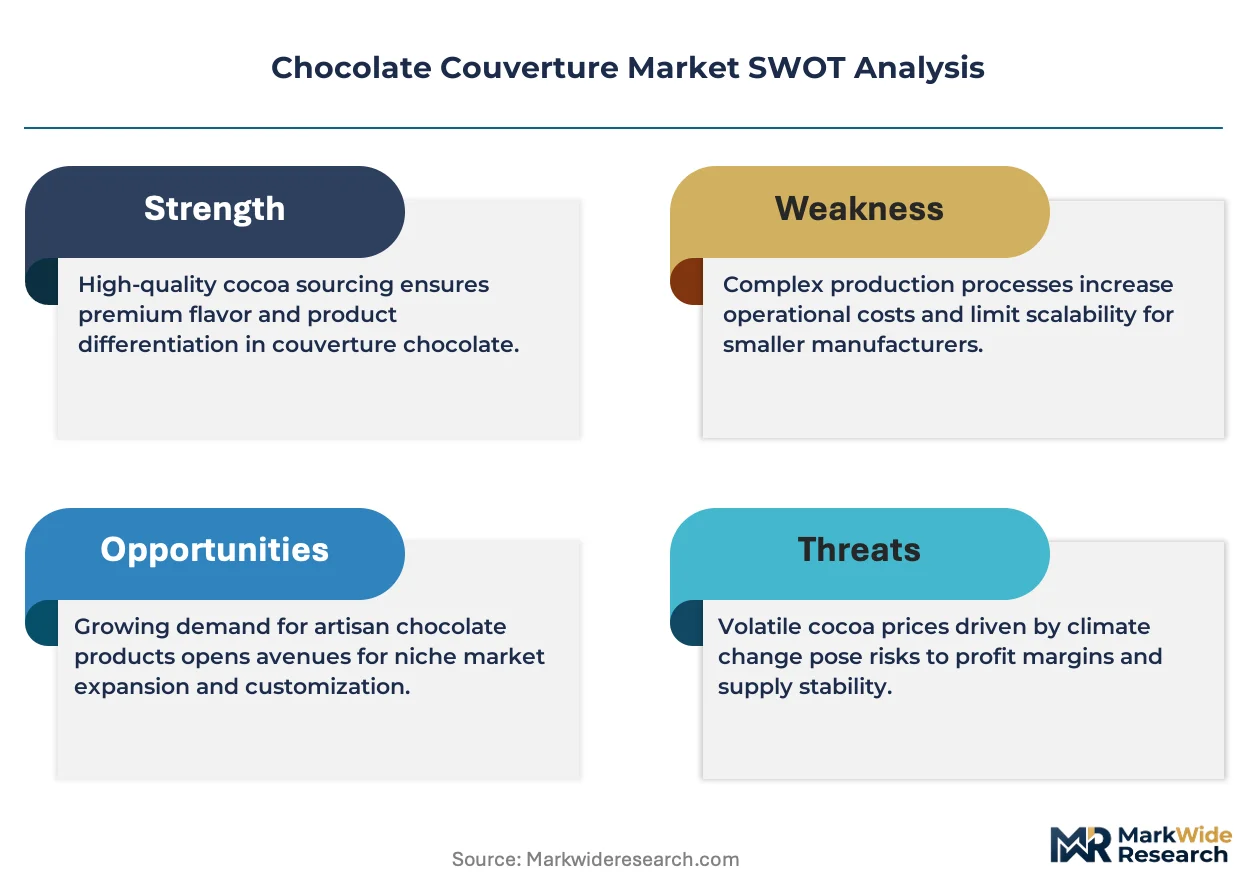
EU Deforestation Regulation (EUDR) traceability mandates are compressing supplier qualification timelines and forcing couverture manufacturers to deploy geolocation verification systems across West African and Latin American cocoa corridors. This regulatory pressure is restructuring sourcing relationships and capital allocation priorities.
Growth Catalysts
- EUDR Compliance Infrastructure:Mandatory geolocated proof-of-origin requirements for cocoa bean shipments are accelerating investments in blockchain-enabled traceability platforms among European processors.
- Artisan Bakery Specification Upgrades:Belgian and French craft bakeries now require minimum 35 percent cocoa butter content for enrobing applications, pulling premium-grade volume through specialized distribution channels.
- Cocoa Butter Equivalence Technology:Advanced enzymatic interesterification processes are expanding formulation flexibility for manufacturers seeking cost-optimized tempering stability in tropical climates.
Market Restraints
- Cocoa Butter Price Volatility:Cocoa butter futures on ICE exchange exhibit structural sensitivity to West African harvest disruptions, compressing margin predictability for mid-tier processors.
- Ivorian-Ghanaian Supply Concentration:Over 60 percent of global cocoa bean origination flows through Abidjan and Tema port infrastructure, creating single-point vulnerability for EUDR-compliant supply chains.
- Substitution Pressure from Compound Coatings:Vegetable fat-based alternatives achieve cost parity at 40-50 percent below couverture pricing, displacing volume in mass-market confectionery segments.
Strategic Opportunities
- Madagascar Origin Expansion:Criollo and Trinitario genetic stocks in Sambirano Valley offer untapped premium positioning for single-origin dark couverture targeting Japanese and Nordic markets.
- Direct-to-Artist Distribution Platforms:Digital procurement portals connecting Ecuadorian cooperatives directly with European chocolatiers bypass traditional four-tier commodity trading structures.
- EU Green Deal Carbon Border Adjustments:Anticipated CBAM extensions to processed agricultural goods will reward verified low-emission cocoa processing facilities with competitive access advantages.
Industry Challenges
- Master Chocolatier Talent Scarcity:European confectionery programs report insufficient graduation rates to fill tempering-specialist roles across industrial and artisan production lines.
- EUDR System Integration Complexity:Legacy ERP platforms at mid-scale processors require 18-24 month migration timelines to achieve real-time farm polygon geolocation data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Couverture Market |
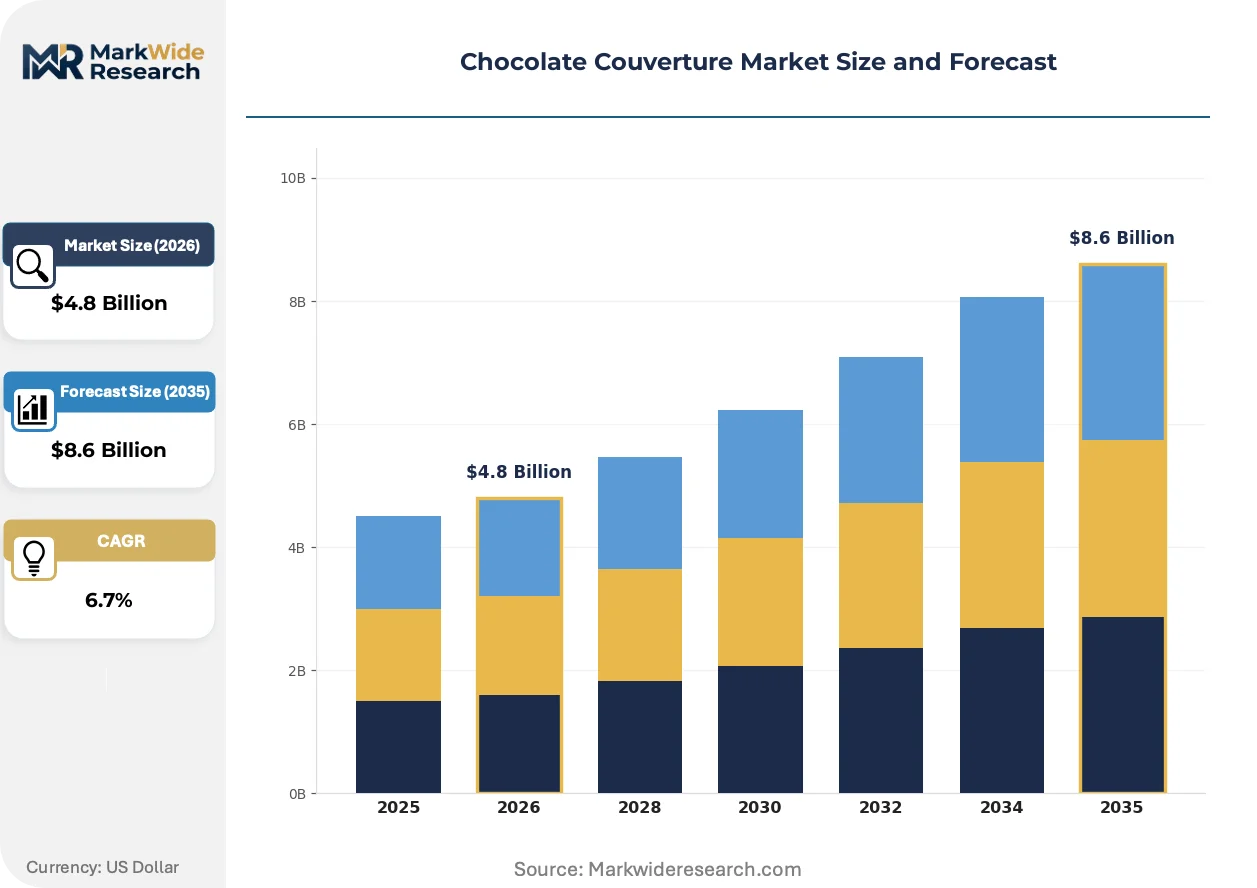
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Couverture, Milk Couverture, White Couverture, Ruby Couverture Form: Chips, Blocks, Buttons, Coatings End User: Restaurants, Bakeries, Confectioneries, Home Bakers Quality Grade: Premium, Standard, Organic, Fair Trade |
| Companies Covered | Barry Callebaut AG, Valrhona, Cocoa Processing Company Ltd., Scharffen Berger, ICAM, Max Felchlin AG, Guittard Chocolate Company, Struben Couverture Chocolate Factory, Lindt & Sprüngli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Couverture Market Emerging Trajectories
Precision fermentation-derived cocoa butter alternatives are entering commercial-scale production, threatening to bifurcate the market between botanical-extraction purists and biotechnology adopters. This technological inflection is redrawing R&D investment patterns and supplier partnership criteria.
Near-infrared spectroscopy is integrating into inline quality control systems at tempering lines, enabling real-time cocoa butter crystallization monitoring without destructive sampling. Industrial chocolate manufacturers in Belgium and Switzerland are deploying these sensors at 15-20 percent of new line installations. The technology is compressing batch rejection rates and reducing skilled operator dependency in high-throughput environments.
EU Deforestation Regulation due diligence obligations are extending liability upstream to couverture manufacturers for supplier non-compliance, effective across all 27 member states. Chocolate processors must now maintain polygon-mapped farm boundary data for 100 percent of cocoa volumes, with national competent authorities conducting risk-based inspections. Dark couverture categories face the steepest compliance burden given their higher cocoa mass content and corresponding origin verification surface area.
Buyer concentration among European industrial chocolate clusters is consolidating procurement decision-making into fewer technical specification teams. Belgium's Wieze processing hub and Italy's Perugina facilities now coordinate annual volume tenders through centralized category managers, displacing distributed purchasing authority. This pattern concentrates pricing leverage with buyers and compresses supplier negotiation cycles across the Benelux and Po Valley regions.
Chocolate Couverture Market Segmentation
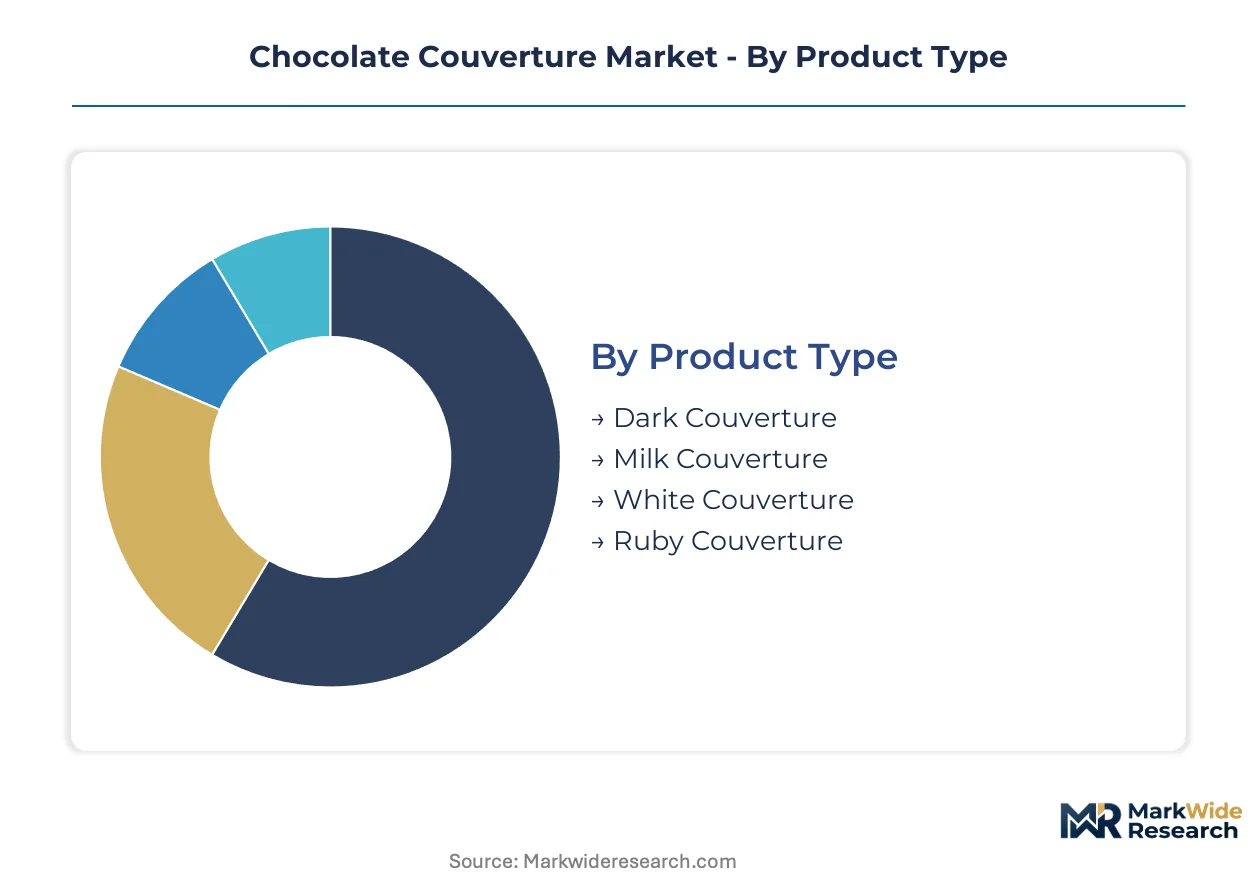
Chocolate couverture segmentation reflects divergent technical requirements across artisan and industrial processing environments. Product viscosity specifications, tempering protocols, and origin verification obligations vary sharply by end-use application and regulatory jurisdiction.
Product Type:
Dark couverture functions as a standalone tempering system requiring no dairy integration, while milk and white variants demand embedded fat-phase management for stability.
- Dark Couverture:Contains minimum 31 percent cocoa butter with cocoa mass as the sole fat source, engineered for snap and gloss in enrobing applications. Belgian industrial clusters around Wieze specify 35 percent cocoa butter minimums for artisan bakery contracts, pulling volume through specialized distribution channels. EUDR traceability mandates impose the steepest compliance burden here due to higher cocoa content requiring expanded origin verification.
- Milk Couverture:Incorporates milk solids and cocoa butter in balanced ratios for caramel and praline work. French craft bakeries are upgrading procurement specifications toward higher cocoa butter tiers, expanding the premium-grade addressable market for this category.
- White Couverture:Cocoa butter base without cocoa solids, dependent on milk powder and vanilla for flavor architecture. Swiss and Belgian processors dominate technical formulation standards.
- Ruby Couverture:Utilizes specific cocoa bean varieties to achieve natural pink coloration without added dyes. Japanese and Nordic markets show concentrated demand for this visual differentiation tier.
Volume placements concentrate in Dark Couverture; the faster expansion belongs to Milk Couverture.
Form:
Physical configuration determines melting kinetics and dosing precision across manual artisan versus automated industrial lines.
- Chips:Standardized callet geometry enables rapid volumetric dosing in tempering machines. Industrial chocolate manufacturers in Belgium deploy these formats at 15-20 percent of new line installations for reduced operator dependency.
- Blocks:Large-format ingots require manual portioning and extended melting cycles. Artisan chocolatiers in France and Italy prefer this form for small-batch control over crystallization profiles.
- Buttons:Intermediate sizing bridges artisan and semi-automated applications. German confectionery equipment suppliers optimize dosing systems for this geometry.
- Coatings:Pre-tempered liquid or semi-liquid formats eliminate crystallization management for end-users. North American bakery chains specify these for operational simplicity in high-throughput environments.
Industrial procurement favors Chips for throughput velocity; artisan channels sustain demand for Blocks.
End User:
Customer type segmentation maps directly to specification complexity and certification requirements.
- Restaurants:Dessert-focused establishments require versatile couverture for plating and molded components. Michelin-tier kitchens in France and Spain specify single-origin dark grades for menu differentiation.
- Bakeries:Artisan and industrial baking operations drive the fastest quality-tier upgrades. Belgian and French craft bakeries now mandate minimum 35 percent cocoa butter content for enrobing applications.
- Confectioneries:Dedicated chocolate manufacturers integrate couverture into praline, truffle, and bar production. This segment concentrates procurement volume through centralized category managers in Benelux industrial clusters.
- Home Bakers:Retail-packaged formats emphasize tempering simplicity and recipe guidance. E-commerce platforms in Germany and the United Kingdom are expanding direct-to-consumer distribution for this segment.
Confectioneries anchor procurement volume; Bakeries are climbing the fastest on specification upgrades.
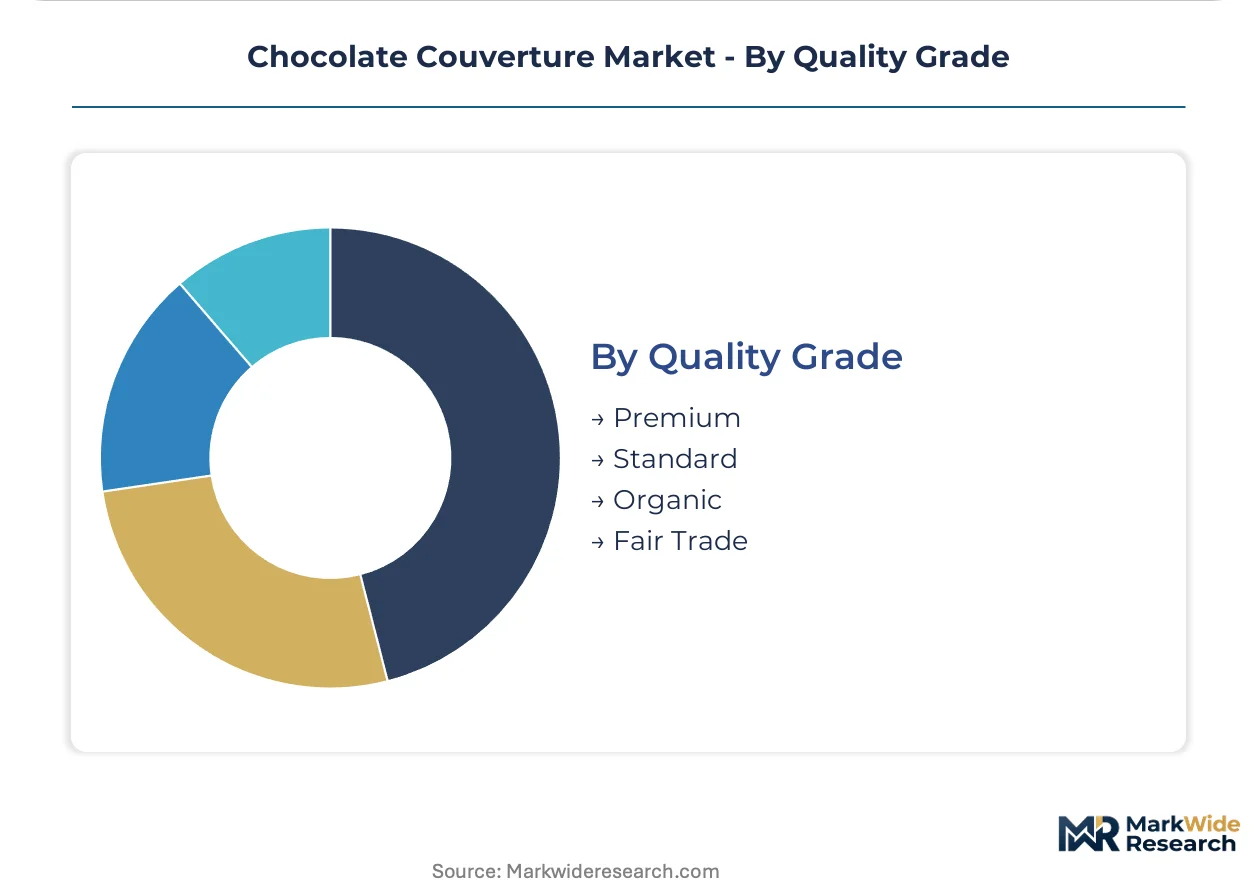
Quality Grade:
Certification tiers reshape supplier qualification protocols and margin structures across European and North American buyers.
- Premium:Defined by controlled-origin supply chains, specific genetic stocks, and batch-traceable processing. Valrhona's Latin American and Madagascar networks exemplify this positioning for Japanese and Nordic markets.
- Standard:Commodity-grade couverture meeting minimum cocoa butter thresholds without origin guarantees. Mid-tier processors face margin compression from cocoa butter futures volatility on ICE exchange.
- Organic:Certified cultivation excluding synthetic pesticides and fertilizers. EU organic regulation compliance adds 12-18 month supplier qualification timelines.
- Fair Trade:Price premium mechanisms guaranteeing minimum farmgate payments. EUDR traceability mandates now overlap with Fair Trade verification requirements, consolidating audit burdens.
Premium grade commands the deepest margin pools; Organic and Fair Trade certifications are gaining share fastest on procurement decision criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's Wieze industrial cluster operates as a tax-advantaged processing hub, concentrating European couverture manufacturing capacity and drawing supplier investment toward Flemish logistics corridors.
Belgium
Artisan bakeries in Brussels and Antwerp now specify minimum 35 percent cocoa butter content for enrobing contracts, upgrading procurement tiers across the premium segment. EUDR traceability mandates from the European Commission require geolocated farm polygon data for all cocoa shipments entering Belgian ports. The Wieze industrial cluster hosts concentrated tempering and molding capacity serving confectionery manufacturers across the Benelux region.
Switzerland
Swiss chocolatiers maintain specification leadership for white couverture formulations, driving technical standards for milk powder integration and vanilla profiling. The country's Federal Food Safety and Veterinary Office enforces purity criteria that exceed baseline EU requirements for cocoa butter content declarations. Zurich and Vevey processing facilities coordinate R&D investment patterns for precision tempering technologies.
France
Michelin-tier kitchens in Paris and Lyon anchor demand for single-origin dark couverture, creating premium pricing pools for Latin American and Madagascar genetic stocks. ANSM and DGCCRF enforce food contact material regulations that shape packaging specifications for artisan distribution channels. The Perugina-adjacent processing corridor in southeastern France coordinates volume tenders with Italian industrial clusters.
Germany
German confectionery equipment suppliers optimize dosing systems for button-format couverture, bridging artisan and semi-automated production lines. The Federal Ministry of Food and Agriculture implements EU organic regulation compliance timelines that extend supplier qualification periods by 12-18 months. Cologne and Hamburg distribution hubs manage bulk import flows for industrial bakery chains across Central Europe.
United States
North American bakery chains specify pre-tempered liquid couverture formats to eliminate crystallization management in high-throughput environments. FDA standards for chocolate identity define minimum cocoa butter thresholds that shape import qualification protocols. Guittard Chocolate Company and Scharffen Berger anchor West Coast processing capacity serving specialty food distributors.
Chocolate Couverture Market Vendor Landscape
Belgian and Swiss producers anchor the premium tier; West African processors and American craft specialists hold complementary positions. The vendor base concentrates around three strategic archetypes: vertically integrated bean-to-bar operators, industrial-scale tempering specialists, and origin-focused premium brands. Competitive dynamics center on EUDR compliance infrastructure deployment and direct-to-artist distribution platform development.
Within the integrated processor tier, Barry Callebaut AG exemplifies scale-driven African sourcing network control. Valrhona and Lindt & Sprüngli occupy positions defined by controlled-origin supply chain architecture and manufacturing footprint breadth. These three anchors represent divergent strategic postures toward traceability investment, premium positioning, and geographic market prioritization.
| Leading Market Players |
|---|
| Barry Callebaut AG |
| Valrhona |
| Cocoa Processing Company Ltd. |
| Scharffen Berger |
| ICAM |
| Max Felchlin AG |
| Guittard Chocolate Company |
| Struben Couverture Chocolate Factory |
| Lindt & Sprüngli |
| Others |
Supply Flow & Price Mechanics
Enzymatic interesterification of cocoa butter alternatives is compressing cost structures for tropical-climate formulations while simultaneously concentrating procurement leverage among Belgian and Swiss processors with captive technology access. This production-method transition rewards integrated manufacturers who internalize both enzymatic capacity and West African sourcing networks, tightening supply-side discipline across mid-tier competitors.
Pricing Analysis
Short lead-time premiums now dominate contract negotiations, with artisan bakeries paying marked-up rates for EUDR-compliant spot inventory while industrial confectioneries lock in discounted annual offtake through centralized Benelux tender processes. Three-tier pricing structure across premium, standard, and economy levels stratifies by cocoa butter percentage and origin verification depth. Cost compression in standard-grade tiers is intensifying because compound coatings achieve functional parity at substantially lower input costs. Industrial bakery chains exhibit the highest price sensitivity, while Michelin-tier kitchens absorb premiums for single-origin genetic stocks.
Supply Chain Analysis
Dual-sourcing mandates from European confectionery clusters now require qualified backup suppliers for all EUDR-verified cocoa volumes, extending qualification timelines and freezing out single-source operators. Geographic concentration centers on Côte d'Ivoire, Ghana, and Ecuador for bean origination, with Belgian and Swiss facilities dominating downstream tempering capacity. Raw material dependencies encompass cocoa butter futures, milk powder solids, and Madagascar vanilla extracts. Single-point vulnerability persists through Abidjan and Tema port infrastructure. Distribution runs through Flemish logistics corridors serving Benelux industrial clusters and Po Valley confectionery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master chocolatier talent scarcity across European training programs props pricing for technical labor, constraining capacity expansion regardless of capital availability. This supply-constrained dynamic favors incumbents with established apprenticeship pipelines and proprietary tempering expertise.
For Market Incumbents: Extend EUDR compliance infrastructure into predictive farm-polygon monitoring systems that preempt regulatory inspection failures. Deepen backward integration into Ivorian and Ghanaian cooperative networks to secure origin-verified bean flows before qualification timelines compress further. Channel control through direct-to-artist digital platforms defends margin position against commodity trader intermediation.
For New Entrants and Emerging Players: Begin with Madagascar single-origin positioning for Japanese and Nordic premium markets where Valrhona and Lindt & Sprüngli hold weaker distribution density. Target direct-to-artist procurement portals as the most penetrable channel, bypassing four-tier commodity structures that incumbents dominate. A cooperative-origin storytelling approach unlocks white-space access before scaling to industrial volume tenders.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated African processors seeking European tempering technology and brand equity. Long-term viability over the next decade hinges on EUDR compliance infrastructure deployment rather than commodity scale alone. Watch for inflection when blockchain-enabled traceability platforms achieve real-time farm-polygon verification at sub-five-second latency, signaling technology maturation for platform consolidation plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | EUDR mandates geolocated proof-of-origin, rewarding early platform investments at Belgian processing hubs. |
| Madagascar Origin Expansion | Criollo and Trinitario genetic stocks in Sambirano Valley unlock premium positioning for Japanese chocolatiers. |
| Precision Fermentation R&D | Biotechnology-derived cocoa butter alternatives threaten to bifurcate markets between extraction purists and adopters. |
| Direct-to-Artist Platform Launch | Digital procurement portals connecting Ecuadorian cooperatives to European chocolatiers displace commodity trader margins. |
| Master Chocolatier Apprenticeship Programs | Talent scarcity across European confectionery schools constrains tempering-line expansion regardless of capital deployment. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with tempering-line operators, cocoa procurement managers at industrial confectioneries, artisan chocolatiers, EUDR compliance officers, and cooperative export directors. Secondary sources encompassed EFSA purity criteria documentation, FDA chocolate identity standards, ISO 2451 cocoa bean grading protocols, and ICE exchange futures data. Bottom-up volume modeling across product types, quality grades, and end-user segments triangulated against top-down trade flow assessments.
Granularity-level modeling deployed segment-specific CAGRs across dark, milk, white, and ruby couverture categories, with separate trajectory assumptions for artisan bakery, industrial confectionery, and restaurant end-use applications. Cocoa butter equivalence technology adoption curves and EUDR compliance cost burdens fed directly into margin projections. CAGRs were derived through regression analysis of historical trade volumes against regulatory implementation timelines and consumer preference shifts.
Underlying measurement precision varies by segment; premium-grade and organic-certified categories carry tighter precision than standard-grade commodity tiers due to more transparent origin documentation. Forecasts reflect assumptions around EUDR enforcement intensity, cocoa butter futures volatility, and substitution elasticity from compound coatings. A model refresh is warranted upon material change in EU Green Deal carbon border adjustment scope or precision fermentation scale-up timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Sugar Free White Chocolate Market
Confectionery
Sugar Free Candy Market
Confectionery
Coffee Gummy Market
Confectionery
North America Premium Chocolate Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Cookie Dough Market
Confectionery
Licorice Candy Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
South America Confectionery Market
Confectionery
Sugar Free Mints Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
United States and Europe Macarons Market
Confectionery
Chocolate Flavors Market
Confectionery
China Chocolate Market