
 Truffle Oil Market | 2026-2036
Truffle Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Truffle Oil Market Outlook
EU organic labeling requirements under EFSA oversight is decoupling artisanal truffle oil production from conventional flavoring operations. Urbani leverages its vertical integration from Piedmont foraging networks to finished bottling facilities. Sabatino Tartufi anchors its competitive stance through multi-generational procurement relationships across central Italian truffle zones. Marcel Plantin specializes in cold-pressed infusion methods that preserve volatile aromatic compounds for haute cuisine distribution.
Truffle oil is an aromatic lipid-based condiment manufactured by infusing extra virgin olive oil or neutral carrier oils with extracts from Tuber melanosporum or Tuber magnatum fruiting bodies, typically at concentrations between 0.1% and 2% by volume to achieve characteristic earthy, sulfurous flavor profiles for finishing dishes. White truffle oil commands premium positioning among luxury hospitality buyers, while black truffle oil competes on broader accessibility across mid-tier restaurant segments. The foodservice distribution channel sustains the dominant volume pathway, though specialty stores occupy higher margin pools through curated gift and collector formats.
EFSA purity standards, USDA organic certification for import eligibility, and REACH compliance for European flavoring substances collectively shape formulation protocols and cross-border market access. FDA enforcement of olive oil authenticity testing under its food standards program further constrains adulterated or mislabeled truffle oil circulation. Stakeholders must monitor evolving botanical origin verification technologies and regional harvest volatility to calibrate sourcing strategies.
Market Dynamics
EFSA organic certification mandates are forcing artisanal producers to decouple from conventional flavoring operations, creating a bifurcated supply structure where traceable Piedmont and Umbrian sourcing networks command premium positioning against undifferentiated commodity imports.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of synthetic refrigerants in cold-chain logistics is accelerating investment in natural cooling infrastructure that preserves volatile aromatic compounds during truffle oil extraction and storage.
- Gourmet foodservice expansion:Fine dining establishments across Italy, France, and the United States are expanding truffle oil applications beyond finishing oils into compound butters, emulsions, and sous-vide infusions.
- Urban foraging networks:Concentrated procurement relationships in Alba, Norcia, and Périgord are anchoring supply security for premium black and white truffle varietals.
Market Restraints
- Input cost volatility:Tuber melanosporum and Tuber magnatum harvest yields fluctuate 40-60% annually based on Mediterranean climate patterns, compressing margin predictability for infused oil processors.
- Supply concentration risk:Over 70% of global white truffle foraging concentrates in Italy's Piedmont region, creating single-point vulnerability to regional drought or blight events.
- Regulatory friction:FDA olive oil authenticity testing under its food standards program constrains formulation flexibility for producers using blended carrier oils.
Strategic Opportunities
- Underpenetrated specialty retail:Curated gift formats and collector-tier packaging in Japan and South Korea represent whitespace for premium positioning beyond traditional foodservice channels.
- Clean-label convergence:Cold-pressed infusion methods paired with blockchain traceability are opening positioning against synthetic 2,4-dithiapentane flavoring alternatives.
- USDA organic tailwind:Certification eligibility for import into the United States is creating tiered pricing separation between certified and conventional production batches.
Industry Challenges
- Skill gap in volatile compound preservation:Master infusers capable of maintaining aromatic integrity across temperature-variable extraction processes command scarcity premiums that constrain production scaling.
- REACH compliance timeline:European flavoring substance registration requirements are extending product reformulation cycles and delaying new market entry for experimental infusion techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truffle Oil Market |
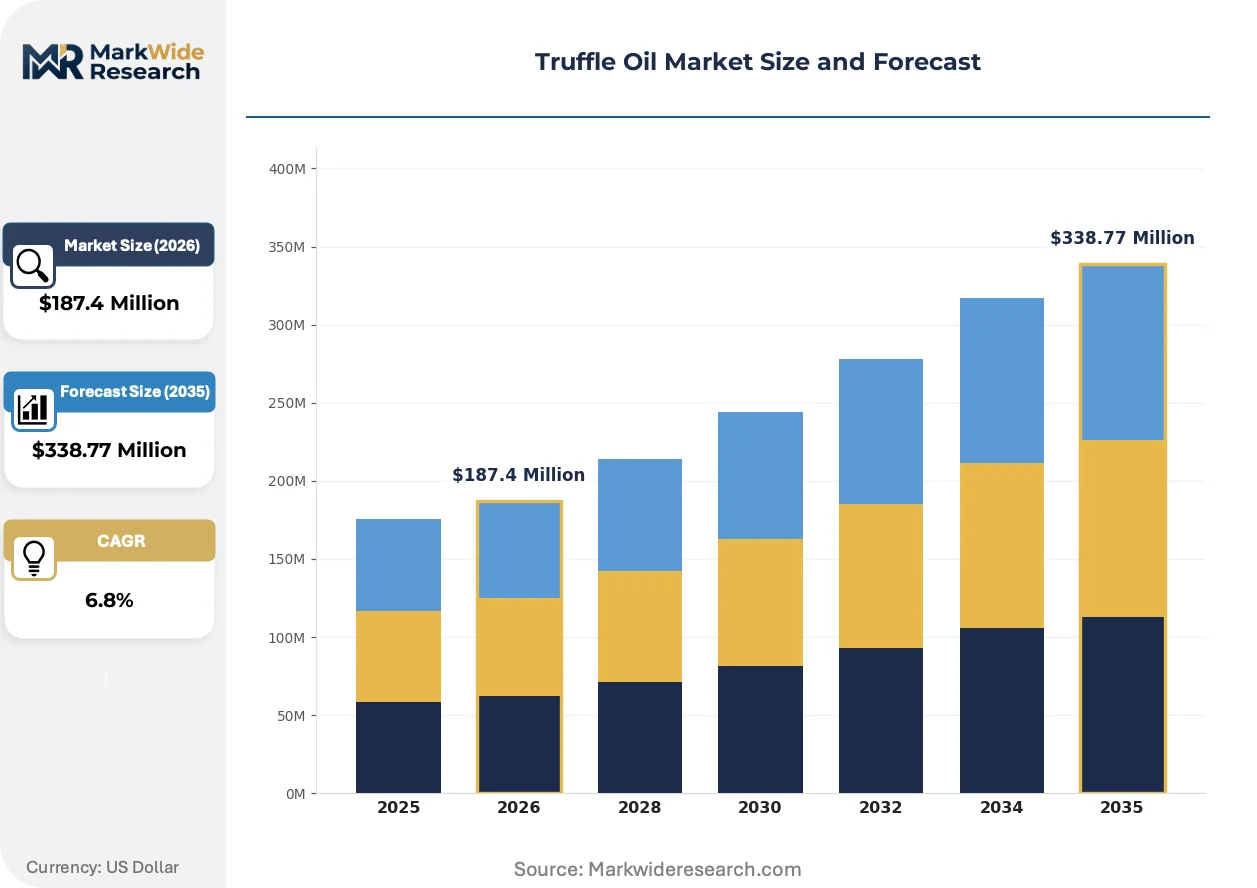
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Truffle Oil, Black Truffle Oil, Truffle Infused Oil, Truffle Flavored Oil End User: Households, Restaurants, Food Processors, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Foodservice Outlets Packaging Type: Bottles, Cans, Pouches, Bulk Containers |
| Companies Covered | Marcel Plantin, AROTZ, Urbani, La Truffle du Ventoux, Black Boar Truffle, Sabatino Tartufi, TruffleHunter Inc., MarDona Specialty Foods, Ltd., Monini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truffle Oil Market Strategic Shifts
Carbon dioxide supercritical extraction is reshaping how aromatic compounds are captured from fresh fruiting bodies, compressing traditional maceration timelines while preserving molecular complexity that heat-based methods degrade.
Supercritical CO2 extraction systems are overtaking conventional cold-soak maceration for premium oil production. Haute cuisine distributors in France and Italy are adopting these systems to secure consistent aromatic profiles across harvest seasons. The technology is overtaking artisanal batch methods by enabling year-round production without seasonal foraging dependency.
REACH registration requirements for European flavoring substances are tightening documentation burdens on imported truffle extracts. Producers must now submit full toxicological dossiers for novel infusion compounds, extending compliance timelines. Small-batch Italian processors are responding by consolidating formulation lines around pre-approved aromatic matrices.
Direct-to-restaurant procurement is displacing traditional distributor intermediation among Michelin-tier establishments. Sommelier-led buying committees in Paris, New York, and Tokyo are establishing captive supply relationships with specific foraging cooperatives. This pattern is most visible in three-star kitchens where origin specificity commands menu storytelling value.
Truffle Oil Market Segmentation
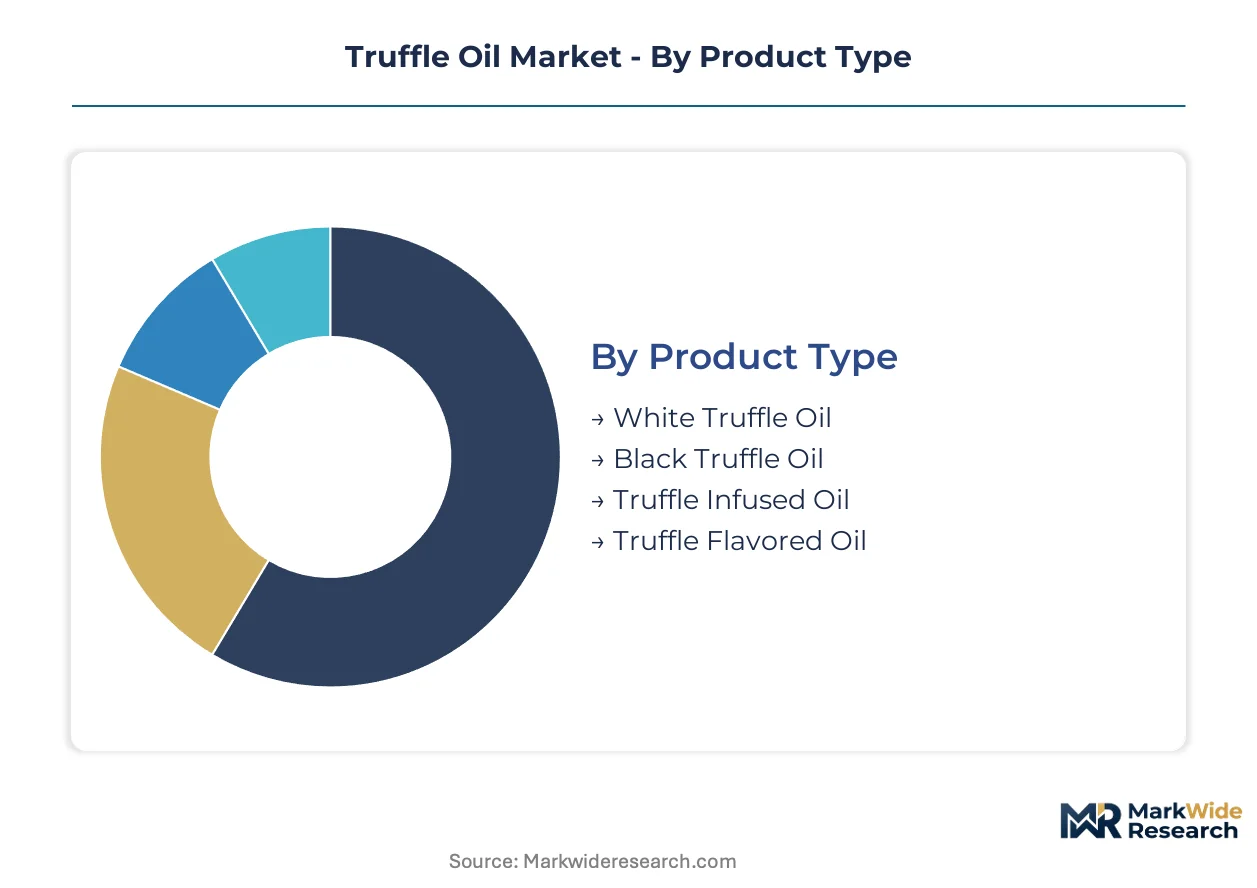
Truffle oil segmentation reflects a tension between artisanal craft traditions and scalable flavoring operations. Product differentiation, end-use application, and channel access each create distinct margin pools and sourcing requirements across the value chain.
Product Type:
The customization-standardization spectrum runs from terroir-specific varietals to synthetic flavoring alternatives, with extraction method and botanical origin commanding divergent price positions.
- White Truffle Oil:Cold-pressed infusions of Tuber magnatum extracts in extra virgin olive oil deliver the most volatile aromatic complexity. Demand concentrates in Michelin-tier kitchens across France and Italy, where origin specificity from Alba or Acqualagna supports menu storytelling premiums.
- Black Truffle Oil:Tuber melanosporum-based formulations offer broader accessibility through more stable harvest volumes from Périgord and Norcia zones. Mid-tier restaurant segments in the United States absorb the majority of volume, trading some aromatic intensity for supply predictability.
- Truffle Infused Oil:Extended maceration methods using dried fruiting bodies rather than fresh extracts.
- Truffle Flavored Oil:Synthetic 2,4-dithiapentane formulations for cost-sensitive food manufacturing applications.
Leading the category by volume: Black Truffle Oil. Expanding most quickly: White Truffle Oil.
End User:
Volume concentration shifts from institutional procurement toward specialized food manufacturing as private-label truffle products multiply.
- Restaurants:Fine dining establishments command the highest per-unit pricing through direct-forager relationships and seasonal menu rotations. Paris, New York, and Tokyo three-star kitchens prioritize Piedmont-sourced white truffle oil for finishing applications.
- Food Processors:Industrial-scale buyers integrate truffle oil into compound butters, shelf-stable sauces, and snack seasonings. EFSA flavoring substance regulations under REACH compliance timelines constrain formulation flexibility for European manufacturing facilities.
- Households:Gift-format purchases through specialty retail channels.
- Catering Services:High-volume event provisioning with standardized black truffle oil specifications.
Dominant by revenue: Restaurants. Steepest expansion trajectory: Food Processors.
Distribution Channel:
Channel selection determines margin capture, with direct procurement displacing traditional intermediation at the premium tier.
- Foodservice Outlets:Dedicated distribution to restaurant groups and hospitality chains captures volume concentration. Urban foraging cooperatives in Italy increasingly bypass wholesalers to supply named kitchens directly.
- Specialty Stores:Curated retail formats in Japan and South Korea command collector-tier pricing through limited-release packaging and provenance documentation.
- Supermarkets:Mass-market accessibility for blended black truffle oil variants.
- Online Retail:Direct-to-consumer growth in premium gift segments.
Highest volume flow: Foodservice Outlets. Gaining share fastest: Specialty Stores.
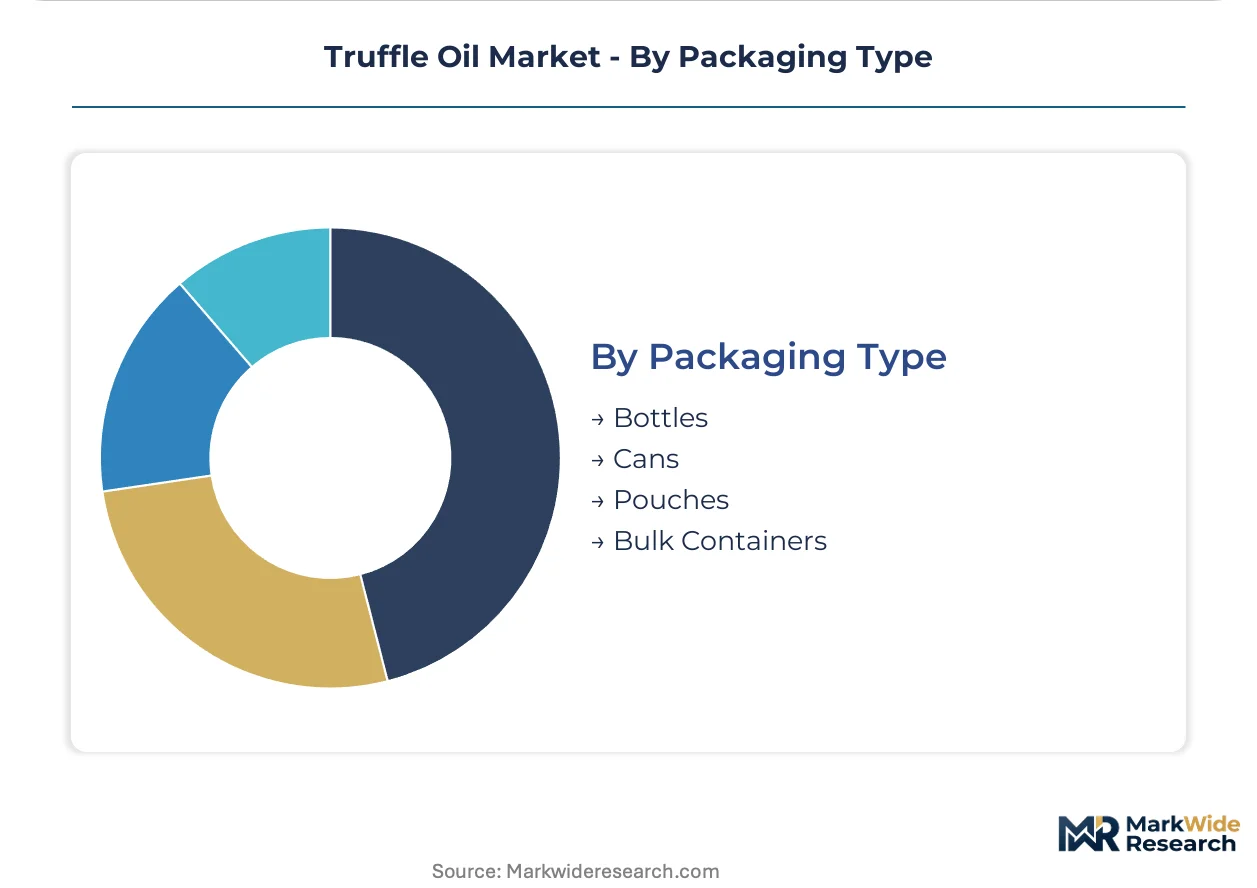
Packaging Type:
Packaging economics track usage occasion and oxidation sensitivity, with format selection directly impacting shelf-life performance.
- Bottles:Dark glass with inert gas flushing preserves volatile sulfur compounds for retail and foodservice finishing applications. Italian and French producers favor 100ml and 250ml formats for haute cuisine positioning.
- Bulk Containers:Stainless steel totes and drums serve industrial food processors with calibrated dosing systems. REACH-compliant labeling requirements extend compliance timelines for European manufacturing customers.
- Cans:Light-protected metal packaging for mid-tier restaurant supply.
- Pouches:Flexible format for single-serve hospitality amenities and airline catering.
Standard by volume: Bulk Containers. Premium positioning leader: Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alba anchors global white truffle oil production through its concentrated Piedmont foraging networks and cold-press bottling facilities serving Michelin-tier kitchens across France and Italy.
Italy
Piedmont's Alba and Acqualagna clusters supply Tuber magnatum extracts for premium cold-pressed formulations. EFSA organic certification mandates under Regulation 2018/848 tighten traceability requirements for artisanal bottlers. Norcia's central Italian truffle zones sustain black truffle oil volume for mid-tier foodservice export.
France
Périgord's Tuber melanosporum harvests anchor supply security for black truffle oil processors serving domestic haute cuisine distributors. REACH compliance timelines for flavoring substances extend reformulation cycles for infusion specialists. Paris three-star kitchens drive direct-forager procurement bypassing traditional wholesale channels.
United States
New York and Los Angeles fine dining establishments absorb premium white truffle oil imports for finishing applications and compound butter formulations. FDA olive oil authenticity testing under its food standards program constrains adulterated product circulation. Specialty retail channels in California command collector-tier pricing through provenance documentation.
Japan
Tokyo's Michelin-tier kitchens prioritize origin-specific Piedmont sourcing for menu storytelling value in kaiseki and French-Japanese fusion concepts. METI import standards for organic products create tiered pricing separation for certified batches. Osaka and Kyoto specialty stores represent whitespace for limited-release gift formats.
South Korea
Seoul's luxury hospitality sector drives demand for curated truffle oil packaging in duty-free and department store channels. MFDS food additive regulations govern synthetic flavoring alternatives in imported products. Busan distributors are expanding direct procurement relationships with Italian foraging cooperatives.
Truffle Oil Market Competitive Environment
The competitive structure tilts toward vertically integrated artisanal specialists with captive foraging networks. Concentration remains moderate with tiered positioning between heritage Piedmont processors and scaled flavoring operations. Two archetypes dominate: terroir-specific bottlers with multi-generational procurement relationships, and diversified olive oil houses with truffle line extensions. Capacity consolidation and direct-to-restaurant channel expansion represent the primary competitive vectors.
Among Italian heritage specialists, Urbani, Sabatino Tartufi, and Marcel Plantin exemplify the terroir-anchored archetype through their positioning within Piedmont and central Italian sourcing corridors. These entities occupy positions defined by extraction methodology differentiation and provenance documentation rather than scale economies. AROTZ and Monini represent the diversified oil house model, leveraging existing distribution infrastructure for truffle line extensions. TruffleHunter Inc. anchors the English-speaking market specialist tier. The competitive dynamic centers on aromatic integrity preservation against synthetic alternatives, with regulatory compliance timelines under REACH and FDA frameworks shaping viable strategic postures.
| Leading Market Players |
|---|
| Marcel Plantin |
| AROTZ |
| Urbani |
| La Truffle du Ventoux |
| Black Boar Truffle |
| Sabatino Tartufi |
| TruffleHunter Inc. |
| MarDona Specialty Foods, Ltd. |
| Monini |
| Others |
Value Chain & Pricing Dynamics
Tuber magnatum spot price volatility in Alba's wholesale markets cascades through three distinct pricing tiers, with harvest yield compression amplifying premiums for cold-pressed white truffle oil while synthetic alternatives capture cost-sensitive manufacturing demand.
Pricing Analysis
Menu storytelling value anchors the dominant pricing model, with Michelin-tier kitchens absorbing per-unit premiums for documented Piedmont provenance that mid-tier restaurants reject. Certification grade under EFSA organic mandates and extraction methodology—supercritical CO2 versus conventional maceration—drive the steepest price differentiation. Cost compression in synthetic 2,4-dithiapentane formulations is intensifying because REACH compliance timelines extend reformulation cycles for natural extract competitors. Food processors exhibit highest price sensitivity, while three-star establishments in Paris and Tokyo demonstrate near-zero elasticity for origin-specific white truffle oil.
Supply Chain Analysis
Refrigerated freight costs from Piedmont to Paris and New York constrain margin capture for small-batch producers lacking direct-restaurant relationships. Raw material sourcing draws from Italy's Alba and Acqualagna clusters, France's Périgord zones, and emerging procurement networks in South Korea's Busan corridor. Single-source vulnerability concentrates in Piedmont's concentrated Tuber magnatum harvests, where regional drought or blight would sever premium white truffle oil supply. Distribution runs through foodservice intermediaries at volume tiers, with direct-forager procurement displacing wholesale channels among Michelin-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is displacing legacy cold-soak maceration methods, compressing production timelines while preserving aromatic integrity that heat-based processes degrade.
For Market Incumbents: Extend captive foraging network coverage into undercontracted Umbrian and Périgord zones to secure supply buffer against Piedmont harvest volatility. Deepen backward integration into cold-press bottling infrastructure to capture margin pools currently absorbed by third-party processors. Synthetic flavoring alternatives from Asian chemical manufacturers represent the most acute substitution threat requiring quality-differentiation investment. For New Entrants and Emerging Players: Direct-to-restaurant digital procurement platforms offer the most penetrable channel wedge, bypassing entrenched foodservice distributors that Urbani and Sabatino Tartufi dominate. Target South Korean duty-free and Japanese specialty retail formats where provenance documentation commands collector-tier pricing elasticity. Position blockchain traceability as the core go-to-market differentiator against undifferentiated commodity imports. For Investors and Strategic Acquirers: Distressed-cycle entries favor terroir-anchored bottlers with multi-generational Alba procurement relationships and EFSA organic certification already secured. Long-term viability hinges on aromatic integrity preservation capabilities that resist synthetic substitution across the next decade. Watch supercritical CO2 equipment utilization rates as the inflection signal for production scalability thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Capacity Expansion | Piedmont bottling investments capture margin from volatile Tuber magnatum harvest premiums. |
| Blockchain Traceability Integration | Provenance documentation opens pricing separation in Japanese and South Korean specialty channels. |
| Direct-to-Restaurant Procurement | Bypassing wholesale intermediaries secures menu storytelling value in Paris and New York kitchens. |
| EFSA Organic Certification | Regulatory compliance creates tiered import eligibility for USDA-certified batches entering United States. |
| Synthetic Substitution Defense | Aromatic complexity preservation justifies premium positioning against 2,4-dithiapentane alternatives. |
Study Parameters
Multi-period observation of Alba wholesale price indices, EFSA certification issuance rates, and supercritical CO2 equipment deployment anchored the trend analysis, supplemented by interviews with master infusers, foodservice procurement directors at Michelin-tier establishments, specialty retail buyers in Tokyo and Seoul, and EFSA regulatory affairs specialists. Secondary validation drew from customs import records, REACH registration databases, FDA food standards enforcement reports, and hospitality industry procurement surveys. Bottom-up volume estimates from foraging cooperative output data triangulated against top-down market sizing from foodservice distribution channel flows.
Segment-weighting across product type, end-user application, distribution channel, and packaging format calibrated value distribution. CAGRs derived from trend extrapolation of harvest yield patterns, regulatory compliance cost trajectories, and channel shift velocities across the projection horizon. Forecast inputs incorporated Mediterranean climate variability indices and cold-chain infrastructure investment pipelines.
The model holds under stable EFSA regulatory frameworks and consistent Mediterranean precipitation patterns; deviation in harvest yield compression or REACH timeline acceleration would shift volume projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Pea Starch Market
Ingredients
Beef Concentrate Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Textured Soy Protein Market
Ingredients
India Olive Oil Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Honey Powder Market
Ingredients
Ice Cream Bases Market
Ingredients
Sunflower Oil Market
Ingredients
Agarwood Oil Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
Compressed Yeast Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Energy Ingredients Market
Ingredients
Africa Plant Protein Ingredients Market