
 Ice Cream Coating Market | 2026-2036
Ice Cream Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Coating Market Foresight
Recipe-as-a-service licensing is decoupling coating formulations from bulk commodity sales, allowing ingredient houses to capture recurring revenue independent of cocoa price cycles. Barry Callebaut leverages its integrated bean sourcing to lock in supply security for industrial buyers. Chr. Hansen Holding A/S specializes in natural color stability systems that extend shelf appeal through freeze-thaw cycles.
Ice cream coating denotes a thin, solidified fat-and-sugar layer applied to frozen desserts, typically comprising 20-40% cocoa butter or its equivalents, emulsifiers, and flavoring agents, which hardens on contact with sub-zero temperatures to provide texture contrast and moisture barrier protection. Chocolate type coatings dominate volume due to universal consumer recognition, while fruit-based variants capture faster growth in clean-label product lines. Dipping formulations command premium positioning in artisanal channels, whereas spraying technology anchors industrial throughput for stick and cone production.
EFSA Novel Food regulations govern alternative fat acceptance in European formulations, while FDA GRAS determinations shape cocoa butter replacer pathways in the United States. BIS standards in India and GB standards in China add compliance layers for exporters targeting those production bases. Stakeholders must monitor evolving emulsifier approval timelines across jurisdictions to avoid reformulation delays.
Market Dynamics
Recipe-as-a-service licensing is decoupling coating formulations from bulk commodity sales, allowing ingredient houses to capture recurring revenue independent of cocoa price cycles and fundamentally restructuring how value flows through the supply chain.
Growth Catalysts
- EFSA Novel Food pathways:Accelerated approval timelines for cocoa butter alternatives in European formulations are expanding the addressable ingredient base for clean-label coatings.
- Premium ice cream line extensions:Artisanal producers in Germany, Italy, and Belgium are launching coated SKUs that command shelf space and formulation complexity.
- Spraying technology adoption:Industrial throughput gains for stick and cone production are lowering unit economics for mass-market coated novelties.
Market Restraints
- Cocoa butter price volatility:Weather-driven supply disruptions in West African growing regions compress margins for chocolate-type coating producers.
- FDA GRAS determination timelines:Extended review periods for novel fat replacers delay product launches and tie up R&D capital.
- Supply concentration in Belgian processors:Limited qualified toll manufacturers for specialized dipping formulations create bottlenecks during seasonal demand spikes.
Strategic Opportunities
- India's organized retail expansion:Cold chain infrastructure investments in Mumbai and Delhi are creating first-mover advantages for coated frozen dessert entrants.
- FSSAI clean-label incentives:India's regulatory push for natural color and flavor declarations opens formulation partnerships with domestic dairy cooperatives.
- Freeze-thaw stability systems:Converging emulsifier and natural color technologies are enabling ambient distribution trials for coated products in Southeast Asian markets.
Industry Challenges
- Cross-jurisdictional emulsifier approvals:Divergent EFSA and FDA timelines for novel lecithin alternatives force parallel development tracks and duplicate testing costs.
- Legacy equipment retrofit requirements:Tempering and enrobing machinery designed for pure cocoa butter formulations demands capital-intensive modification for alternative fat compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Coating Market |
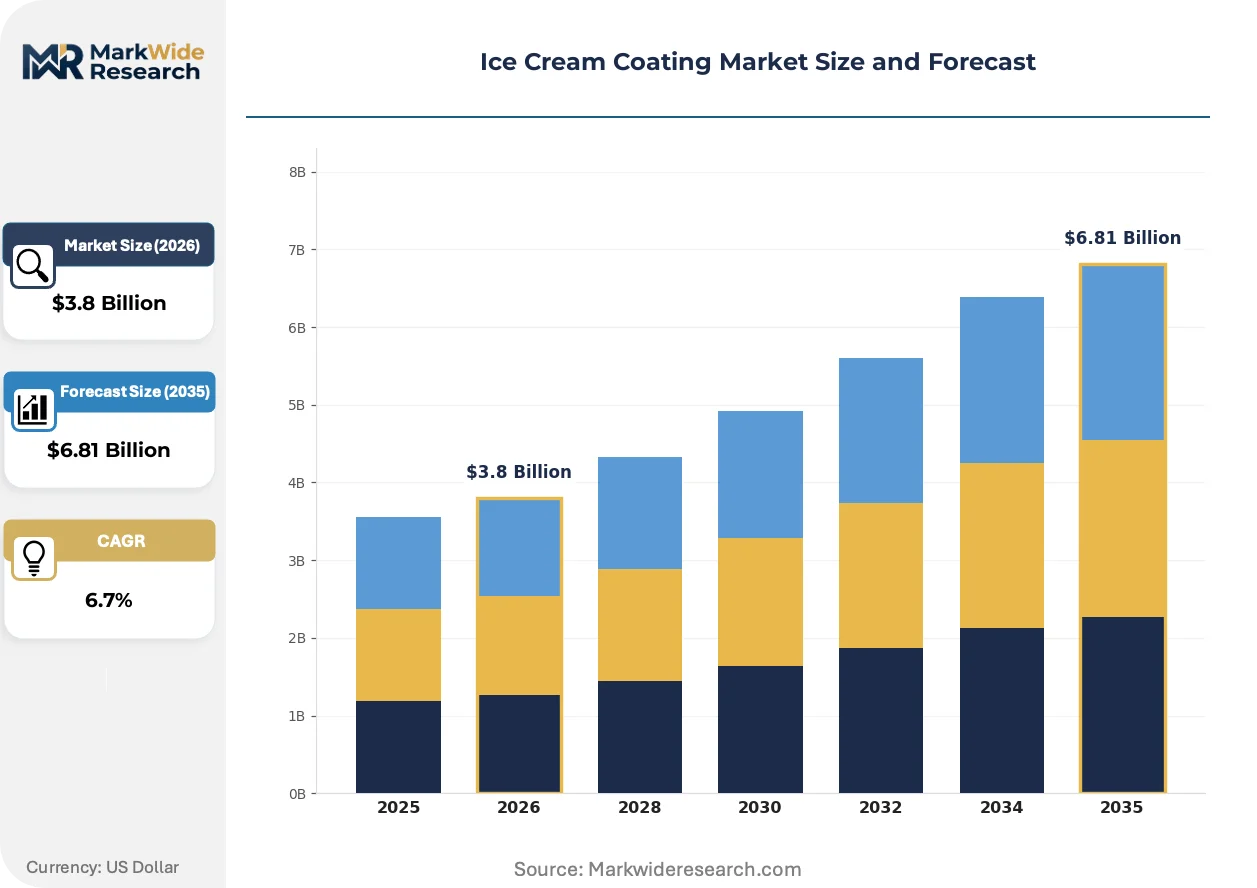
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Chocolate, Caramel, Fruit-Based, Nut-Based Formulation: Coating, Dipping, Spraying, Topping Ingredient: Milk Powder, Cocoa Butter, Sugar, Emulsifiers Application: Artisanal, Industrial, Food Service, Retail |
| Companies Covered | Barry Callebaut, The J.M. Smucker Company, Chr. Hansen Holding A/S, FONA International, Blommer Chocolate Company, Walter Rau Neusser Ol und Fett AG, Palsgaard, Göteborgsfood Budapest Ltd., Bunge Loders Croklaan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Coating Market Shifts & Advancements
Active reformulation across the value chain is compressing development cycles and redrawing competitive boundaries between commodity suppliers and specialized solution providers.
Enrobing automation is unifying temperature control, viscosity management, and crystallization sequencing into single-platform systems. Mid-scale dairy processors in Belgium and the Netherlands are adopting these integrated lines to reduce changeover downtime. The technology is unifying what were previously separate coating and freezing operations, collapsing facility footprints and labor requirements.
REACH restrictions on synthetic emulsifiers are compelling European formulators to accelerate natural alternative qualification programs. Industrial buyers are demanding full substance-level disclosure to preempt future regulatory friction. Chocolate-type coatings for stick novelties face the steepest compliance burden, with German producers already reformulating to exclude targeted chemistries.
Direct-to-manufacturer ingredient supply contracts are displacing traditional distributor intermediaries in coating procurement. Large frozen dessert brands in Italy are negotiating multi-year fat and color supply agreements that bundle technical service with volume commitments. This pattern is most pronounced in the premium segment, where formulation exclusivity confers shelf differentiation.
Ice Cream Coating Market Segmentation
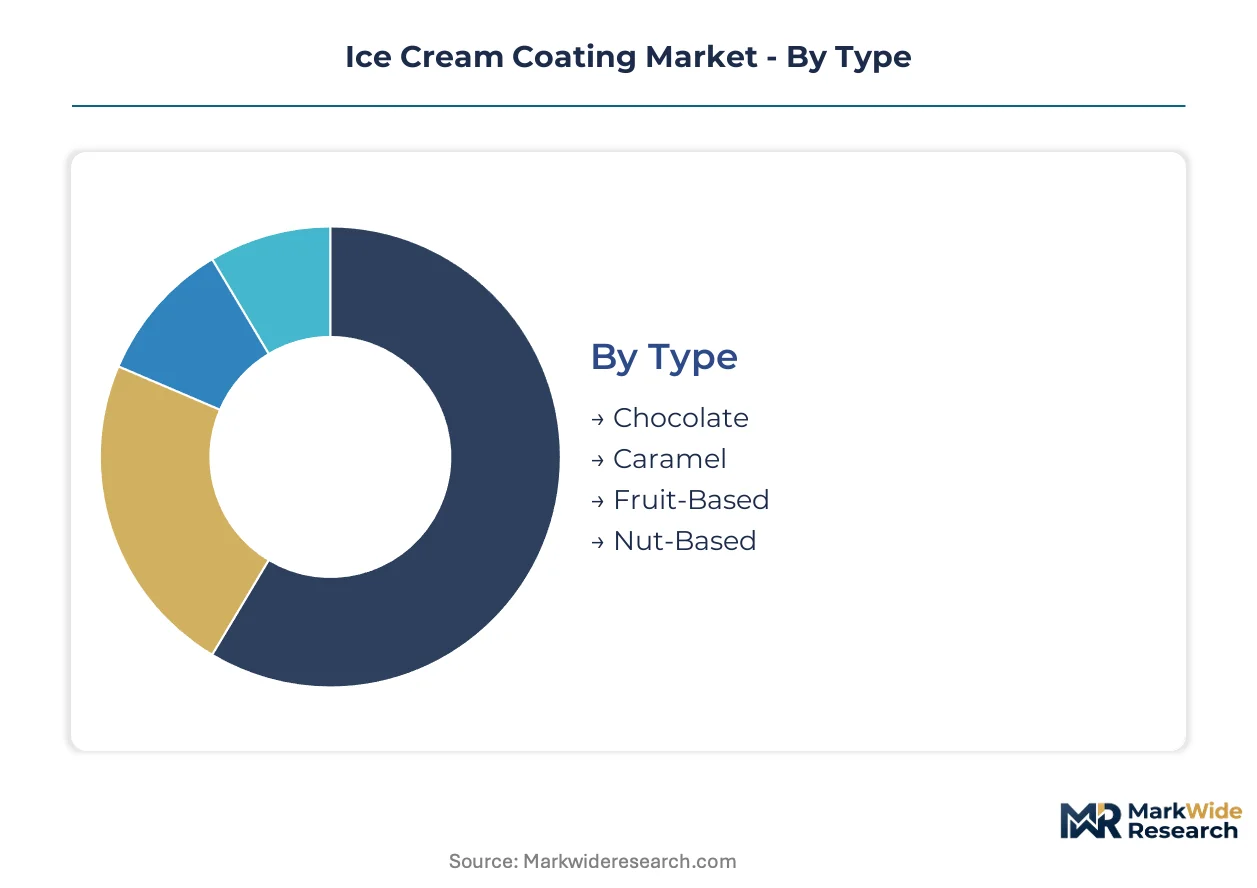
Coating type selection determines fat crystallization requirements and equipment compatibility. Formulation complexity separates commodity suppliers from technical partners. Application channel dictates shelf-life specifications and regulatory compliance burden.
Type:
Upgrade cycles in coating technology favor formulations with cleaner melt profiles and broader temperature tolerance windows.
- Chocolate:Dominant volume segment comprising cocoa butter or equivalent fat bases with 20-40% fat content. Industrial stick novelty producers in Germany and Belgium specify chocolate coatings for universal consumer recognition and established supply security.
- Caramel:High-sugar formulations with distinct Maillard-derived flavor profiles requiring precise moisture barrier engineering. Artisanal channels in Italy favor caramel coatings for premium positioning and textural differentiation against standard chocolate offerings.
- Fruit-Based:Clean-label growth segment capturing reformulation investment from EFSA Novel Food pathways.
- Nut-Based:Allergen-controlled specialty tier with concentrated demand in premium private-label contracts.
Chocolate sits at the top of the volume ranking, with Fruit-Based climbing the fastest.
Formulation:
Cost tier separation runs from capital-intensive dipping systems to lean spraying operations.
- Coating:Standard enrobing process with controlled crystallization for uniform shell thickness. Mass-market producers optimize coating lines for throughput, with Belgian toll manufacturers specializing in seasonal surge capacity.
- Dipping:Artisanal-grade application delivering thicker, irregular layers with premium texture contrast. Italian gelato chains specify dipping formulations for flagship store differentiation and visual craftsmanship signaling.
- Spraying:High-velocity atomization for complex geometries and reduced fat pickup per unit.
- Topping:Decorative finishing layer applied post-hardening for visual and textural accent.
Coating commands the installed equipment base, while Spraying gains share fastest in new facility investments.
Ingredient:
Supply concentration shapes procurement strategy across the four core input categories.
- Milk Powder:Protein and lactose source affecting browning kinetics and flavor development. European formulators monitor EFSA dairy specification updates for cross-border shipment compliance.
- Cocoa Butter:Primary crystallization scaffold defining snap and melt characteristics. West African supply disruptions force price hedging strategies among German industrial buyers.
- Sugar:Bulk sweetener with particle size distribution critical to viscosity control.
- Emulsifiers:Interface stabilizers enabling fat-water dispersion stability through freeze-thaw cycles.
Cocoa Butter anchors value concentration, with Emulsifiers seeing the steepest specification change velocity.
Application:
Customer type segmentation separates specification complexity from volume scale.
- Artisanal:Small-batch production with formulation flexibility and ingredient provenance emphasis. Belgian and Italian producers drive demand for customized dipping systems with rapid changeover capability.
- Industrial:High-throughput operations with standardized specifications and multi-year supply contracts. Large frozen dessert brands negotiate bundled technical service agreements covering fat and color supply security.
- Food Service:Dispense-format coatings for on-premise dessert finishing.
- Retail:Pre-coated packaged products with extended distribution cold chain requirements.
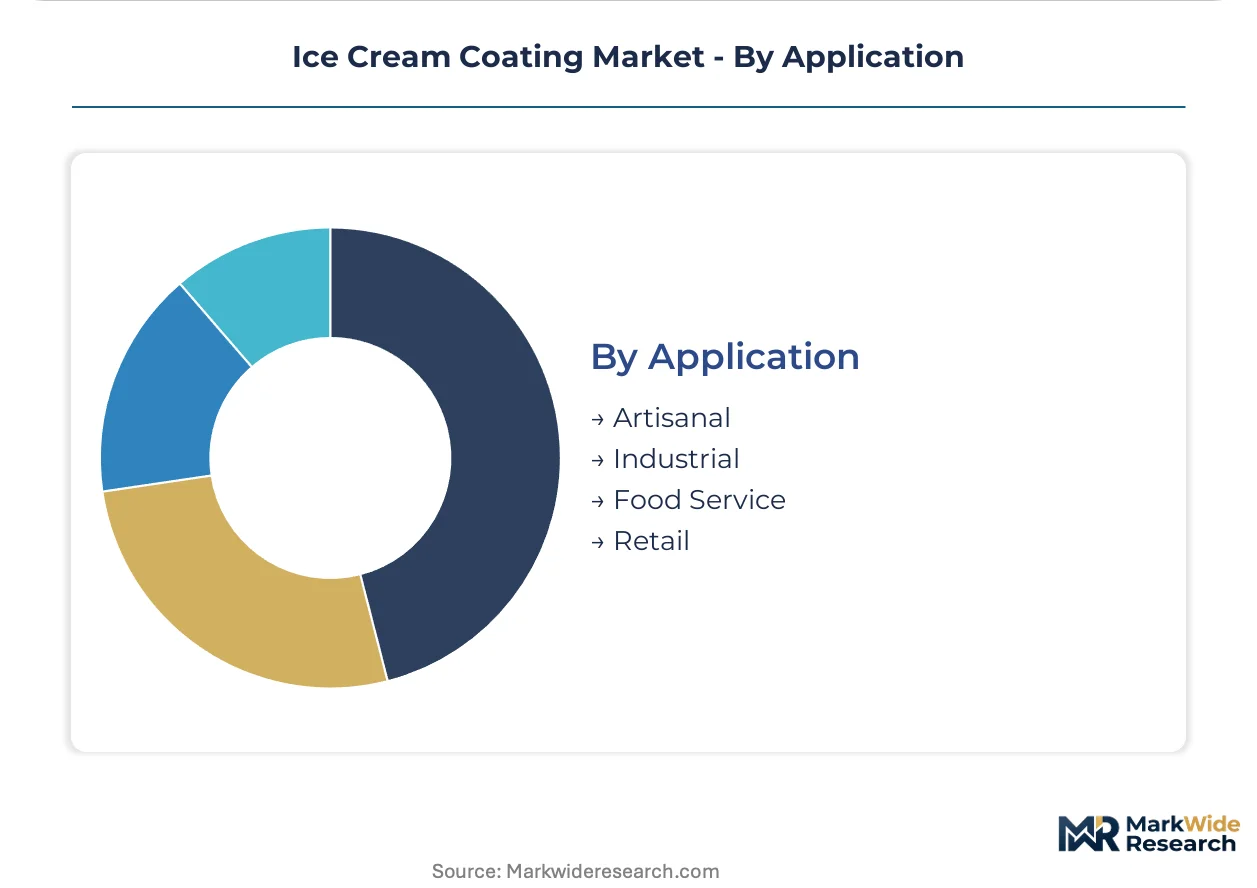
Industrial leads absolute volume, with Artisanal expanding most quickly in premium line extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting coating production toward jurisdictions with streamlined novel-food approval pathways, as EFSA and FDA divergence creates compliance-cost gaps that influence facility siting decisions.
Germany
Artisanal gelato chains and industrial stick novelty producers drive coating demand across premium and mass-market tiers. EFSA Novel Food regulations govern alternative fat acceptance, accelerating clean-label reformulation timelines. The Cologne-Düsseldorf corridor hosts specialized toll manufacturers managing seasonal surge capacity for European brands.
United States
Frozen dessert brands expand coated SKU portfolios to capture premiumization trends in retail and food service channels. FDA GRAS determinations shape cocoa butter replacer development pathways, extending review periods for novel fat systems. Chicago-area processing clusters anchor industrial throughput for national distribution networks.
Belgium
Confectionery heritage and enrobing equipment expertise concentrate coating formulation capability among mid-scale dairy processors. REACH restrictions on synthetic emulsifiers compel natural alternative qualification programs. Antwerp-Brussels logistics hubs facilitate cross-border shipment compliance for pan-European supply chains.
Italy
Gelato culture sustains dipping formulation demand for flagship store differentiation and visual craftsmanship signaling. EFSA dairy specification updates require continuous monitoring for cross-border ingredient shipments. Emilia-Romagna and Lombardy production bases specialize in rapid-changeover coating systems for artisanal channels.
India
Organized retail expansion in Mumbai and Delhi creates first-mover opportunities for coated frozen dessert entrants. FSSAI clean-label incentives for natural color and flavor declarations open formulation partnerships with domestic dairy cooperatives. Cold chain infrastructure investments enable ambient distribution trials for coated products in emerging markets.
Ice Cream Coating Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated ingredient houses capturing recurring revenue through recipe-as-a-service licensing while toll processors compete on seasonal surge capacity. The vendor base organizes around three archetypes: bean-to-coating integrated suppliers, natural color stability specialists, and regional fat-processing intermediaries. M&A activity concentrates on enrobing automation capabilities, and direct-to-manufacturer supply contracts displace traditional distributor relationships.
Among integrated suppliers, Barry Callebaut anchors the bean-sourcing tier with captive supply security for industrial buyers. Chr. Hansen Holding A/S occupies a position within natural color stability systems, exemplifying the specialist archetype focused on shelf-appeal extension through freeze-thaw cycles. Bunge Loders Croklaan sits within the fat-processing tier, representing regional supply concentration for cocoa butter alternatives.
| Leading Market Players |
|---|
| Barry Callebaut |
| The J.M. Smucker Company |
| Chr. Hansen Holding A/S |
| FONA International |
| Blommer Chocolate Company |
| Walter Rau Neusser Ol und Fett AG |
| Palsgaard |
| Göteborgsfood Budapest Ltd. |
| Bunge Loders Croklaan |
| Others |
Supply & Pricing Matrix
Industrial frozen dessert brands in Germany and Belgium anchor procurement volume and negotiate contract-based long-term offtake agreements that bundle technical service with fat supply security. This buyer concentration enables ingredient houses to capture recurring revenue through recipe-as-a-service licensing while compressing spot-market exposure for commodity coating suppliers.
Pricing Analysis
Capacity additions in Belgian toll manufacturing are reshaping price floors for specialized dipping formulations. Three-tier pricing structure across premium, standard, and economy levels separates artisanal dipping systems from industrial spraying lines and mass-market coating commodities. Price differentiation hinges on formulation complexity and EFSA Novel Food certification status. Pricing pressure stems from cocoa butter price volatility in West African supply regions, with industrial stick novelty producers exhibiting highest price sensitivity and premium gelato chains demonstrating lowest.
Supply Chain Analysis
EFSA Novel Food qualification and FDA GRAS determination pathways gate market access for alternative fat suppliers. Supply concentrates in Belgium, Germany, and Italy for specialized enrobing formulations. Raw material flows draw from West African cocoa butter origins, Indian dairy solids for milk powder, and Southeast Asian emulsifier feedstocks. Single-source vulnerability runs through Belgian toll processors managing seasonal surge capacity. Distribution runs through direct-to-manufacturer contracts displacing traditional distributor intermediaries in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where artisanal producers in Italy and Belgium are shifting specification requirements toward clean-label coatings with EFSA Novel Food approval status.
For Market Incumbents: Extend formulation exclusivity through multi-year supply contracts bundling technical service with volume commitments. Lock in backward integration into cocoa butter alternatives to hedge West African supply disruption risk. Certify natural color stability systems under REACH-compliant pathways to preempt regulatory friction from synthetic emulsifier restrictions. For New Entrants and Emerging Players: Mid-scale dairy cooperatives in India represent the most penetrable buyer archetype for coated frozen dessert entrants. Cold chain infrastructure investments in Mumbai and Delhi create first-mover positioning for ambient distribution trials. Pursue FSSAI clean-label partnership frameworks as the primary go-to-market angle. For Investors and Strategic Acquirers: Integrated food ingredient houses are the most active acquirer in this space, targeting enrobing automation capabilities and natural color stability specialists. The five-to-ten year viability window favors vendors with captive supply security and recurring revenue licensing models. Watch EFSA-FDA convergence timelines on novel fat replacer approvals as the inflection indicator for alternative ingredient valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Recipe-as-a-Service Licensing | Decouples formulation revenue from cocoa price cycles for ingredient houses. |
| Backward Integration into Alternative Fats | Locks supply security for industrial buyers facing West African disruption risk. |
| Enrobing Automation Investment | Belgian and Dutch processors adopt integrated lines to collapse facility footprints. |
| EFSA Novel Food Certification | Accelerates clean-label reformulation timelines for fruit-based coating variants. |
| Direct-to-Manufacturer Supply Contracts | Italian premium brands negotiate multi-year agreements bundling technical service. |
Research Methodology
Multiple input streams — executive interviews with coating formulation directors, procurement leads at frozen dessert brands, toll manufacturing operators, and regulatory affairs specialists — were reconciled against customs trade data, EFSA Novel Food registry entries, FDA GRAS determination filings, and SEC disclosures from integrated ingredient suppliers. Primary fieldwork with plant managers in Belgian enrobing facilities and category buyers at German retail chains anchored demand-side validation. Bottom-up volume builds across coating type, formulation method, and application channel were triangulated against top-down market sizing from trade flow analysis.
Data-stream reconciliation informed the analytical framework applied across the projection horizon. Segmentation dimensions modeled include coating type, formulation complexity tier, ingredient input category, and application channel. CAGRs were derived from slope analysis of normalized growth curves fitted to historical shipment data and forward pipeline visibility from disclosed capacity investments. Industry-specific forecast inputs incorporated EFSA approval timeline assumptions and cold chain infrastructure buildout rates in emerging markets.
Underlying measurement precision varies by segment; chocolate-type coatings and industrial application channels carry tighter precision than fruit-based variants and artisanal channels due to disclosure density. Forecasts reflect documented assumptions on regulatory approval velocities and commodity price normalization. Deviation in EFSA-FDA convergence timelines or West African cocoa supply disruption severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Calorie Chocolate Market
Confectionery
Diet Candy Market
Confectionery
North America Confectionery Market
Confectionery
Caramel Chocolate Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Brain Mint Market
Confectionery
South America Compound Chocolate Market
Confectionery
Confectionery Coating Market
Confectionery
Low Calorie Treats Market
Confectionery
India Industrial Chocolate Market
Confectionery
Europe Compound Chocolate Market
Confectionery
Liquorice Shellac Market
Confectionery
Italy Chocolate Market
Confectionery
Black Treacle Market
Confectionery
Real and Compound Chocolate Market