
 Sugar Confectionery Market | 2026-2036
Sugar Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Confectionery Market Intelligence
The retail channel's dominance in sugar confectionery sales is consolidating as supermarkets and hypermarkets expand their private-label offerings and promotional activities. Mars Incorporated leverages its extensive global distribution network to maintain broad market penetration. The Hershey Company specializes in chocolate-based confections, anchoring its position in the North American market. Ferrero Group differentiates through premium product positioning and iconic brand marketing.
Sugar confectionery comprises food items made from a base of sugar and syrups, which are cooked to specific temperatures to create textures ranging from hard-crack for lollipops to soft-ball for fudges. Its primary commercial purpose is for direct consumption as an impulse or gift item. Chocolate products command the largest market share by value, while the gummies segment is expanding rapidly due to innovations in flavors and functional ingredients. Hard candy remains a mature, high-volume category with stable demand.
Regulations from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) mandate strict allergen and nutritional labeling on packaging. In parallel, India's FSSAI sets standards for additives and contaminants, shaping market access. Producers must now navigate consumer demand for novel indulgence while managing increasing health-focused regulatory pressures on sugar content.
Market Dynamics
The central tension shaping the sugar confectionery market is the conflict between its core identity as an indulgence product and intensifying global health regulations. This dynamic forces producers to innovate toward healthier formulations while preserving the taste and texture consumers expect from traditional sweets.
Growth Catalysts
- Expanding Retail Infrastructure in India:The rapid expansion of supermarkets, hypermarkets, and convenience stores across India is improving product accessibility and visibility, stimulating impulse purchases. This development, supported by the FSSAI's framework, provides a structured channel for both domestic and international brands to reach a wider consumer base.
- Food Service Sector Integration:Increased use of sugar confections as components in plated desserts, milkshakes, and baked goods within restaurants and cafes is creating a new B2B demand channel. This application adds value and visual appeal, driving volume sales beyond direct-to-consumer retail.
- Functional Ingredient Innovation:The incorporation of vitamins, minerals, and plant-based extracts into gummies and other confections is appealing to health-conscious consumers. This product evolution allows brands to position sweets as permissible treats with perceived wellness benefits, opening new market segments.
Market Restraints
- Volatile Sugar and Cocoa Prices:The market is highly exposed to price fluctuations in core raw materials like sugar and cocoa, driven by climate events, trade policies, and supply chain disruptions. This volatility directly impacts production costs and profit margins, making financial planning difficult for manufacturers.
- Stringent Nutritional Labeling Mandates:Regulations from bodies like the US FDA and Europe's EFSA require clear, front-of-pack nutritional information and allergen warnings. These compliance requirements increase packaging costs and can deter consumers by highlighting high sugar or fat content.
- Competition from Healthy Snacks:A growing consumer preference for healthier snack alternatives, such as fruit bars, nuts, and yogurt, presents a significant substitution threat. This shift in snacking habits diverts consumer spending away from the traditional sugar confectionery category.
Strategic Opportunities
- Market Entry in Southeast Asia:Countries such as Vietnam and Indonesia, with their young populations and rising disposable incomes, represent significant untapped markets. Establishing distribution networks in these regions offers a pathway for long-term growth beyond mature Western markets.
- Premium and Adult-Oriented Confections:There is a growing niche for sophisticated confections featuring complex flavor profiles, artisanal ingredients, and elegant packaging targeted at adult consumers. This segment allows for higher price points and brand differentiation based on quality rather than volume.
- Direct-to-Consumer E-commerce Channels:Developing online stores and subscription models enables brands to build direct relationships with consumers, gather valuable data, and offer personalized or exclusive products. This channel bypasses traditional retail gatekeepers and can improve margins.
Industry Challenges
- Ethical Sourcing and Supply Chain Transparency:Manufacturers face increasing pressure from consumers and regulators to ensure their raw materials, particularly cocoa and palm oil, are sourced sustainably and ethically. Establishing and verifying a transparent supply chain is a complex and costly operational hurdle.
- Product Reformulation Complexity:Reducing sugar content to comply with health guidelines or sugar taxes without compromising taste, texture, and shelf life is a major technical challenge. This requires significant R&D investment in alternative sweeteners and bulking agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Confectionery Market |
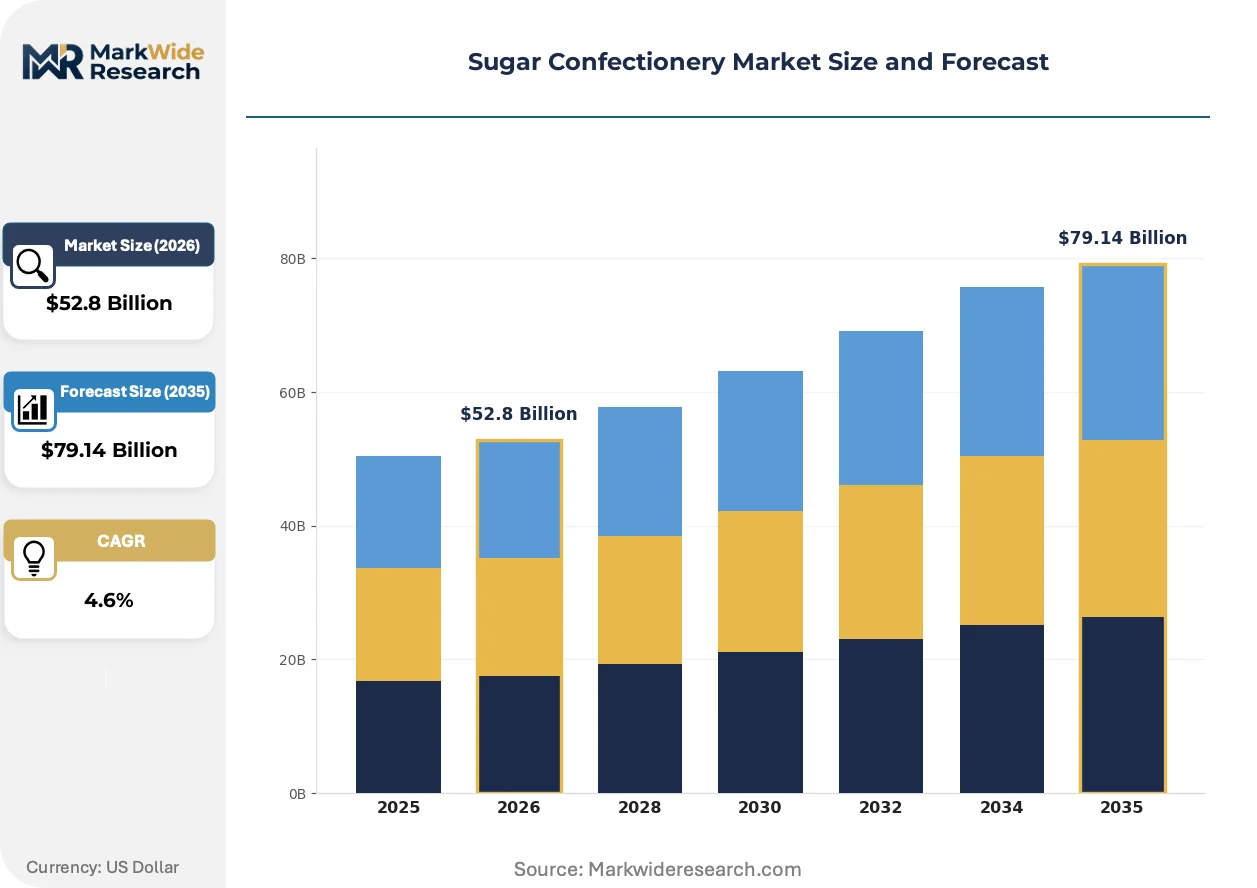
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Hard Candy, Gummies, Marshmallow End User: Retailers, Food Service, E-commerce, Hospitals Distribution Channel: Supermarkets, Convenience Stores, Online Platforms, Specialty Stores Ingredient Type: Sugar, Sweeteners, Flavorings, Colors |
| Companies Covered | Mars Incorporated, Mondelēz International, Ferrero Group, The Hershey Company, Perfetti Van Melle, Nestlé, Lindt & Sprüngli, Haribo, Meiji Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Confectionery Market Strategic Shifts & Innovations
Confectionery's evolution is accelerating as manufacturers balance consumer demand for novel experiences with a global push toward healthier eating habits. This pivot is driving significant changes in product formulation, regulatory compliance, and consumption patterns across the industry.
Advanced manufacturing methods like 3D printing are enabling unprecedented customization in confectionery. Premium and novelty segments are adopting this technology to create personalized shapes, intricate designs, and bespoke flavor combinations for gifting and special events. This technology is modularizing product design, allowing for the on-demand creation of unique items that break away from the constraints of traditional mass-production molds.
Regulatory pressure from sugar taxes and mandatory front-of-pack labeling schemes, prominent in the United Kingdom and Mexico, is becoming a standard global expectation. This forces manufacturers to accelerate investment in sugar reduction technologies and alternative sweeteners to avoid financial penalties and negative consumer perception. The chocolate and hard candy categories are most affected, prompting widespread reformulation to align with public health goals.
Consumer behavior is shifting toward a model of "permissible indulgence," where shoppers seek smaller portion sizes or functional benefits from their treats. This trend disrupts the market for traditional large, multi-serving bags, favoring the growth of single-serve formats and portion-controlled multipacks. This purchasing pattern is most visible in North America and Europe, especially within the premium chocolate and functional gummy segments.
Sugar Confectionery Market Segmentation
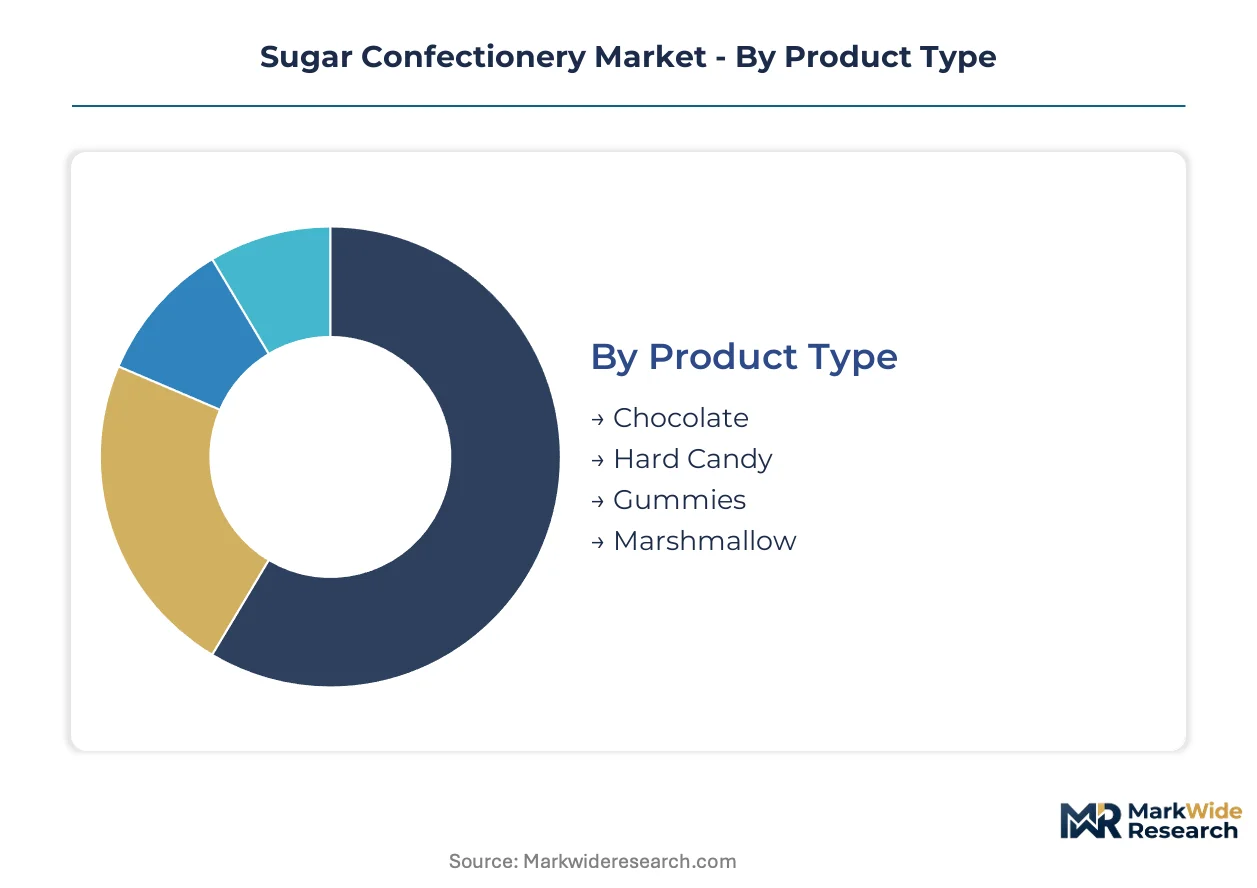
The sugar confectionery market's diverse segmentation reflects varying consumer preferences and operational models across the value chain. Understanding these distinct segments allows manufacturers to tailor product development, marketing strategies, and distribution networks effectively. This granular view highlights areas of growth and competitive differentiation.
Product Type:
Consumer choices for sugar confections are primarily driven by desired indulgence experience, ranging from rich textures to refreshing flavors.
- Chocolate:This segment encompasses products made from cocoa solids, cocoa butter, and sugar, offering a rich, melt-in-the-mouth experience. Demand in North America and Europe is strong, driven by established gifting traditions and premium product offerings.
- Gummies:These gelatin-based confections feature a chewy texture and come in various fruit flavors and shapes. The segment is expanding rapidly in Asia-Pacific, fueled by innovations in functional ingredients and plant-based alternatives appealing to health-conscious consumers.
- Hard Candy:Comprising sugar and syrup cooked to a hard-crack stage, this category offers long-lasting flavor and a classic confectionery experience.
- Marshmallow:Light, airy confections made from sugar, gelatin, and whipped egg whites, often used in baking or as a standalone treat.
Chocolate leads on scale; Gummies lead on momentum.
End User:
The end-user landscape dictates volume requirements and presentation formats for confectionery products, influencing supply chain dynamics.
- Retailers:This segment includes supermarkets, hypermarkets, and convenience stores, purchasing in bulk for direct consumer sales. Demand in India is strengthening due to expanding retail infrastructure and promotional activities.
- Food Service:Restaurants, cafes, and bakeries utilize confections as ingredients for plated desserts, beverages, and baked goods. This application creates a new B2B demand channel, adding value and visual appeal to culinary offerings.
- E-commerce:Online platforms enable direct-to-consumer sales, offering convenience and access to specialized or niche confectionery products.
- Hospitals:This segment represents a smaller, specialized demand for specific dietary or comfort-related confectionery items.
Retailers represent the largest volume purchasers, while Food Service exhibits an accelerating trajectory for B2B demand.
Distribution Channel:
Distribution channels define how confectionery products reach their target consumers, impacting market penetration and profit margins for manufacturers.
- Supermarkets:Large retail stores offering a wide variety of groceries and confectionery, leveraging private-label offerings and extensive promotional activities. This channel dominates sales in mature markets like North America and Europe.
- Online Platforms:E-commerce sites and direct-to-consumer websites facilitate personalized sales and niche product offerings, bypassing traditional retail gatekeepers. This channel is gaining share rapidly in urban centers globally.
- Convenience Stores:Smaller retail outlets providing quick access to impulse purchases, particularly for single-serve confectionery items.
- Specialty Stores:Boutiques focusing on premium, artisanal, or imported confections, catering to niche consumer preferences and gifting occasions.
Supermarkets provide foundational reach, while Online Platforms are experiencing the steepest expansion trajectory.
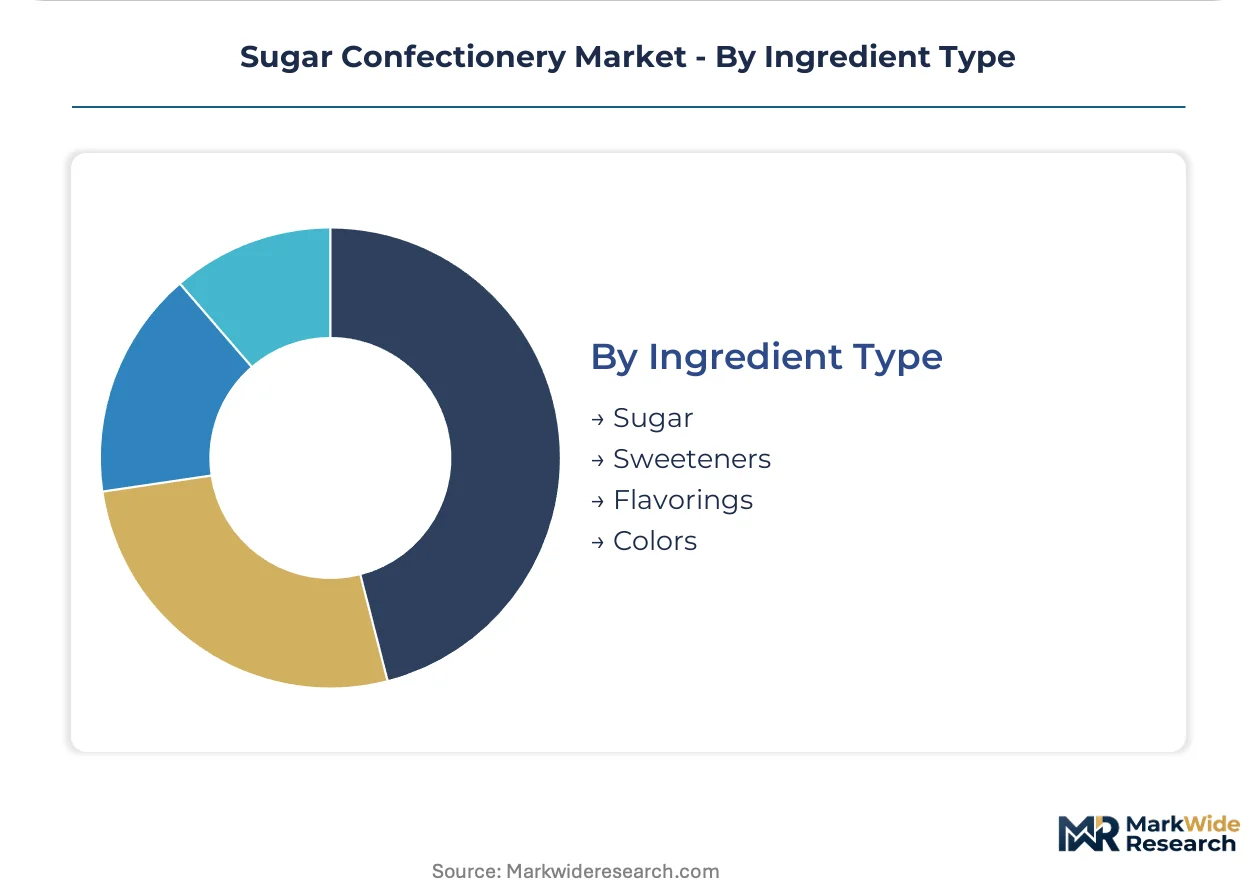
Ingredient Type:
The choice of ingredient type directly influences product formulation, cost structure, and compliance with evolving health regulations.
- Sugar:The traditional base for most confections, providing sweetness, texture, and bulk. Volatile sugar prices impact production costs, particularly for high-volume manufacturers.
- Sweeteners:Alternative ingredients like artificial sweeteners or natural sugar substitutes used to reduce calorie content or meet specific dietary needs. Innovation in this area is a priority for manufacturers addressing health-focused regulatory pressures in the UK and Mexico.
- Flavorings:Natural and artificial compounds added to impart specific tastes, crucial for product differentiation and consumer appeal.
- Colors:Dyes and pigments used to enhance visual appeal, with natural colorants gaining preference due to consumer demand for clean labels.
Sugar forms the foundational ingredient, but Sweeteners are driving significant reformulation efforts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The expanding retail landscape across India, coupled with rising disposable incomes, drives significant demand for sugar confectionery. This market dynamism reflects varied consumer preferences and regulatory environments globally. Diverse regional consumption patterns influence product development and distribution strategies for manufacturers.
India
India's expanding retail infrastructure and increasing consumer disposable income stimulate significant impulse purchases of sugar confectionery. The FSSAI actively sets standards for food additives and contaminants, shaping market access for producers. Urban centers like Mumbai and Delhi observe a concentration of new product launches and promotional activities.
United States
American consumers maintain strong demand for chocolate-based confections, particularly within established gifting traditions and premium segments. The US FDA mandates strict nutritional and allergen labeling, influencing product formulation across the industry. Hershey, Pennsylvania, remains a central hub for chocolate production and innovation, driving market trends.
Germany
The German market exhibits stable demand for traditional hard candy and gummies, reflecting a mature market with consistent consumption patterns. The EFSA's stringent food safety and labeling regulations significantly impact product development and market entry for manufacturers. Cologne, a key European trade fair city, acts as an important hub for confectionery innovation and distribution.
Indonesia
Indonesia represents a significant market entry opportunity, driven by its young population and rising disposable incomes for impulse purchases. Local food safety authorities, such as BPOM, regulate food additives and labeling, influencing product compliance. Jakarta's urban centers show increasing adoption of international and functional confectionery products among consumers.
United Kingdom
The United Kingdom market sees a clear shift towards permissible indulgence, favoring smaller portion sizes and functional benefits in confectionery. UK sugar taxes and mandatory front-of-pack labeling schemes accelerate product reformulation efforts across the industry. London's vibrant retail sector concentrates premium and adult-oriented confectionery brands, reflecting evolving consumer preferences.
Sugar Confectionery Market Key Industry Players
Portfolio diversification dominates the current landscape, with major players expanding their product offerings and market reach. The sugar confectionery market exhibits a tiered structure, from global conglomerates managing extensive brand portfolios to niche regional specialists. Strategic archetypes include large-scale producers focused on volume, premium brand houses emphasizing quality and experience, and agile innovators targeting specific consumer trends. Companies are actively engaged in geographic expansion, brand portfolio optimization, and e-commerce channel development to sustain market share and capture new growth.
At the scale-driven end, Mars Incorporated exemplifies a global conglomerate leveraging its extensive distribution network for broad market penetration. The Hershey Company, a North American specialist, anchors its position through a strong focus on chocolate-based confections. Ferrero Group occupies a premium brand house archetype, differentiating through iconic brand marketing and sophisticated product positioning. These entities demonstrate varied approaches to maintaining competitive advantage within the dynamic confectionery market.
| Leading Market Players |
|---|
| Mars Incorporated |
| Mondelēz International |
| Ferrero Group |
| The Hershey Company |
| Perfetti Van Melle |
| Nestlé |
| Lindt & Sprüngli |
| Haribo |
| Meiji Holdings |
| Others |
Cost & Logistics Intelligence
3D printing technology is enabling unprecedented customization in confectionery, simultaneously reshaping cost economics for premium segments and decentralizing traditional mass-production supply concentrations. This innovation supports higher price points for bespoke items while reducing reliance on large-scale manufacturing infrastructure.
Pricing Analysis
Volatile sugar and cocoa prices exert significant pressure on manufacturers, requiring strategic cost pass-through or absorption. The market primarily employs a tiered pricing structure across premium, standard, and economy levels, with price differentiation stemming from brand premium, artisanal quality, and product customization. Pricing softness impacts high-volume, standard-tier confections due to raw material fluctuations and competition from healthy snacks. Retailers demonstrate high price sensitivity for bulk purchases, contrasting with specialty store consumers who accept higher price points.
Supply Chain Analysis
Stringent nutritional labeling mandates from bodies like the US FDA and EFSA gate market access, requiring complex supply chain compliance for all ingredients. Geographic supply of key raw materials such as cocoa concentrates in West Africa and South America, while sugar production is significant in Brazil and India. Volatile sugar and cocoa prices present a structural risk, impacting manufacturers globally and creating procurement challenges. Distribution primarily runs through supermarkets and online platforms for direct consumer sales, with a growing B2B channel via food service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
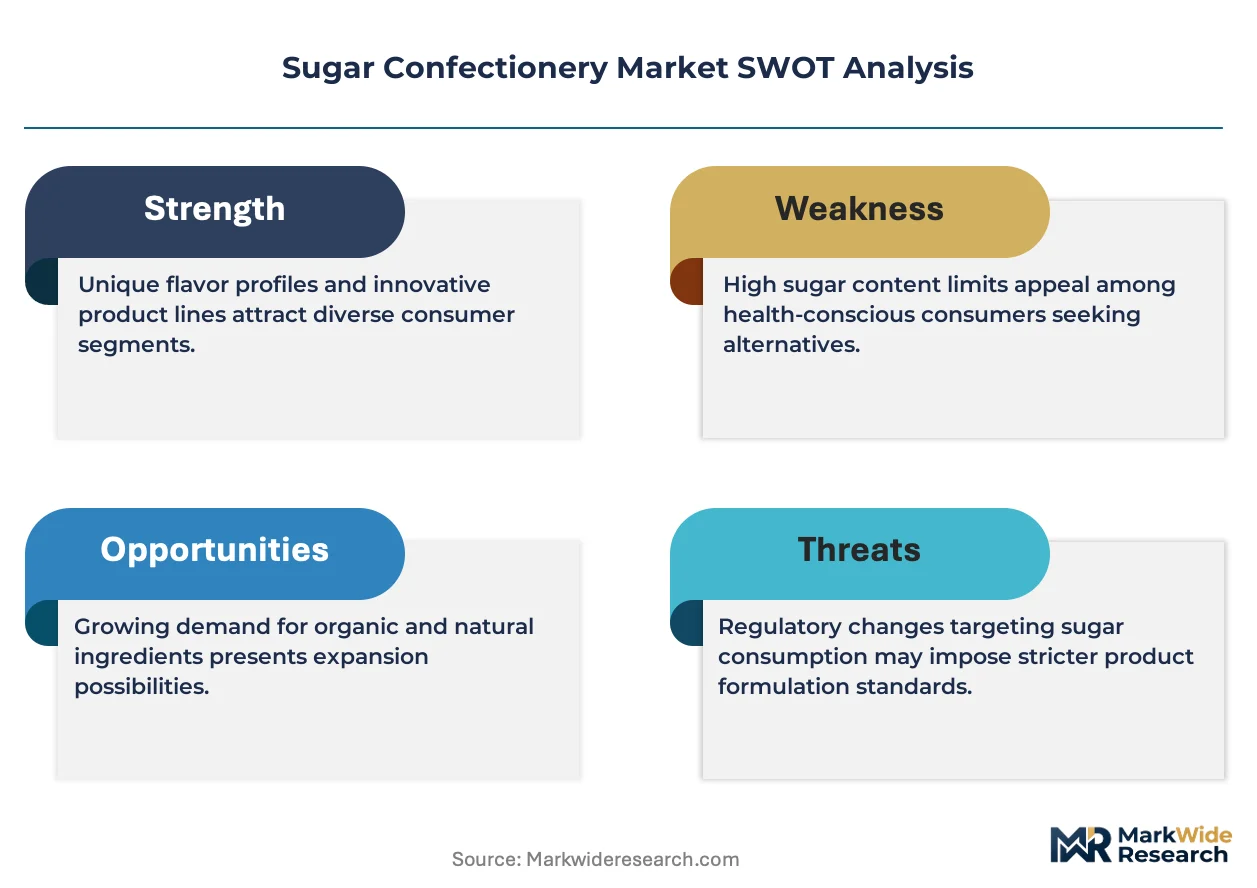
The sugar confectionery market is evolving into a late-cycle quality story, driven by consumer demand for sophisticated premium and adult-oriented confections. This shift emphasizes artisanal ingredients and complex flavor profiles over traditional mass-market volume.
For Market Incumbents: Deepen investment in sugar reduction technologies and alternative sweeteners to mitigate health-focused regulatory pressures and sugar taxes. Expand functional ingredient innovation within gummy segments to appeal to health-conscious consumers, countering the threat from healthy snack alternatives. Mars Incorporated could leverage its global distribution to introduce premium, portion-controlled offerings. Cultivating direct-to-consumer e-commerce channels also provides valuable data and strengthens brand loyalty.
For New Entrants and Emerging Players: Begin with targeted market entry in Southeast Asia, particularly Vietnam and Indonesia, leveraging their young populations and rising disposable incomes. Focus on the premium and adult-oriented confectionery niche, offering sophisticated flavor profiles and elegant packaging for differentiation. Functional gummies incorporating plant-based extracts represent a penetrable segment, especially through online platforms. Specialized retail partnerships in urban centers can establish initial brand presence.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists demonstrating innovation in sugar reduction or functional ingredient integration. The long-term viability of the confectionery market rests on brands that effectively balance indulgence with health-conscious consumer demands over a five-to-ten-year window. Target acquisition profiles include agile innovators developing novel alternative sweeteners or plant-based gummies. The signal to watch is sustained growth in direct-to-consumer e-commerce penetration, indicating successful brand-consumer connection.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Reformulation for Sugar Reduction | This initiative aligns products with evolving health regulations and consumer preferences for lower sugar content. |
| Functional Ingredient Integration | Incorporating vitamins and plant-based extracts allows brands to capture the permissible indulgence segment. |
| Direct-to-Consumer Channel Expansion | Building proprietary online platforms fosters direct consumer relationships and provides valuable purchasing data. |
| Geographic Market Entry in Southeast Asia | Expanding distribution networks into Vietnam and Indonesia taps into young populations with rising disposable incomes. |
| Premium Tier Introduction | Developing sophisticated, adult-oriented confections enables higher price points and brand differentiation based on quality. |
Research Approach
Coverage spans India, the United States, Germany, Indonesia, and the United Kingdom, with primary inputs from each region. This involved interviews with confectionery brand managers, retail category buyers, food service procurement leads, and R&D directors. Secondary validation drew from US FDA filings, EFSA reports, FSSAI guidelines, and trade association publications. Both bottom-up market sizing and top-down validation were employed for robust data triangulation.
Global, regional, and country-level granularity informed market dynamics modeling over the projection horizon. Segmentation dimensions included Product Type, End User, Distribution Channel, and Ingredient Type, alongside key geographies. Compound annual growth rates were derived from historical trends and projected market dynamics. Raw material price volatility, regulatory changes, and evolving consumer health trends served as critical forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or extreme climate shocks. Forecasts reflect documented assumptions, acknowledging revisions from sudden trade policy shifts or disruptive food technologies. A model refresh is warranted upon material change in global commodity prices or major regulatory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Mints Market
Confectionery
Fruit Jellies Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
UK Chocolate Market
Confectionery
Milk Chocolate Market
Confectionery
Brazil Chocolate Market
Confectionery
Chocolate Confectionery Market
Confectionery
Functional Confectionery Market
Confectionery
Jellies and Gummies Market
Confectionery
North America Gummy Market
Confectionery
Confectionery Coating Market
Confectionery
Global Candy Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Caramel Market