
 Milk Chocolate Market | 2026-2036
Milk Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Chocolate Market Intelligence
The scarcity of skilled chocolatiers and sustainable cocoa farming expertise is redrawing the competitive landscape for milk chocolate production. This skills gap impacts the ability to innovate and guarantee ethical supply chains. In this environment, Barry Callebaut leverages its dominant position as a B2B supplier of cocoa and chocolate products. Meanwhile, Mondelez International differentiates through its vast portfolio of consumer brands and extensive global distribution channels, while The Hershey Company focuses on its stronghold in the North American market.
Milk chocolate is a solid confectionary product composed of cocoa solids, milk solids, sugar, and cocoa butter. Regulations, such as those from the FDA in the United States, mandate a minimum of 10% cocoa mass and 12% milk solids for a product to be labeled as milk chocolate. Its primary purpose is for direct consumption as a treat and as a versatile ingredient in food manufacturing. While classic bars represent a mature and high-volume product type, filled chocolates and coated chocolates are areas of significant innovation. Flavors such as caramel and hazelnut continue to drive consumer purchasing decisions within these categories.
The market operates within a complex regulatory framework that governs composition, labeling, and sourcing. The US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) enforce strict standards of identity and allergen labeling. In parallel, regulations like the EU Green Deal are placing greater emphasis on sustainable cocoa sourcing and deforestation-free supply chains. Stakeholders must therefore navigate the challenge of securing ethically sourced raw materials while meeting consumer expectations for taste and affordability.
Market Dynamics
The central tension between stringent ethical sourcing regulations, such as the EU's CSRD, and escalating consumer demand for premium, traceable products is reshaping the milk chocolate market. This dynamic forces a strategic re-evaluation of supply chains, especially for producers targeting discerning customers in high-growth geographies like China.
Growth Catalysts
- Premiumization in Asia:A rising middle class in China is driving demand for higher-quality and novel flavored milk chocolates. This trend stimulates product line innovation and expansion for premium brands.
- Industrial Food Applications:The expanding use of milk chocolate as a key ingredient in the global bakery and beverage sectors is creating significant B2B volume growth, particularly for coatings and inclusions.
- Sustainable Sourcing Mandates:Regulations like the EU Green Deal are compelling manufacturers to adopt transparent and sustainable cocoa sourcing, which in turn enhances brand equity and consumer trust.
Market Restraints
- Cocoa Price Volatility:Unpredictable price fluctuations for raw cocoa, often linked to climate conditions and political instability in West African producing nations, create significant cost pressures for manufacturers.
- Strict Compositional Standards:Regulatory frameworks from bodies like the US FDA, which mandates minimum cocoa and milk solid percentages, limit formulation flexibility and present barriers to market entry.
- Health and Wellness Pressures:Growing consumer aversion to high sugar content, along with sugar taxes in several countries, forces costly product reformulations that risk altering the classic taste profile of milk chocolate.
Strategic Opportunities
- Plant-Based Formulations:Developing milk chocolate products using alternative milks, such as oat, almond, or soy, opens a significant market segment catering to vegan and lactose-intolerant consumers.
- Functional Ingredient Fortification:The incorporation of ingredients like protein, probiotics, and vitamins into chocolate bars allows brands to position products within the health and wellness snack category.
- Direct-to-Consumer Channels:E-commerce platforms enable artisanal and specialty producers to bypass traditional retail, build direct customer relationships, and offer customized or small-batch products.
Industry Challenges
- Specialized Skills Scarcity:A persistent shortage of skilled chocolatiers and cocoa agronomists constrains innovation in high-end confectionery and impedes the effective implementation of sustainable farming techniques.
- Traceability System Implementation:Establishing robust, technology-driven traceability systems to comply with deforestation-free sourcing regulations requires substantial capital investment and complex supplier coordination.
- Allergen Management Complexity:Preventing cross-contamination of allergens like milk and nuts in manufacturing facilities demands rigorous operational protocols and continuous risk management, adding to production costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Chocolate Market |
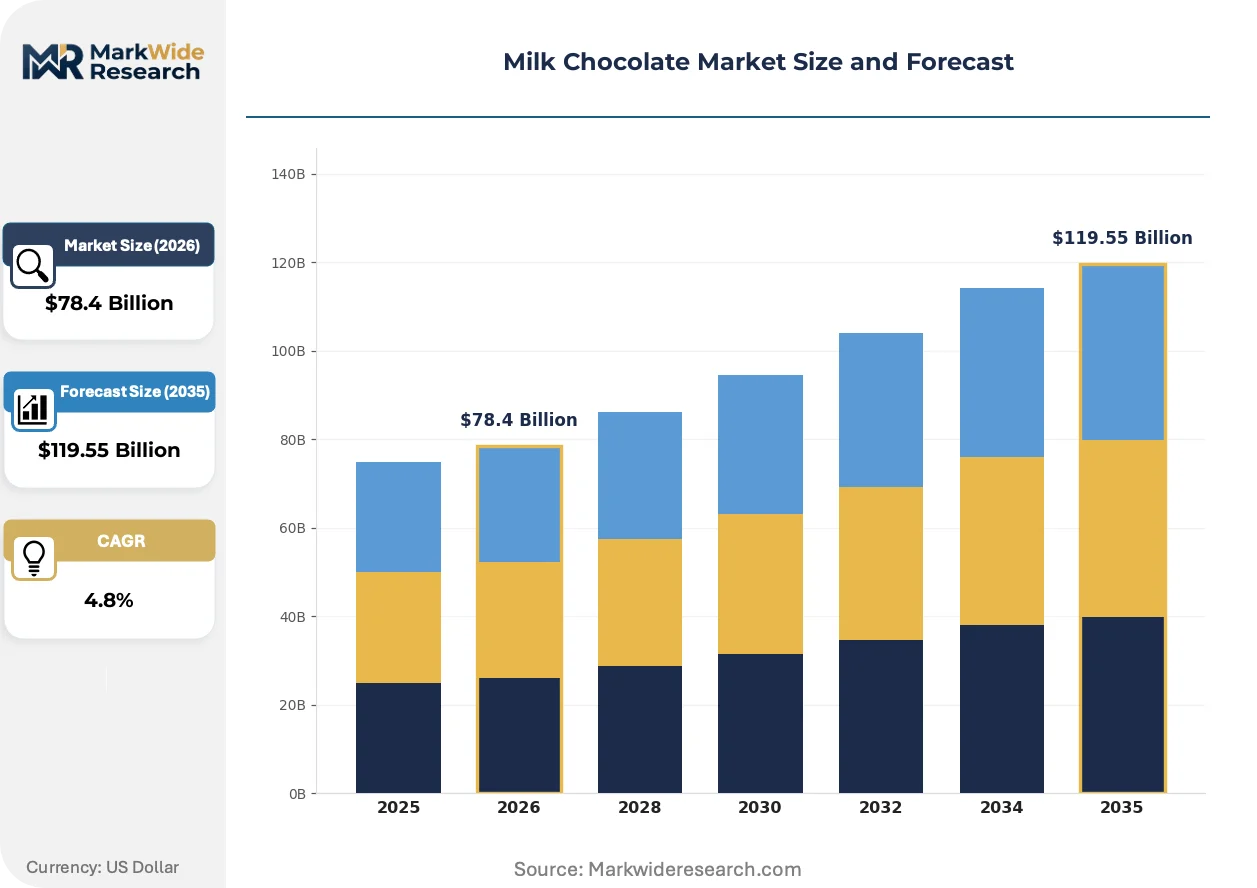
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Blocks, Filled Chocolates, Coated Chocolates, Baking Chips Flavor: Caramel, Hazelnut, Almond, Coffee, Vanilla, Mint Application: Confectionery, Bakery, Ice Cream, Beverages, Desserts, Snacks End User: Retailers, Food Service Providers, Manufacturers, Wholesalers |
| Companies Covered | Ferrero Group, Lindt & Sprüngli, Nestle, Meiji Co. Ltd., Barry Callebaut, Mars Incorporated, The Hershey Company, Godiva Chocolatier, Mondelez International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Chocolate Market Strategic Shifts & Innovations
A convergence of digital traceability technologies and shifting consumer ethics around health and sustainability defines the market's current evolution. These forces compel manufacturers to rethink product formulation and supply chain transparency, influencing both ingredient procurement and final product branding.
Blockchain technology provides an immutable ledger for cocoa sourcing, increasing traceability from farm to factory. Premium brands and large-scale food manufacturers are adopting this for supply chain validation and to substantiate marketing claims. The resulting transparency is fragmenting the undifferentiated commodity cocoa market into distinct tiers based on verifiable origin and ethical data.
New regulations like the European Union's Corporate Sustainability Reporting Directive (CSRD) mandate extensive disclosure on environmental and social supply chain impacts. This legislation is forcing major chocolate producers to overhaul their data collection and reporting mechanisms for cocoa. The confectionery segment sold within the EU is most affected, prompting significant investment into auditable sustainability programs and transparent reporting.
Purchasing decisions are increasingly influenced by clean-label and ethical certifications, including Fair Trade and Rainforest Alliance. This behavioral shift disrupts the mass-market segment, where price was once the primary driver, by creating a preference for brands with transparent sourcing narratives. This trend is most prominent in North America and Western Europe, particularly among millennial and Gen Z consumers.
Milk Chocolate Market Segmentation
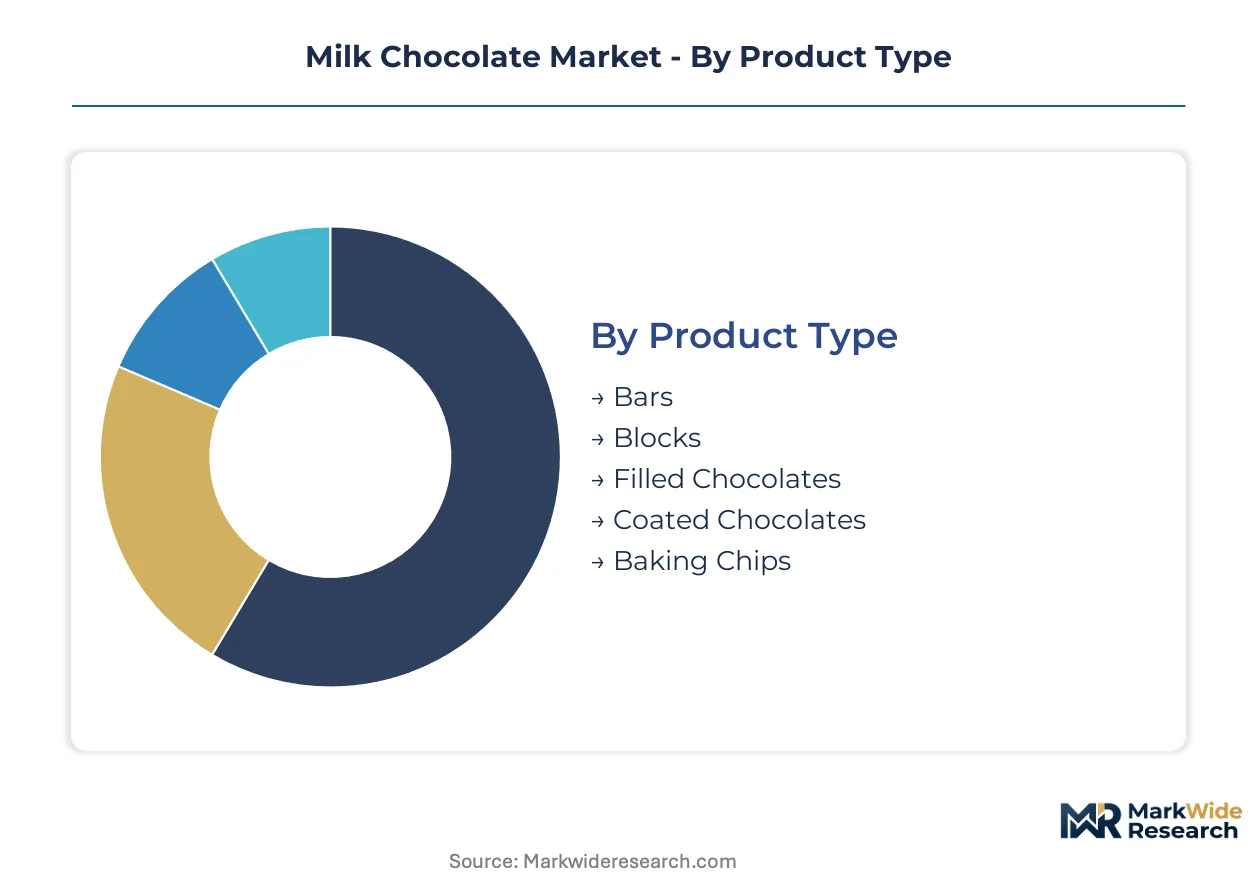
The milk chocolate market's segmentation reveals distinct consumer preferences and industrial requirements. Understanding these granular divisions allows stakeholders to tailor product development and distribution strategies effectively. This detailed analysis highlights areas of concentrated demand and emerging opportunities.
Product Type:
Product type segments face varying degrees of substitution pressure from alternative confectionery formats and snack options. Consumers often choose based on occasion and perceived value.
- Bars:These classic solid blocks of milk chocolate are primarily for direct consumption as a treat. Demand remains high across North America and Europe, driven by established brand loyalty and impulse purchases.
- Filled Chocolates:These confections feature a milk chocolate shell encasing a soft or crunchy center, offering textural variety. Innovation in fillings, especially caramel and hazelnut, stimulates purchasing decisions among discerning consumers in Western Europe.
- Blocks:Larger format solid chocolate intended for baking, sharing, or portioning.
- Coated Chocolates:Products where milk chocolate enrobes another item, such as nuts, fruit, or biscuits.
- Baking Chips:Small, uniform pieces of milk chocolate designed to melt consistently in baked goods.
Bars anchors the volume base while Filled Chocolates gains share at the steepest rate.
Flavor:
Flavor differentiation directly impacts consumer purchasing decisions, often dictating product application and regional appeal. Unique flavor profiles can command premium pricing.
- Caramel:This rich, sweet flavor provides a creamy, often chewy, contrast to milk chocolate. It consistently ranks as a top preference, driving sales of filled chocolates and confectionery items globally.
- Hazelnut:Offering a nutty, earthy complement, hazelnut is a traditional pairing with milk chocolate. This flavor enjoys particular popularity in European markets, especially within premium praline and bar segments.
- Almond:Provides a crunchy texture and subtle nutty taste, commonly found in chocolate bars and coated confections.
- Coffee:A sophisticated flavor pairing that adds a bitter counterpoint, appealing to adult palates in dessert and beverage applications.
- Vanilla:A foundational flavor that enhances the inherent sweetness and creaminess of milk chocolate.
- Mint:Offers a refreshing, cool sensation, often popular in seasonal or after-dinner chocolate offerings.
Caramel maintains broad appeal across all consumer demographics, while Coffee flavor products are expanding quickly in specialty markets.
Application:
Volume requirements vary significantly across different applications, influencing the form and scale of milk chocolate procurement by industrial users. B2B demand for milk chocolate as an ingredient is substantial.
- Confectionery:This primary application encompasses direct-to-consumer products like bars, truffles, and molded chocolates. It represents the largest volume segment for milk chocolate usage, driven by global consumer indulgence.
- Bakery:Milk chocolate serves as a key ingredient in cakes, cookies, pastries, and other baked goods. The expanding global bakery sector creates significant B2B volume growth for coatings and inclusions.
- Ice Cream:Utilized as a flavoring, coating, or inclusion in frozen desserts, contributing texture and richness.
- Beverages:Incorporated into hot chocolates, milkshakes, and specialty coffee drinks, particularly in foodservice.
- Desserts:Used in a wide array of prepared desserts, including puddings, mousses, and glazes.
- Snacks:Found in granola bars, trail mixes, and other convenience food items, adding flavor and energy.
Confectionery remains the largest application by volume, with Bakery applications showing the steepest expansion trajectory.
End User:
Supply concentration for milk chocolate products varies by end-user type, reflecting distinct purchasing patterns and distribution channels. Each end-user group has specific requirements for product format and packaging.
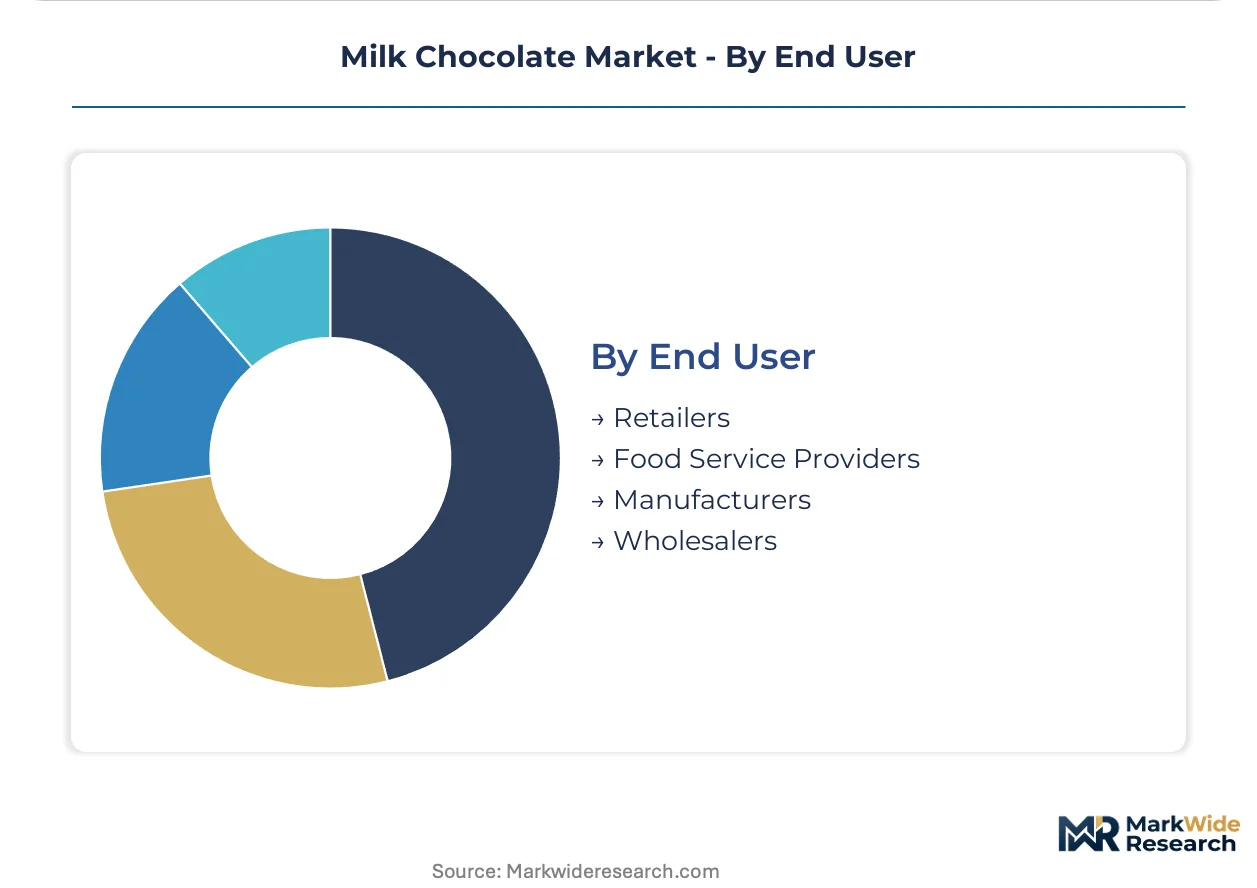
- Retailers:Supermarkets, convenience stores, and specialty shops directly distribute milk chocolate products to consumers. This channel demands diverse product types, from impulse buys to premium gift items, influencing packaging and shelf presence.
- Manufacturers:Food and beverage producers purchase milk chocolate as a raw ingredient for their own products. This B2B segment requires large volumes of bulk chocolate, often in specific formulations for industrial processing.
- Food Service Providers:Restaurants, cafes, and catering companies use milk chocolate in prepared dishes and beverages.
- Wholesalers:Intermediaries who purchase in bulk from manufacturers and distribute to smaller retailers or food service operations.
Retailers drive significant consumer-facing sales, while Manufacturers represent the most consistent bulk purchasing segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global consumption mix for milk chocolate exhibits significant geographic variation, particularly in its growth trajectories. China's expanding consumer base drives demand for premium and novel flavored products, contrasting with the mature, high-volume classic bar segments prevalent in established Western markets. This differential influences product innovation and market penetration strategies across diverse regions.
China
A rising middle class in China fuels demand for higher-quality and novel flavored milk chocolates. Regulations from the State Administration for Market Regulation (SAMR) govern food safety and labeling standards for imported and domestic products. Shanghai serves as a key hub for confectionery innovation and premium brand launches, catering to discerning urban consumers.
United States
The United States market maintains strong demand for milk chocolate as a direct-consumption treat and a key ingredient in bakery applications. The US Food and Drug Administration (FDA) mandates specific compositional standards for products labeled as milk chocolate. Pennsylvania's confectionery cluster, including Hershey, continues to drive manufacturing and product development for the North American market.
Germany
Germany showcases robust demand for filled chocolates and products emphasizing sustainable sourcing practices. The European Food Safety Authority (EFSA) ensures strict food safety standards, while the EU Green Deal influences cocoa supply chain ethics. Cologne, a major confectionery center, hosts significant manufacturing operations and trade events, reflecting market trends.
France
French consumers prioritize artisanal and premium milk chocolate offerings, often seeking unique flavor profiles. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) oversees food safety and labeling, complemented by the Corporate Sustainability Reporting Directive (CSRD) for supply chain transparency. Lyon, a renowned gastronomic city, supports a vibrant community of fine chocolate makers and specialty retailers.
United Kingdom
The United Kingdom market sees consistent demand for milk chocolate in snacking and beverage applications. The Food Standards Agency (FSA) enforces labeling and compositional rules, with sugar taxes influencing product reformulation efforts. Bournville, a historic center for chocolate manufacturing, remains a significant production site for major confectionery brands.
Milk Chocolate Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the milk chocolate market's structure. This tiered landscape features global confectionery giants alongside specialized B2B ingredient suppliers. Key archetypes include large-scale consumer brand owners, dedicated cocoa and chocolate ingredient providers, and regional market strongholds. Manufacturers frequently engage in strategic partnerships for sustainable sourcing and portfolio diversification through new product development.
Within the B2B ingredient supplier archetype, Barry Callebaut AG, a Swiss-headquartered company, anchors a significant portion of the global cocoa and chocolate supply. Mondelez International, Inc., a US-based corporation, exemplifies the extensive portfolio of consumer brands and wide distribution capabilities. Meanwhile, The Hershey Company, another US-based entity, occupies a strong position within the North American market, focusing on its established brand presence.
| Leading Market Players |
|---|
| Ferrero Group |
| Lindt & Sprüngli |
| Nestle |
| Meiji Co. Ltd. |
| Barry Callebaut |
| Mars Incorporated |
| The Hershey Company |
| Godiva Chocolatier |
| Mondelez International |
| Others |
Cost & Logistics Intelligence
Large-scale cocoa processing operations establish significant economies of scale, influencing both global supply concentration and the underlying price floors for bulk milk chocolate ingredients. This dynamic shapes the competitive landscape for both B2B suppliers and consumer-facing brands.
Pricing Analysis
Long-term offtake agreements characterize bulk milk chocolate ingredient sales, providing stability for large manufacturers. Price differentiation stems from cocoa quality grade, ethical certification levels like Fair Trade, and the volume scale of procurement. Pricing softness reflects growing consumer aversion to high sugar content, prompting costly reformulations. Industrial manufacturers purchasing bulk ingredients exhibit the highest price sensitivity, while discerning consumers for premium filled chocolates show less.
Supply Chain Analysis
Strategic stockpiling of cocoa beans is common among major processors to mitigate price volatility and ensure consistent supply. Geographic supply concentration for cocoa centers on West African nations like Côte d'Ivoire and Ghana, while advanced processing occurs in Europe and North America. The supply chain relies heavily on cocoa beans, milk solids, and sugar. Commodity price volatility for cocoa presents a structural risk to manufacturers. Distribution runs through a dual channel, serving B2B industrial users and B2C retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The milk chocolate market presents high-growth disruption, driven by digital traceability technologies like blockchain that redefine supply chain transparency.
For Market Incumbents: Consolidate cocoa sourcing networks to enhance transparency and comply with stringent regulations like the EU Green Deal. Invest in research and development for plant-based milk chocolate formulations to address health and wellness pressures. Leverage existing distribution channels to introduce certified sustainable product lines, countering the threat from specialty brands. Deepen vertical integration into cocoa processing to control quality and cost.
For New Entrants and Emerging Players: Fair Trade certification fast-tracks market entry for new players, appealing to ethically conscious consumers. Target premium segments in high-growth geographies like China with novel flavor profiles, such as coffee or unique fruit infusions. Utilize direct-to-consumer e-commerce platforms to establish brand presence and build direct customer relationships. Focus on clean-label products as a key go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors agile firms leveraging digital traceability solutions for enhanced supply chain transparency. Acquisition targets should include mid-sized specialty producers with strong regional brand equity or advanced plant-based formulation capabilities. Long-term viability rests on the consumer shift towards premiumization and sustainable consumption. A signal to watch is increased M&A activity in alternative milk chocolate producers or cocoa traceability technology providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification: Plant-Based Formulations | Addresses growing consumer demand for vegan and lactose-free options in Europe. |
| Supply Chain Digitization: Blockchain Implementation | Enhances traceability for cocoa sourcing, meeting EU CSRD mandates. |
| Market Expansion: China Premium Product Launch | Captures rising middle-class demand for novel flavored milk chocolates. |
| Sustainability Investment: Fair Trade Certification | Builds brand equity and consumer trust in North American markets. |
| Channel Optimization: Direct-to-Consumer E-commerce | Enables specialty producers to reach discerning customers directly. |
Research Approach
A standing panel of chocolatiers, cocoa agronomists, and food safety regulators provided ongoing calibration for market insights. This approach combined primary interviews with industry stakeholders and secondary validation through industry association reports, government food safety guidelines, and trade statistics. Bottom-up market sizing from production data was triangulated with top-down validation against consumer spending trends.
Consistency checks validated all forecast outputs against external benchmarks and established industry growth trajectories. The analytical framework modeled segmentation across product type, flavor, application, end-user, and regional consumption patterns over the projection horizon. Compound annual growth rates were derived from historical data, projected demand drivers, and anticipated regulatory impacts. Cocoa bean yield forecasts and sugar pricing trends served as key forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of stable cocoa supply; material deviation would warrant model refresh. Forecasts reflect assumptions regarding consistent regulatory enforcement and predictable consumer health trends. Revision becomes warranted when significant changes in raw material availability or major regulatory overhauls cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
Pralines Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Diet Candy Market
Confectionery
Ice Cream Coating Market
Confectionery
Buttercream Frosting Market
Confectionery
Low Calorie Sweets Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Gummy Market
Confectionery
North America Dark Chocolate Market
Confectionery
South America Chocolate Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Chocolate Confectionery Market
Confectionery
North America Compound Chocolate Market
Confectionery
Cocoa and Chocolate Market