
 South Africa Fast Food Market | 2026-2036
South Africa Fast Food Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Fast Food Market Insights
Premium ingredient specifications and halal certification tiers is bifurcating the South Africa fast food landscape into value-driven and quality-positioned operators. Famous Brands Inc. leverages its vertically integrated supply chain across the Debonairs Pizza and Steers networks to sustain margin control. McDonald's Corporation anchors its position through standardized cold-chain logistics that dominate metropolitan distribution. Nando's Group Holding Ltd. differentiates through peri-peri sauce specialization and flame-grilled preparation protocols that command price premiums in middle-income suburbs.
South Africa fast food comprises prepared meals served through limited-service formats, characterized by standardized cooking temperatures, portion-controlled assembly lines, and shelf-life management systems designed for high-throughput commercial feeding. The sector serves time-constrained consumers requiring caloric intake without table-service delays. Chicken and burger categories lead volume throughput due to protein affordability and local taste alignment, while delivery service types capture the fastest expansion as third-party logistics platforms extend reach beyond traditional drive-thru catchments. Family customer types concentrate spending during weekend peak periods, whereas young adult segments generate higher per-visit frequency through digital app-based ordering.
The Department of Health enforces front-of-pack labeling regulations that compel calorie disclosure and sodium reduction across quick-service menus, while the National Regulator for Compulsory Specifications mandates food safety certifications for franchise operations. Municipal health bylaws in Johannesburg, Cape Town, and Durban impose graded hygiene inspections that shape outlet licensing and operational continuity. Stakeholders must monitor enforcement intensity around sugar taxation proposals and plastic packaging restrictions that could restructure cost structures and supply chain configurations.
Market Dynamics
Third-party logistics platforms are fragmenting traditional catchment boundaries by extending delivery reach beyond drive-thru radii into underserved townships, while the Department of Health's front-of-pack labeling mandates force simultaneous menu reformulation across all operator tiers.
Growth Catalysts
- Halal certification expansion:Rising Muslim consumer populations in Gauteng and Western Cape provinces drive demand for certified supply chains. Operators securing JAKIM-equivalent accreditation unlock access to previously restricted consumer pools.
- Third-party platform integration:Uber Eats and Mr D Food aggregators compress delivery logistics costs for independent outlets. Township-based operators now serve metropolitan demand corridors without proprietary fleet investment.
- Young adult urbanization:Migration into Johannesburg and Pretoria metropolitan corridors concentrates time-constrained consumers. Digital-native cohorts generate higher order frequency through app-based payment systems.
Market Restraints
- Poultry input cost volatility:Feed grain price fluctuations and avian influenza outbreaks compress protein margins. Chicken-dominant menus face margin instability when maize and soybean futures spike.
- Cold-chain infrastructure concentration:Metropolitan logistics hubs in Gauteng and Western Cape create supply vulnerability. Load-shedding disruptions at centralized distribution points halt multi-province operations.
- Sugar taxation proposals:Pending National Treasury levies threaten fountain beverage profitability. Formulation shifts to artificial sweeteners risk taste-profile alienation among core consumer segments.
Strategic Opportunities
- Eastern Cape underpenetration:Port Elizabeth and East London corridors lack premium quick-service density. First-mover operators capture middle-income suburban expansion with limited competitive pressure.
- Plant-based protein convergence:Pea-protein and mycelium technologies mature for price-competitive menu integration. Health-conscious segments in Cape Town's Atlantic seaboard suburbs demonstrate trial willingness.
- Municipal hygiene grading systems:Johannesburg, Cape Town, and Durban health bylaws create differentiation through A-grade certification display. Transparent scoring mechanisms enable quality-signaling without marketing expenditure.
Industry Challenges
- Food safety certification timelines:National Regulator for Compulsory Specifications approval processes delay new outlet openings. Franchise expansion schedules compress against bureaucratic review cycles.
- Load-shedding operational continuity:Eskom grid instability forces generator and solar backup capital deployment. Smaller operators lack balance sheet capacity for redundant power infrastructure.
- Digital payment integration complexity:Legacy point-of-sale systems require costly retrofitting for app-based ordering convergence. Technical debt accumulates across multi-brand franchise portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Fast Food Market |
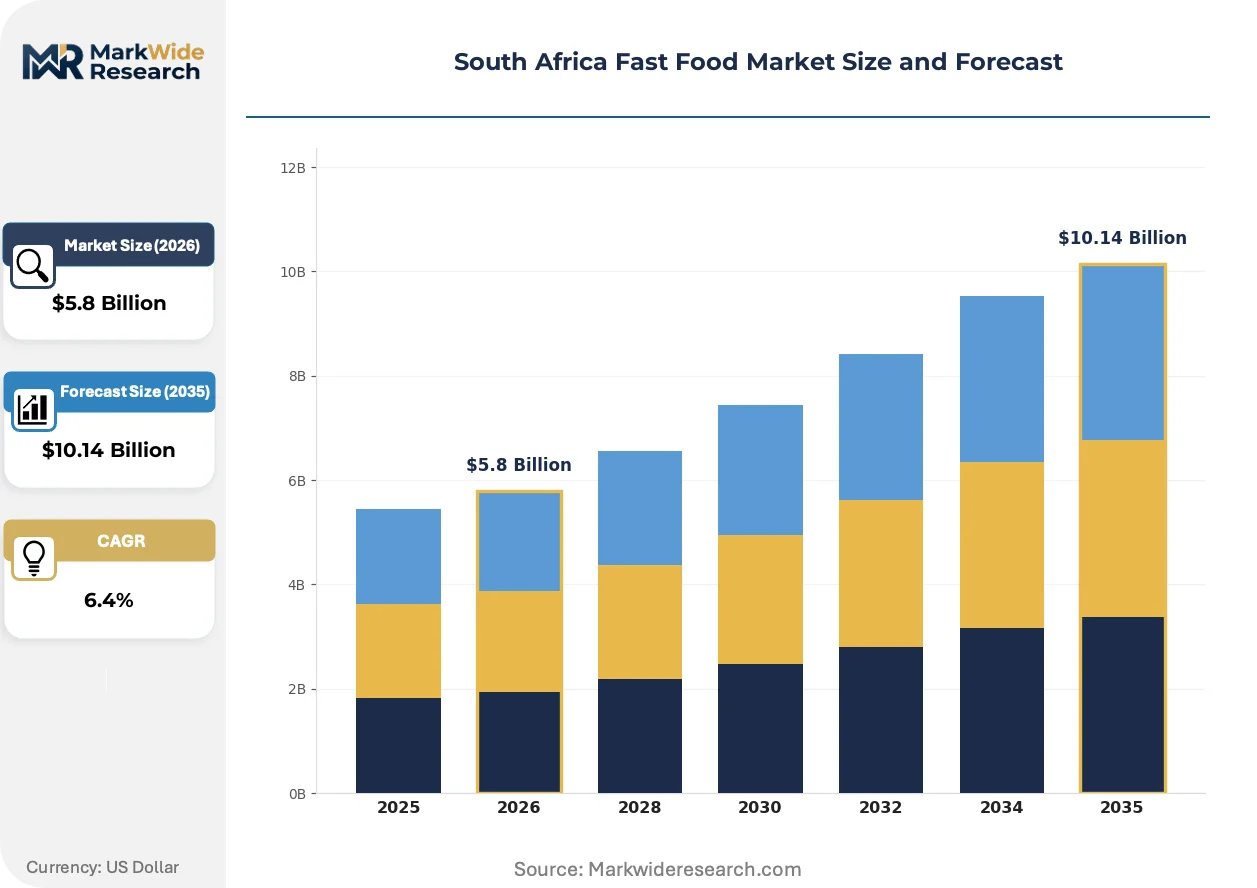
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
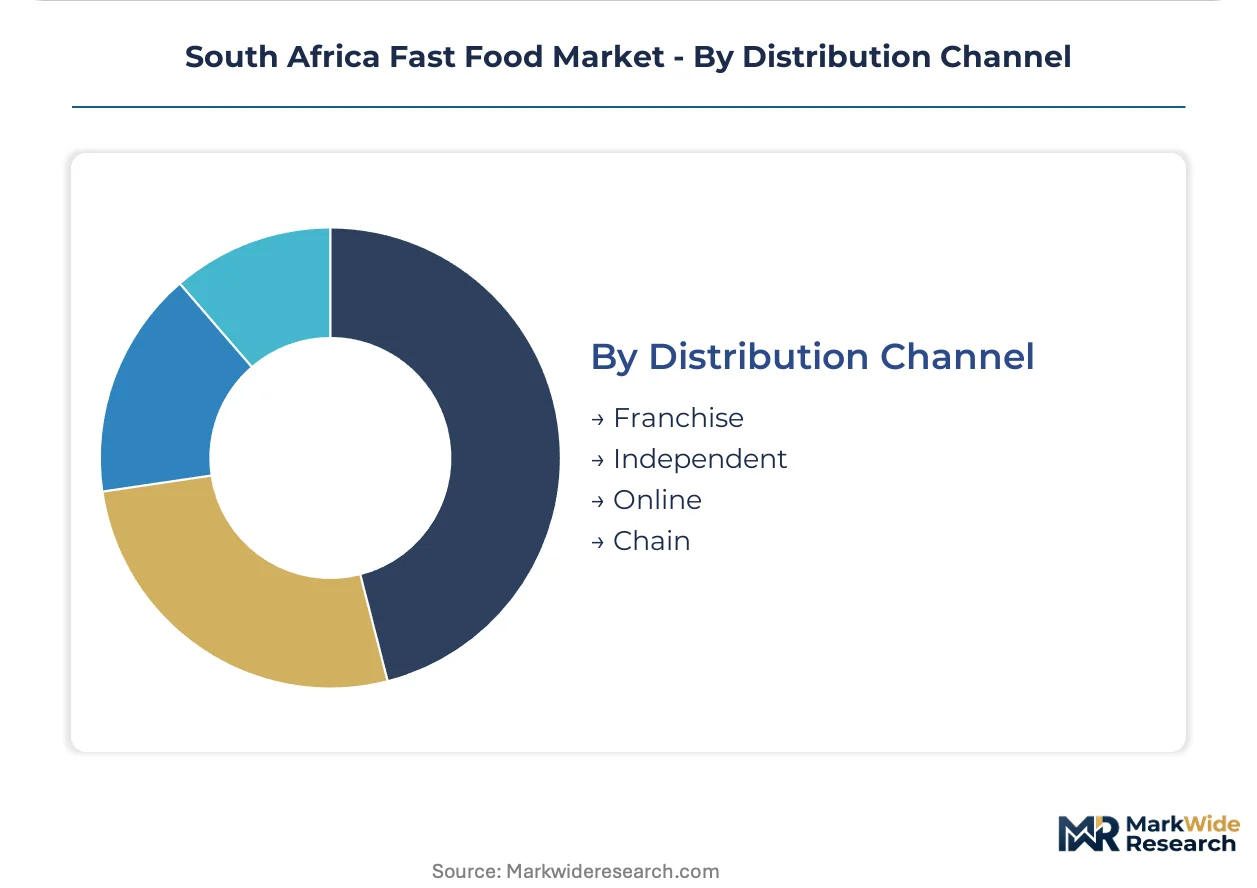
| Segmentation | Product Type: Burgers, Chicken, Pizza, Sandwiches Customer Type: Families, Young Adults, Professionals, Students Service Type: Dine-in, Takeaway, Drive-thru, Delivery Distribution Channel: Franchise, Independent, Online, Chain |
| Companies Covered | Famous Brands Inc., Burger King, McDonald's Corporation, Hungry Lion, Chicken Licken, Yum Brands Inc., Taste Holding Ltd., King Pie Holdings, Nando's Group Holding Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Fast Food Market Trends and Innovations
Automation and data-driven personalization are compressing labor costs while fragmenting how operators engage time-constrained consumers across income tiers.
Artificial intelligence-powered demand forecasting is fragmenting inventory management across the sector. Cloud-based kitchen display systems now integrate with third-party delivery APIs to synchronize preparation timing with driver arrival. Mid-sized chains in Durban and Cape Town adopt these tools fastest, compressing waste ratios and labor idle time against established metropolitan competitors.
The Department of Health's front-of-pack labeling regulations are forcing sodium reduction and calorie disclosure across all menu tiers. Manufacturers reformulate proprietary sauces and marinades to maintain taste profiles under tightened compositional limits. Family-oriented operators face the steepest adjustment curves as children's meal combinations trigger the most stringent disclosure thresholds.
Subscription-based meal plans are displacing transactional ordering among young professional segments in Johannesburg's northern suburbs. Operators bundle weekly delivery commitments with price discounts and priority scheduling. This model concentrates predictable revenue streams while fragmenting traditional peak-period demand patterns across weekday lunch and dinner slots.
South Africa Fast Food Market Segmentation
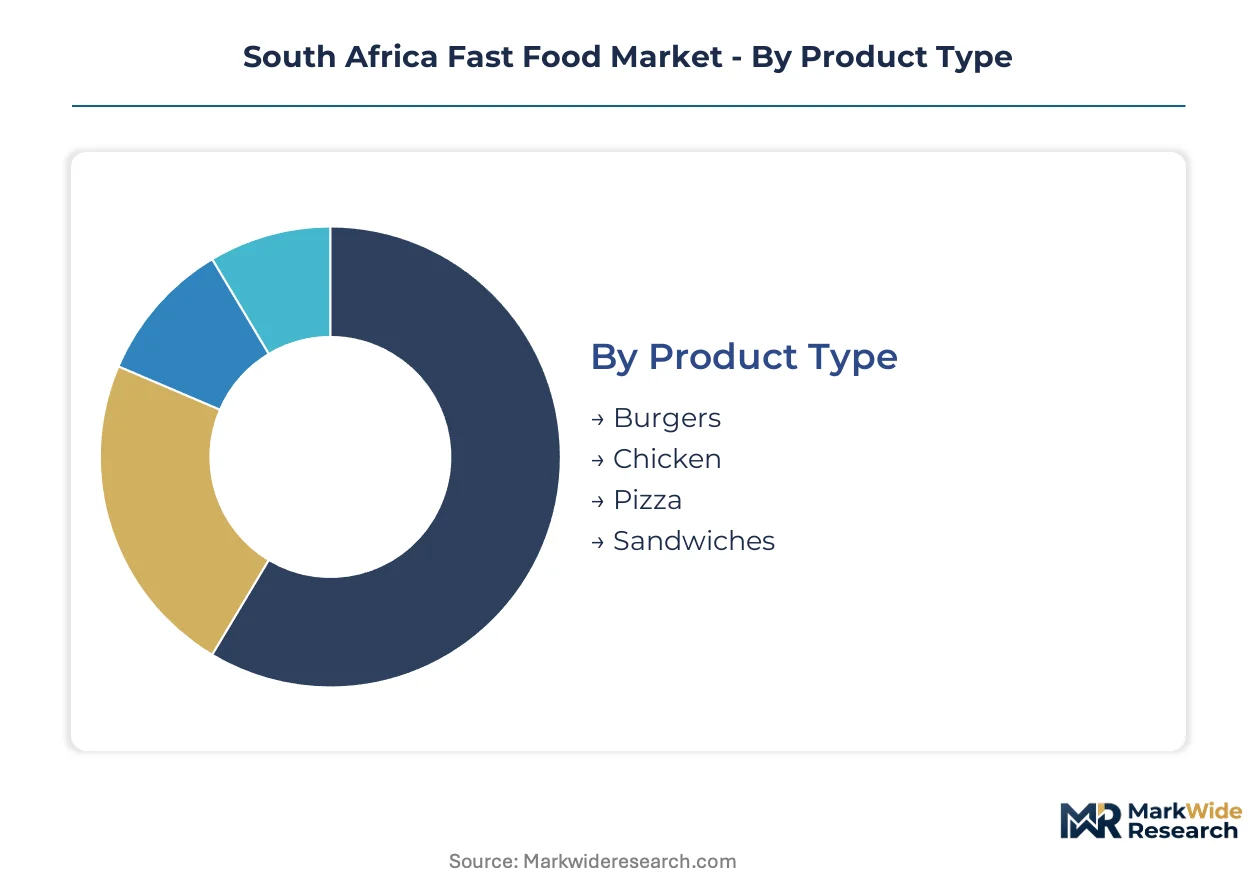
Segmentation in the South Africa fast food market reveals how protein preferences, service format expectations, and channel economics create distinct competitive battlegrounds. Operators must align capital deployment and menu engineering with the specific substitution pressures each segment faces from informal food vendors, supermarkets, and home meal preparation.
Product Type:
Chicken and burger categories face the strongest substitution threat from informal township braai vendors and supermarket rotisserie counters, forcing branded operators to differentiate through consistency and speed.
- Chicken:Flame-grilled and fried preparations dominate volume throughput across Gauteng and Western Cape metropolitan corridors. Load-shedding resilience at outlet level determines operational continuity for this perishable-intensive category. Chicken retains volume leadership; pizza holds the steepest expansion curve.
- Burgers:Standardized patty specifications and bun freshness protocols define quality positioning against independent competitors. Premium beef sourcing from Karoo and Free State ranches supports price tier differentiation in Johannesburg's northern suburbs.
- Pizza:Thin-crust and deep-pan variants concentrate demand in family-oriented suburban nodes. Debonairs Pizza's vertically integrated dough production enables margin control against franchise competitors.
- Sandwiches:Health-positioned sub chains capture lunch-hour professionals in Cape Town's CBD and Sandton financial district. Cold-chain requirements limit independent operator penetration.
Chicken commands the highest absolute throughput; pizza delivery formats are expanding most quickly through third-party platform integration.
Customer Type:
Young adult frequency patterns concentrate spending in digital-native channels, while family occasion-based demand sustains weekend peak economics across dine-in and drive-thru formats.
- Families:Weekend occasion clustering and children's meal bundling drive average transaction value in suburban mall locations. Front-of-pack labeling regulations from the Department of Health impose the strictest disclosure thresholds on this segment's menu combinations.
- Young Adults:App-based ordering and subscription meal plans displace transactional purchasing in Johannesburg and Pretoria metropolitan corridors. This cohort generates the highest per-capita order frequency through digital payment integration.
- Professionals:Time-constrained lunch demand concentrates in CBD and business park catchments with limited parking tolerance. Premium positioning through ingredient provenance supports margin capture.
- Students:Price elasticity drives value-menu concentration near university campuses in Stellenbosch, Grahamstown, and Pretoria. Combo meal engineering maximizes perceived value against limited disposable income.
Families retain volume leadership; young adults are gaining share fastest through platform-native consumption habits.
Service Type:
Delivery service expansion fragments traditional catchment boundaries, while drive-thru infrastructure requires capital intensity that advantages established chain operators.
- Delivery:Third-party logistics platforms compress fulfillment costs for township-based operators serving metropolitan demand corridors. Uber Eats and Mr D Food aggregators extend reach beyond proprietary fleet limitations.
- Drive-thru:Queue management systems and dual-lane configurations maximize throughput during peak periods in Johannesburg and Cape Town suburban nodes. Real estate requirements constrain independent operator entry.
- Takeaway:Counter service efficiency and packaging durability standards support commuter corridor positioning near transport hubs. Municipal hygiene grading systems enable quality signaling without marketing expenditure.
- Dine-in:Experience-oriented formats concentrate in mall and entertainment complex locations with extended dwell time tolerance. Family segments drive weekend utilization rates.
Drive-thru retains volume leadership; delivery climbs the fastest as platform economics mature.
Distribution Channel:
Franchise standardization creates quality consistency that independent operators struggle to replicate, while online channel growth forces legacy point-of-sale retrofitting across all tiers.
- Franchise:National Regulator for Compulsory Specifications certification requirements and supply chain standardization support multi-province expansion. Famous Brands Inc. leverages this structure across Debonairs Pizza and Steers networks.
- Chain:Corporate-owned outlets enable rapid format experimentation and pricing coordination in competitive metropolitan corridors. McDonald's Corporation anchors position through standardized cold-chain logistics.
- Independent:Flexibility in menu localization and halal certification tier selection supports niche positioning in Muslim-concentrated townships. Capital constraints limit load-shedding resilience investment.
- Online:Direct-to-consumer app development and subscription model deployment capture recurring revenue from young professional segments. Technical debt accumulates across legacy system integrations.
Franchise retains volume leadership; online channels show the steepest expansion trajectory as native digital ordering displaces telephone and walk-in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-chain logistics hubs concentrate in Gauteng and Western Cape provinces, creating supply vulnerability when load-shedding disrupts centralized distribution points. Metropolitan corridors in Johannesburg and Pretoria generate the highest transaction volumes through digital-native ordering platforms.
Gauteng Province
Young adult urbanization into Johannesburg and Pretoria corridors accelerates quick-service meal adoption among time-constrained professionals. The Department of Health's front-of-pack labeling regulations compel calorie disclosure and sodium reduction across all operator menus in this province. Sandton and Rosebank financial districts concentrate premium-positioned outlets serving lunch-hour demand with limited parking tolerance.
Western Cape
Middle-income suburbs in Cape Town's Atlantic seaboard demonstrate willingness to trial plant-based protein alternatives as health consciousness rises. Municipal health bylaws impose graded hygiene inspections that shape outlet licensing and operational continuity in metropolitan nodes. Stellenbosch university corridors attract value-menu engineering targeting price-elastic student segments.
KwaZulu-Natal
Durban's coastal positioning supports experience-oriented dine-in formats in mall and entertainment complex locations with extended dwell time tolerance. The National Regulator for Compulsory Specifications mandates food safety certifications that delay new outlet openings against franchise expansion schedules. Township-based operators leverage third-party logistics platforms to serve metropolitan demand corridors without proprietary fleet investment.
Eastern Cape
Port Elizabeth and East London corridors exhibit underpenetration in premium quick-service density relative to population growth. Municipal health grading systems create differentiation through A-grade certification display with limited competitive pressure. First-mover operators capture middle-income suburban expansion as infrastructure investment accelerates.
Mpumalanga and Limpopo
Mining corridor towns generate concentrated demand during shift-change periods with specific timing requirements for high-throughput service. Eskom grid instability forces generator and solar backup capital deployment that smaller operators struggle to fund. Nelspruit and Polokwane urban nodes attract halal-certified operators serving Muslim-concentrated consumer pools.
South Africa Fast Food Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South Africa fast food sector. Vertically integrated supply chains sustain margin control for established networks, while platform-dependent independents compete on localization flexibility. Three archetypes dominate: multinational standardizers with proprietary logistics, domestic brand aggregators with multi-format portfolios, and independent specialists with certification-tier differentiation. Competitive moves concentrate on third-party platform integration and load-shedding resilience infrastructure deployment.
Among domestic brand aggregators, Famous Brands Inc. and Taste Holding Ltd. occupy positions exemplifying multi-format portfolio strategies across pizza, burger, and quick-service categories. McDonald's Corporation anchors the multinational standardizer archetype through metropolitan cold-chain dominance. Nando's Group Holding Ltd. represents the specialist tier with flame-grilled preparation protocols commanding price premiums in suburban nodes.
| Leading Market Players |
|---|
| Famous Brands Inc. |
| Burger King |
| McDonald's Corporation |
| Hungry Lion |
| Chicken Licken |
| Yum Brands Inc. |
| Taste Holding Ltd. |
| King Pie Holdings |
| Nando's Group Holding Ltd. |
| Others |
Pricing and Supply Chain Analysis
Seventy-two-hour cold-chain freshness windows concentrate pricing power among operators with captive distribution networks, while maize and soybean futures volatility compresses margins for chicken-dominant menus. The Department of Health's front-of-pack labeling mandates add compliance costs that stratify pricing tiers between certified and uncertified supply chains.
Pricing Analysis
The Department of Health's front-of-pack labeling regulations dictates the pricing tier structure across the South Africa fast food landscape. Three-tier pricing structure across premium, standard, and economy levels separates halal-certified flame-grilled specialists from value-positioned township operators. Cost compression in the chicken category is intensifying because feed grain price spikes and avian influenza outbreaks squeeze protein margins. Students near Stellenbosch and Grahamstown campuses exhibit highest price sensitivity, while professionals in Sandton and Rosebank tolerate premium positioning through ingredient provenance claims.
Supply Chain Analysis
South Africa and Brazil anchor poultry protein supply for quick-service operators, with maize and soybean inputs drawn from domestic Free State and Mpumalanga agricultural corridors. Frozen patty specifications and proprietary sauce formulations rest on cold-chain infrastructure concentrated in Gauteng and Western Cape metropolitan hubs. Single-source vulnerability at centralized distribution points exposes multi-province operators to Eskom load-shedding disruptions. Distribution runs through vertically integrated franchise networks for Famous Brands Inc. and McDonald's Corporation, while independents rely on third-party logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as third-party platform penetration in underserved townships accelerates adoption beyond traditional drive-thru catchments.
For Market Incumbents: Consolidate cold-chain infrastructure investment in Gauteng and Western Cape hubs to defend against load-shedding operational continuity threats. Backward integration into proprietary dough production and sauce formulation protects margin control when commodity inputs spike. Certification investment in JAKIM-equivalent halal tiers unlocks previously restricted Muslim consumer pools in Western Cape and Gauteng provinces.
For New Entrants and Emerging Players: Anchor in Eastern Cape corridors where Port Elizabeth and East London exhibit underpenetration in premium quick-service density. Municipal health grading systems enable quality-signaling without marketing expenditure against limited competitive pressure. Subscription-based meal plans targeting young professionals in Johannesburg's northern suburbs offer predictable revenue capture with lower customer acquisition costs than transactional models.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across delivery-native format deployment as generator and solar backup infrastructure becomes mandatory for operational continuity. Long-term viability favors operators with balance sheet capacity for redundant power systems and proprietary app development. The signal to watch is enforcement intensity around sugar taxation proposals and plastic packaging restrictions that could restructure cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Load-Shedding Resilience Infrastructure | Generator and solar backup deployment at outlet level ensures operational continuity during Eskom grid instability. |
| Halal Certification Tier Expansion | JAKIM-equivalent accreditation unlocks Muslim consumer pools in Gauteng and Western Cape provinces. |
| Third-Party Platform Integration | Uber Eats and Mr D Food aggregation extends township-based operator reach without proprietary fleet investment. |
| Subscription Model Deployment | Weekly delivery commitments with price discounts capture predictable revenue from young professional segments. |
| Front-of-Pack Labeling Compliance | Department of Health mandates force sodium reduction and calorie disclosure across all menu tiers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of franchise operations data, municipal health inspection records, and Department of Health regulatory filings. Supply chain directors at Famous Brands Inc. and Taste Holding Ltd., outlet operators in Johannesburg and Cape Town townships, and third-party logistics platform managers provided operational perspectives. Customs records, National Regulator for Compulsory Specifications certification databases, and Eskom grid reliability reports furnished secondary validation. Bottom-up outlet counts triangulate against top-down provincial consumption estimates.
Segmentation dimensions modeled include product type, customer type, service type, and distribution channel across the projection horizon. CAGRs derive from trend extrapolation of digital platform penetration rates, urbanization patterns in metropolitan corridors, and regulatory enforcement trajectories. Chicken and burger volume throughput, pizza delivery format expansion, and young adult app-based ordering frequency constitute industry-specific forecast inputs.
Material uncertainties — avian influenza outbreaks, sugar taxation implementation timelines, and load-shedding intensity escalation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and infrastructure investment continuity. Recalibration cycles align with material shifts in Department of Health enforcement patterns and third-party platform commission structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Oman Food Service Market
Food Service
Global Dark Store Market
Food Service
Canada Food Service Market
Food Service
Commercial Cutlery Market
Food Service
Commercial Burger Grill Market
Food Service
Brazil Foodservice Market
Food Service
Food Service Pasta Market
Food Service
Chile Food Delivery Market
Food Service
Singapore Food Service Market
Food Service
Pizza Foodservice Market
Food Service
GCC Online Grocery Market
Food Service
New Zealand Foodservice Market
Food Service
Germany Foodservice Market
Food Service
Gourmet Street Food Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Supermarkets Market