
 Brazil Chocolate Market | 2026-2036
Brazil Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Chocolate Market Analysis
Multi-source cocoa bean procurement is shifting toward vertically integrated supply chains across Brazil's chocolate sector. Mars Incorporated leverages its direct farmer partnerships in Bahia to secure fine-flavor cacao volumes. Arcor S.A.I.C anchors its competitive stance through backward integration into cocoa processing and domestic sugar refining. Nestlé SA differentiates via specialized R&D facilities in Minas Gerais focused on tropical-stability formulations.
Chocolate comprises roasted and ground cacao nibs combined with cocoa butter, sugar, and emulsifiers, typically refined to particle sizes below 30 microns for smooth mouthfeel, serving confectionery, bakery, and beverage applications. Dark chocolate commands premium shelf positioning as health-conscious Brazilian consumers prioritize higher cacao-content products with reduced sugar profiles. Specialty stores represent the fastest-growing distribution channel, capturing margin pools through experiential retail and bean-to-origin storytelling that online retail cannot replicate. Milk chocolate retains volume dominance among retail consumers, though its growth rate lags behind dark and ruby chocolate variants.
ANVISA mandates strict allergen labeling and maximum contaminant thresholds for cocoa products sold in Brazil, while the Ministry of Agriculture enforces geographic indication protections for cacao from designated regions like Bahia's Diamantina Plateau. Compliance with Mercosur technical regulations shapes cross-border trade flows between Brazil and neighboring markets. Stakeholders must monitor evolving deforestation-free supply chain requirements and their impact on sourcing economics and consumer trust metrics.
Market Dynamics
ANVISA's updated food labeling mandates are compressing formulation timelines and forcing manufacturers to reconfigure supply chains around cleaner ingredient declarations, while Southeast Brazil's urban density clusters concentrate purchasing power in São Paulo and Rio de Janeiro food service channels.
Growth Catalysts
- ANVISA Allergen Transparency:Mandatory disclosure protocols for cocoa contaminants are accelerating premium product development as manufacturers compete on clean-label credentials.
- Southeast Urban Density:São Paulo and Rio de Janeiro food service operators are expanding chocolate-based dessert menus to capture concentrated purchasing power.
- Fine-Flavor Cacao Sourcing:Bahia's Diamantina Plateau geographic indication protections are creating premium tier differentiation for origin-designated chocolate products.
Market Restraints
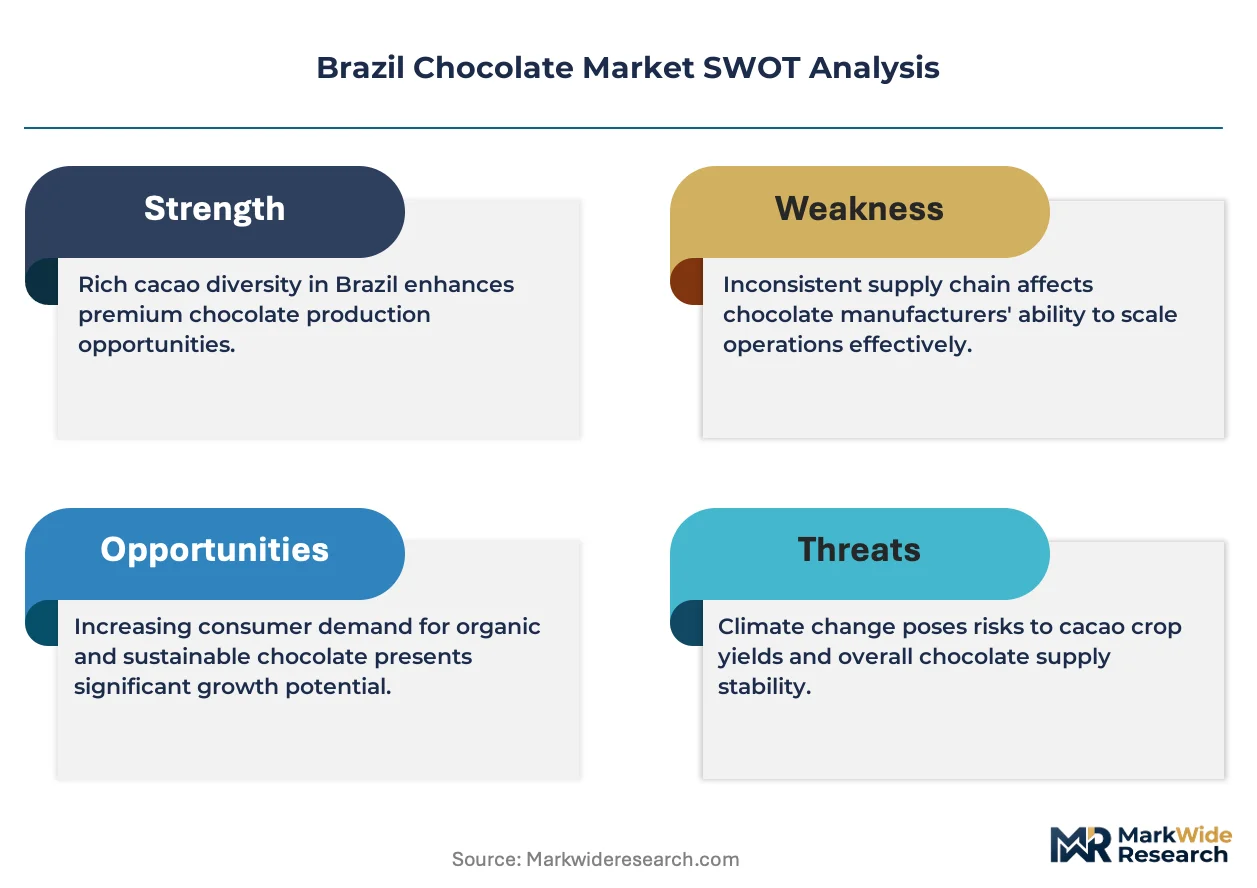
- Cocoa Butter Input Volatility:International commodity price swings for cocoa butter compress margin predictability for domestic processors.
- Deforestation-Free Supply Chain Mandates:Emerging traceability requirements for Amazon-sourced cacao are raising compliance costs and supplier qualification barriers.
- Substitution Threat from Ruby Chocolate:Nestlé's ruby chocolate formulations are capturing novelty-seeking consumers who previously purchased traditional milk chocolate.
Strategic Opportunities
- Northeast Underpenetration:Recife and Salvador retail channels present white space for specialty store expansion beyond Southeast concentration.
- Bean-to-Bar Experiential Retail:Origin storytelling and in-store roasting demonstrations are capturing margin pools that conventional supermarkets cannot replicate.
- Mercosur Cross-Border Harmonization:Technical regulation alignment with Argentina and Uruguay is reducing export friction for Brazilian processors.
Industry Challenges
- Tropical Stability Formulation Expertise:Heat-resistant chocolate chemistry requires specialized R&D talent that concentrates in Minas Gerais facilities.
- ANVISA Compliance Timeline Compression:Accelerated certification reviews for reformulated products are straining regulatory affairs bandwidth.
- Legacy ERP Integration with Traceability Systems:Blockchain-enabled supply chain tracking demands middleware investment that mid-tier processors struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Chocolate Market |
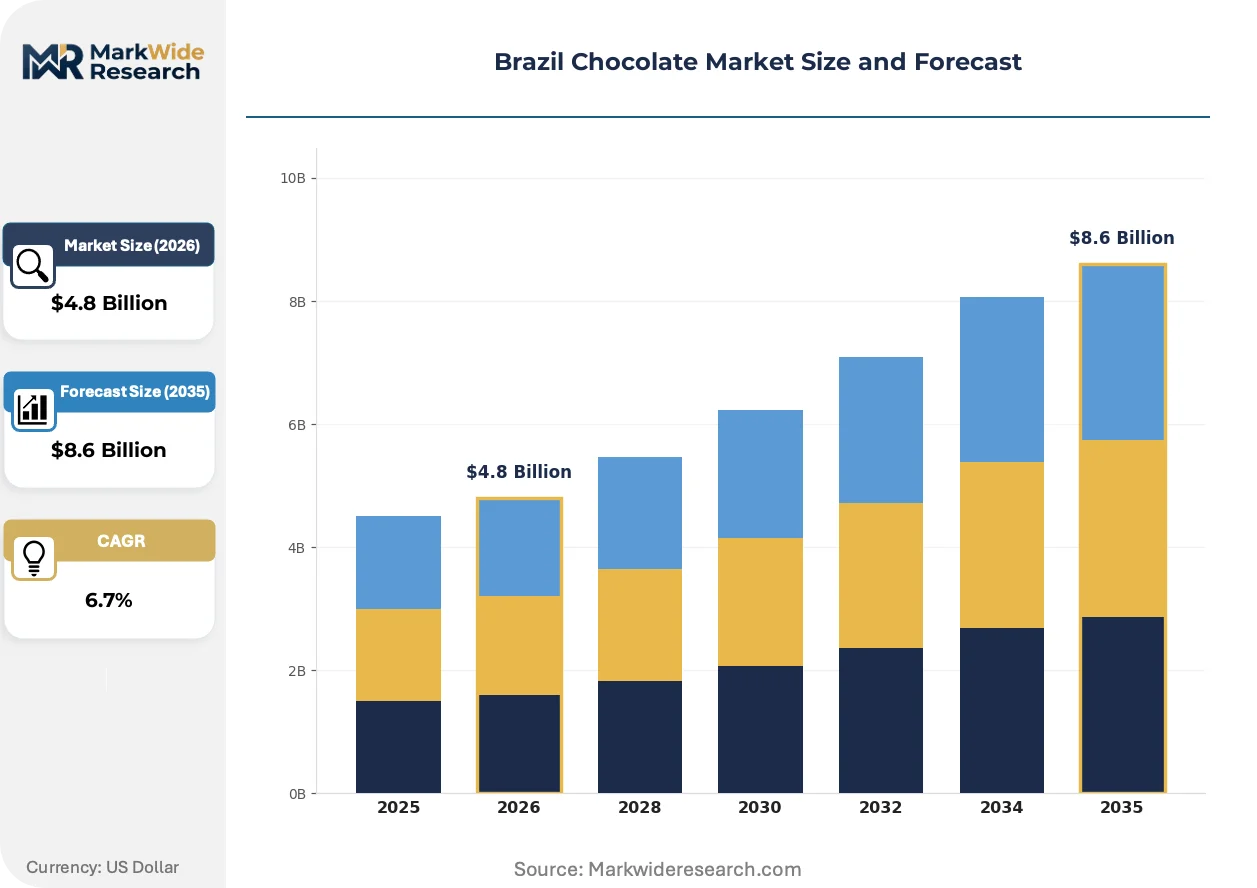
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores End User: Retail Consumers, Food Service, Manufacturers, Exporters Packaging Type: Bulk Packaging, Gift Boxes, Chocolate Bars, Eco-Friendly Packaging |
| Companies Covered | Mars Incorporated, Arcor S.A.I.C, Nestlé SA, Dengo Chocolates, The Hershey Company, Mondelez International Inc., Cacau Show, Chocoladefabriken Lindt & Sprüngli AG, Ferrero International SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Chocolate Market Emerging Trajectories
Particle size refinement below 30 microns is consolidating quality tiers as manufacturers compete on mouthfeel differentiation, while regulatory pressure on sugar content and experiential retail formats are simultaneously reshaping production and distribution architectures.
Precision conching technology is consolidating control over chocolate rheology and flavor development in Brazilian processing facilities. Mid-tier manufacturers in São Paulo state are adopting automated conching systems to match premium particle size distribution without capital intensity of fully integrated lines. This equipment diffusion is consolidating market share among processors who can guarantee sub-25 micron consistency for food service clients.
ANVISA's maximum contaminant thresholds for heavy metals in cocoa products are forcing reformulation investments across domestic manufacturing. Chocolate destined for children's product categories faces the strictest lead and cadmium limits, pushing processors toward Bahia-origin beans with naturally lower soil uptake. Compliance costs are concentrating volume among manufacturers with in-house laboratory testing capabilities.
Specialty store channels are displacing conventional supermarket dominance for premium chocolate purchases in Brazil's Southeast corridor. Bean-to-origin storytelling and in-store tasting experiences capture consumer willingness to pay price premiums that online retail cannot replicate. This channel rotation is most visible in São Paulo's Jardins and Pinheiros districts, where single-origin boutiques cluster within walking distance of affluent residential zones.
Brazil Chocolate Market Segmentation
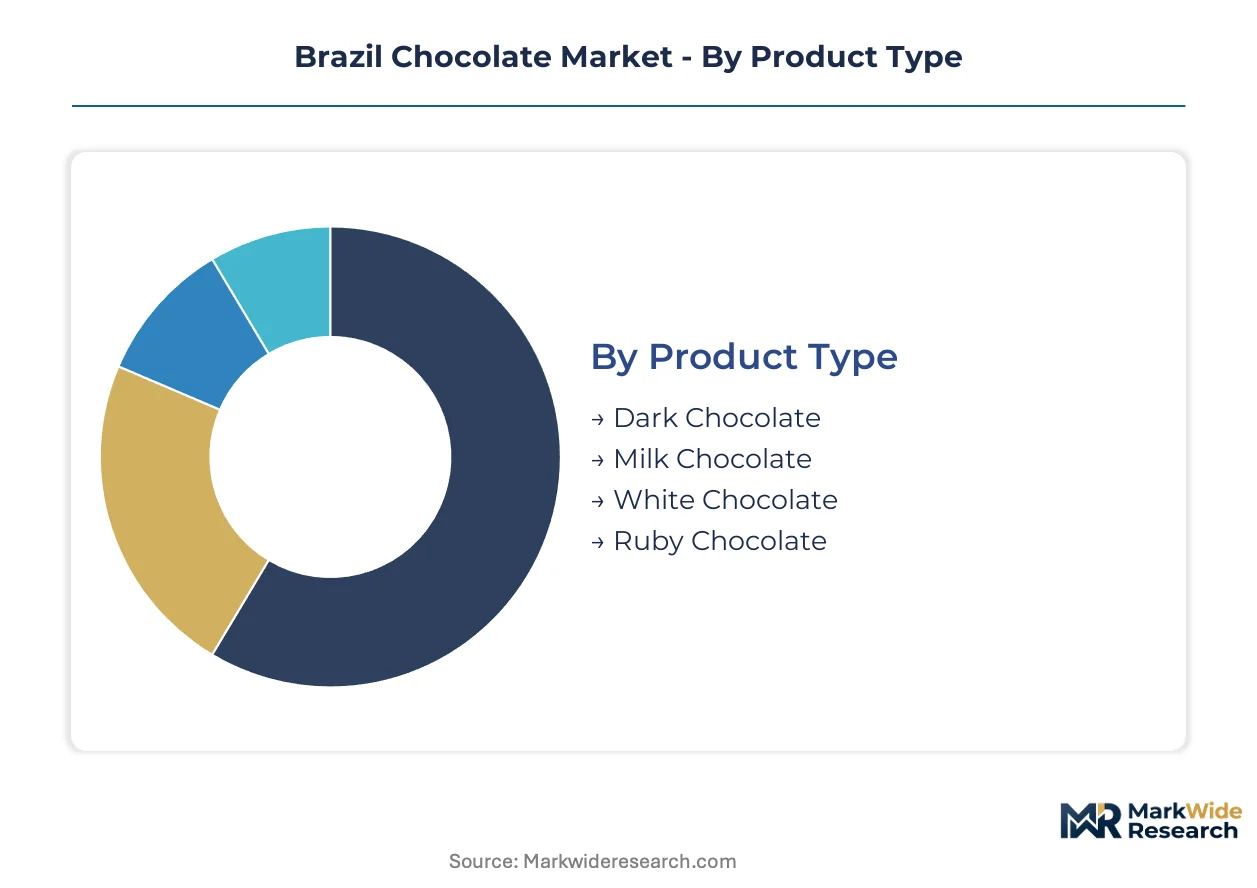
Segmentation in Brazil's chocolate market exposes how capital allocation, regulatory exposure, and channel economics diverge across product tiers and customer interfaces. Each dimension carries distinct margin structures and compliance burdens that reshape competitive positioning.
Product Type:
Capital intensity concentrates in dark chocolate manufacturing, where extended conching cycles and precision particle refinement demand dedicated equipment investments that milk chocolate lines cannot accommodate without retrofit.
- Dark Chocolate:Formulations with cacao content above 50% require specialized tempering protocols and extended conching durations to achieve sub-30 micron particle distribution. Demand clusters in São Paulo's Jardins and Pinheiros districts, where ANVISA's contaminant thresholds for heavy metals push processors toward Bahia-origin beans with lower soil uptake.
- Milk Chocolate:Standard formulations combining cocoa solids, milk powder, and sugar dominate volume throughput across retail channels. Southeast Brazil's supermarket networks anchor demand, though ruby chocolate novelty is eroding share among younger demographics in Rio de Janeiro food service.
- White Chocolate:Cocoa butter-based formulations without cocoa solids occupy a narrow premium niche in gift packaging segments.
- Ruby Chocolate:Nestlé's proprietary cultivar-derived category captures experiential retail margins through distinctive pink coloration and berry notes.
Most installed capacity flows through milk chocolate. Expansion is steepest in dark chocolate.
Distribution Channel:
Channel selection determines working capital intensity, with specialty stores requiring the highest inventory carrying costs due to SKU proliferation and origin-specific procurement.
- Specialty Stores:Bean-to-origin boutiques with in-house roasting equipment capture price premiums through experiential retail formats. São Paulo's Jardins corridor concentrates this channel, where storytelling around Diamantina Plateau provenance justifies margin structures unavailable to conventional retail.
- Supermarkets:Volume-dominant channel with standardized shelf fees and promotional calendar dependencies. Southeast urban density clusters in São Paulo and Rio de Janeiro drive throughput, though specialty store encroachment is compressing premium-tier space allocation.
- Online Retail:Logistics constraints around temperature-controlled fulfillment limit penetration in tropical climates.
- Convenience Stores:Impulse-driven single-serve formats with localized replenishment cycles.
Supermarkets retain the deepest installed base. Specialty stores are climbing the fastest.
End User:
Customer type segmentation maps directly to formulation complexity and certification requirements, with food service demanding the most customized product development resources.
- Food Service:Dessert menu integration across São Paulo and Rio de Janeiro operators requires tropical-stability formulations and consistent rheological profiles for plating applications. ANVISA allergen disclosure mandates add documentation overhead that retail channels avoid.
- Retail Consumers:Packaged goods purchasers with preference fragmentation across health-positioned dark chocolate and conventional milk variants. Southeast purchasing power clusters concentrate volume.
- Manufacturers:Industrial chocolate users in bakery and confectionery applications with specification-driven procurement.
- Exporters:Mercosur-aligned cross-border shippers navigating technical regulation harmonization with Argentina and Uruguay.
Retail consumers absorb the largest capacity share. Food service is gaining share fastest.
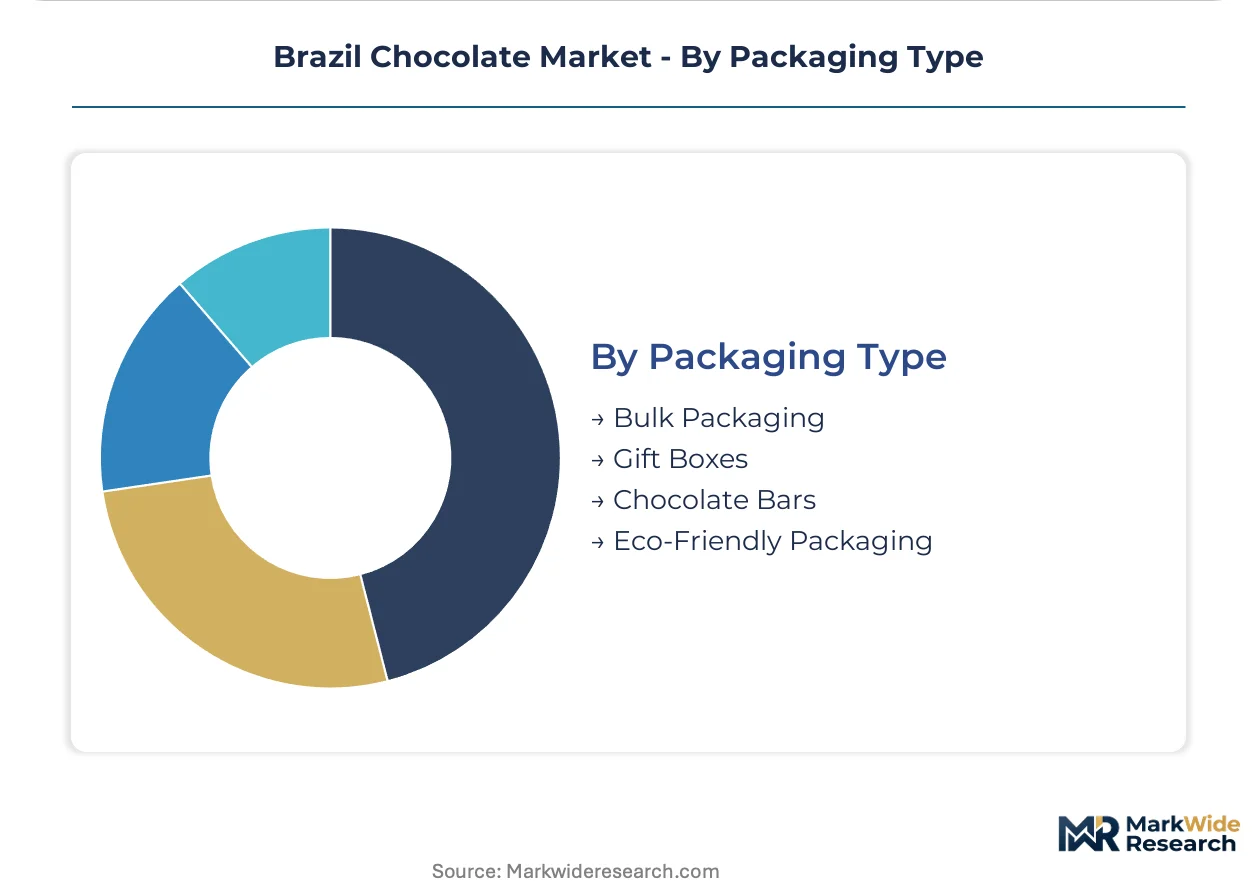
Packaging Type:
Packaging economics split between commodity-scale bulk operations and value-added formats where design and sustainability credentials command premium positioning.
- Eco-Friendly Packaging:Biodegradable and recyclable materials addressing ANVISA-adjacent consumer pressure and deforestation-free supply chain narratives. São Paulo specialty stores mandate this format for shelf placement.
- Gift Boxes:Seasonal and occasion-driven formats with highest margin per kilogram, concentrated in Southeast urban centers during calendar peaks.
- Chocolate Bars:Standard retail format with established price points across supermarket channels.
- Bulk Packaging:Industrial-scale formats for food service and manufacturer segments with minimal value-add.
Chocolate bars move the most volume. Eco-friendly packaging is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Brazil's chocolate demand through concentrated purchasing power and food service density. Southeast urban clusters generate volume concentration unmatched elsewhere. State-level regulatory enforcement varies across ANVISA's national framework.
São Paulo
Jardins and Pinheiros districts concentrate specialty store proliferation and bean-to-origin retail formats. ANVISA's allergen disclosure mandates compress formulation timelines for local manufacturers. Precision conching technology adoption clusters in São Paulo state processing facilities serving food service clients.
Rio de Janeiro
Food service operators expand chocolate dessert menus across upscale neighborhoods. The state's consumer protection enforcement adds documentation layers beyond federal ANVISA requirements. Copacabana and Ipanema retail corridors drive premium chocolate throughput in experiential formats.
Minas Gerais
Specialized R&D facilities concentrate tropical-stability formulation expertise unavailable elsewhere. State-level agricultural extension programs support cacao cultivar development. Belo Horizonte anchors industrial chocolate processing capacity for bakery and confectionery supply.
Bahia
Diamantina Plateau geographic indication protections create premium tier differentiation for origin-designated products. Federal Ministry of Agriculture enforcement shields designated cacao regions from generic competition. Ilhéus processing clusters handle fine-flavor bean volumes for export and domestic specialty channels.
Rio Grande do Sul
Underpenetrated retail channels present white space for specialty store expansion beyond Southeast concentration. State-level environmental regulations align with emerging deforestation-free supply chain mandates. Porto Alegre's food service sector demands consistent rheological profiles for plated dessert applications.
Brazil Chocolate Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue experiential retail and origin-designated positioning. Mars Incorporated, Nestlé SA, and Mondelez International anchor volume throughput through supermarket and convenience networks. Three archetypes dominate: vertically integrated cocoa processors controlling Bahia supply chains, R&D-focused multinationals with tropical formulation patents, and bean-to-bar specialists capturing margin through storytelling. Competitive moves concentrate on backward integration into cocoa processing and specialty store channel expansion.
Among multinational CPG conglomerates, Mars Incorporated and Nestlé SA exemplify scale-driven archetypes with captive supply arrangements, while Mondelez International occupies a position bridging mass-market distribution and premium portfolio diversification. Arcor S.A.I.C represents Latin American regional specialists with integrated sugar refining capabilities. Cacau Show and Dengo Chocolates anchor the domestic specialist tier, with the former exemplifying retail format innovation and the latter representing bean-to-bar provenance positioning.
| Leading Market Players |
|---|
| Mars Incorporated |
| Arcor S.A.I.C |
| Nestlé SA |
| Dengo Chocolates |
| The Hershey Company |
| Mondelez International Inc. |
| Cacau Show |
| Chocoladefabriken Lindt & Sprüngli AG |
| Ferrero International SA |
| Others |
Supply Flow & Price Mechanics
Precision conching technology adoption across São Paulo state processing facilities is compressing production cost curves while simultaneously concentrating capacity among manufacturers who can guarantee sub-25 micron consistency. This equipment diffusion rewards scale players with quality-tier access that mid-tier processors cannot match, reshaping margin distribution across dark chocolate and milk chocolate categories.
Pricing Analysis
Input-cost pass-through from cocoa butter commodity volatility runs through formulation economics, with international price swings compressing margin predictability for domestic processors lacking backward integration. Three-tier pricing structure across premium, standard, and economy levels separates bean-to-origin specialty products from mass-market milk chocolate and private-label economy tiers. Pricing pressure stems from ruby chocolate novelty capturing novelty-seeking consumers who previously purchased traditional milk variants. Food service operators show least price sensitivity due to menu price elasticity, while retail consumers in supermarket channels exhibit highest sensitivity to promotional calendar dependencies.
Supply Chain Analysis
Reverse-logistics flows for temperature-controlled chocolate returns are minimal given perishability constraints, though specialty store channels manage small-batch refurbishment of seasonal gift inventory. Geographic supply concentration draws from Bahia's Diamantina Plateau for fine-flavor cacao, West African origins for bulk cocoa butter, and domestic sugar refining in São Paulo state. Raw material dependencies rest on cocoa butter, milk powder, and emulsifier inputs. Single-source vulnerability from Amazon-sourced cacao traceability requirements poses structural risk as deforestation-free mandates raise supplier qualification barriers. Distribution runs through supermarket networks for volume, with specialty stores capturing premium-tier throughput in São Paulo and Rio de Janeiro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Brazil's chocolate sector hinges on precision conching technology lowering unit costs for quality-tier access, while specialty store channel rotation enables premium pricing power unavailable to conventional retail.
For Market Incumbents: Anchor defensive positioning through backward integration into Bahia cocoa processing and captive supply arrangements with Diamantina Plateau growers. Invest in Minas Gerais R&D facilities for tropical-stability patent protection against Nestlé's formulation lead. Ruby chocolate substitution threat demands accelerated premium dark chocolate portfolio expansion. For New Entrants and Emerging Players: Capture white space in Recife and Salvador specialty store channels where origin storytelling around Northeast cacao cultivars remains underdeveloped. Target food service dessert menu integration in Rio Grande do Sul's underpenetrated upscale dining segment. Lead with bean-to-bar experiential retail formats that supermarkets cannot replicate. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier processors lacking in-house laboratory testing capabilities for ANVISA heavy metal compliance. Long-term viability favors vertically integrated players with Bahia supply chain control and specialty store distribution relationships. Monitor ANVISA enforcement intensity for children's product lead and cadmium thresholds as margin compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cocoa Processing | Captive supply from Bahia's Diamantina Plateau insulates margin from international cocoa butter volatility. |
| Specialty Store Channel Expansion | Bean-to-origin boutiques in São Paulo's Jardins corridor capture price premiums through experiential retail formats. |
| Tropical-Stability R&D Investment | Minas Gerais formulation patents protect food service market share against heat-resistant chocolate competitors. |
| ANVISA Compliance Infrastructure | In-house laboratory testing capabilities concentrate volume among manufacturers meeting children's product contaminant thresholds. |
| Mercosur Export Harmonization | Technical regulation alignment with Argentina and Uruguay reduces cross-border friction for processed chocolate shipments. |
Methodological Framework
Bottom-up food service and retail consumer modeling reconciled against top-down cocoa bean procurement tracking forms the analytical core of this study. Primary interviews with brand managers at multinational CPG conglomerates, category buyers at São Paulo supermarket networks, supply planners at domestic processors, and channel sales heads at specialty store operators combined with secondary validation. Secondary sources include ANVISA regulatory filings, Ministry of Agriculture geographic indication records, Mercosur technical regulation databases, and customs trade data for cocoa bean imports. Triangulation between demand-side consumption patterns and supply-side processing capacity ensures consistency across volume estimates.
Input-output matrix framing connects cocoa butter input costs, conching equipment utilization rates, and channel-specific price realization across product type, distribution channel, end user, and packaging type segmentation dimensions. CAGRs derive from regression analysis against historical volume trajectories and projected demand elasticity parameters. Industry-specific forecast inputs include ANVISA compliance timeline acceleration and specialty store square footage expansion in Southeast urban corridors.
Cocoa butter commodity price spikes, ANVISA enforcement intensity escalation, and deforestation-free supply chain mandate expansion are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around regulatory stability and consumer preference persistence without explicit scenario weighting. Practitioners should monitor international cocoa futures volatility, ANVISA children's product threshold announcements, and Amazon basin traceability system deployment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Confectionery Coating Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
Truffle Chocolate Market
Confectionery
Japan Chocolate Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Chocolate Flavors Market
Confectionery
Caramel Market
Confectionery
Global Chocolate Market
Confectionery
Coffee Gummy Market
Confectionery
Chocolate Couverture Market
Confectionery
Global Confectionery Market
Confectionery
North America Chocolate Confectionery Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
UK Confectionery Market
Confectionery
South Africa Confectionery Market
Confectionery
Asia Pacific Sugar Confectionery Market