
 Low Calorie Granola Market | 2026-2036
Low Calorie Granola Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Granola Market Analytics
Clean-label sweetener technology is narrowing the taste gap between reduced-calorie and conventional granola formulations. Bob's Red Mill leverages its vertically integrated milling operations to control oat and seed sourcing costs. General Mills sustains mass-market penetration through Nature Valley's established grocery distribution network. Purely Elizabeth differentiates with certified organic and grain-free ingredient positioning that commands premium placement in health food stores.
Low calorie granola denotes baked cereal products formulated with reduced caloric density through controlled fat content, alternative sweeteners such as monk fruit or allulose, and high-fiber base grains typically processed through extrusion or conventional oven baking to achieve crispy texture with minimal added oils. Clusters dominate shelf-stable formats due to superior bowl retention and yogurt parfait compatibility, while bars capture on-the-go consumption occasions among fitness professionals seeking portion-controlled energy. Online retailers represent the fastest-expanding distribution vector as direct-to-consumer subscription models bypass traditional slotting fee barriers and capture repeat purchase data from weight watcher segments.
FDA nutrition labeling requirements and EU health claims regulation under EFSA scrutiny constrain permissible marketing language around calorie reduction and weight management benefits. USDA organic certification and Non-GMO Project verification function as de facto market access requirements for premium positioning in North American health food channels. Stakeholders must monitor evolving added-sugar disclosure mandates across multiple jurisdictions, as front-of-package warning systems threaten conventional formulation architectures and reward early movers with compliant product pipelines.
Market Dynamics
Clean-label sweetener technology is collapsing the taste-performance gap that historically protected conventional granola formulations, forcing incumbents to reformulate or surrender premium shelf positioning to compliant competitors.
Growth Catalysts
- FDA Added-Sugar Disclosure Mandates:Front-of-package labeling requirements are accelerating manufacturer migration toward monk fruit and allulose formulations to maintain permissible health claims.
- Fitness-Professional Snacking Routines:Urban millennials in New York, Los Angeles, and Chicago are integrating portion-controlled granola clusters into pre-workout and post-workout nutrition protocols.
- Extrusion Technology Advancement:High-pressure extrusion systems now achieve crispy texture profiles with 40% less added oil than conventional oven baking.
Market Restraints
- Oat and Seed Input Volatility:Weather-driven supply fluctuations in Canadian prairie provinces and Ukrainian grain corridors compress margin predictability for North American processors.
- EU EFSA Health Claims Scrutiny:Strict evidentiary requirements for calorie-reduction marketing language block cross-border label standardization.
- Protein Bar Substitution:Shelf-stable protein bars with comparable portability and superior macronutrient density capture overlapping consumption occasions.
Strategic Opportunities
- Direct-to-Consumer Subscription Channels:Bypassing traditional grocery slotting fees enables margin capture and first-party data accumulation from weight management segments.
- USDA Organic Certification Tailwinds:Federal procurement preferences and retailer placement incentives reward early organic pipeline investment.
- Grain-Free Formulation Convergence:Combining sprouted seed bases with alternative sweeteners opens placement in paleo and ketogenic retail sets.
Industry Challenges
- Clean-Label Reformulation Timelines:Achieving FDA-compliant Nutrition Facts panels while maintaining 12-month shelf stability demands extended R&D cycles.
- Non-GMO Project Verification Backlogs:Third-party audit capacity constraints delay market access for premium-positioned entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Granola Market |
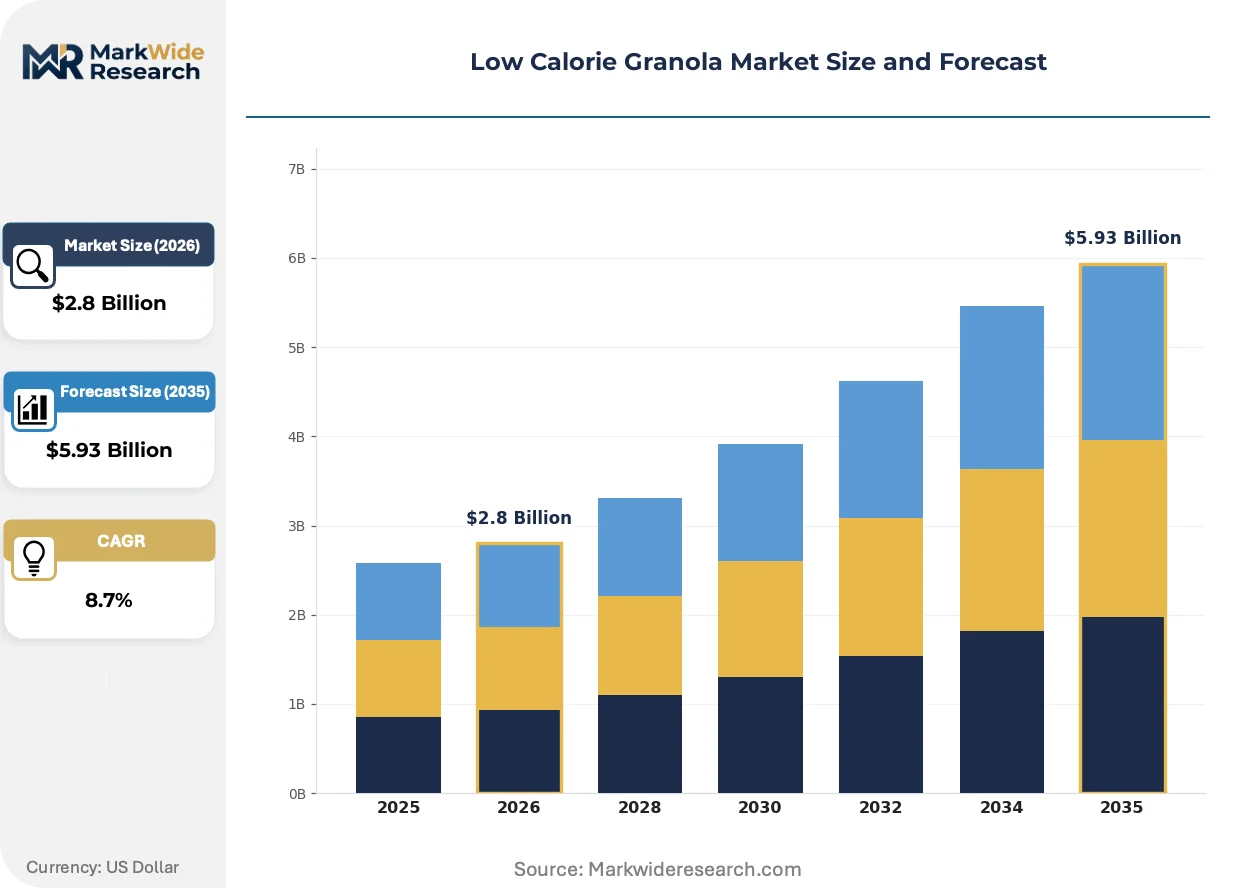
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clusters, Bars, Flakes, Cookies Ingredient Type: Nuts, Seeds, Whole Grains, Dried Fruits Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores Target Consumer: Health Enthusiasts, Weight Watchers, Fitness Professionals, Busy Professionals |
| Companies Covered | Bob's Red Mill, Struesli, Go Raw, Purely Elizabeth, Paleonola, Nature Valley, General Mills, Nestlé, Brekky Mix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Granola Market Evolving Landscape
Alternative sweetener technology and extrusion processing are converging to eliminate the formulation trade-offs that previously forced manufacturers to choose between clean-label compliance and sensory performance.
Allulose and monk fruit extract blends are collapsing the caloric density threshold for crispy granola texture without the cooling aftertaste that plagued earlier stevia formulations. Health-conscious consumers in Austin, Denver, and Seattle are adopting these reformulated products at rates that outpace conventional granola in matched store sets. This technology is collapsing the premium price umbrella that protected legacy brands with conventional sugar architectures.
EU F-Gas Regulation and accompanying EFSA added-sugar surveillance are forcing reformulation investments ahead of 2025 compliance deadlines. Manufacturers targeting German, French, and Dutch retail banners must submit revised ingredient declarations or face delisting from health-food channel planograms. Premium private-label suppliers are responding by accelerating organic certification timelines to maintain placement in Aldi Süd and Edeka banners.
Subscription-based replenishment models are displacing conventional impulse purchasing in urban professional segments. Direct-to-consumer platforms capture repeat purchase data that enables flavor customization and portion-size tailoring unavailable through grocery intermediaries. This behavioral shift concentrates in coastal metropolitan markets where delivery density supports economically viable last-mile logistics.
Low Calorie Granola Market Segmentation
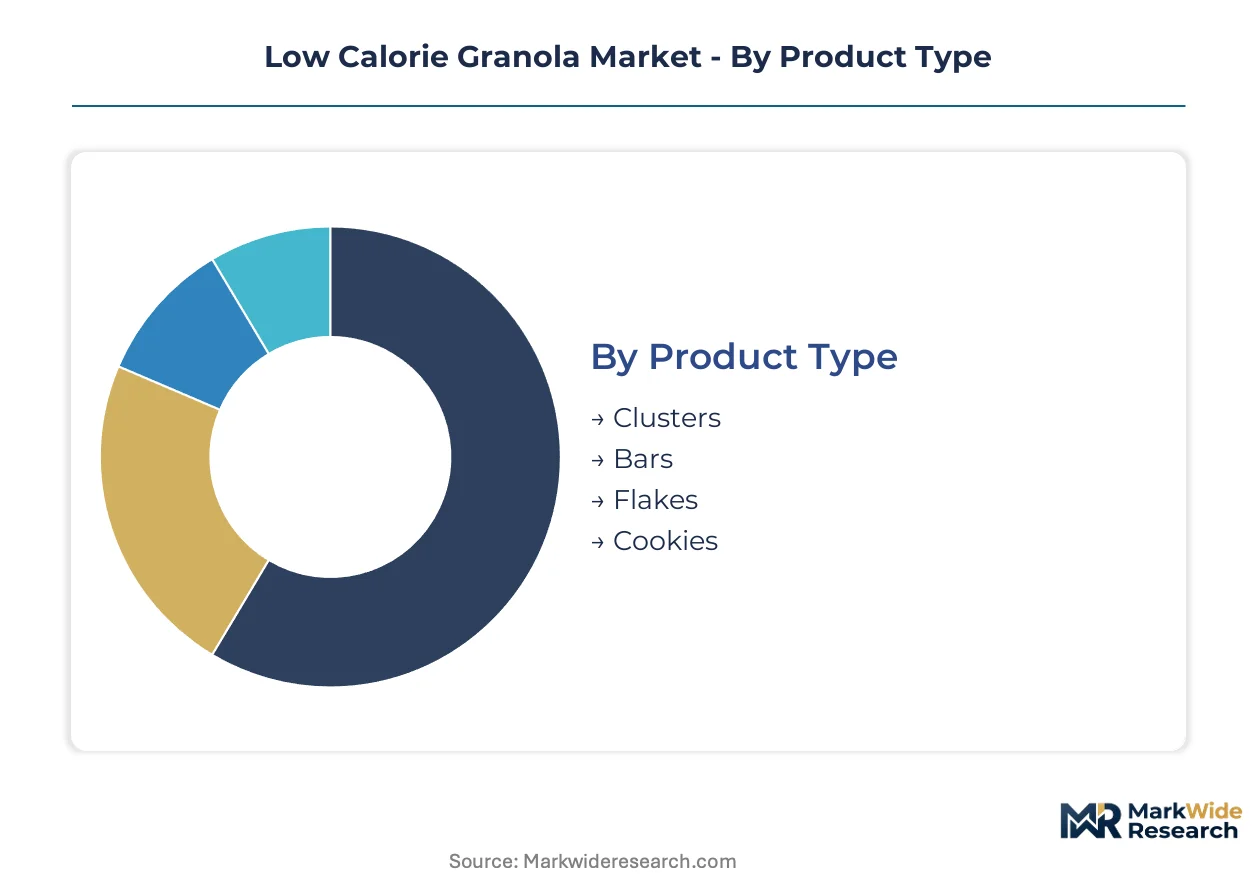
Granola manufacturers align formulation architecture and channel strategy against distinct consumption rituals. Each segmentation axis reveals divergent margin structures and regulatory exposure profiles that determine competitive viability.
Product Type:
Mature clusters coexist with emerging bar formats as manufacturers balance shelf stability against portability demands.
- Clusters:Baked aggregate formations of rolled oats, seeds, and binding syrups processed through rotary oven or extrusion methods. Bowl retention properties drive placement in dairy and yogurt parfait applications across United States conventional grocery sets.
- Bars:Compressed and thermoformed portions delivering portion-controlled caloric loads for pre-workout consumption. Fitness professionals in Los Angeles and New York metropolitan corridors adopt these for commute-compatible energy intake.
- Flakes:Thin-sheet cereal substrates with reduced cluster density for milk-pour applications. European retailers favor these for breakfast cereal aisle adjacency.
- Cookies:Cookie-format baked goods incorporating granola textures and reduced-sweetener binding systems. Emerging placement in grab-and-go bakery sections targets impulse purchasing occasions.
Clusters retain volume leadership; bars hold the steepest expansion curve.
Ingredient Type:
Cost tier separation between commodity grain bases and premium tree nut inclusions shapes procurement strategy and certification requirements.
- Nuts:Almond, pecan, and walnut inclusions delivering protein density and satiety signaling. California almond handlers supply processors with pasteurized kernels meeting USDA organic and Non-GMO Project specifications for premium channel placement.
- Seeds:Pumpkin, sunflower, and chia seed components offering allergen-friendly protein alternatives. Sprouted seed processing opens paleo and ketogenic retail positioning in Denver and Austin specialty stores.
- Whole Grains:Rolled oat, quinoa, and amaranth substrates providing fiber bulk and extrusion compatibility. Canadian prairie oat supplies face weather-driven volatility affecting North American processor margins.
- Dried Fruits:Cranberry, blueberry, and date inclusions contributing natural sweetness and moisture retention. EU EFSA added-sugar surveillance constrains permissible fruit concentrate levels in health claims marketing.
Whole grains dominate volume throughput; seeds gain share fastest in premium positioning.
Distribution Channel:
Geographic concentration of purchasing power determines slotting fee tolerance and private-label penetration depth.
- Supermarkets:Conventional grocery banners including Kroger and Whole Foods Market commanding mass-market volume. Clean-label reformulation mandates under FDA nutrition labeling requirements accelerate shelf resets in these channels.
- Online Retailers:Direct-to-consumer and third-party marketplace platforms capturing subscription replenishment models. First-party data accumulation enables flavor customization unavailable through brick-and-mortar intermediaries.
- Health Food Stores:Independent and bannered specialty retailers requiring USDA organic certification as de facto market access condition. Placement here signals premium positioning to health-conscious urban millennials.
- Convenience Stores:C-store chains targeting impulse and travel-oriented consumption with single-serve bar formats. Portion-controlled packaging aligns with grab-and-go occasion requirements.
Supermarkets maintain volume concentration; online retailers expand most quickly through subscription capture.
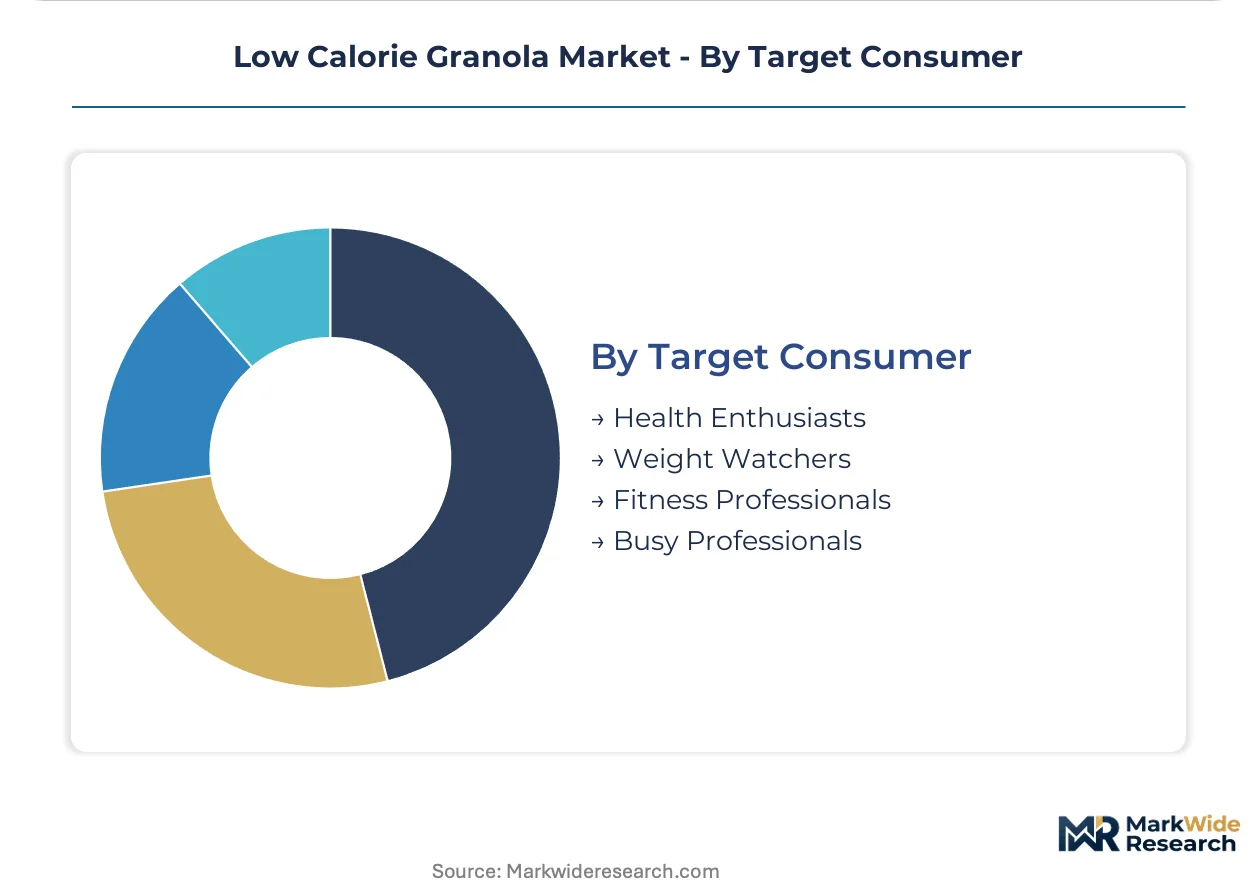
Target Consumer:
Customer type segmentation maps distinct nutritional protocols against product architecture and messaging frameworks.
- Health Enthusiasts:Consumers prioritizing clean-label ingredient transparency and organic certification. These buyers drive demand for monk fruit and allulose formulations in coastal metropolitan markets.
- Weight Watchers:Calorie-conscious purchasers seeking portion-controlled formats with explicit nutritional accounting. Direct-to-consumer subscription models capture repeat purchase loyalty from this segment.
- Fitness Professionals:Athletes and trainers integrating granola into structured pre-workout and post-workout nutrition protocols. Protein density and macronutrient clarity determine brand selection.
- Busy Professionals:Time-constrained urban workers prioritizing portability and shelf stability over preparation requirements. Bar formats dominate this occasion set.
Health enthusiasts anchor premium pricing; fitness professionals drive the steepest volume trajectory in urban corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious urban millennials concentrate purchasing power in coastal metropolitan corridors, while regulatory divergence between FDA and EFSA frameworks forces parallel formulation strategies for cross-border suppliers.
United States
Fitness professionals in New York and Los Angeles drive cluster-format adoption through pre-workout snacking rituals. FDA added-sugar disclosure mandates under Nutrition Facts Label revisions compel reformulation toward monk fruit and allulose architectures. Austin and Denver specialty retailers anchor grain-free positioning for paleo and ketogenic consumer segments.
Germany
Clean-label enthusiasts in Berlin and Munich prioritize organic certification and transparent ingredient sourcing. EU F-Gas Regulation and EFSA added-sugar surveillance enforce stringent reformulation deadlines ahead of 2025 compliance windows. The Rhine-Ruhr industrial corridor hosts extrusion technology suppliers serving reformulation demands across Central European processing facilities.
United Kingdom
Subscription-model adoption concentrates among London professionals seeking portion-controlled replenishment. UK Food Standards Agency labeling requirements align with EU health claims scrutiny while maintaining post-Brexit regulatory autonomy. Manchester and Birmingham distribution hubs facilitate direct-to-consumer fulfillment density for weight management segments.
Canada
Prairie oat supply volatility from Saskatchewan and Alberta compresses margin predictability for North American processors. Health Canada nutrition labeling regulations mirror FDA frameworks while permitting distinct organic certification pathways. Toronto and Vancouver metropolitan markets anchor premium private-label placement in Loblaw and Whole Foods Market banners.
Australia
Grain-free formulation demand accelerates in Sydney and Melbourne wellness-oriented retail channels. Food Standards Australia New Zealand maintains added-sugar disclosure requirements that reward early clean-label adopters. The Murray-Darling basin supplies sprouted seed inputs for allergen-friendly product architectures targeting export markets.
Low Calorie Granola Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered shelf-space allocations. Mass-market penetration demands grocery distribution scale, while premium positioning requires organic certification and health-food channel credibility. Three archetypes dominate: legacy cereal conglomerates with established slotting relationships, vertically integrated natural food specialists with captive ingredient sourcing, and direct-to-consumer subscription platforms with first-party data advantages. Competitive moves concentrate on clean-label reformulation speed and direct-to-consumer subscription capture.
Within the vertically integrated specialist tier, Bob's Red Mill and Purely Elizabeth exemplify archetypes built on ingredient sourcing control and certified organic positioning respectively. General Mills occupies the mass-market penetration position through Nature Valley's established grocery network. These three anchors illustrate the strategic divergence between upstream supply control, premium certification signaling, and distribution scale economics.
| Leading Market Players |
|---|
| Bob's Red Mill |
| Struesli |
| Go Raw |
| Purely Elizabeth |
| Paleonola |
| Nature Valley |
| General Mills |
| Nestlé |
| Brekky Mix |
| Others |
Value Network & Pricing Analysis
Canadian prairie oat supply volatility determines both the premium-to-economy pricing spread across North American granola tiers and the geographic shape of upstream procurement networks. Weather-driven yield compression in Saskatchewan and Alberta forces processors to either absorb margin erosion or pass through cost spikes, compressing mid-tier pricing umbrellas while reinforcing premium organic positioning.
Pricing Analysis
Cost-plus contracts with Chicago Board of Trade oat futures indexation dominate procurement agreements between Canadian grain handlers and North American processors. Pricing stratifies across premium USDA organic, standard clean-label, and economy conventional tiers, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from Ukrainian grain corridor disruptions elevating global oat substitute costs. Weight watchers through direct-to-consumer channels exhibit highest price sensitivity, while fitness professionals in coastal metros tolerate premium positioning.
Supply Chain Analysis
Export-control regimes under EU F-Gas Regulation restrict extrusion technology transfers to non-compliant processing facilities, fragmenting equipment sourcing. Supply concentrates in Canada, the United States, and Ukraine for oat inputs, with California almond handlers and Chinese monk fruit extract suppliers as critical secondary dependencies. Single-source vulnerability centers on Canadian prairie oat monoculture exposure to drought cycles. Distribution runs through Kroger and Whole Foods Market banners for mass-market volume, with direct-to-consumer platforms capturing fastest expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label reformulation expertise functions as the scarce capability separating viable competitors from delisted suppliers, with monk fruit and allulose formulation chemistry representing the binding constraint.
For Market Incumbents: Harden defensible positioning through backward integration into sprouted seed processing in Denver and Austin corridor facilities, insulating against Canadian oat volatility. Accelerate FDA-compliant Nutrition Facts panel R&D cycles ahead of added-sugar disclosure mandate enforcement, preserving shelf placement against compliant private-label entrants. For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting weight watcher segments in London and New York metropolitan markets, where delivery density supports viable unit economics. Capture first-party consumption data for flavor customization unavailable through grocery intermediaries, establishing switching costs before incumbent platform replication. For Investors and Strategic Acquirers: The market sits at a regulatory-compliance phase that favors early organic pipeline investors with verified Non-GMO Project status. Long-term viability across the projection horizon hinges on extrusion technology ownership and certified clean-label formulation libraries. Monitor EU EFSA added-sugar surveillance enforcement strictness as the inflection signal for cross-border label standardization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Acceleration | Monk fruit and allulose adoption preserves FDA health claims eligibility against added-sugar disclosure mandates. |
| Direct-to-Consumer Subscription Launch | First-party data capture from weight watcher segments enables flavor customization beyond grocery intermediaries. |
| USDA Organic Certification Pipeline Investment | Federal procurement preferences and Whole Foods Market placement incentives reward early compliance. |
| Backward Integration into Sprouted Seed Processing | Captive supply of paleo-positioned inputs insulates margin from Canadian oat futures volatility. |
| Extrusion Technology Capacity Expansion | High-pressure systems achieving 40% oil reduction secure clean-label texture performance against conventional baking. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with brand managers at granola manufacturers, category buyers at Kroger and Whole Foods Market, supply planners at Canadian grain handlers, and clean-label R&D directors; and secondary validation through FDA nutrition labeling guidance documents, USDA organic certification databases, EU EFSA health claims registers, and Nielsen retail audit data. Bottom-up volume triangulation against top-down value estimation anchored forecast reliability.
Forecast inputs considered product type segmentation across clusters, bars, flakes, and cookies; ingredient architecture separating whole grain, seed, nut, and dried fruit formulations; and distribution channel dynamics spanning supermarkets, online retailers, health food stores, and convenience chains. CAGRs were derived from segment-level growth pattern analysis incorporating fitness-professional snacking adoption curves and regulatory compliance timeline acceleration across the modeling period.
Practitioners should monitor Canadian prairie weather patterns, EU F-Gas Regulation enforcement strictness, and monk fruit extract supply availability for early signals of forecast deviation. Forecasts reflect assumptions regarding clean-label sweetener technology maturation and extrusion equipment deployment timelines. Material shifts in FDA added-sugar disclosure implementation schedules or Ukrainian grain corridor stability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Europe Popcorn Market
Snacks
Poland Snack Bar Market
Snacks
India Snack Bar Market
Snacks
Europe Extruded Snack Food Market
Snacks
United States Children's Snack Bar Market
Snacks
Brazil Snack Bar Market
Snacks
North America Snack Pellets Market
Snacks
South East Asia Snack Bar Market
Snacks
North America Baked Chips Market
Snacks
Cheese Snacks Market
Snacks
Low-Fat Tortillas Market
Snacks
Thailand Snack Bar Market
Snacks
Saudi Arabia Snacks Industry Market
Snacks
South Africa Savory Snacks Market
Snacks
Pretzels (Savory Snacks) Market
Snacks
High Fiber Snack Foods Market