
 Global Candy Market | 2026-2036
Global Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Candy Market Intelligence
A transition from multi-source to single-origin cocoa procurement is shifting the competitive landscape for premium chocolate. The Hershey Company leverages its established supply chain in North America to maintain market leadership. Mondelez International differentiates through its extensive portfolio of iconic brands across multiple candy categories. Ferrero Group specializes in premium chocolate confections, targeting the adult consumer segment.
Candy is a confection based on sugar or its substitutes, often combined with chocolate, fruits, or nuts. Production requires precise temperature control to create textures ranging from the amorphous glass of hard candy to crystalline fudge. The Chocolate segment holds the largest value share, but Gummies are expanding quickly due to formulation flexibility. While Supermarkets and Convenience Stores dominate distribution, Online Retailers are capturing growth in the premium and gift segments.
Food safety and labeling standards are enforced by agencies including the US FDA, the European Food Safety Authority (EFSA), and India's FSSAI. These regulations mandate clear allergen declarations and nutritional information, directly influencing product formulation and packaging design choices. Navigating evolving consumer preferences for healthier ingredients alongside divergent regional sugar tax policies will be critical for sustained profitability.
Market Dynamics
The global candy market is defined by a fundamental tension between consumer demand for indulgent, premium experiences and mounting regulatory and health pressures to reduce sugar content. This dynamic forces manufacturers to innovate simultaneously in formulation, sourcing, and product positioning to capture growth.
Growth Catalysts
- Premiumization for Gifting:The expansion of the gift-giving consumer segment is driving demand for high-quality ingredients, artisanal production methods, and sophisticated packaging, particularly within the premium chocolate category.
- Formulation Innovation:Advances in sugar substitutes and natural flavorings enable the creation of low-sugar or functional candies, such as vitamin-enriched gummies, appealing to health-conscious consumers without sacrificing taste.
- Demand in Emerging Economies:Rising disposable incomes and westernization of diets in markets like India are creating significant new consumer bases for both mass-market and premium confectionery products.
Market Restraints
- Input Commodity Volatility:The market is highly exposed to price fluctuations in key agricultural commodities like cocoa and sugar, which can compress margins and create production cost instability.
- Divergent Sugar Taxation:A patchwork of national and regional sugar taxes, such as those implemented in the United Kingdom and Mexico, creates regulatory complexity and forces costly, market-specific product reformulations.
- Supply Chain Concentration Risks:The shift toward single-origin cocoa for premium products increases vulnerability to climate events, crop diseases, and geopolitical instability in specific equatorial growing regions.
Strategic Opportunities
- Plant-Based and Vegan Formulations:There is a significant opportunity to develop and market plant-based confectionery, particularly in the gummy and chocolate segments, to cater to the growing vegan and flexitarian consumer base.
- Direct-to-Consumer (DTC) Channels:Establishing online DTC platforms allows brands to control the customer experience, capture higher margins, and test new premium or personalized products directly with engaged consumers.
- Functional Confectionery:Incorporating functional ingredients like probiotics, vitamins, or adaptogens into candy formats provides an avenue to enter the broader wellness market and appeal to health-focused shoppers.
Industry Challenges
- Sustainable Sourcing Compliance:Transitioning to fully traceable and ethically certified supply chains for ingredients like cocoa and palm oil is a complex operational challenge requiring significant investment in technology and supplier verification.
- Global Labeling Harmonization:Navigating disparate food safety and allergen labeling requirements from agencies like the US FDA, EFSA, and FSSAI complicates packaging design and international distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Candy Market |
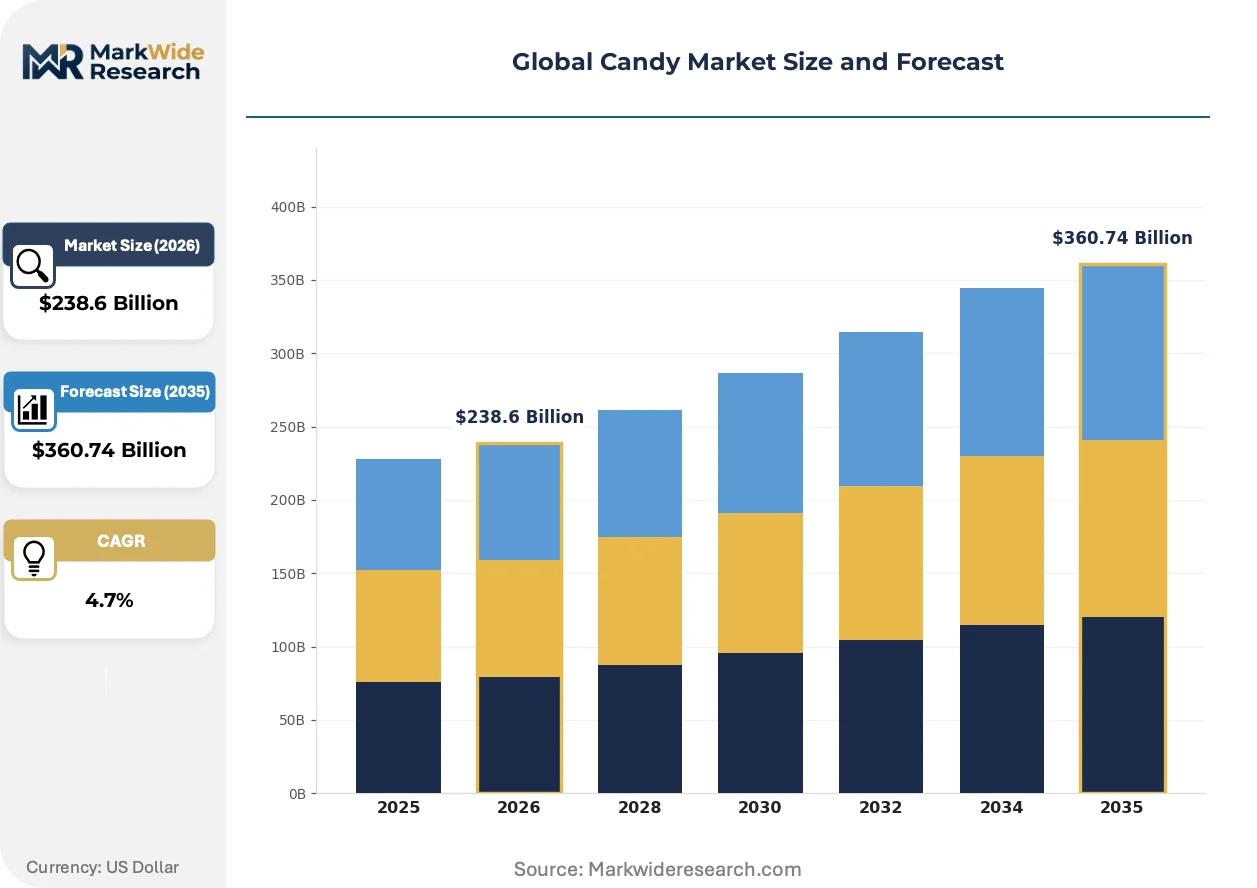
| Market Size in 2026 | $238.6 Billion |
| Market Size in 2035 | $360.74 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Gummies, Hard Candy, Licorice, Toffee, Caramel Packaging Type: Wrapper, Box, Tin, Bag, Blister Pack, Bulk Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops, Vending Machines, Department Stores Customer Type: Children, Teenagers, Adults, Gift Buyers, Event Organizers, Foodservice Vendors |
| Companies Covered | The Hershey Company, Pladis, Mars Inc., Chocoladefabriken Lindt & Sprüngli AG, Meiji Co. Ltd., Mondelez International, Nestlé SA, Haribo GmbH & Co. KG, Ferrero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Candy Market Strategic Shifts & Innovations
Product development in the candy market is being reshaped by the parallel pursuits of enhanced sensory experience and healthier ingredient profiles. This duality is driving innovation from ingredient sourcing and processing technology all the way to final product packaging and marketing.
Advanced manufacturing methods like 3D printing are enabling the creation of highly customized confectionery. The technology allows for intricate, bespoke designs that were previously impossible with traditional molding techniques. Premium and gifting segments are adopting this for personalized products, and the capability for on-demand customization is electrifying the luxury chocolate space.
Mandatory front-of-pack nutritional labeling is becoming a global standard, promoted by organizations like the WHO. This policy forces manufacturers to display simplified nutritional information, often using traffic-light color codes to signal health value. The children's candy segment is most impacted, compelling brands to accelerate reformulation toward lower sugar content to avoid negative on-shelf labeling.
Consumers are increasingly seeking smaller, portion-controlled indulgences that fit into a snacking-oriented lifestyle. This behavioral shift disrupts the market for large, family-sized formats, creating demand for single-serve packages and "thins" or "bites" product lines. The trend is most visible in urban convenience channels and among adult consumers managing caloric intake.
Global Candy Market Segmentation
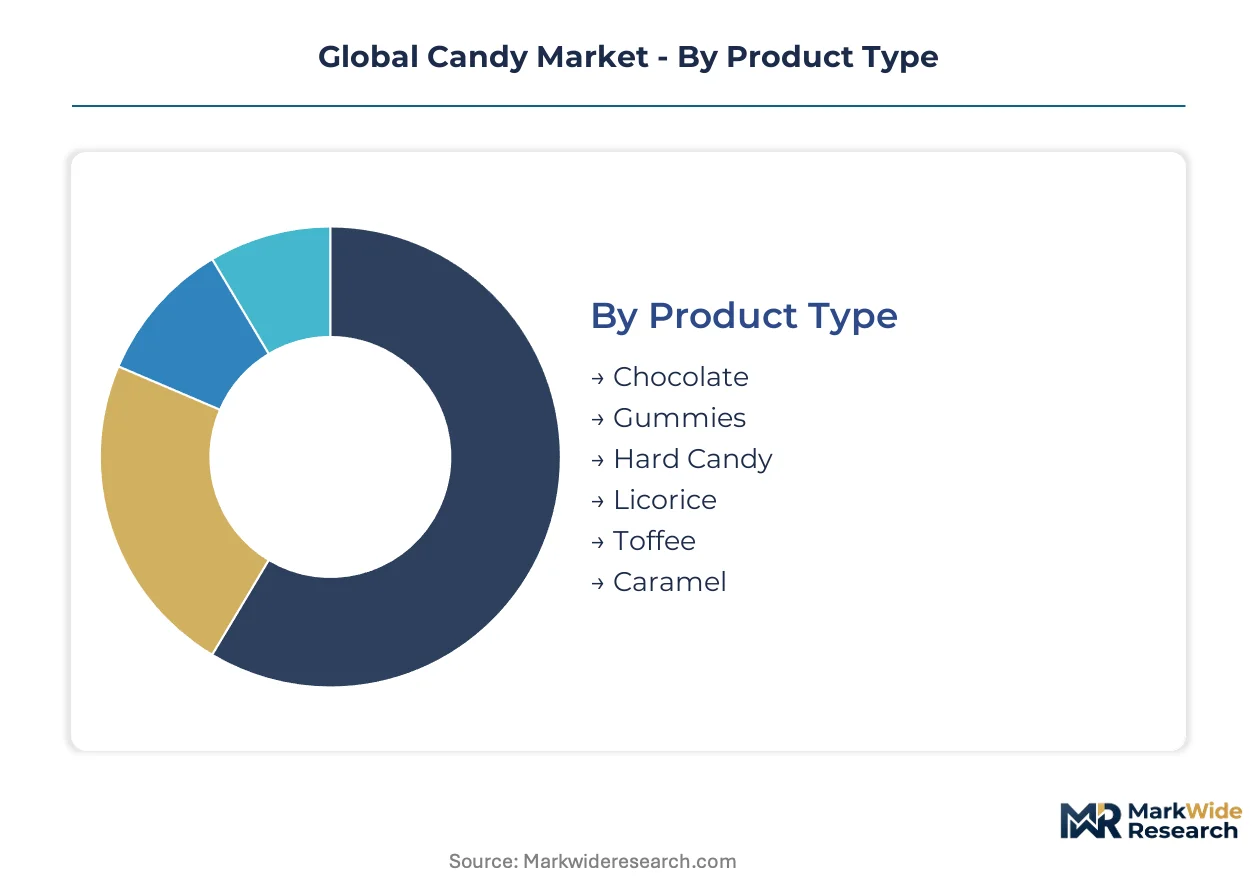
Understanding the segmentation of the global candy market is crucial for manufacturers to tailor product development, pricing strategies, and distribution networks effectively. Segmentation highlights distinct consumer preferences and operational requirements across various product formats, packaging solutions, sales channels, and end-user demographics.
Product Type:
The market for candy products varies significantly based on the depth of ingredient integration and textural complexity, influencing both production methods and consumer appeal.
- Chocolate:This segment encompasses products made primarily from cocoa solids and cocoa butter, often combined with sugar, milk, and flavorings, requiring precise tempering. Demand concentrates in developed markets like the United States and Europe, driven by premiumization and gifting occasions.
- Gummies:These confections are characterized by their chewy, gelatin-based or pectin-based texture, allowing for diverse shapes, colors, and functional ingredient incorporation. Their formulation flexibility makes them highly popular in emerging economies like India, where health-conscious consumers seek vitamin-enriched options.
- Hard Candy:Composed mainly of sugar and water, cooked to a high temperature to achieve an amorphous glass-like texture.
- Licorice:A confection flavored with the extract of the licorice plant, available in various chewy and firm forms.
- Toffee:A chewy candy made by boiling sugar or molasses with butter and sometimes flour.
- Caramel:A soft, chewy candy produced by cooking sugar, cream, butter, and sometimes milk to a specific temperature.
Chocolate leads volumes today; Gummies are gaining share fastest.
Packaging Type:
Packaging solutions differentiate candy products based on their perceived value and intended consumption occasion, ranging from economical mass-market formats to sophisticated premium presentations.
- Wrapper:Individual protective layers, typically plastic or foil, designed for single-serve portions and mass-market distribution, prioritizing cost-efficiency and convenience. This format is essential for high-volume sales in convenience stores across all regions.
- Box:Rigid or semi-rigid containers, often used for multi-piece assortments, gifting, or premium chocolate confections, emphasizing presentation and product protection. Boxed chocolates see strong demand in holiday seasons within the United Kingdom and Germany.
- Tin:Durable metal containers providing excellent protection and a premium, reusable aesthetic, frequently used for seasonal or specialty candies.
- Bag:Flexible packaging, usually plastic, suitable for bulk quantities, shareable formats, and often seen in supermarket aisles.
- Blister Pack:A pre-formed plastic cavity with a paperboard backing, offering product visibility and tamper resistance for smaller candy items.
- Bulk:Large-format packaging for industrial use or self-serve retail, minimizing individual packaging costs.
Wrapper packaging remains essential for mass market appeal, while Box packaging supports premium offerings.
Distribution Channel:
The channels through which candy reaches consumers vary by market maturity and product positioning, influencing brand visibility and accessibility.
- Supermarkets:Large retail stores offering a wide assortment of candy products, serving as the primary channel for mass-market confectionery due to extensive reach and competitive pricing. Supermarkets in the United States and Canada account for significant sales volumes.
- Online Retailers:E-commerce platforms enabling direct-to-consumer sales, particularly effective for niche, personalized, or premium candy products that benefit from broader geographical access. This channel experiences rapid growth in regions like Europe for specialized confectionery.
- Convenience Stores:Smaller retail outlets providing quick access to impulse purchases and single-serve candy items, characterized by high foot traffic.
- Specialty Shops:Dedicated confectionery stores or artisan boutiques offering unique, handcrafted, or imported candy selections at premium prices.
- Vending Machines:Automated dispensers providing immediate access to single candy bars or packs in high-traffic public locations.
- Department Stores:Larger retail establishments often featuring dedicated food halls or confectionery sections for premium and gift-oriented candy.
Traditional channels maintain market dominance, but digital platforms capture specialized demand.
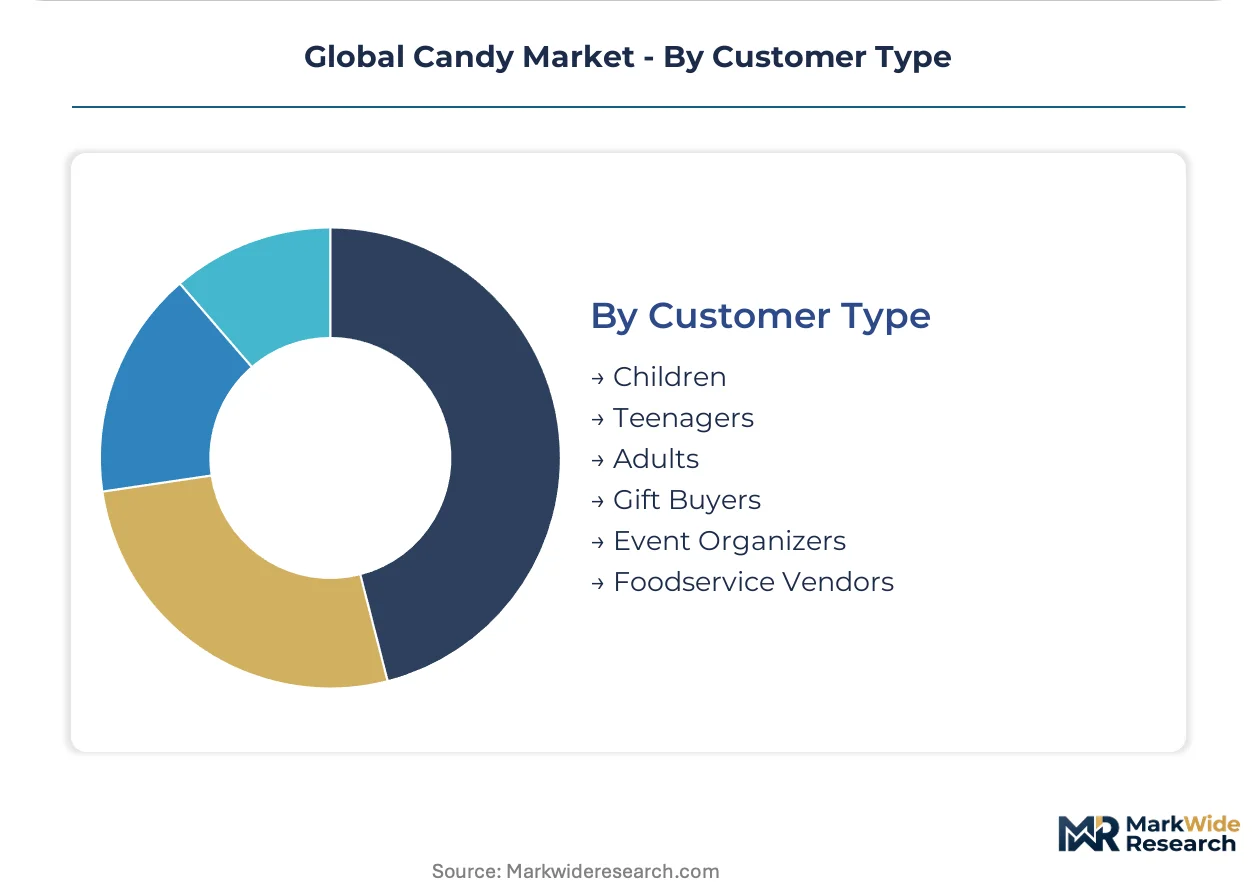
Customer Type:
Candy consumption patterns are heavily influenced by the demographic and behavioral characteristics of different consumer segments, from children to adult gift-givers.
- Adults:This segment seeks sophisticated flavor profiles, premium ingredients, and often portion-controlled indulgences, with a focus on sensory experience. Adult consumers in France and Italy drive demand for dark chocolate and gourmet confections.
- Gift Buyers:Consumers purchasing candy primarily for gifting occasions, prioritizing attractive packaging, high-quality ingredients, and brand reputation. This segment drives premiumization trends and seasonal sales, particularly in the United Kingdom during holidays.
- Children:Characterized by preferences for sweet, colorful, and novelty candy forms, often influenced by marketing and popular culture.
- Teenagers:This group often gravitates towards trendy, shareable, and snack-sized candy products, influenced by social media and peer trends.
- Event Organizers:Procure candy in bulk for events, parties, or corporate functions, focusing on variety and quantity.
- Foodservice Vendors:Businesses like restaurants, cafes, and hotels that purchase candy for desserts, garnishes, or complimentary offerings.
The market increasingly diversifies to cater to distinct consumer motivations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European confectionery heartland, encompassing nations like Germany and France, drives innovation in premium chocolate and artisanal candies. Regulatory frameworks across these regions influence product formulation and packaging design. Demand for both indulgent and health-conscious options shapes market dynamics globally.
United States
Demand for diverse candy formats, from traditional chocolate bars to functional gummies, characterizes the United States market. The US FDA mandates stringent food safety and labeling standards, influencing ingredient transparency. The confectionery industry in Pennsylvania, particularly around Hershey, continues to innovate in product development and distribution.
India
Rising disposable incomes and a youthful demographic fuel significant consumption of both mass-market and premium confectionery in India. The FSSAI enforces comprehensive food safety regulations, including specific guidelines for ingredients and additives. Major production hubs around Mumbai and Delhi are expanding capacity to meet this escalating demand.
United Kingdom
Gifting occasions and a strong preference for boxed chocolates sustain robust demand in the United Kingdom. The UK government's sugar tax policies accelerate reformulation efforts towards lower-sugar alternatives across the industry. Confectionery manufacturers in regions like the Midlands are focusing on sustainable sourcing and innovative packaging.
Germany
Consumers in Germany prioritize high-quality ingredients and traditional confectionery, driving demand for premium chocolate and hard candies. The European Food Safety Authority (EFSA) provides scientific advice for food safety, impacting product development across the EU. Specialized confectionery clusters in Bavaria and North Rhine-Westphalia lead in artisanal production techniques.
France
Sophisticated adult palates drive demand for dark chocolate and gourmet confections in France. ANSM regulations ensure the safety and quality of food products, including confectionery. The renowned chocolate houses in Paris and Lyon continue to set global trends in luxury confectionery design and flavor profiles.
Global Candy Market Key Industry Players
Established producers occupy the standard tier, leveraging extensive distribution networks; emerging entrants pursue functional confectionery and plant-based alternatives. The market structure exhibits consolidation among top-tier players alongside a fragmented landscape of specialized regional brands. Strategic archetypes encompass diversified food conglomerates, premium chocolate specialists, and mass-market confectioners focused on value. Portfolio diversification into new product categories and strategic partnerships with ingredient suppliers are dominant competitive moves for market participants.
Among global confectionery giants, The Hershey Company exemplifies a strong regional leader, leveraging its established North American supply chain and brand recognition to maintain market leadership. Mondelez International represents a diversified food conglomerate, anchoring its position with an extensive portfolio of iconic brands across multiple candy categories, catering to broad consumer preferences. The Ferrero Group, an Italian-based entity, occupies a distinct niche as a premium chocolate specialist, consistently targeting discerning adult consumer segments with its sophisticated confections and gifting-oriented products.
| Leading Market Players |
|---|
| The Hershey Company |
| Pladis |
| Mars Inc. |
| Chocoladefabriken Lindt & Sprüngli AG |
| Meiji Co. Ltd. |
| Mondelez International |
| Nestlé SA |
| Haribo GmbH & Co. KG |
| Ferrero Group |
| Others |
Cost & Logistics Intelligence
Cocoa futures prices directly influence manufacturer margins, cascading through the candy supply chain into distinct pricing tiers for premium and mass-market products. This dynamic forces continuous adaptation in sourcing strategies and product positioning.
Pricing Analysis
Volatile cocoa and sugar prices directly influence manufacturers' ability to pass through costs across the candy market. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by single-origin cocoa quality and packaging sophistication. Regulatory sugar taxes, such as those in the United Kingdom, create downward pressure on standard and economy segments. Mass-market consumers exhibit high price sensitivity, while gift buyers show less elasticity for premium confections.
Supply Chain Analysis
The minimal presence of reverse logistics flows for confectionery products means waste management focuses on packaging recycling initiatives. Cocoa bean sourcing heavily concentrates in West Africa, primarily Côte d'Ivoire and Ghana, while sugar production centers in Brazil and India. The industry relies on cocoa, sugar, and dairy as key inputs. Climate events and crop diseases in these regions pose a significant single-source vulnerability. Downstream distribution primarily moves through supermarkets and online retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global candy market presents a compelling margin-expansion story, driven by the strategic shift towards premiumization and functional confectionery.
For Market Incumbents: Hedge against input commodity volatility through long-term futures contracts for cocoa and sugar. Diversify sourcing regions beyond West Africa to mitigate climate-related threats. Invest in R&D for natural sweeteners and acquire specialized plant-based confectionery brands to counter regulatory sugar taxes.
For New Entrants and Emerging Players: The European Food Safety Authority (EFSA) guidance on novel foods in Europe opens a window for functional confectionery startups. Target white-space opportunities in plant-based gummies and probiotic-infused chocolates. Health-conscious adult consumers represent the most penetrable segment for these innovations. Direct-to-consumer (DTC) e-commerce platforms offer a cost-effective market entry point.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized ingredient suppliers and sustainable cocoa farmers. The market's long-term viability depends on adapting to evolving health trends and ethical sourcing practices. Mid-sized companies with proprietary sugar substitute technologies or established plant-based product lines represent attractive acquisition targets. Increased investment in traceable supply chain platforms signals market readiness for broader ethical compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Low-Sugar Formulations | Addresses sugar tax policies in the United Kingdom and Mexico, expanding consumer appeal. |
| Expand Direct-to-Consumer Channels | Allows brands to control customer experience and capture higher margins for premium products. |
| Invest in Sustainable Cocoa Sourcing | Ensures long-term supply stability amidst climate events and meets consumer ethical demands. |
| Introduce Plant-Based Confectionery Lines | Captures the growing vegan and flexitarian consumer base in regions like Europe. |
| Integrate Functional Ingredients | Appeals to health-conscious consumers seeking vitamin-enriched gummies and other wellness benefits. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. The analysis involved discussions with R&D directors, procurement leads, brand managers, and retail buyers in key markets. Secondary research leveraged regulatory filings from the US FDA and FSSAI, EFSA reports, and confectionery trade association publications. This mixed-methods approach enabled bottom-up market sizing and top-down validation of market trends.
Segment-weighting models were applied to project market evolution across the analysis window, incorporating product type, packaging type, distribution channel, and customer type. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Key inputs included per capita candy consumption trends and commodity price forecasts for cocoa and sugar.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory shifts or commodity price shocks. All forecasts reflect assumptions regarding consumer preferences and economic stability. Practitioners should monitor evolving sugar tax policies and climate impacts on crop yields for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Saudi Arabia Chocolate Market
Confectionery
Green Tea Chocolate Market
Confectionery
Confectionery Coating Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Boiled-Cooked Icing Market
Confectionery
Confectionery Fats Market
Confectionery
Crunchy Chocolate Market
Confectionery
UK Compound Chocolate Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Milk Chocolate Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Gum Base Candy Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Low Calorie Treats Market