
 Caramel Market | 2026-2036
Caramel Market Size, Share, and Industry Trends Forecast 2026-2036
Caramel Market Analysis
Confectionery flavor chemist talent is rotating toward natural extraction and thermal processing specialties as brands reformulate away from synthetic caramel colorants. Barry Callebaut leverages its integrated cocoa and caramel ingredient platform to supply compound coatings for European chocolatiers. Cargill, Incorporated sustains bulk liquid caramel output through its corn syrup supply chain and industrial food service channels. Kerry Group plc differentiates via clean-label caramelized sugar concentrates targeted at dairy and beverage manufacturers seeking reduced additive declarations.
Caramel is a heat-treated sugar product produced through Maillard browning of sucrose, glucose, or lactose at temperatures between 110°C and 180°C, yielding colorant, flavoring, and functional texturizing properties for food systems. Liquid caramel leads volume share due to its pumpability in automated bakery and dairy processing lines, while caramel coating commands margin concentration in premium confectionery and ice cream novelty applications. Soft caramel competes for share in filled chocolate and snack bar segments where chew texture and extended shelf stability determine procurement specifications.
FDA color additive regulations under 21 CFR 73.85 govern caramel coloring classifications and purity criteria for U.S. food manufacturers, while EFSA maintains maximum permissible levels for 4-MEI contaminants in Class III and IV caramel colors sold across Europe. India's FSSAI has tightened labeling requirements for caramel-containing packaged foods, compelling reformulation among domestic confectioners and importers. Stakeholders must monitor evolving contaminant thresholds and natural caramel alternatives as regulatory divergence between jurisdictions reshapes formulation costs and supply qualification protocols.
Market Dynamics
Clean-label reformulation pressure is compressing synthetic caramel colorant margins while redirecting capital toward thermal processing infrastructure and natural extraction capabilities. Manufacturers face immediate qualification hurdles as EFSA and FDA tighten contaminant thresholds simultaneously.
Growth Catalysts
- FSSAI Labeling Mandates:India's tightened packaged food disclosure rules compel domestic confectioners to source natural caramel alternatives, expanding the addressable base for clean-label suppliers.
- Dairy Dessert Premiumization:Ice cream and yogurt manufacturers in Germany and the United States are specifying higher-inclusion caramel for texture and visual differentiation in super-premium lines.
- Maillard Process Optimization:Advances in controlled thermal browning enable precise color consistency without Class III/IV artificial additives, satisfying bakery automation requirements.
Market Restraints
- Corn Syrup Price Volatility:Liquid caramel production remains exposed to feedstock fluctuations in the United States grain belt, compressing margin predictability for bulk suppliers.
- 4-MEI Contaminant Scrutiny:EFSA maximum permissible levels for Class III and IV caramel colors impose costly purification investments on European manufacturers.
- Natural Extract Supply Concentration:Vanilla and caramelized fruit concentrate sourcing clusters in Madagascar and specific Indian states, creating geographic risk for clean-label formulators.
Strategic Opportunities
- Plant-Based Confectionery:Dairy-free caramel formulations for vegan chocolate and frozen dessert segments remain underdeveloped in Germany and the United States.
- Beverage Caramel Concentrates:Ready-to-drink coffee and flavored milk processors seek reduced-sugar caramelized sugar syrups with clean-label declarations.
- Small-Scale Artisan Distribution:Direct-to-bakery supply relationships bypass commoditized liquid caramel channels for specialty caramel coatings with origin storytelling.
Industry Challenges
- Flavor Chemist Specialization Gap:Thermal processing expertise for natural caramel development outpaces available talent pools in European and North American food science programs.
- Legacy Equipment Retrofit Costs:Automated bakery lines require pump system recalibration to handle higher-viscosity natural caramel alternatives without throughput loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caramel Market |
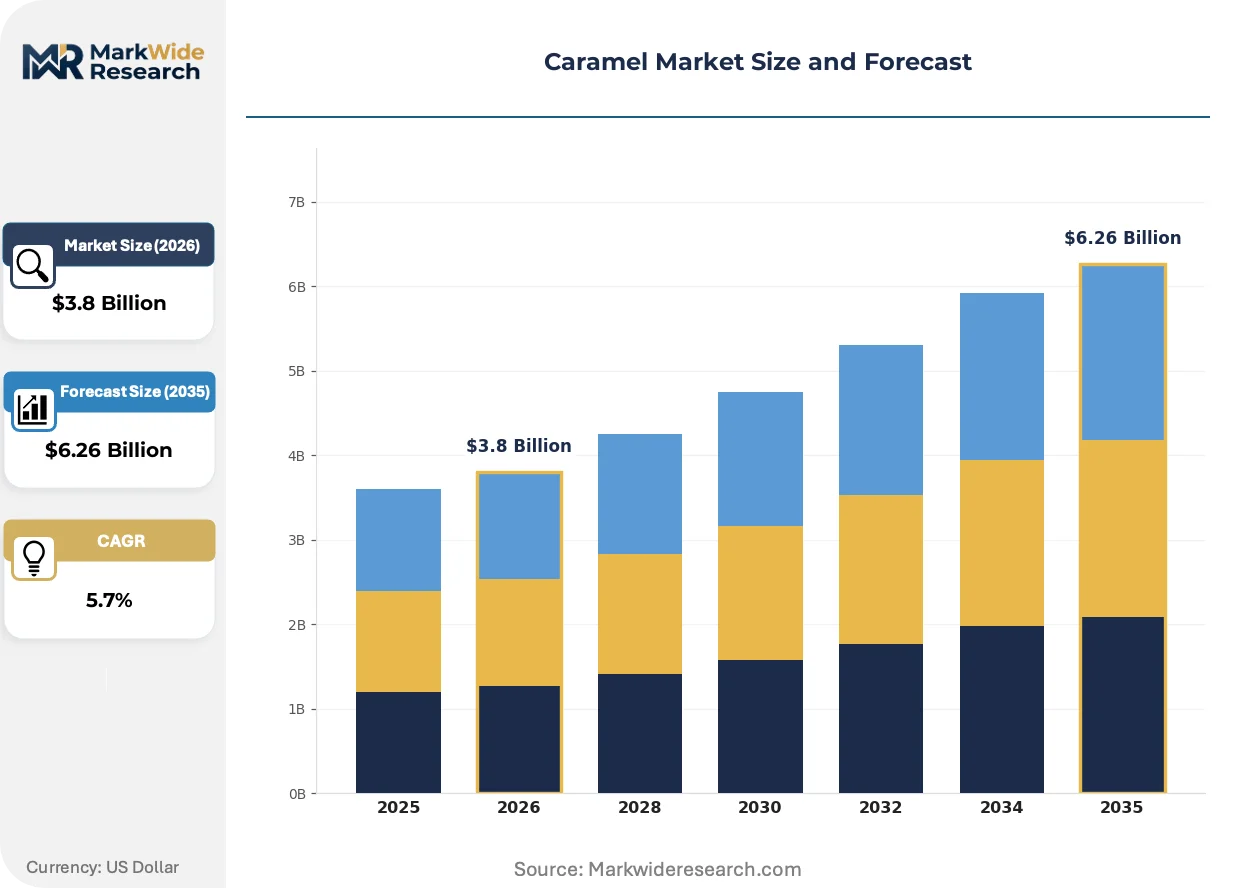
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Caramel, Soft Caramel, Hard Caramel, Caramel Coating Application: Bakery, Confectionery, Dairy Products, Sauces End User: Food Manufacturers, Retailers, Catering Businesses, Bakeries Form: Granulated, Syrup, Block, Powder |
| Companies Covered | Barry Callebaut, Mondelez International, Inc., Cargill, Incorporated, The Hershey Company, Mars, Incorporated, Kerry Group plc, Nestlé S.A., Ferrero Group, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caramel Market Emerging Trajectories
Reformulation chemistry is pivoting decisively toward plant-derived browning agents and precision thermal control systems. Three distinct vectors are compressing legacy synthetic colorant economics while opening premium positioning for natural process innovators.
Controlled Maillard reaction engineering is fragmenting the traditional caramel colorant supply base. Precision temperature and pH modulation systems now enable consistent natural browning without synthetic Class IV additives. Artisan chocolate manufacturers in Belgium and Switzerland are piloting these systems for small-batch compound coatings. The technology is fragmenting procurement patterns away from bulk liquid caramel toward in-house thermal processing capabilities.
REACH chemical registration requirements are extending disclosure obligations to caramel colorant impurities in European food-contact materials. Manufacturers must now document 4-MEI and other thermal process byproducts across their supply chains. German and French confectioners are accelerating supplier audits to preempt enforcement actions. This regulatory compression favors integrated producers with captive analytical laboratories over merchant colorant traders.
Bakery procurement teams are consolidating supplier relationships around dual-source natural caramel qualification programs. Large-scale automated lines in the United States and Germany now require redundant supply agreements for clean-label caramelized sugar concentrates. This consolidation is displacing spot-market liquid caramel purchases with contracted annual volumes tied to certification maintenance. The shift is most visible in private-label cookie and cracker manufacturing where retailer clean-label mandates cascade directly to ingredient specifications.
Caramel Market Segmentation
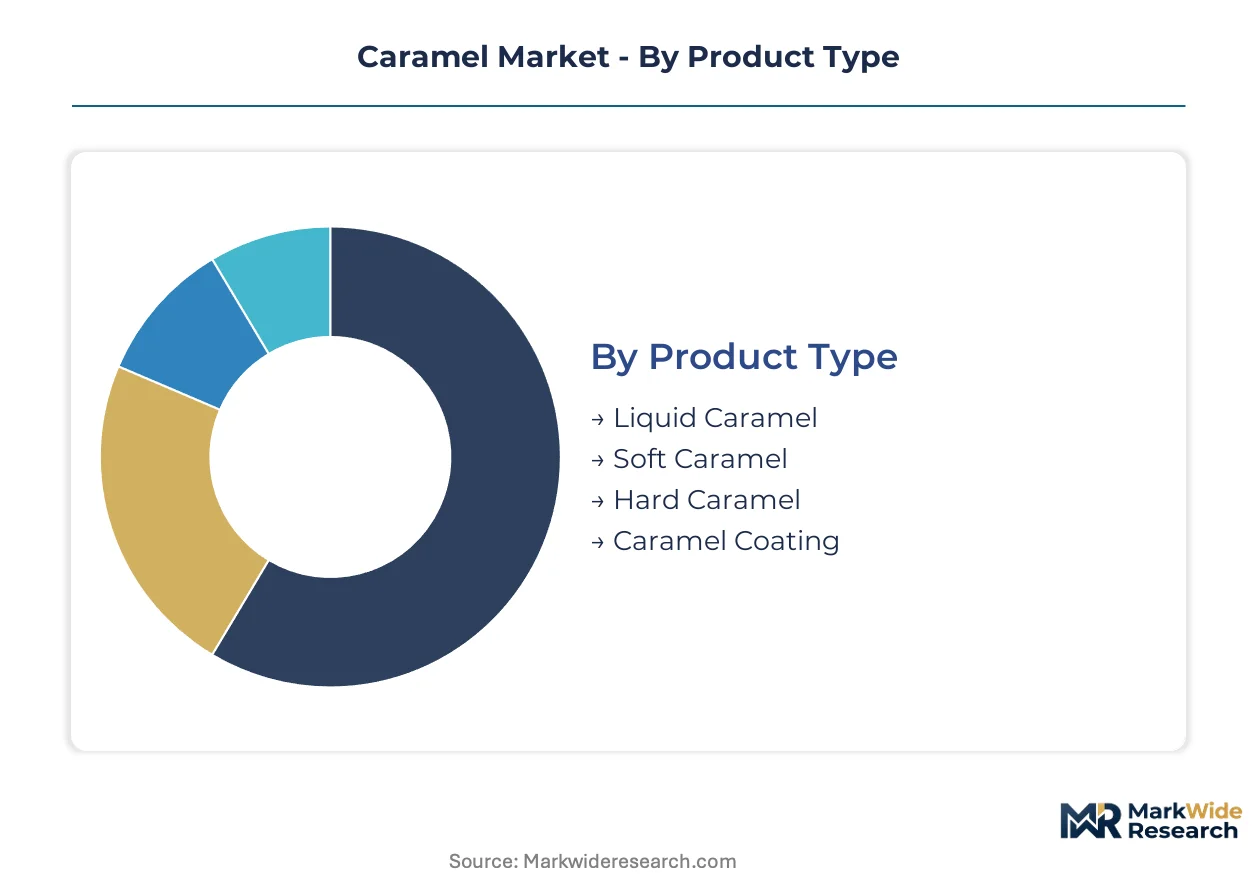
Caramel procurement patterns diverge sharply across product formats and processing requirements. Bakery and confectionery channels impose incompatible viscosity and thermal stability specifications, forcing suppliers to maintain parallel production assets.
Product Type:
Liquid caramel faces the most acute substitution threat from in-house Maillard processing systems that large bakeries are installing for color consistency control.
- Liquid Caramel:Pumpable sucrose-glucose solutions processed to 75-85 Brix viscosity for automated dosing in industrial bakery and dairy lines. United States food manufacturers specify this format for high-throughput cookie and ice cream novelty production where equipment compatibility determines supplier selection. Corn syrup feedstock exposure creates margin pressure for bulk producers.
- Soft Caramel:Intermediate-moisture confectionery centers with 8-12% fat inclusion and controlled water activity for extended shelf stability. German chocolatiers and United States snack bar manufacturers specify soft caramel for filled chocolate and protein bar applications where chew texture and cold-flow resistance determine procurement.
- Hard Caramel:Low-moisture amorphous glass with brittle fracture properties for hard candy and decorative applications.
- Caramel Coating:Viscous compound coatings with tailored fat bloom resistance for enrobing operations.
Liquid caramel anchors the volume base while soft caramel gains share at the steepest rate.
Application:
Cost tier stratification separates commodity bakery applications from premium confectionery specifications that command formulation service premiums.
- Confectionery:High-inclusion caramel for chocolate enrobing, praline centers, and toffee applications requiring precise color consistency and flavor intensity. Belgium and Switzerland chocolate manufacturers specify premium caramel coatings with origin storytelling for artisan positioning. Clean-label reformulation is redirecting procurement toward natural process suppliers.
- Bakery:Automated dosing applications in cookie, cracker, and pastry manufacturing where pumpability and thermal stability determine line efficiency. United States private-label manufacturers consolidate supplier relationships around dual-source qualification programs to meet retailer clean-label mandates.
- Dairy Products:Ice cream ripple sauces and yogurt inclusions with freeze-thaw stability requirements.
- Sauces:Savory applications including dessert toppings and culinary preparations.
Bakery applications dominate volume throughput while confectionery commands the widest margin spread.
End User:
Customer type fragmentation creates distinct service models between industrial procurement teams and artisan bakery operators.
- Food Manufacturers:Industrial-scale procurement with annual volume contracts, technical service requirements, and dual-source qualification mandates. United States and Germany-based manufacturers specify clean-label caramelized sugar concentrates with full contaminant documentation for EFSA and FDA compliance.
- Bakeries:Small-to-medium enterprises with flexible batch sizing and origin-specific sourcing preferences. Direct supply relationships bypass commodity channels for specialty coatings with provenance credentials.
- Retailers:Private-label development teams with cascading clean-label specifications to ingredient suppliers.
- Catering Businesses:Foodservice operators with cost-optimized procurement and standard product requirements.
Food manufacturers concentrate procurement volume while bakeries generate the most rapid supplier relationship expansion.
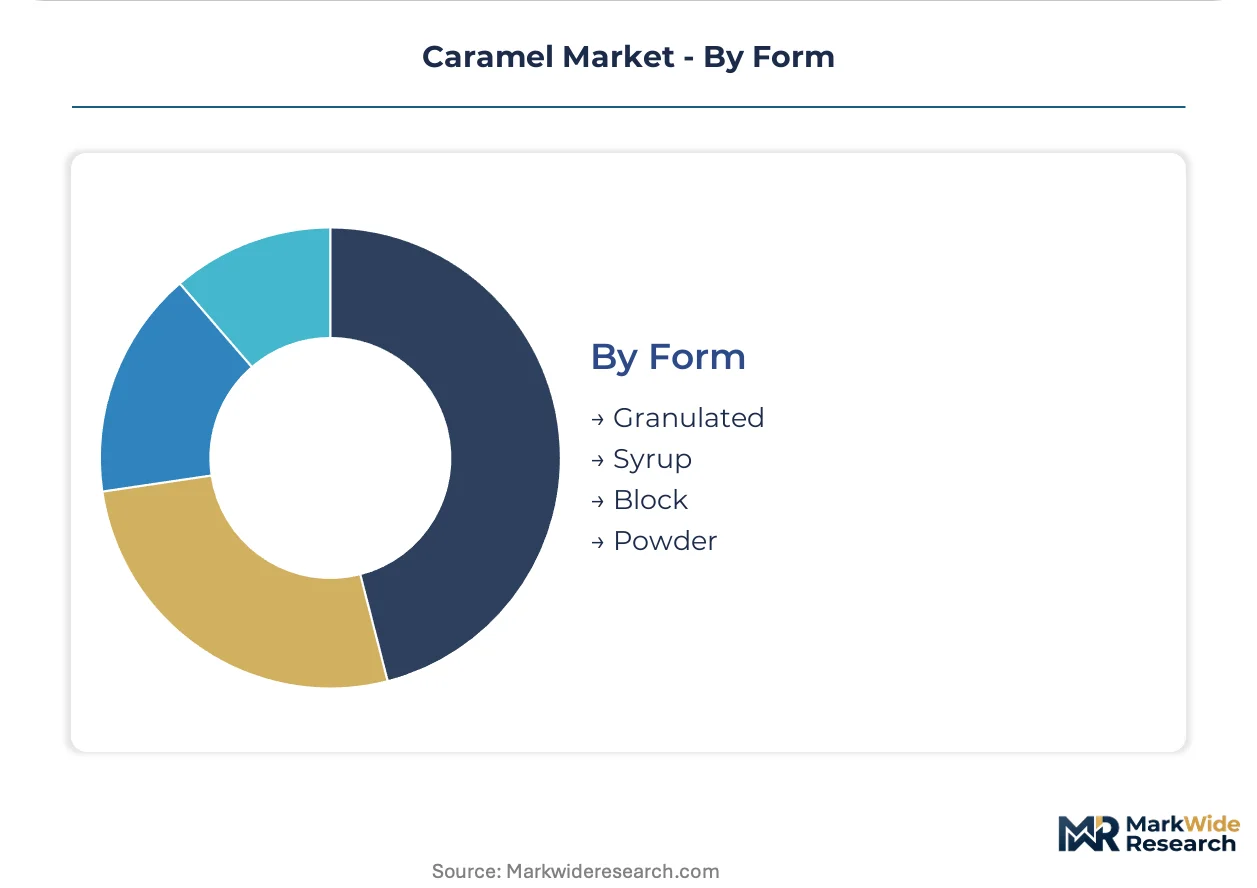
Form:
Supply concentration in syrup and block formats reflects processing infrastructure legacy and transportation economics.
- Syrup:Liquid concentrate format with maximum pumpability for automated manufacturing lines and beverage applications. Ready-to-drink coffee and flavored milk processors in the United States seek reduced-sugar caramelized sugar syrups with clean-label declarations.
- Block:Solid format for artisan confectionery operations and reconstitution into custom viscosity preparations. European chocolatiers prefer block caramel for small-batch compound coating production with precise temperature control.
- Granulated:Free-flowing powder for dry mix applications and instant beverage formulations.
- Powder:Spray-dried format for extended shelf stability and reduced transportation costs.
Syrup maintains the largest installed base while block formats expand most quickly in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets: United States buyers prioritize pumpable liquid formats for automated bakery lines, while European confectioners emphasize contaminant documentation under REACH, and Indian regulators push natural alternatives through FSSAI mandates.
United States
Private-label cookie manufacturers and ice cream novelty producers drive liquid caramel procurement for high-throughput automation. FDA regulations under 21 CFR 73.85 govern color additive classifications and purity standards. Chicago and Minneapolis house concentrated industrial bakery operations where dual-source qualification programs for clean-label caramelized sugar concentrates are becoming standard procurement practice.
Germany
Chocolatiers and dairy dessert manufacturers specify premium caramel coatings with freeze-thaw stability for super-premium yogurt and ice cream lines. EFSA maximum permissible levels for 4-MEI contaminants in Class III and IV caramel colors impose costly purification investments. Cologne and Hamburg anchor European compound coating production where REACH chemical registration requirements extend disclosure obligations to caramel colorant impurities.
India
Domestic confectioners and importers face reformulation pressure as FSSAI tightens labeling requirements for caramel-containing packaged foods. The country's national food regulator compels disclosure of artificial versus natural caramel sources. Maharashtra and Gujarat host expanding domestic chocolate manufacturing where clean-label caramel alternatives from local suppliers are displacing imported synthetic colorants.
Belgium
Artisan chocolate manufacturers pilot controlled Maillard reaction systems for small-batch compound coatings with origin storytelling. EFSA contaminant thresholds apply equally here, driving supplier audit acceleration. Brussels and Liège concentrate premium confectionery innovation where in-house thermal processing capabilities fragment traditional bulk liquid caramel procurement patterns.
Switzerland
Premium chocolate houses demand precise color consistency for praline centers and enrobing applications without synthetic Class IV additives. Swissmedic maintains pharmaceutical-grade purity expectations that cascade into food-contact material standards. Zurich and Vevey anchor high-margin confectionery R&D where natural caramel process innovation commands supplier selection premiums.
Caramel Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in caramel supply. The upper tier combines captive corn syrup supply chains with industrial food service distribution, while specialists concentrate on clean-label caramelized sugar concentrates for dairy and beverage channels. Three archetypes dominate: integrated agribusiness conglomerates with syrup-to-caramel processing, flavor-house specialists with thermal processing expertise, and confectionery multinationals with captive ingredient production. Competitive moves center on backward integration into corn syrup supply and geographic expansion of clean-label certification programs.
Within the integrated agribusiness tier, Cargill, Incorporated and Barry Callebaut occupy positions that exemplify divergent strategic paths—Cargill representing North American bulk liquid caramel scale, Barry Callebaut anchoring European cocoa-caramel integration for chocolatiers. Kerry Group plc sits within the flavor-house specialist archetype, its Irish corporate structure signaling clean-label concentrate development for dairy and beverage manufacturers seeking reduced additive declarations. These three entities collectively illustrate how regulatory divergence between FDA and EFSA jurisdictions reshapes supplier qualification and capital allocation across the industry.
| Leading Market Players |
|---|
| Barry Callebaut |
| Mondelez International, Inc. |
| Cargill, Incorporated |
| The Hershey Company |
| Mars, Incorporated |
| Kerry Group plc |
| Nestlé S.A. |
| Ferrero Group |
| Sensient Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-day corn syrup inventory cycles in United States grain belt operations tether bulk liquid caramel pricing to feedstock volatility, compressing margin predictability for suppliers while amplifying procurement leverage for large-scale food manufacturers with dual-source qualification mandates.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between industrial food manufacturers and integrated agribusiness suppliers, though spot-market purchases persist for artisan bakery channels. Price differentiation hinges on clean-label certification grade and volume scale, with natural caramelized sugar concentrates commanding premiums over synthetic Class III/IV alternatives. Pricing pressure intensifies in liquid caramel tiers due to in-house Maillard processing adoption by automated bakery lines. Private-label manufacturers exhibit highest price sensitivity, while premium chocolatiers in Belgium and Switzerland prioritize color consistency over unit cost.
Supply Chain Analysis
The United States anchors bulk liquid caramel production through integrated corn syrup processing infrastructure, while Belgium and Switzerland concentrate premium compound coating supply for artisan chocolatiers. Madagascar and specific Indian states feed vanilla and caramelized fruit concentrate sourcing for clean-label formulators. Supply chain risk centers on single-source vulnerability in natural extract geographies. Distribution runs through industrial food service channels for bulk formats and direct-to-bakery relationships for specialty coatings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Caramel procurement is consolidating around platform-economics logic as clean-label certification programs become interoperability standards between retailers and ingredient suppliers, with FSSAI and REACH disclosure requirements accelerating supplier audit centralization.
For Market Incumbents: Secure backward integration into corn syrup supply chains to defend against feedstock volatility, while accelerating captive analytical laboratory investments to preempt EFSA enforcement actions on 4-MEI documentation. Dual-source natural caramel qualification programs represent the priority channel-control lever against merchant colorant traders.
For New Entrants and Emerging Players: FSSAI clean-label fast-track certification opens immediate white-space in Maharashtra and Gujarat chocolate manufacturing, where domestic confectioners displace imported synthetic colorants. Plant-based caramel formulations for vegan frozen desserts in Germany and the United States offer the most penetrable segment, with direct-to-bakery origin storytelling as the viable go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergence between FDA and EFSA contaminant thresholds creates persistent supplier qualification premiums for integrated producers with multi-jurisdictional compliance capabilities. Acquisition targets should display thermal processing expertise and captive analytical infrastructure. The signal to watch is automated bakery line retrofit announcements indicating in-house Maillard processing adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Syrup Supply | Cargill's captive feedstock control insulates margin predictability against United States grain belt volatility. |
| Clean-Label Certification Program Expansion | Kerry Group's reduced additive declarations align with FSSAI and REACH disclosure mandates cascading from retailers. |
| Controlled Maillard Reaction System Deployment | Belgian artisan chocolatiers fragment bulk liquid caramel demand through in-house thermal processing capabilities. |
| Dual-Source Qualification Program Consolidation | United States private-label cookie manufacturers lock in redundant supply agreements to meet retailer mandates. |
| Plant-Based Caramel Formulation Development | Dairy-free alternatives address underdeveloped vegan chocolate and frozen dessert segments in Germany and the United States. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA color additive filings, EFSA contaminant threshold documentation, FSSAI labeling mandates, and trade customs data for corn syrup and caramel colorant flows. Interviews with confectionery flavor chemists, thermal processing equipment specialists, procurement leads at industrial bakeries, and regulatory affairs directors at integrated ingredient suppliers inform qualitative assessments. Bottom-up volume modeling from segment-level production data triangulates against top-down value estimates derived from manufacturer revenue disclosures.
Segmentation dimensions modeled span product type, application channel, end-user archetype, and supply form across the analysis window, with additional granularity on clean-label certification status and contaminant class tier. CAGRs derive from regression analysis against historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporate Maillard process technology adoption curves and regulatory enforcement probability weightings for 4-MEI thresholds.
Decision-makers should treat outputs as directional under stable corn syrup feedstock pricing and sustained clean-label regulatory tightening; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in EFSA contaminant thresholds, FSSAI enforcement patterns, and automated bakery line technology adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Confectionery Coating Market
Confectionery
Non-Chocolate Candy Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Sugar-Free Gummy Market
Confectionery
South Korea Chocolate Market
Confectionery
UK Chocolate Market
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
Sugar Confectionery Market
Confectionery
White Chocolate Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
North America Premium Chocolate Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Mints Market
Confectionery
Low-Calorie Dark Chocolate Market