
 Sugar Free White Chocolate Market | 2026-2036
Sugar Free White Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Free White Chocolate Market Analytics
Confectionery formulation talent is rotating from traditional milk chocolate programs toward sugar-free white chocolate innovation as CPG brands expand reduced-sugar portfolios. Lindt & Sprüngli leverages its Swiss R&D infrastructure to sustain premium positioning in European sugar-free confectionery. Hershey's anchors North American shelf presence through mass-market distribution networks for alternative-sweetener products. Mondelez International competes across multiple price tiers with global manufacturing scale that supports regional recipe adaptation.
Sugar free white chocolate denotes a cocoa butter-based confection containing milk solids, emulsifiers, and non-nutritive sweeteners such as erythritol or allulose in place of sucrose, typically maintaining minimum cocoa butter content of 20 percent by weight to preserve mouthfeel and tempering properties. The product serves industrial food manufacturers requiring clean-label dessert components and retail consumers managing glycemic response. Bars dominate current revenue contribution among product types due to established gifting rituals and portion-controlled consumption patterns. Online sales channels represent the fastest-expanding distribution vector as direct-to-consumer brands bypass traditional retail slotting constraints. Food manufacturers constitute a concentrated margin pool within end users, purchasing bulk coatings and chips for incorporation into bakery and ice cream applications.
FDA nutrition labeling requirements govern sugar content claims and alternative sweetener disclosure thresholds in the United States, while EFSA evaluates novel food status for emerging sweeteners entering European formulations. BIS standards in India and GB standards in China additionally shape import specifications and local production compliance for multinational suppliers. Stakeholders must monitor evolving sweetener approval pipelines and clean-label certification requirements as regulatory divergence across major economies complicates unified product platform strategies.
Market Dynamics
Formulation chemists face mounting pressure to reconcile FDA sugar content disclosure thresholds with clean-label positioning as maltitol and allulose compete for shelf space dominance.
Growth Catalysts
- Stevia-erythritol blending protocols:Advanced co-crystallization methods now mask bitter aftertastes in high-cocoa-butter matrices, expanding acceptable sweetness profiles for industrial bakers.
- India FSSAI sweetener approvals:Expanded clearance for novel polyols accelerates local production capacity and reduces import dependency for South Asian confectionery manufacturers.
- Germany:Functional snacking rituals in German retail channels normalize premium sugar-free positioning, creating pull-through for adjacent European markets.
Market Restraints
- Cocoa butter price volatility:West African supply disruptions transmit directly to margin compression for mid-tier producers lacking forward-contract coverage.
- EFSA novel food status reviews:Pending allulose classification delays European product launches and fragments R&D investment timelines across Atlantic operations.
- High-intensity sweetener substitution:Sucralose-sweetened compound coatings threaten white chocolate's premium positioning in cost-sensitive industrial applications.
Strategic Opportunities
- Brazil ANVISA pathway harmonization:Emerging regulatory alignment with FDA standards reduces dual-registration burdens for multinational portfolio expansion.
- Direct-to-consumer subscription channels:Bypassing traditional retail slotting fees enables margin capture and rapid flavor-variant testing with glycemic-conscious households.
- Precision fermentation cocoa butter:Convergence with cellular agriculture supply chains promises supply security decoupled from commodity crop cycles.
Industry Challenges
- Tempering technician scarcity:Sugar-free matrices demand tighter viscosity control than conventional chocolate, yet vocational programs emphasize legacy milk chocolate production methods.
- Dual-label certification complexity:Simultaneous organic and sugar-free validations extend product development cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Free White Chocolate Market |
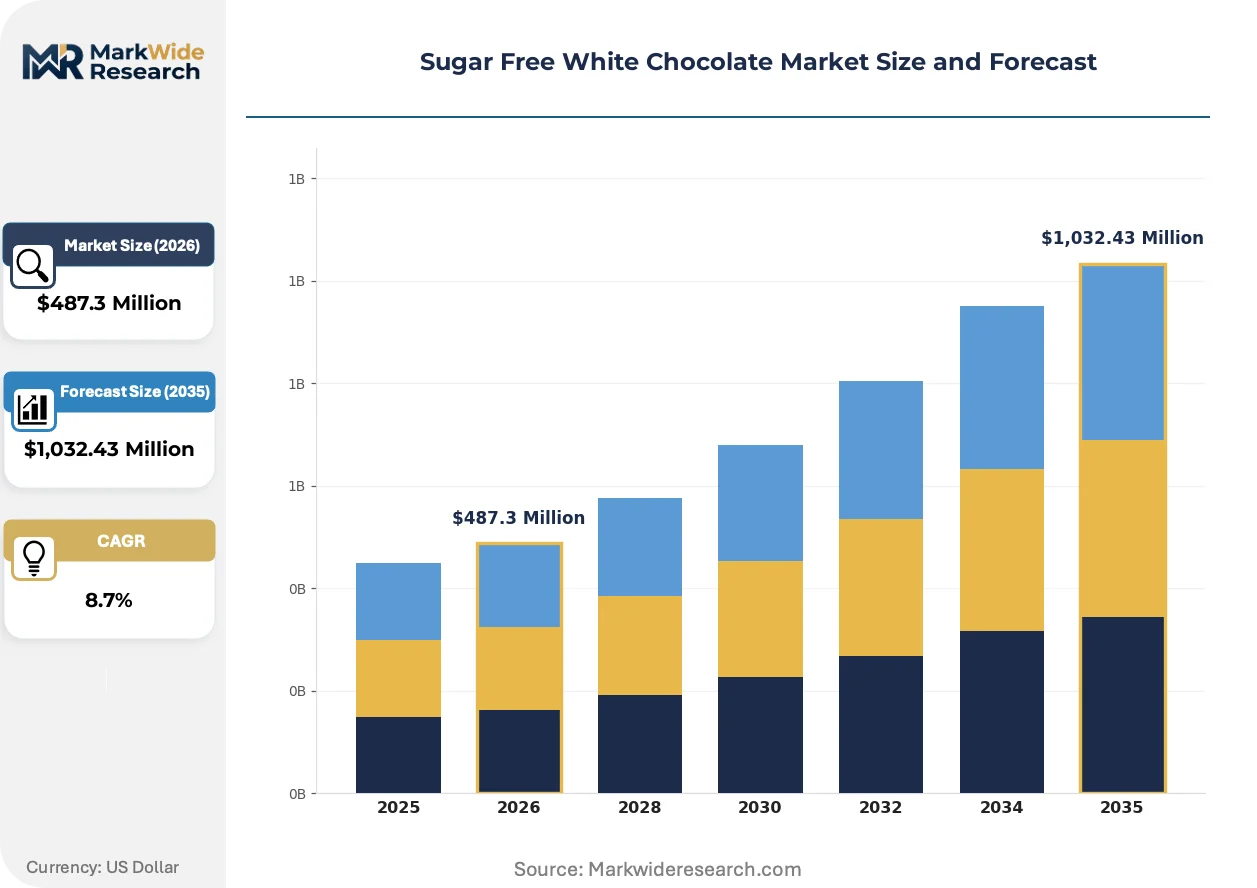
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Chips, Coatings, Bakes End User: Retail Consumers, Food Manufacturers, Bakeries, Restaurants Packaging Type: Bulk Packs, Retail Boxes, Pouches, Jars Sales Channel: Online, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Lindt & Sprüngli, Hershey’s, Mondelez International, Mars, Inc., Nestlé, Lily’s Sweets, Russell Stover Chocolates, ChocZero, Pascha Chocolate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Free White Chocolate Market Evolving Landscape
Clean-label sweetener sourcing and precision manufacturing are compressing formulation cycles while fragmenting competitive advantage across ingredient suppliers and finished goods manufacturers.
Allulose crystallization technology is bifurcating industrial procurement patterns. Food manufacturers in the bakery and ice cream sectors now specify this rare sugar for its Maillard-reactive properties and minimal cooling effect. The technology is bifurcating supplier tiers, separating firms with patented purification methods from commodity polyol distributors.
EFSA's evolving stance on novel food categorization for rare sugars is reshaping European launch timelines. Manufacturers now pre-submit dossiers eighteen months ahead of commercialization to secure market access. German and Swiss brands with established regulatory affairs capabilities capture first-mover positioning while smaller competitors defer entry.
Subscription-based replenishment models are displacing conventional impulse-purchase distribution for sugar-free confectionery. Direct-to-consumer brands bypass slotting fee structures and capture consumption data that informs rapid flavor iteration. This pattern concentrates in United States metropolitan corridors where glycemic management apps drive purchase timing.
Sugar Free White Chocolate Market Segmentation
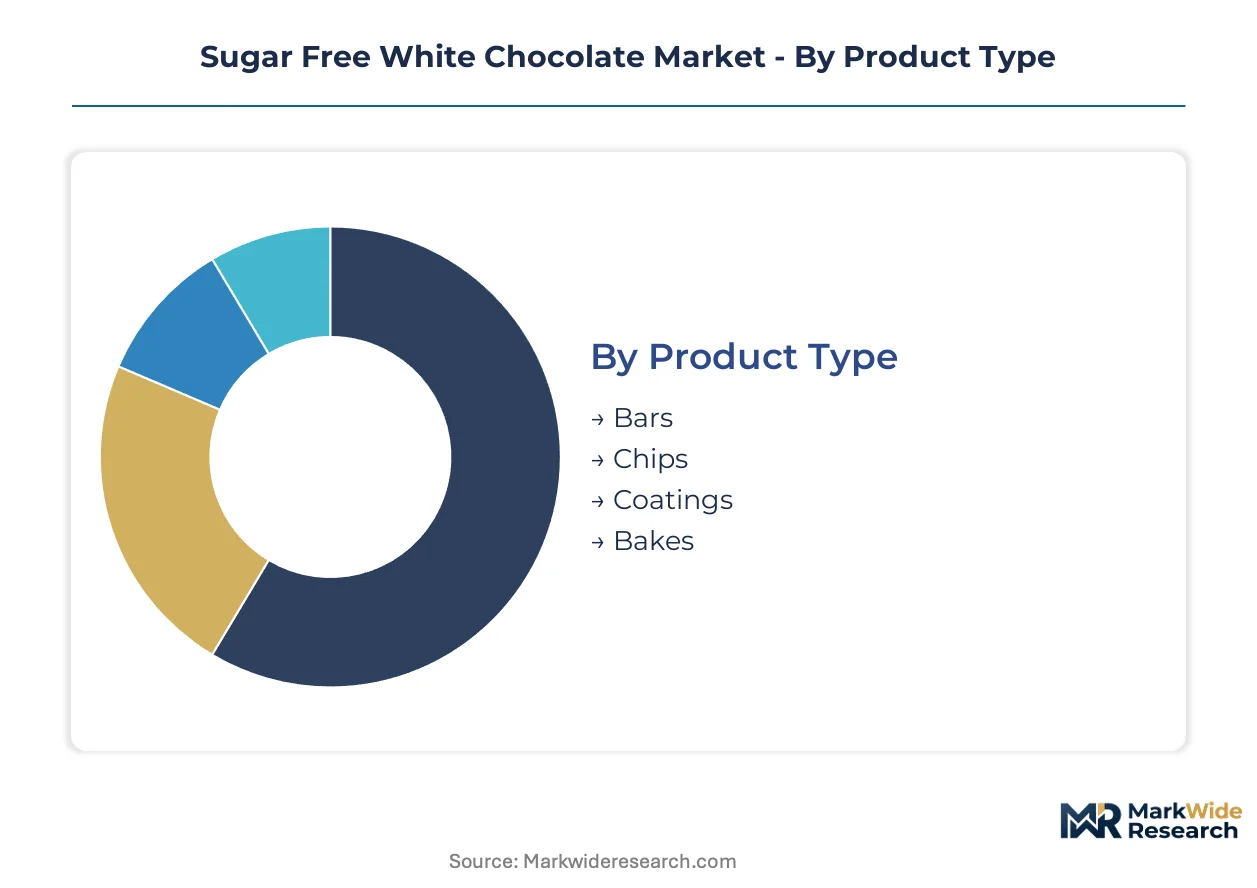
Sugar-free white chocolate segmentation reveals divergent margin structures across product formats and procurement channels. Industrial buyers prioritize functional specifications while retail channels reward brand positioning and portion-controlled formats.
Product Type:
Premium margin capture concentrates in formats serving industrial food manufacturing and gift-oriented retail rituals.
- Bars:Molded tablets maintain minimum 20 percent cocoa butter content for snap and tempering stability. Gifting occasions in the United States and Germany sustain premium positioning through seasonal packaging and portion-controlled consumption rituals.
- Chips:Calibrated drop formats with controlled fat bloom resistance serve bakery and ice cream manufacturing lines. Food manufacturers in Japan specify narrow particle size distributions for automated depositing equipment.
- Coatings:Compound formulations with modified fat systems for enrobing applications.
- Bakes:Chunk and inclusion formats engineered for thermal stability in oven applications.
The dominant share belongs to bars, while chips are closing the gap fastest.
End User:
Procurement scale and specification complexity separate concentrated industrial demand from fragmented retail purchasing patterns.
- Food Manufacturers:Bulk purchasers of coatings and inclusions for bakery, dairy, and frozen dessert applications. Clean-label certification requirements and glycemic index documentation dominate supplier qualification protocols in North American and European facilities.
- Retail Consumers:Individual purchasers managing dietary glycemic response through portion-controlled formats. Direct-to-consumer subscription models in United States metropolitan corridors displace conventional impulse channels.
- Bakeries:Artisan and commercial operations requiring temper-stable decorations and inclusion formats.
- Restaurants:Dessert program chefs sourcing premium couverture for plated applications.
Food manufacturers command the largest procurement volumes, though retail consumers are expanding most quickly through digital channels.
Packaging Type:
Distribution economics and shelf-life requirements drive format selection across temperature-controlled and ambient supply chains.
- Bulk Packs:Industrial totes and pails for high-volume manufacturing integration. Food manufacturers in Germany and Japan specify nitrogen-flushed formats for extended storage stability.
- Retail Boxes:Gift-oriented cartons with tempering instructions and portion guidance.
- Pouches:Flexible formats for club-store and e-commerce fulfillment.
- Jars:Spreadable and drizzle applications for home baking segments.
Bulk packs dominate procurement tonnage, while pouches are gaining share fastest through e-commerce expansion.
Sales Channel:
Margin retention and customer data access separate emerging direct channels from established retail infrastructure.
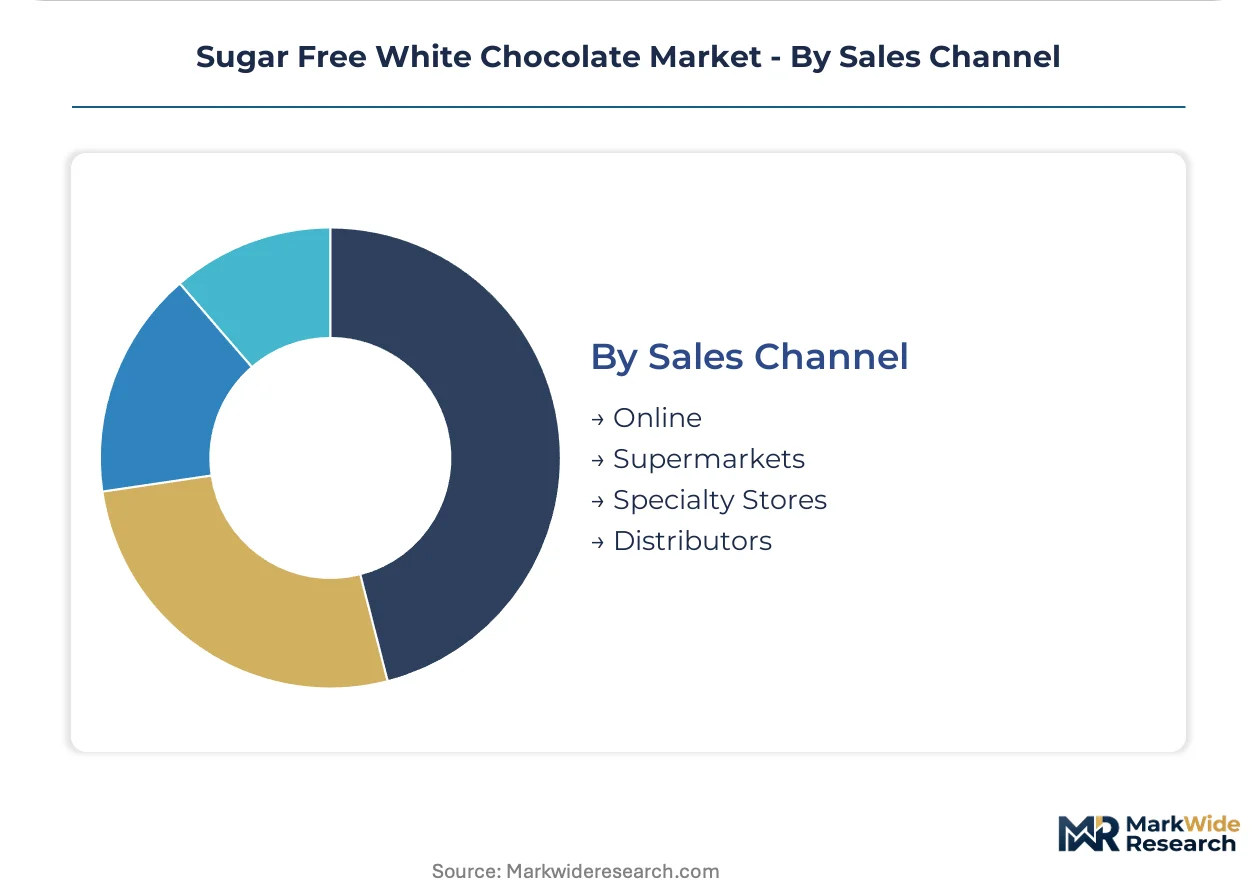
- Online:Direct-to-consumer platforms and marketplace storefronts bypassing traditional slotting fee structures. Subscription replenishment models in United States urban markets capture consumption data that accelerates flavor-variant development cycles.
- Supermarkets:Mass-market retail with planogram placement fees and promotional calendar dependencies.
- Specialty Stores:Premium confectionery and health-food retailers with educated staff and sampling programs.
- Distributors:Foodservice and industrial supply intermediaries with technical sales support and inventory financing.
Supermarkets retain the largest revenue share, while online channels are climbing the fastest as digital-native brands scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with German consumers favoring premium gifting formats while Japanese buyers prioritize precision-calibrated industrial chips for automated production lines.
United States
Functional snacking rituals and glycemic management apps drive direct-to-consumer subscription growth in metropolitan corridors. FDA sugar content disclosure thresholds and alternative sweetener labeling requirements shape formulation decisions for domestic manufacturers. Chicago and Pennsylvania host concentrated confectionery R&D clusters where brands test stevia-erythritol blends for mass-market distribution.
Germany
Retail channels normalize premium sugar-free positioning through educated staff and sampling programs in specialty confectionery stores. EFSA novel food status reviews for emerging sweeteners create regulatory lead times that favor established regulatory affairs capabilities. The Cologne-Düsseldorf corridor anchors European sugar-free chocolate innovation with integrated pilot production facilities.
Japan
Food manufacturers specify narrow particle size distributions for automated depositing equipment in bakery and ice cream applications. METI industrial standards and JIS certification requirements govern import specifications for bulk coatings and inclusions. The Kansai region concentrates precision confectionery manufacturing with technical sales support for industrial procurement.
Switzerland
Swissmedic food safety protocols and premium positioning sustain margins for cocoa butter-intensive formulations targeting gift occasions. The Lake Geneva corridor integrates R&D infrastructure with chocolate tempering expertise for reduced-sugar matrices. Zurich and Vevey host formulation centers developing maltitol-sweetened alternatives for adjacent European markets.
India
FSSAI expanded clearance for novel polyols accelerates local production capacity and reduces import dependency for South Asian manufacturers. BIS standards shape import specifications for multinational suppliers entering the market. Maharashtra and Gujarat develop confectionery manufacturing clusters with nitrogen-flushed bulk packaging for extended storage stability.
Sugar Free White Chocolate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational CPG conglomerates leveraging global manufacturing scale against nimble direct-to-consumer entrants. The upper tier commands shelf presence through mass-market distribution networks and established retail slotting relationships. Three archetypes dominate: Swiss-heritage premium houses, North American mass-market giants, and digital-native specialty brands. Competitive moves concentrate on portfolio diversification into reduced-sugar lines and strategic partnerships with precision fermentation suppliers for cocoa butter security.
Within the heritage premium tier, Lindt & Sprüngli anchors European positioning through Swiss R&D infrastructure, while Hershey's exemplifies mass-market scale advantages in North American retail channels. Mondelez International occupies a position spanning multiple price tiers with regional recipe adaptation capabilities. These three represent contrasting strategic postures on formulation investment, geographic prioritization, and channel access.
| Leading Market Players |
|---|
| Lindt & Sprüngli |
| Hershey's |
| Mondelez International |
| Mars, Inc. |
| Nestlé |
| Lily's Sweets |
| Russell Stover Chocolates |
| ChocZero |
| Pascha Chocolate |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for cocoa butter concentrates in Swiss and German processing facilities directly amplify pricing power for integrated heritage brands while compressing margin buffers for spot-market-dependent compound coating producers. This lead-time asymmetry rewards forward-contract coverage and penalizes speculative procurement in volatile West African supply environments.
Pricing Analysis
Long-term offtake agreements dominate procurement for industrial-scale food manufacturers, while spot purchasing persists among artisan bakeries and emerging direct-to-consumer brands. Three-tier pricing structure across premium couverture, standard compound, and economy coating levels separates Lindt's Swiss-heritage positioning from Mondelez's mass-market adaptation and private-label alternatives. Price differentiation hinges on cocoa butter content certification and clean-label sweetener pedigree, with FDA disclosure compliance adding tier-separating documentation costs. Pricing pressure stems from sucralose-sweetened compound coatings threatening white chocolate's premium positioning in cost-sensitive industrial applications. Food manufacturers exhibit highest price sensitivity due to formulation cost targets, while gift-oriented retail consumers show lowest sensitivity when glycemic management claims are substantiated.
Supply Chain Analysis
Côte d'Ivoire and Ghana anchor raw cocoa bean supply, with Malaysia and Indonesia contributing cocoa butter processing capacity for Asian manufacturing integration. Sugar-free white chocolate production draws from cocoa butter, milk solids, and polyol sweetener inputs, with allulose and erythritol sourcing increasingly tethered to fermentation-based and corn-derived supply chains respectively. Single-source vulnerability concentrates in West African bean supply, where climate disruption and political instability transmit directly to input cost volatility. Distribution runs through temperature-controlled bulk logistics for industrial buyers, while ambient parcel networks serve direct-to-consumer subscription channels with nitrogen-flushed retail formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in this market as direct-to-consumer subscription models displace conventional retail slotting and create niche entry points for formulation-specialist brands. Glycemic management app ecosystems now drive purchase timing, fragmenting demand across precision-segmented consumer cohorts.
For Market Incumbents: Secure forward-contract coverage for cocoa butter supply extending eighteen to twenty-four months to buffer West African disruption risk. Invest in precision fermentation partnerships for cellular agriculture-derived cocoa butter that decouples from commodity crop cycles. Defend against sucralose-sweetened compound coatings by accelerating stevia-erythritol co-crystallization R&D in Swiss and German pilot facilities.
For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription channels for United States metropolitan corridors where glycemic-conscious households bypass traditional retail slotting constraints. Target precision fermentation cocoa butter sourcing as a supply security wedge against incumbent commodity dependence. Deploy rapid flavor-variant testing protocols using consumption data from replenishment models to outpace legacy brand development cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a functional snacking infrastructure play because glycemic management trends embed sugar-free confectionery into preventive health consumption patterns. Acquisition targets should emphasize regulatory affairs capabilities with EFSA pre-submission track records and established clean-label certification pipelines. The signal to watch is FDA allulose labeling guidance clarity, which would unlock European market access and consolidate first-mover positioning for dossier-ready portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Cellular agriculture supply chains promise cocoa butter security decoupled from West African commodity volatility. |
| Direct-to-Consumer Subscription Launch | Bypassing retail slotting fees enables margin capture and rapid flavor iteration with glycemic-conscious households. |
| Clean-Label Certification Investment | Simultaneous organic and sugar-free validations extend product development cycles but command premium positioning. |
| Stevia-Erythritol Co-Crystallization R&D | Advanced blending protocols mask bitter aftertastes in high-cocoa-butter matrices for industrial baker acceptance. |
| EFSA Pre-Submission Dossier Pipeline | Eighteen-month regulatory lead times favor established affairs capabilities for novel sweetener market access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with confectionery formulation chemists, industrial procurement managers at bakery and ice cream manufacturers, retail category buyers, and regulatory affairs specialists at heritage and emerging brands. Secondary validation incorporated FDA GRAS notifications, EFSA novel food status registers, FSSAI sweetener approval gazettes, customs trade data for cocoa butter imports, and SEC filings from publicly traded CPG conglomerates. Bottom-up volume estimates from ingredient supplier shipments were triangulated against top-down retail audit data from Nielsen and Circana coverage of confectionery planograms.
Across the analysis window, forecasts were constructed using a segmented growth model spanning product type, end-user industry, packaging format, and sales channel dimensions. CAGRs were derived from historical volume trajectories adjusted for regulatory approval timelines, sweetener substitution elasticities, and channel shift acceleration parameters. Industry-specific inputs included cocoa butter price forward curves, polyol production capacity expansion announcements, and glycemic management app download correlation indices with confectionery purchase timing.
Material uncertainties — EFSA allulose classification delays, West African supply disruptions, and FSSAI regulatory expansion timelines — sit outside the modeled envelope and could revise trajectory assumptions. Forecasts reflect documented assumptions about sweetener approval pipelines and clean-label certification adoption rates. Recalibration cycles align with material shifts in regulatory guidance, commodity price volatility bands, and direct-to-consumer channel penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Green Tea Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
India Industrial Chocolate Market
Confectionery
Liquorice Shellac Market
Confectionery
North America Dark Chocolate Market
Confectionery
Non-Chocolate Candy Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Premium Chocolate Market
Confectionery
Edible Glitter Market
Confectionery
Gum Base Candy Market
Confectionery
Buttercream Frosting Market
Confectionery
Sugar Free Mints Market
Confectionery
Low Calorie Nutella Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
South America Confectionery Market
Confectionery
Global Sugar Free Chewing Gums Market