
 North America Gummy Market | 2026-2036
North America Gummy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gummy Market Insights
Adult preventive health applications are broadening within the North America gummy landscape as consumers shift from pediatric vitamin routines to personalized, age-specific formulations. Bayer AG leverages its pharmaceutical heritage to sustain credibility in clinically positioned gummy supplements. SmartyPants Vitamins anchors its competitive stance through transparent supply-chain sourcing and third-party testing protocols. Pharmavite, LLC dominates mass retail pharmacy channels with its Nature Made gummy extensions.
North America gummies comprise gelatin or pectin-based chewable matrices infused with vitamins, minerals, botanical extracts, or functional actives, manufactured through starch molding or deposited candy processes that control moisture content below fifteen percent to ensure stability and texture. These products serve nutritional supplementation, condition-specific wellness, and confectionery indulgence purposes across consumer demographics. Functional gummies command premium shelf positioning and margin pools as consumers prioritize sleep support, immunity, and stress management claims over basic multivitamin formats. Sugar-free gummies occupy a narrowing but defensible niche driven by diabetic-friendly and dental-health positioning. Online retail channels are capturing incremental volume as direct-to-consumer subscription models reduce traditional supermarket dependency.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements while the FTC monitors advertising substantiation for health claims, creating a dual compliance architecture that elevates barriers for new entrants lacking quality infrastructure. Health Canada regulates gummy products crossing into the Canadian market through its Natural and Non-prescription Health Products Directorate, requiring distinct site licenses and evidence standards. Stakeholders must monitor evolving state-level cannabis and hemp-derived CBD gummy regulations, as patchwork legislation across California, Colorado, and New York threatens to fragment distribution strategies and reformulation requirements.
Market Dynamics
The North America gummy market is undergoing structural compression as FDA CGMP enforcement intensifies and adult wellness formulations displace legacy pediatric-centric portfolios, forcing manufacturers to rebuild quality infrastructure around clinical-grade positioning.
Growth Catalysts
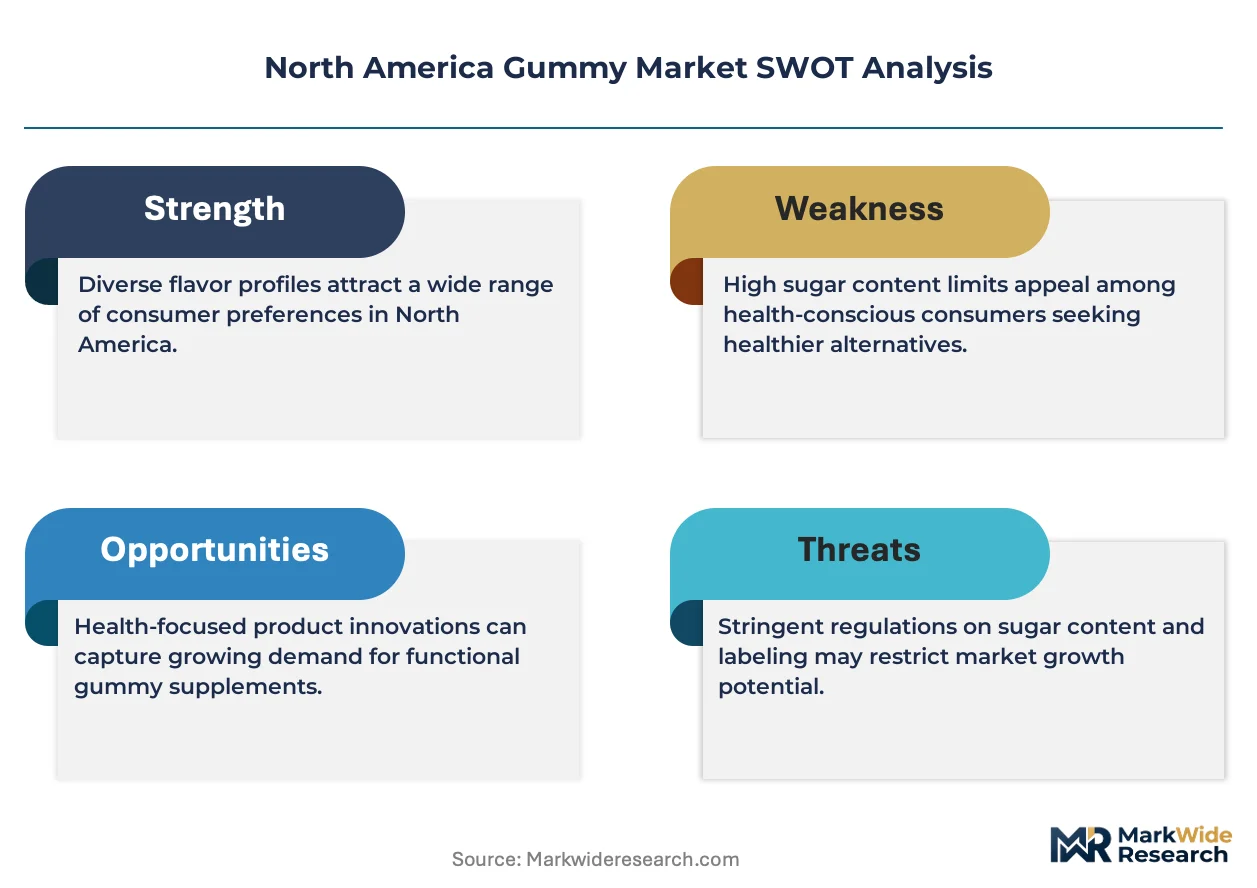
- Preventive health prioritization:Adult consumers in the United States and Canada are migrating from reactive treatment to daily supplementation routines, expanding addressable demand beyond traditional vitamin deficiency correction.
- FTC substantiation standards:Stricter advertising claim requirements are filtering out unsubstantiated products, concentrating volume with manufacturers possessing clinical trial capabilities and quality documentation.
- Pectin-based clean-label migration:Gelatin alternatives derived from citrus and apple sources are capturing plant-forward consumer segments previously excluded from conventional gummy categories.
Market Restraints
- Gelatin price volatility:Bovine and porcine-derived inputs face feedstock cost fluctuations and religious dietary restrictions that complicate formulation standardization across US and Canadian distribution.
- CGMP compliance capital intensity:Small and mid-tier manufacturers lack resources to upgrade facilities to FDA's evolving equipment validation and documentation standards, creating exit pressure.
- CBD regulatory fragmentation:Inconsistent state-level hemp-derived ingredient rules across California, Colorado, and New York force parallel inventory systems and reformulation costs.
Strategic Opportunities
- Mexico market underpenetration:Functional gummy adoption in Mexican pharmacy and modern trade channels remains nascent relative to US saturation, offering first-mover positioning for clinically branded entrants.
- Direct-to-consumer subscription models:Recurring revenue platforms bypass slotting fee burdens of conventional retail, enabling margin recovery and personalized formulation services.
- Sugar-free diabetic positioning:Erythritol and allulose-sweetened matrices address unmet demand from prediabetic and dental-conscious segments underserved by conventional sucrose-based products.
Industry Challenges
- Stability science talent scarcity:Formulation chemists capable of managing sub-fifteen-percent moisture matrices with bioactive integrity command premium compensation and limited supply.
- Third-party certification timelines:NSF International and USP verification processes extend launch schedules by eight to fourteen months, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gummy Market |
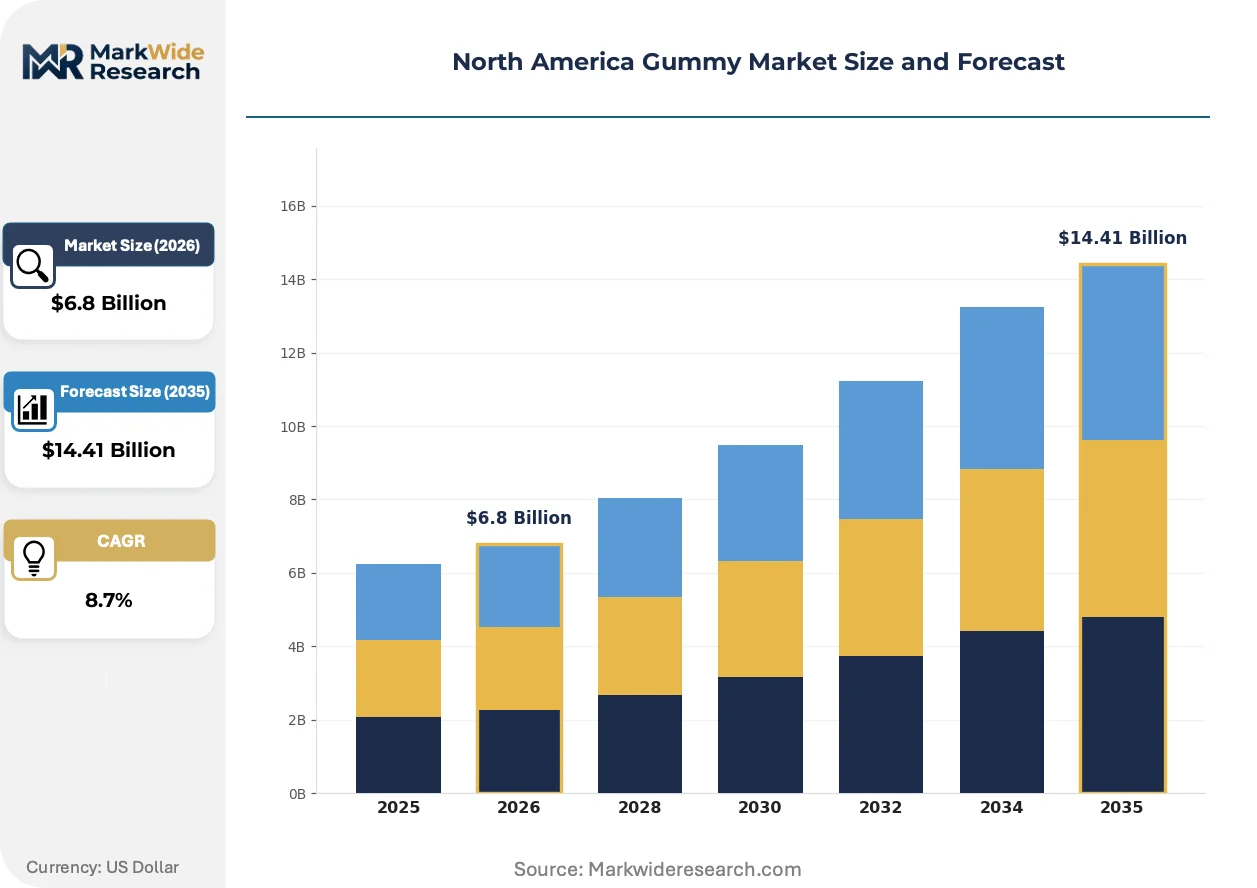
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegan Gummies, Sugar-Free Gummies, Functional Gummies, Organic Gummies Flavor Profile: Fruit, Sour, Herbal, Chocolate Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores Target Consumer: Children, Adults, Seniors, Fitness Enthusiasts |
| Companies Covered | Church & Dwight Co., Inc., Bayer AG, Haleon plc, SmartyPants Vitamins, Garden of Life, Pharmavite, LLC, Nature’s Bounty, Ferrara Candy Company, The Hershey Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gummy Market Trends and Innovations
Formulation science and channel architecture are converging to reshape competitive advantage in North American gummies, with stability engineering and regulatory navigation displacing mere flavor innovation as primary differentiators.
Microencapsulation technology for heat-sensitive actives like probiotics and certain botanical extracts is electrifying product development pipelines. Premium wellness brands in California and New York are adopting these protective matrices at accelerated pace. This engineering capability is compressing the shelf-life gap between gummies and traditional capsules, enabling pharmacy-tier positioning previously unattainable for confectionery formats.
FDA's evolving dietary supplement labeling requirements are forcing systematic reformulation across the United States. Manufacturers must rebuild specification sheets and supplier qualification protocols to meet tightened identity testing mandates. The clinical and condition-specific wellness segments are responding fastest, investing in in-house analytical laboratories rather than relying on contract testing.
Subscription-based replenishment models are displacing conventional supermarket impulse purchasing among core adult demographics. Direct-to-consumer platforms capture recurring revenue from sleep support and stress management formulations, bypassing slotting fee structures that burden mass retail channels. This behavioral shift concentrates most visibly in urban coastal markets where delivery infrastructure and digital payment penetration enable frictionless reordering cycles.
North America Gummy Market Segmentation
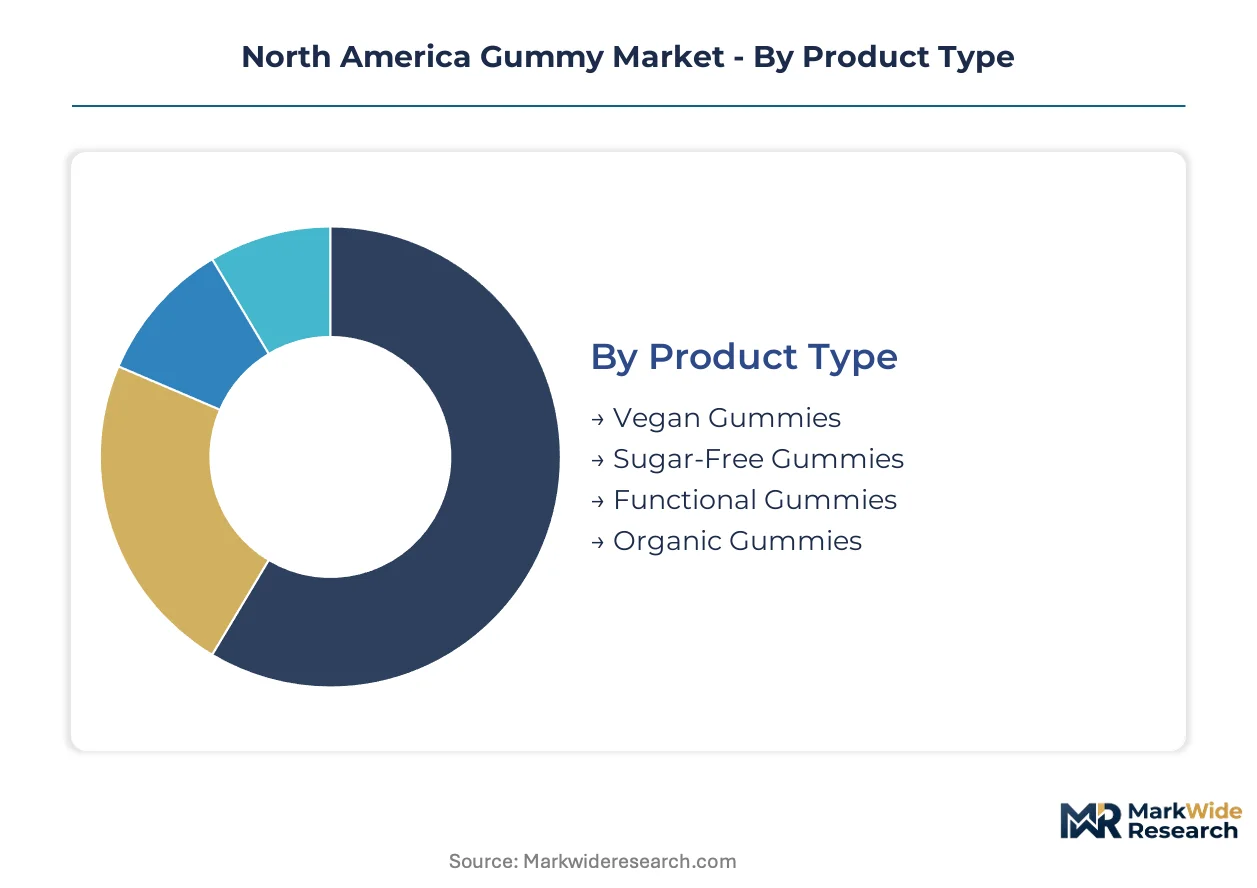
Segmentation in the North America gummy market reveals how formulation chemistry and channel architecture fragment production capacity across distinct margin pools. Manufacturers must align facility investments with specific matrix requirements and regulatory exposure profiles.
Product Type:
Supply concentration clusters around gelatin-based legacy infrastructure, though pectin-capable facilities command premium positioning as clean-label demand reshapes procurement patterns.
- Functional Gummies:These matrices incorporate condition-specific actives including melatonin, ashwagandha, and elderberry extracts within stabilized sub-fifteen-percent moisture environments. Demand concentrates in California and New York metro corridors where pharmacy-tier positioning and subscription replenishment models dominate. Sleep support and immunity claims drive premium shelf placement.
- Vegan Gummies:Citrus and apple-derived pectin replaces animal gelatin to capture plant-forward consumer segments and religious dietary compliance. Production requires modified setting temperatures and acidulant profiles that constrain contract manufacturing options.
- Sugar-Free Gummies:Erythritol and allulose sweetening matrices address diabetic-friendly and dental-health positioning.
- Organic Gummies:USDA-certified ingredient sourcing with restricted synthetic additive portfolios.
Functional gummies absorb the bulk of installed capacity; vegan gummies are expanding most quickly.
Flavor Profile:
Cost tier differentiation separates commodity fruit formulations from premium botanical and confectionery-positioned variants, with sour profiles commanding specialized acidulant infrastructure.
- Fruit:Strawberry, orange, and mixed berry profiles dominate mass retail velocity with standardized flavor house supply agreements.
- Sour:Citric and malic acid coatings require dedicated tumbling equipment and humidity-controlled finishing rooms.
- Herbal:Echinacea, turmeric, and ginger extracts mask bitterness through advanced flavor modulation technologies.
- Chocolate:Cocoa butter and alkalized powder matrices demand fat-compatible gelling systems with distinct temperature protocols.
Fruit flavors anchor volume throughput; herbal profiles gain share fastest in adult wellness channels.
Distribution Channel:
Volume concentration in conventional retail is eroding as direct-to-consumer platforms capture recurring revenue from condition-specific formulations with superior margin recovery.
- Online Retail:Subscription-based replenishment models bypass slotting fee burdens while enabling personalized formulation services and customer data capture. California and New York urban markets show highest penetration.
- Supermarkets:Impulse-driven multivitamin purchases concentrate in mass retail pharmacy sections with heavy trade promotion dependency.
- Health Food Stores:Natural channel positioning with third-party certification requirements and educated staff recommendations.
- Convenience Stores:Single-serve energy and immunity gummies targeting immediate consumption occasions.
Supermarkets retain the largest share of physical throughput; online retail climbs the fastest with steepest expansion trajectory.
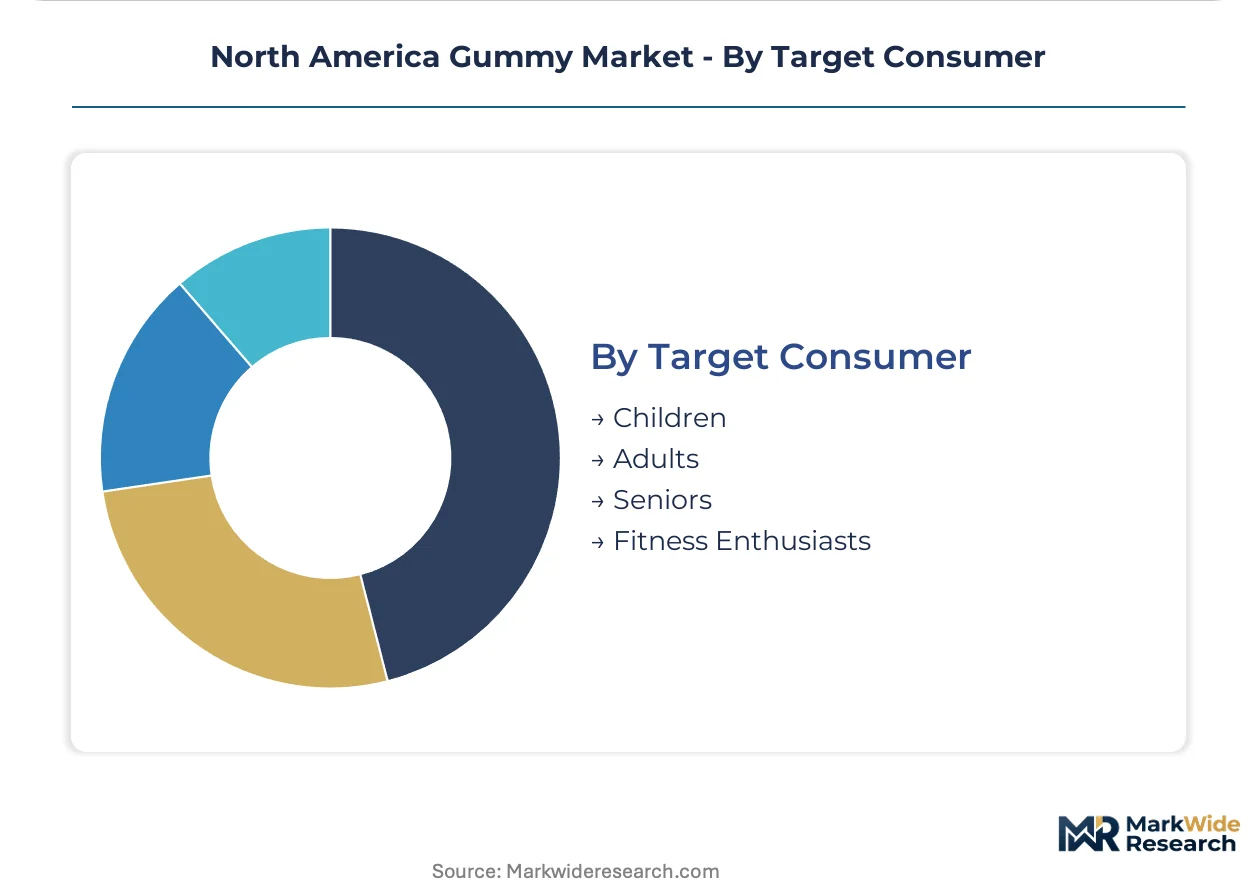
Target Consumer:
Application focus has shifted decisively from pediatric deficiency correction toward adult preventive health and condition-specific wellness routines.
- Adults:Personalized, age-specific formulations targeting stress management, sleep quality, and metabolic support with clinical-grade positioning. Demand clusters in professional urban demographics.
- Fitness Enthusiasts:Pre-workout energy, post-workout recovery, and electrolyte replacement matrices with performance marketing.
- Children:Traditional vitamin A, C, and D supplementation with taste-optimized profiles for compliance.
- Seniors:Joint health, cognitive support, and medication interaction-conscious formulations with softer texture requirements.
Adult segments capture the majority of formulation R&D investment; fitness enthusiast targeting is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in distressed urban census tracts have concentrated gummy manufacturing investment in designated low-income communities across the United States, creating tax-advantaged production clusters that reshape regional supply patterns.
United States
Adult wellness subscription models concentrate demand in California and New York metro corridors where direct-to-consumer platforms capture recurring revenue from sleep support formulations. FDA CGMP enforcement intensifies compliance burdens, forcing facility upgrades among domestic manufacturers. Los Angeles and Brooklyn host emerging clean-label production clusters serving plant-forward consumer segments.
Canada
Natural health product licensing through Health Canada's NNHP Directorate creates distinct entry barriers for US brands seeking cross-border distribution. Toronto and Vancouver anchor functional gummy demand in pharmacy and natural retail channels. Quebec's regulatory bilingualism requirements add localization costs for national distribution strategies.
Mexico
Modern trade pharmacy channels in Mexico City and Monterrey show nascent functional gummy adoption relative to US saturation levels. COFEPRIS regulatory alignment with US FDA standards facilitates import pathways for clinically positioned brands. Nuevo León's manufacturing corridor attracts contract production investment serving North American distribution.
North America Gummy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical heritage companies commanding pharmacy-tier positioning while confectionery giants leverage retail velocity. The vendor base organizes around three strategic archetypes: clinical-credibility players with pharmaceutical lineages, clean-label specialists emphasizing supply-chain transparency, and mass-market confectionery houses with distribution scale. Capacity expansion and third-party certification acquisition represent the dominant competitive moves as quality infrastructure becomes the primary differentiator.
Among pharmaceutical-heritage competitors, Bayer AG exemplifies clinical-grade positioning through its supplement portfolio, while SmartyPants Vitamins occupies a position within the transparency-focused specialist tier. Pharmavite, LLC represents the mass-retail pharmacy archetype through its Nature Made extensions, anchoring volume concentration in conventional drugstore channels.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Bayer AG |
| Haleon plc |
| SmartyPants Vitamins |
| Garden of Life |
| Pharmavite, LLC |
| Nature's Bounty |
| Ferrara Candy Company |
| The Hershey Company |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up contract manufacturers dominate North American gummy production capacity, creating disciplined pricing power through consolidated procurement leverage and selective capacity allocation across branded and private-label portfolios.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent replenishment orders commanding premium positioning from scheduled contract volumes securing baseline economics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from gelatin feedstock volatility and CGMP compliance capital requirements compressing margins at mid-tier manufacturers. Mass retail pharmacy buyers exhibit highest price sensitivity due to trade promotion dependency, while direct-to-consumer subscription platforms absorb modest premiums for formulation customization.
Supply Chain Analysis
Single-source vulnerability sits with bovine and porcine gelatin suppliers concentrated in Brazil and Argentina, exposing formulation standardization to religious dietary restriction complications and feedstock cost swings. Active ingredient sourcing draws from India and China for botanical extracts and synthetic vitamins, with pectin alternatives anchored in citrus processing regions of Florida and California. Tariff exposure on imported raw materials creates margin instability for manufacturers lacking backward integration into gelling agent production. Distribution runs through regional distribution centers serving mass retail pharmacy chains, with direct-to-consumer fulfillment bypassing traditional wholesale layers in urban coastal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as FDA CGMP enforcement and third-party certification timelines force sub-scale manufacturers toward exit or acquisition, concentrating viable production capacity with quality-infrastructure leaders.
For Market Incumbents: Anticipate margin compression from pectin-based clean-label migration by securing multi-year citrus pectin supply agreements and accelerating in-house analytical laboratory investment to compress NSF verification timelines. Defensive positioning requires channel control through direct-to-consumer subscription platform development, reducing trade promotion dependency in mass retail pharmacy. Threat substitution from functional beverage formats demands clinical trial substantiation for condition-specific claims to sustain pharmacy-tier positioning. For New Entrants and Emerging Players: Capture underpenetrated pharmacy channels in Mexico City and Monterrey through COFEPRIS-aligned clinical positioning, leveraging regulatory familiarity from US FDA experience. White-space concentration in sugar-free diabetic positioning with erythritol and allulose matrices offers formulation differentiation from sucrose-saturated domestic competition. Go-to-market execution favors pharmacy detailing relationships over supermarket slotting fee battles, building prescriber endorsement before retail expansion. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with validated CGMP infrastructure but constrained working capital in Qualified Opportunity Zones across distressed urban census tracts. Long-term viability over the next decade hinges on subscription revenue platform integration and clean-label production capability. The inflection signal to monitor is pectin-capable facility utilization rates crossing threshold levels that trigger capacity expansion decisions among consolidated contract manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| CGMP Facility Certification | FDA compliance validation opens pharmacy-tier distribution channels previously inaccessible to confectionery-format entrants. |
| Pectin Production Capability | Plant-forward gelling systems capture religious dietary compliance and vegan consumer segments in California and New York. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models bypass supermarket slotting fees while capturing recurring revenue from sleep support formulations. |
| Microencapsulation Technology Investment | Heat-sensitive active protection enables probiotic and botanical extract stability for pharmacy-grade positioning. |
| Mexico Market Entry | COFEPRIS regulatory alignment facilitates first-mover positioning in nascent functional gummy pharmacy channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with formulation chemists, contract manufacturing executives, retail pharmacy category buyers, and Health Canada licensing specialists. FDA CGMP inspection databases, NSF International certification registries, and Nielsen retail audit data provided volume and positioning validation. Bottom-up capacity modeling across gelatin and pectin-capable facilities reconciled with top-down expenditure estimates from disclosed manufacturing investments.
Data-stream reconciliation across shipment records, production capacity surveys, and channel inventory positions informed the analytical framework over the projection horizon. Segmentation dimensions encompassed product matrix type, distribution channel architecture, target consumer demographic, and flavor profile positioning. CAGRs were derived from fitted trend extrapolation moderated by regulatory event probability and raw material cost trajectory assumptions, with specific weighting applied to adult wellness subscription growth patterns and Mexican market penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA labeling requirement evolution, state-level CBD regulatory fragmentation, and gelatin price volatility from feedstock markets. Forecasts reflect documented assumptions regarding CGMP enforcement intensity and clean-label migration velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Caramel Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
Macarons Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Edible Glitter Market
Confectionery
South America Confectionery Market
Confectionery
Germany Chocolate Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
Chocolate Couverture Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Milk Chocolate Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
Fat Free Candy Market
Confectionery
Middle-East and Africa Compound Chocolate Market