
 Very Low Calorie Desserts Market | 2026-2036
Very Low Calorie Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Very Low Calorie Desserts Market Analytics
Single-source to multi-source ingredient procurement is recalibrating how dessert manufacturers manage sweetener and dairy substitute supply chains. Grupo Bimbo leverages its North American bakery network to secure alternative sweetener contracts at scale. Welch Foods, Inc. anchors its positioning through controlled fruit sourcing for gelatin and pudding lines. Pepperidge Farm Inc. differentiates via in-house R&D facilities that test low-calorie formulations before commercial rollout.
Very low calorie desserts are formulated products delivering fewer than 40 calories per standard serving, typically employing high-intensity sweeteners, bulking agents, and modified starch systems to replicate conventional dessert mouthfeel and texture. Their primary commercial purpose centers on enabling portion-controlled indulgence within calorie-restricted dietary regimens. Gelatin desserts occupy the mature volume base due to established manufacturing infrastructure and lower ingredient costs, while ice creams capture premium margin pools through complex emulsion engineering and flavor masking technology. The fitness enthusiast end-user segment shows structural momentum as protein-fortified low-calorie formats expand beyond traditional diet positioning.
FDA nutrition labeling mandates and EFSA health claim frameworks jointly shape permissible calorie thresholds and marketing language across major markets. The USDA National Organic Program and EU organic regulations further constrain sweetener and additive selections for certified product lines. Stakeholders must monitor evolving sweetener safety assessments and front-of-pack labeling schemes to anticipate reformulation cycles and retailer listing requirements.
Market Dynamics
FDA calorie disclosure mandates and EFSA nutrient profiling frameworks are forcing simultaneous reformulation across multiple product lines, compressing development cycles and elevating R&D capex requirements for dessert manufacturers.
Growth Catalysts
- FDA Nutrition Labeling Mandates:Calorie disclosure requirements push manufacturers toward reformulated portfolios, expanding shelf space for compliant low-calorie formats in US retail channels.
- Protein Fortification Technology:Fitness enthusiasts drive structural demand for hybrid dessert-nutrition products, blurring traditional category boundaries and creating premium positioning opportunities.
- Western Europe Retail Consolidation:EFSA-aligned retailer acceptance standards concentrate distribution power behind validated low-calorie lines, accelerating category maturation in Germany, France, and the United Kingdom.
Market Restraints
- High-Intensity Sweetener Cost Volatility:Sucralose and stevia extract prices fluctuate with agricultural yields and extraction capacity constraints, squeezing margin stability for reformulated products.
- Emulsion Engineering Bottlenecks:Ice cream applications require complex fat-replacement systems that few contract manufacturers can execute at scale, limiting premium segment supply elasticity.
- EU Additive Authorization Friction:EFSA novel food assessments delay new bulking agent approvals, extending time-to-market for next-generation texture systems by 18-36 months.
Strategic Opportunities
- US Fitness Channel Expansion:Direct-to-consumer subscription models bypass traditional retail slotting fees, enabling margin capture from protein-fortified dessert loyalists.
- Clean-Label Convergence:USDA Organic certification intersects with low-calorie positioning, opening dual-claim products to premium pricing in natural grocery channels.
- South Korean Functional Food Framework:MFDS health claim pathways permit specific satiety and blood glucose positioning, creating first-mover advantage for clinically substantiated formulations.
Industry Challenges
- Sensory Scientist Scarcity:Formulation expertise spanning high-intensity sweetener masking and texture engineering commands premium compensation, constraining mid-tier manufacturer hiring pipelines.
- Dual Certification Timeline Compression:Simultaneous FDA GRAS self-affirmation and EFSA novel food dossier preparation strains regulatory affairs bandwidth, delaying coordinated transatlantic launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Very Low Calorie Desserts Market |
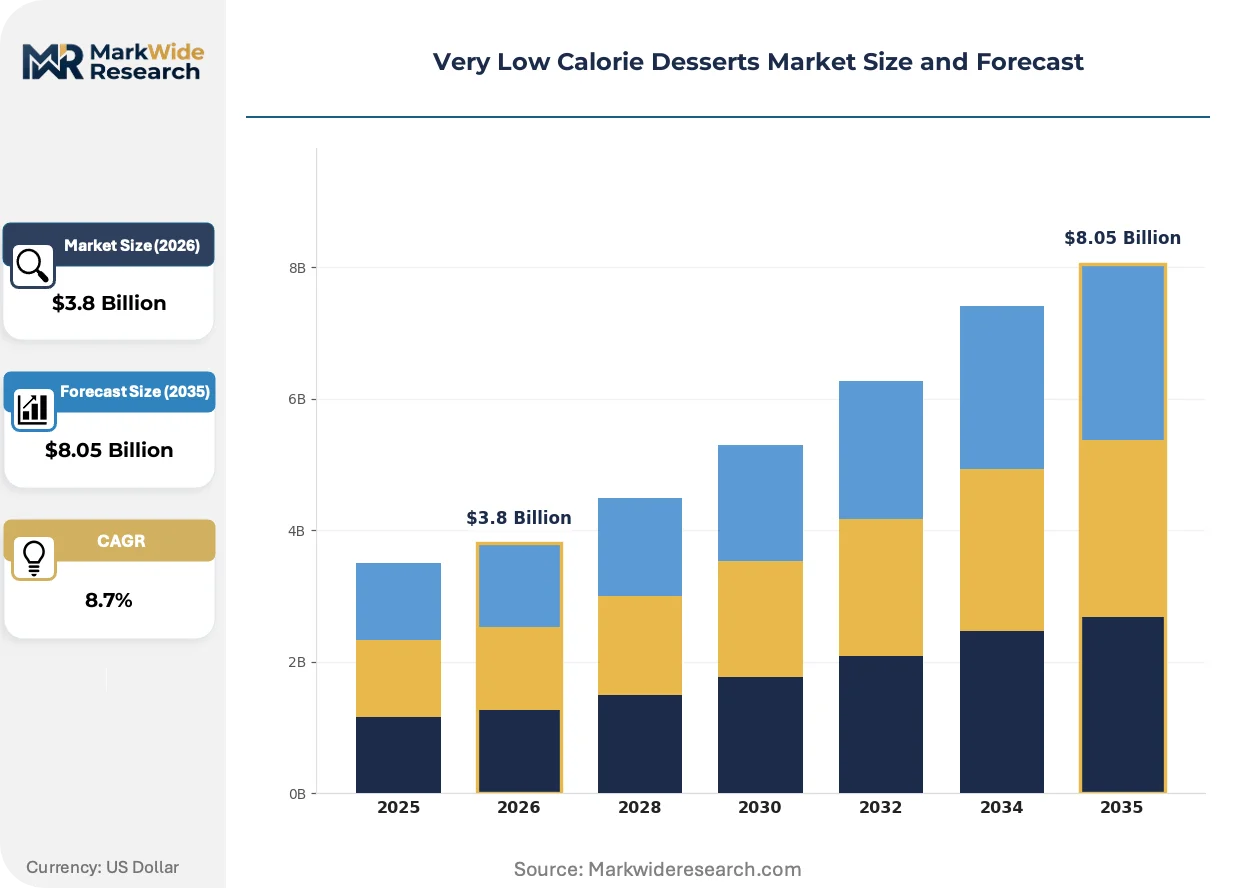
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin Desserts, Puddings, Ice Creams, Soufflés End User: Dieters, Fitness Enthusiasts, Health-Conscious Consumers, Weight Watchers Distribution Channel: Online Retailers, Supermarkets, Health Food Stores, Specialty Shops Flavor Profile: Chocolate, Vanilla, Strawberry, Coconut |
| Companies Covered | Welch Foods, Inc., Sara Lee Corporation, Bake-N-Serv Inc., Perkins & Marie Callender's, LLC, Dole Food Company, Inc., Lawler Foods Ltd., Grupo Bimbo, Pepperidge Farm Inc., Del Monte Food, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Very Low Calorie Desserts Market Evolving Landscape
Texture replication technologies and procurement model evolution are redrawing competitive boundaries between established dessert manufacturers and ingredient technology suppliers, with control over mouthfeel IP emerging as the decisive capability differentiator.
Modified starch and hydrocolloid blending systems are consolidating technical leadership among specialized ingredient houses. Mid-sized dessert manufacturers adopt these pre-validated texture platforms to shortcut internal R&D investment. The technology is consolidating formulation expertise upstream, compressing the value captured by finished goods producers.
EFSA front-of-pack nutrient profiling is reshaping permissible marketing claims across EU member states. Manufacturers must reformulate to meet score thresholds or face retailer delisting pressure. Ice cream and dairy-alternative segments bear the heaviest compliance burden, accelerating clean-label ingredient substitution.
Subscription-based replenishment models are displacing conventional impulse purchasing in the fitness-oriented consumer segment. Direct-to-consumer channels capture recurring revenue from protein-fortified dessert loyalists, bypassing traditional grocery slotting fee structures. This behavioral shift concentrates most visibly in United States metropolitan markets with established meal-kit infrastructure.
Very Low Calorie Desserts Market Segmentation
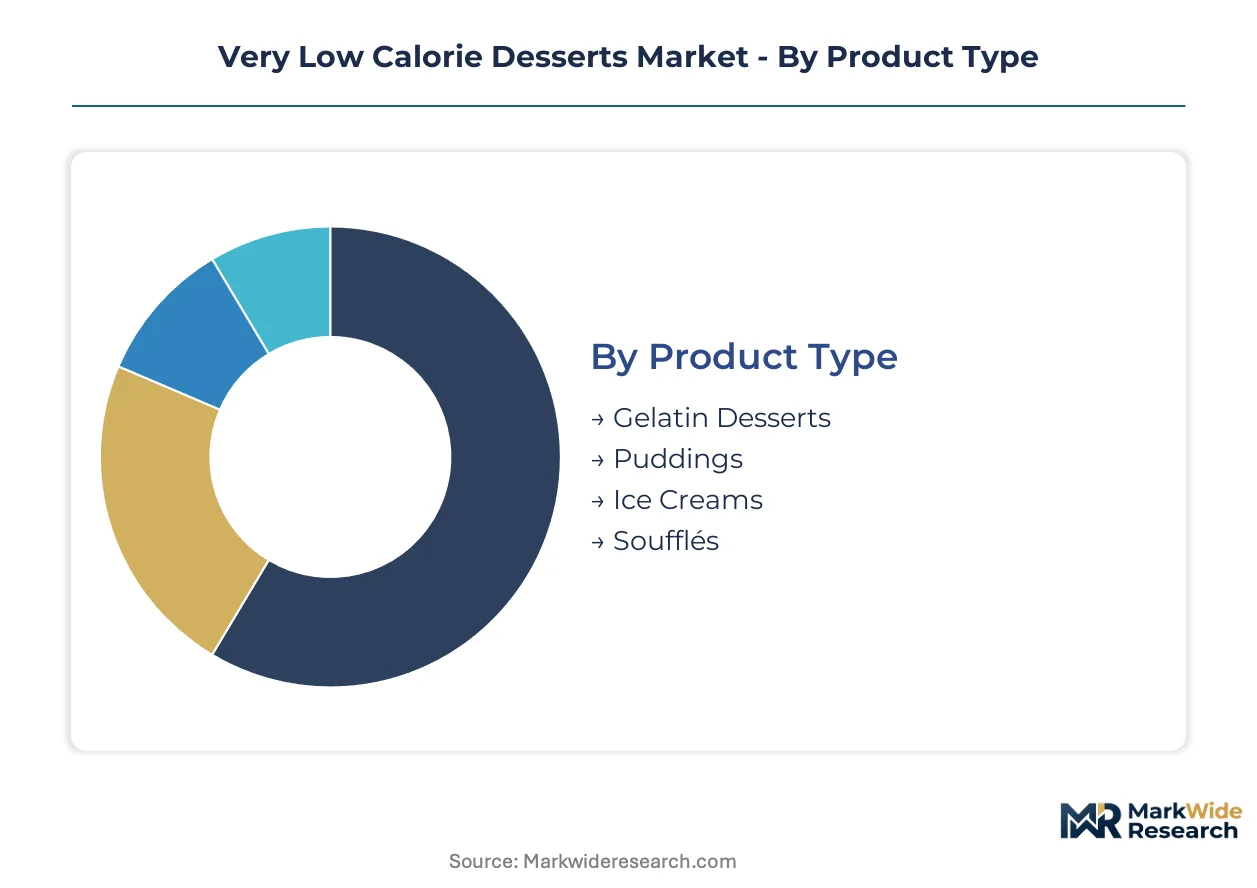
Segmentation in very low calorie desserts reveals distinct certification burdens and technical requirements across product formats. Each category demands specific FDA GRAS affirmations or EFSA novel food approvals that shape commercial viability and geographic rollout sequencing.
Product Type:
FDA GRAS self-affirmation applies universally, yet EFSA novel food dossiers create divergent approval timelines: gelatin desserts clear fastest, while ice creams face extended emulsion additive reviews.
- Ice Creams:Complex fat-replacement emulsions require sucralose-stevia masking systems and modified starch stabilization. Demand concentrates in United States metropolitan fitness corridors where protein-fortified formats command premium shelf positioning.
- Gelatin Desserts:Established manufacturing infrastructure and lower ingredient costs sustain volume leadership. EFSA-aligned retailers in Germany and France validate these lines first, compressing time-to-market for compliant formulations.
- Puddings:Controlled fruit sourcing from suppliers like Welch Foods anchors clean-label positioning for USDA Organic certification.
- Soufflés:Technical complexity limits contract manufacturing capacity, constraining supply elasticity for premium positioning.
Leading the category by volume: Gelatin Desserts. Growing fastest: Ice Creams.
End User:
Customer type determines channel strategy and pricing architecture, with fitness enthusiasts driving subscription economics while traditional dieters remain tethered to impulse retail.
- Fitness Enthusiasts:Protein-fortified hybrid formats blur dessert-nutrition boundaries. Direct-to-consumer subscription models in United States metro markets bypass grocery slotting fees and capture recurring revenue from loyalists.
- Health-Conscious Consumers:Dual-claim USDA Organic and low-calorie positioning opens premium pricing in natural grocery channels across California and New York clusters.
- Dieters:Portion-controlled indulgence demand sustains gelatin dessert volume in conventional retail.
- Weight Watchers:Structured program alignment requires specific calorie threshold compliance for co-branded distribution partnerships.
Volume leadership: Dieters. Steepest expansion trajectory: Fitness Enthusiasts.
Distribution Channel:
Channel selection dictates margin capture mechanics, with online subscription infrastructure displacing traditional retail economics in fitness-oriented segments.
- Online Retailers:Subscription replenishment models concentrate recurring revenue from protein-fortified loyalists. United States meal-kit infrastructure enables direct margin capture without retailer listing fees.
- Supermarkets:EFSA front-of-pack nutrient profiling in Western Europe creates delisting pressure for non-compliant lines, accelerating clean-label reformulation investments.
- Health Food Stores:USDA Organic certification requirements constrain sweetener selections for certified product lines in natural grocery channels.
- Specialty Shops:Curated assortment strategies favor premium ice cream formats with complex texture engineering credentials.
Dominant by transaction volume: Supermarkets. Gaining share fastest: Online Retailers.
Flavor Profile:
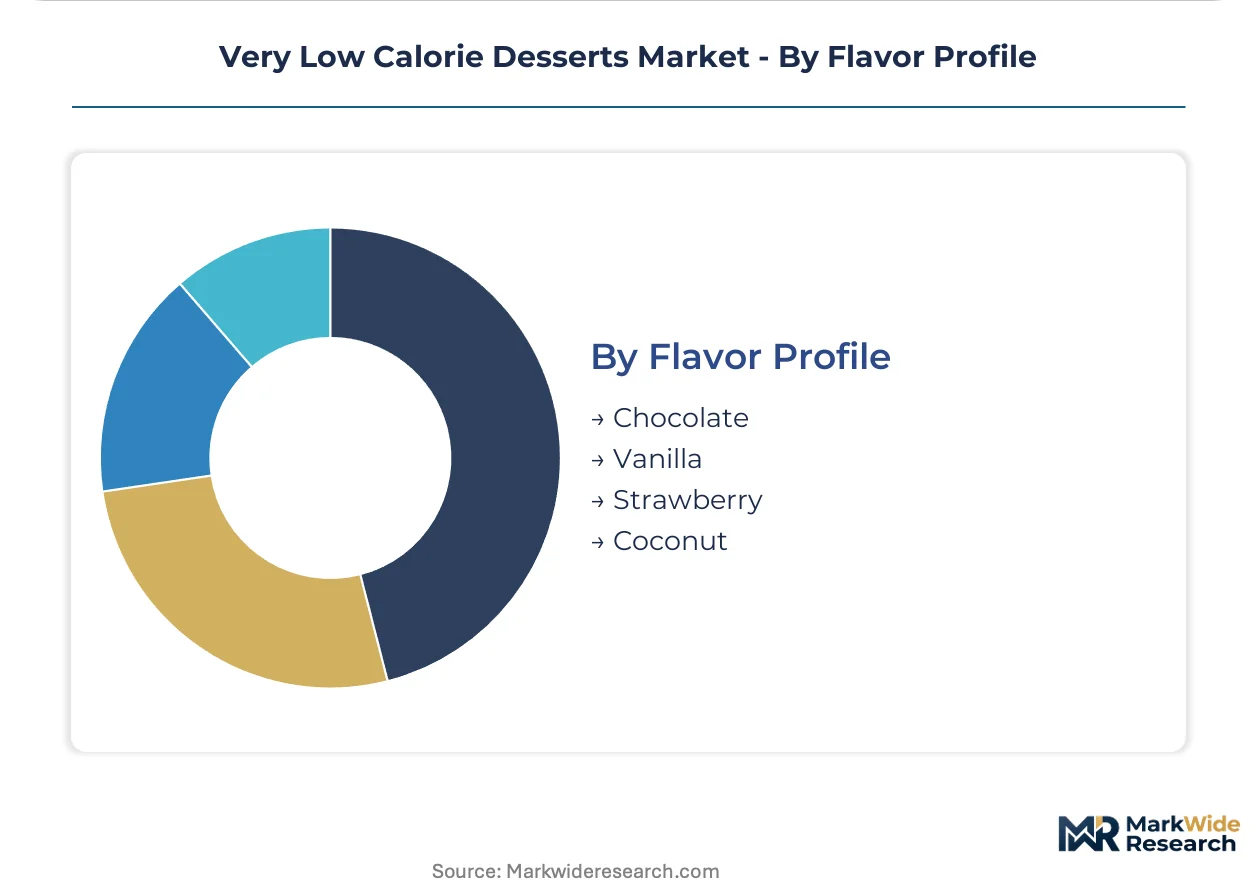
Flavor selection intersects with high-intensity sweetener masking challenges, with vanilla and chocolate demanding most sophisticated formulation engineering to replicate conventional mouthfeel.
- Chocolate:Cocoa polyphenol bitterness requires advanced stevia-sucralose blending systems. Pepperidge Farm in-house R&D facilities test low-calorie chocolate formulations before commercial rollout.
- Vanilla:Clean flavor perception makes masking technology performance most visible to consumers. EFSA additive authorization friction for novel bulking agents delays next-generation vanilla texture systems.
- Strawberry:Controlled fruit sourcing from established suppliers enables clean-label positioning without synthetic flavor additives.
- Coconut:Emerging flavor profile in protein-fortified formats targeting fitness enthusiast subscription channels.
Volume leader: Chocolate. Climbing the fastest: Coconut.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stevia cultivation clusters in Paraguay and China anchor global sweetener supply chains for very low calorie dessert formulations. FDA labeling mandates in the United States and EFSA nutrient profiling in Western Europe drive divergent reformulation priorities across major consumption markets.
United States
Fitness enthusiasts in metropolitan corridors sustain protein-fortified dessert demand through direct-to-consumer subscription channels. FDA calorie disclosure requirements for retail packaged foods compress development cycles for reformulated portfolios. Greater Boston and New York Metro clusters concentrate R&D facilities testing high-intensity sweetener masking systems before national rollout.
Germany
EFSA-aligned retailer acceptance standards validate low-calorie lines ahead of other EU member states. The country's national food safety regulator enforces strict additive authorization timelines that delay novel bulking agent approvals. Bavaria and North Rhine-Westphalia host manufacturing infrastructure for gelatin dessert volume production serving pan-European distribution.
United Kingdom
Health-conscious consumers in London and Southeast England drive dual-claim organic and low-calorie positioning in premium grocery channels. Front-of-pack nutrient profiling schemes create delisting pressure for non-compliant dessert formulations. Midlands industrial zones concentrate contract manufacturing capacity for clean-label pudding production.
South Korea
MFDS health claim pathways permit specific satiety and blood glucose positioning for clinically substantiated formulations. The country's functional food framework attracts first-mover investment in protein-fortified dessert innovation. Seoul Capital Area meal-kit infrastructure enables subscription-based replenishment models bypassing traditional retail economics.
France
EFSA nutrient profiling influences product development priorities for dessert manufacturers targeting EU-wide distribution. The country's national food safety authority maintains rigorous novel food assessment protocols extending time-to-market for texture system innovations. Île-de-France and Auvergne-Rhône-Alpes clusters anchor clean-label ingredient sourcing relationships for certified organic lines.
Very Low Calorie Desserts Market Competitive Landscape
Portfolio diversification dominates the current landscape as established food manufacturers expand into adjacent low-calorie formats. The vendor base spans multinational conglomerates with integrated bakery networks, specialized dessert houses with controlled ingredient sourcing, and regional players with localized flavor expertise. Three archetypes define competitive positioning: scale-driven manufacturers leveraging procurement volume, R&D-intensive formulators controlling texture IP, and sourcing-specialists securing clean-label supply chains. M&A activity and strategic partnerships concentrate among players seeking sweetener security and emulsion engineering capabilities.
Within the scale-driven tier, Grupo Bimbo represents integrated bakery network advantages securing alternative sweetener contracts at volume. Welch Foods, Inc. exemplifies controlled ingredient sourcing archetypes through anchored fruit supply relationships for gelatin and pudding lines. Pepperidge Farm Inc. occupies the R&D-intensive position with in-house facilities testing low-calorie formulations prior to commercial deployment. These three entities collectively illustrate how procurement posture, technical capability, and supply chain control differentiate competitive positioning across the category.
| Leading Market Players |
|---|
| Welch Foods, Inc. |
| Sara Lee Corporation |
| Bake-N-Serv Inc. |
| Perkins & Marie Callender's, LLC |
| Dole Food Company, Inc. |
| Lawler Foods Ltd. |
| Grupo Bimbo |
| Pepperidge Farm Inc. |
| Del Monte Food, Inc. |
| Others |
Value Network & Pricing Analysis
Sensory scientist concentration in Greater Boston and New York Metro clusters drives labor-cost premiums that widen spreads between premium protein-fortified formats and economy gelatin lines. FDA calorie disclosure mandates compress development timelines, forcing manufacturers to absorb specialist compensation premiums or outsource to contract texture houses.
Pricing Analysis
Service bundling separates premium ice cream formulations with in-house R&D validation from unbundled commodity gelatin competing on slotting-fee efficiency. Three-tier pricing structure across premium protein-fortified, standard clean-label, and economy private-label tiers reflects certification grade and after-sales technical support inclusion. Pricing pressure stems from high-intensity sweetener cost volatility squeezing mid-tier manufacturers. Fitness enthusiasts show lowest price sensitivity through subscription lock-in, while conventional dieters in mass retail remain highly elastic.
Supply Chain Analysis
Workforce availability constraints in Bavaria and North Rhine-Westphalia limit gelatin dessert capacity expansion despite pan-European demand. Stevia cultivation in Paraguay and China draws from agricultural yield cycles, while modified starch production concentrates in Midwestern United States and EU ingredient houses. Single-source vulnerability in high-intensity sweetener extraction creates supply chain risk. Distribution runs through EFSA-aligned retail consolidators in Western Europe and direct-to-consumer meal-kit infrastructure in United States metro markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from simultaneous FDA and EFSA reformulation mandates is forcing smaller manufacturers toward acquisition or exit. Technical capability gaps in emulsion engineering and sensory masking create asymmetric consolidation opportunities.
For Market Incumbents: Acquire texture IP portfolios from specialized hydrocolloid houses to internalize mouthfeel differentiation. Lock in multi-year alternative sweetener contracts before agricultural yield volatility intensifies. Expand in-house R&D facilities in Greater Boston clusters to capture scarce sensory scientist talent ahead of competitor hiring. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer lowest barrier-to-entry for protein-fortified dessert launches bypassing grocery slotting fees. Target fitness enthusiast segments in United States metro markets with established meal-kit infrastructure. Lead with coconut flavor profiles where masking technology requirements remain less demanding than chocolate or vanilla. For Investors and Strategic Acquirers: Re-rating potential sits with R&D-intensive formulators controlling validated texture platforms given EFSA novel food approval backlogs extending competitive moats. Long-term viability favors players with captive sweetener sourcing and dual FDA-EFSA regulatory bandwidth. Watch EFSA front-of-pack nutrient profiling implementation velocity as inflection indicator for clean-label premiumization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Texture Platform Acquisition | Consolidates mouthfeel IP upstream, compressing value captured by finished goods producers. |
| Direct-to-Consumer Launch | Bypasses EFSA-aligned retailer slotting fees in United States metropolitan fitness corridors. |
| Dual Certification Investment | Enables coordinated FDA GRAS and EFSA novel food dossier preparation for transatlantic rollout. |
| Controlled Fruit Sourcing Agreement | Anchors USDA Organic certification for clean-label pudding positioning in natural grocery channels. |
| Protein Fortification Scale-Up | Captures structural demand from fitness enthusiasts blurring dessert-nutrition category boundaries. |
Research Methodology
Independent corroboration across sensory scientist interviews, regulatory affairs directors, and retail category buyers underwrites the qualitative findings. Primary fieldwork engaged formulation chemists at ingredient technology houses, procurement leads at dessert manufacturers, and channel partners in United States and Western European distribution networks. Secondary validation drew from FDA GRAS affirmation databases, EFSA novel food registers, and Nielsen retail audit data. Bottom-up segment sizing triangulated against top-down category value estimates.
Rate-of-change decomposition separated volume growth from mix-shift effects across the projection horizon. The analytical framework modeled product type, end user archetype, distribution channel, and flavor profile dimensions. CAGRs derived from segment-level growth trajectories weighted by base-year revenue contribution. Forecast inputs incorporated EFSA additive authorization timelines and protein fortification technology adoption curves.
The model holds under stable regulatory enforcement intensity; deviation in EFSA front-of-pack profiling stringency or FDA sweetener safety reassessments would shift reformulation investment timing. Forecasts reflect assumptions about agricultural yield stability for stevia and sucralose feedstocks. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Europe Functional Water Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
Middle East and Africa Functional Beverages Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Xanthohumol Market