
 Jellies and Gummies Market | 2026-2036
Jellies and Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Jellies and Gummies Market Intelligence
The US Food and Drug Administration's (FDA) developing stance on cannabidiol (CBD) in food products is recalibrating the cost of entry and compliance for manufacturers. Established players like Haribo GmbH & Co. KG leverage immense brand recognition and global distribution to maintain market share. In contrast, Mondelez International utilizes its extensive retail partnerships to introduce new gummy variations. Albanese Confectionery Group Inc. differentiates through its focus on premium ingredients and proprietary manufacturing techniques, appealing to a more discerning consumer base.
Jellies and gummies are hydrocolloid-based confections, primarily using gelatin, pectin, or modified starch to create their characteristic chewy texture through a controlled cooking and depositing process. These products serve as popular sweets and are increasingly used as a delivery system for vitamins, minerals, and active ingredients. The CBD Gummies product segment, while facing regulatory ambiguity in markets like the United States, commands significant price premiums. Demand from adult consumers is the primary growth engine, eclipsing the traditionally dominant children's segment as functional products gain traction.
Market access is governed by a complex web of food safety and labeling standards, enforced by bodies like the US FDA, the European Food Safety Authority (EFSA), and China's State Administration for Market Regulation (SAMR). These regulations dictate permissible ingredients, health claim substantiation, and packaging information, directly influencing product development cycles. Producers must strategically decide whether to compete on volume in the traditional confectionery space or invest in the formulation and compliance capabilities required for the higher-margin functional and nutraceutical segments.
Market Dynamics
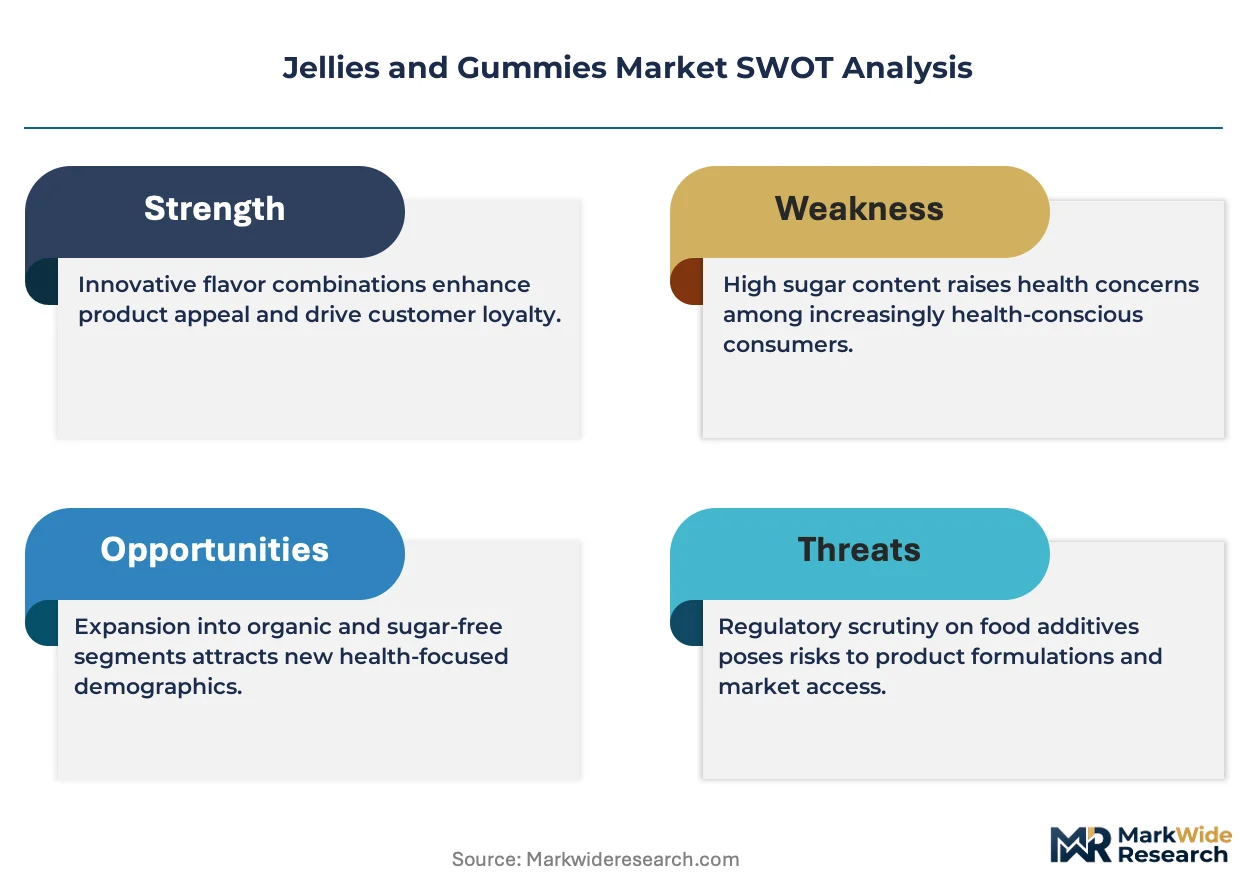
The market's core tension lies between the high-volume, low-margin traditional confectionery segment and the burgeoning, high-compliance functional category. This divergence influences everything from ingredient sourcing to distribution channel strategy and regulatory engagement.
Growth Catalysts
- Adult-Centric Formulations:The pivot in demand from children to adults seeking wellness benefits creates a powerful catalyst, driving development of gummies infused with vitamins, minerals, and nutraceuticals like elderberry or turmeric.
- Pectin and Starch Innovation:Advances in plant-based hydrocolloids, particularly pectin, enable superior texture and flavor release in vegan and clean-label products, expanding the consumer base beyond traditional gelatin users.
- Regulatory Clarity for Additives:The approval of new natural colorants and sweeteners by bodies like the US FDA and EFSA provides manufacturers with a broader, safer palette for creating appealing, health-conscious products.
Market Restraints
- Ingredient Price Volatility:The supply of key inputs like gelatin, pectin, and specialty sugars is subject to agricultural commodity cycles and climate events, creating unpredictable cost structures for manufacturers.
- Regulatory Ambiguity:Unclear legal frameworks for ingredients like cannabidiol (CBD) by the US FDA create significant market entry barriers and investment risk for producers in the functional segment.
- Functional Food Substitution:Consumers can obtain vitamins and supplements from a growing array of alternative formats, including fortified beverages, powders, and bars, which compete directly with nutraceutical gummies.
Strategic Opportunities
- Nutraceutical Category Expansion:There is significant white space for gummies targeting specific wellness outcomes beyond general immunity, such as cognitive enhancement (nootropics), sleep support (melatonin), and skin health (collagen).
- Direct-to-Consumer Channels:Subscription-based models allow brands to build direct relationships with consumers, offering personalized gummy formulations and bypassing traditional retail gatekeepers, especially in North America.
- Geographic Market Entry:Markets in Latin America and Southeast Asia present opportunities for growth, as rising disposable incomes and wellness trends create new demand for functional confectionery products.
Industry Challenges
- Health Claim Substantiation:Meeting the rigorous evidence standards for health claims set by regulators like the European Food Safety Authority (EFSA) requires costly and time-consuming clinical research.
- Complex Production Scaling:Ensuring precise, consistent dosing of active ingredients in every gummy is a significant manufacturing challenge, particularly when scaling production for mass-market distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jellies and Gummies Market |
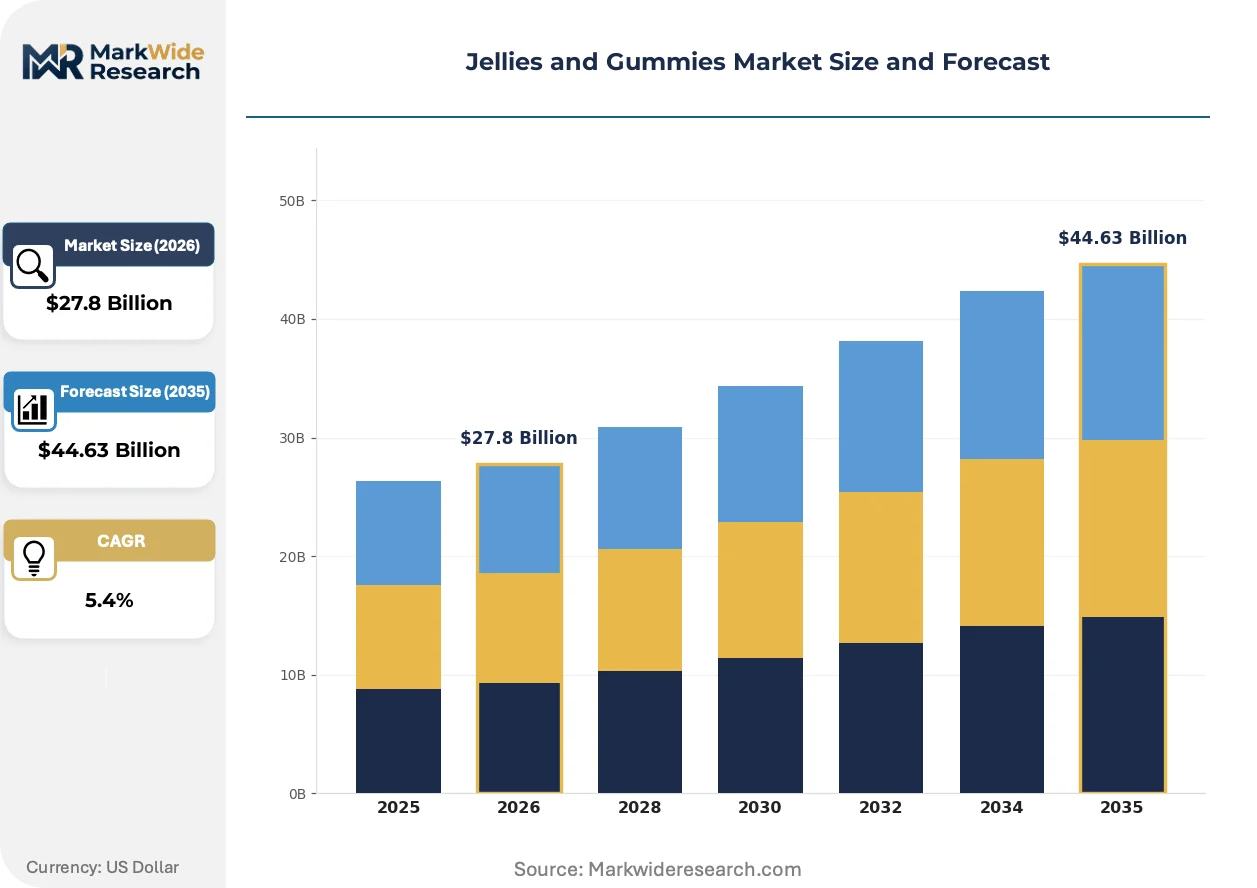
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $44.63 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Jellies, Gummy Bears, Sour Gummies, CBD Gummies End User: Children, Adults, Seniors, Athletes Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Health Food Stores Flavor Profile: Berry, Citrus, Tropical, Mixed Fruit |
| Companies Covered | Ferrero Group, Albanese Confectionery Group Inc., Haribo GmbH & Co. KG, Arcor Group, Lindt & Sprüngli, Mondelez International, Nestlé SA, Shenzhen Amos Sweets & Foods Co. Ltd., Mars Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jellies and Gummies Market Strategic Shifts & Innovations
The convergence of confectionery enjoyment and health management defines market evolution. This blend fosters innovation in ingredient science, pushing products beyond simple sweets into sophisticated delivery systems for active compounds.
Plant-based gelling agents, particularly pectin derived from fruit, provide a vegan alternative to traditional animal-derived gelatin. Consumers focused on clean-label and ethical sourcing are driving rapid adoption of these ingredients. Consequently, pectin-based formulation is overtaking gelatin as the standard for new premium and functional gummy products, especially in North American and European markets.
China's State Administration for Market Regulation (SAMR) has intensified scrutiny over health food registrations and functional claims. This regulatory tightening requires manufacturers to provide robust scientific dossiers, lengthening product launch timelines and increasing compliance costs within the Chinese market. The nutraceutical gummy segment is most impacted, forcing a strategic recalculation of market entry investments.
A behavioral shift from impulse buys at checkout counters to subscription-based online purchasing is reconfiguring distribution. This disintermediates traditional retailers and empowers direct-to-consumer (DTC) brands that offer personalized vitamin and supplement gummy packs. This trend is most advanced among wellness-conscious consumers in the United States and the United Kingdom.
Jellies and Gummies Market Segmentation
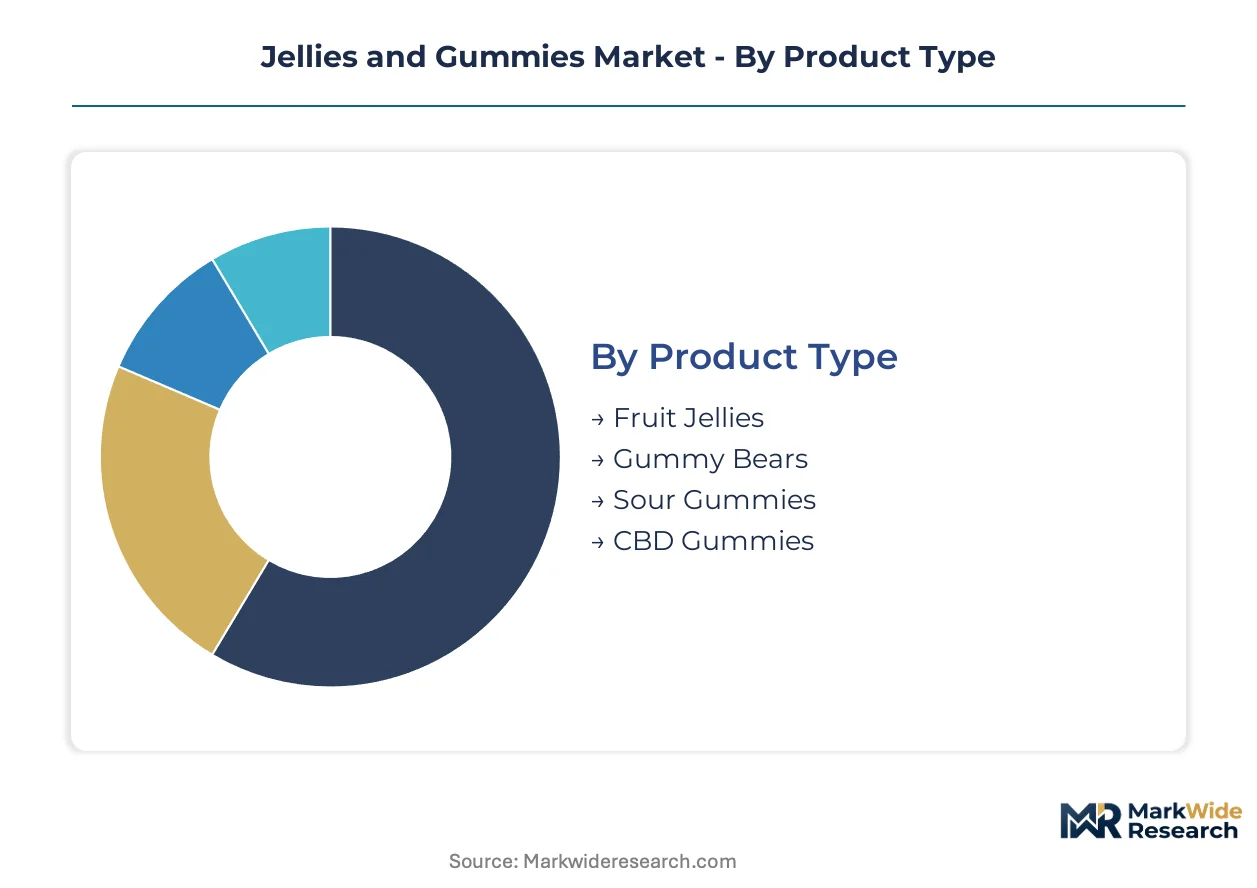
The jellies and gummies market segmentation highlights diverse product offerings and consumer preferences driving market expansion. Understanding these categories allows manufacturers to tailor formulations, distribution, and marketing efforts effectively across consumer groups.
Product Type:
Confectionery ingredients and processing techniques continually upgrade product types, replacing older formulations with advanced options. This innovation drives distinct consumer preferences.
- Gummy Bears:Iconic and globally recognized, these gelatin-based candies offer diverse fruit flavors and a chewy consistency. High volume sales in North America and Germany appeal to both children and adults.
- CBD Gummies:These functional confections incorporate cannabidiol (CBD) as an active ingredient, targeting wellness benefits. Regulatory ambiguity in the United States creates market entry barriers despite significant price premiums.
- Fruit Jellies:These confections use pectin or gelatin, infused with fruit extracts. Traditional confectionery markets in Europe show consistent demand.
- Sour Gummies:These candies feature an acidic coating, providing a sharp taste. Younger consumers in the United States prefer these adventurous profiles.
Gummy Bears sits at the top of the volume ranking, with CBD Gummies climbing the fastest.
End User:
Understanding distinct customer types is crucial for tailoring product formulations and marketing. Each demographic segment exhibits unique preferences and purchasing motivations.
- Children:This segment primarily consumes traditional, sugar-based gummies as recreational sweets, influenced by colorful packaging. Demand remains strong in established markets like the United States and Germany.
- Adults:This demographic increasingly seeks functional gummies infused with vitamins, minerals, or nutraceuticals, moving beyond traditional confectionery. North American and European markets show significant growth.
- Seniors:This group seeks gummies for ease of consumption, often fortified with joint support. Demand is rising in aging populations like Japan.
- Athletes:Gummies with electrolytes, protein, or energy compounds appeal to athletes for convenient nutrition. Sports nutrition brands expand offerings in the United Kingdom.
Adult consumers represent the primary growth engine for functional gummies, while children's consumption maintains consistent market volume.
Distribution Channel:
The configuration of distribution channels directly impacts market reach and consumer accessibility. Channels cater to distinct purchasing behaviors, influencing market penetration.
- Supermarkets:These large-format retail outlets serve as the primary channel for high-volume, traditional confectionery gummies due to extensive reach and competitive pricing. Consumers in the United States and Germany frequently purchase.
- Online Retailers:E-commerce platforms offer unparalleled convenience and vast selection, crucial for niche and functional gummy products. Direct-to-consumer sales in North America and the United Kingdom show significant expansion.
- Specialty Stores:These outlets, including convenience stores, focus on impulse buys and unique confectionery items. European urban centers see consistent sales of artisanal gummies.
- Health Food Stores:These retailers specialize in products for health-conscious consumers, ideal for vitamin-infused and nutraceutical gummies. Demand is robust in Australia and Canada.
Online retailers enable greater direct consumer engagement, while supermarkets maintain dominance for mass-market confectionery volumes.
Flavor Profile:
The application of specific flavor profiles significantly influences consumer appeal and product differentiation. Flavor innovation helps capture new market segments and reinforce brand identity.
- Berry:This broad category includes popular flavors like strawberry and raspberry, often perceived as natural and healthy, making them ideal for functional gummies. Consumers in the United States and Germany show a strong preference.
- Citrus:Flavors such as orange, lemon, and lime offer a refreshing and sometimes tart experience, widely used in traditional and vitamin-fortified gummies. This profile maintains consistent popularity across European and North American markets.
- Tropical:Exotic flavors like mango, pineapple, and passionfruit offer a unique taste, appealing to consumers seeking novelty. Younger demographics in Asia-Pacific show growing interest.
- Mixed Fruit:This classic blend combines several fruit flavors, providing a universally appealing taste profile. It remains a staple in traditional gummy confectionery globally for children.
Mixed Fruit flavors consistently cater to broad consumer preference, while Berry flavors are increasingly favored in the functional segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A skilled confectionery workforce and strong consumer demand anchor the global jellies and gummies market. Functional product innovation drives growth across diverse regions. Regulatory frameworks significantly influence product development and market access.
United States
Adult consumers in the United States increasingly demand functional gummies for wellness benefits, including vitamin and nutraceutical infusions. The US FDA's evolving stance on novel ingredients like CBD impacts market entry and compliance for manufacturers. New York City and Los Angeles serve as hubs for direct-to-consumer brands offering personalized vitamin and supplement gummies.
Germany
Germany maintains high volume sales for traditional gummy bears, appealing to both children and adults with established brand loyalty. The European Food Safety Authority (EFSA) rigorously evaluates health claims, directly influencing product formulation and marketing. The Rhine-Ruhr region remains a production center for established confectionery manufacturers and ingredient suppliers.
China
China experiences growing demand for premium and functional gummy products, particularly from younger demographics seeking health benefits. The State Administration for Market Regulation (SAMR) intensifies scrutiny over health food registrations, lengthening product launch timelines. Shanghai and Guangzhou are key distribution points for imported and domestic confectionery brands.
Japan
Seniors in Japan increasingly seek gummies for ease of consumption, often fortified with joint support or cognitive enhancement compounds. The country's national pharmaceutical regulator oversees the approval of functional food ingredients and health claims. Tokyo serves as a significant market for nutraceutical gummies and innovative confectionery products.
Brazil
Rising disposable incomes in Brazil create new demand for functional confectionery products from wellness-conscious consumers. ANVISA, the Brazilian health surveillance agency, regulates food additives and labeling standards for imported and domestic goods. São Paulo is a major hub for confectionery production and distribution across Latin America.
Jellies and Gummies Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share across the jellies and gummies sector. The market exhibits a tiered structure, with large-scale producers alongside agile niche players. Strategic archetypes include mass-market confectionery giants, functional health innovators, and premium ingredient specialists. Companies frequently engage in portfolio diversification and geographic expansion to solidify their positions.
At the scale-driven end, Haribo GmbH & Co. KG exemplifies a mass-market confectionery giant leveraging immense brand recognition and global distribution networks. Mondelez International, a global food and beverage company, occupies a position through extensive retail partnerships for introducing new gummy variations. Albanese Confectionery Group Inc., a US-based confectionery producer, represents a premium ingredient specialist, differentiating its offerings through proprietary manufacturing techniques and a focus on discerning consumer bases. These players collectively shape the competitive dynamics across traditional and functional segments.
| Leading Market Players |
|---|
| Ferrero Group |
| Albanese Confectionery Group Inc. |
| Haribo GmbH & Co. KG |
| Arcor Group |
| Lindt & Sprüngli |
| Mondelez International |
| Nestlé SA |
| Shenzhen Amos Sweets & Foods Co. Ltd. |
| Mars Inc |
| Others |
Cost & Logistics Intelligence
Clean-label initiatives and ethical sourcing standards gate qualified supply and premium-tier pricing access for jellies and gummies. This market dynamic influences ingredient selection and manufacturing processes, especially for functional products.
Pricing Analysis
Bundled ingredient supply contracts versus unbundled spot market purchases define pricing structures across the jellies and gummies market. Pricing stratifies across premium, standard, and economy tiers, with quality grade and certification level (e.g., organic, vegan) driving significant differentiation. Price softness affects traditional confectionery due to intense competition and private label expansion. Adult consumers seeking functional benefits exhibit lower price sensitivity compared to the highly price-sensitive children's segment.
Supply Chain Analysis
Gelatin supply draws from major producers in Europe and Asia, while pectin sourcing centers on Europe and China. Key raw material dependencies include specialty sugars, fruit extracts, and active nutraceutical ingredients like vitamins or CBD. Ingredient price volatility presents a structural supply chain risk for manufacturers. Mass-market distribution runs through supermarkets, while functional and niche gummy products increasingly rely on online retailers and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The jellies and gummies market presents a geographic-arbitrage opportunity, driven by varying regulatory clarity for novel ingredients like CBD between the United States and European markets.
For Market Incumbents: Hedge against market saturation in traditional segments by aggressively diversifying into functional gummy formulations. Invest in advanced R&D for plant-based hydrocolloids to meet evolving consumer preferences and ethical sourcing demands. Strengthen existing distribution channels, particularly in supermarkets, to maintain volume share against emerging brands. Navigate complex regulatory landscapes, such as EFSA health claim substantiation, to build consumer trust.
For New Entrants and Emerging Players: Advanced ingredient science provides a technology-first wedge into the high-margin functional gummy segment. Target specific wellness outcomes, such as cognitive enhancement or sleep support, which remain underpenetrated. Focus on adult consumers in North America and Europe, leveraging direct-to-consumer subscription models for personalized product offerings. Differentiate through proprietary formulations and transparent ingredient sourcing.
For Investors and Strategic Acquirers: Roll-up economics work for functional gummy brands because market fragmentation creates opportunities for consolidation. Target niche brands with strong intellectual property in active ingredient delivery or a loyal direct-to-consumer customer base. Monitor regulatory developments regarding novel ingredients, particularly CBD, as increased clarity could signal significant market expansion. Long-term viability rests on sustained consumer interest in health and wellness over the next 5-10 years.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch new functional gummy line | Expands product portfolio into higher-margin wellness segments. |
| Invest in plant-based hydrocolloid R&D | Addresses growing consumer demand for vegan and clean-label products. |
| Strengthen direct-to-consumer channels | Builds direct customer relationships and offers personalized product options. |
| Pursue regulatory approval for novel ingredients | Unlocks new product categories and market access for innovative formulations. |
| Form strategic partnerships with nutraceutical suppliers | Secures reliable sourcing for active compounds and specialized ingredients. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, establishing a comprehensive understanding of the jellies and gummies market. This approach combined in-depth discussions with R&D directors, procurement leads, brand managers, and regulatory affairs specialists. Secondary validation drew from public regulatory filings by the US FDA, EFSA reports, SAMR health food registrations, and industry association publications, ensuring robust data triangulation.
The segment-weighting approach informed the analytical framework across the projection horizon, modeling market dynamics across product type, end-user, distribution channel, and flavor profile. Compound annual growth rates were derived from historical trends and future demand projections, integrating insights from consumer wellness trends and anticipated regulatory shifts for functional ingredients. This multi-dimensional analysis provides a granular view of market evolution.
The model holds under current consumer preference for functional foods and prevailing regulatory environments; deviation in global economic stability or significant shifts in agricultural commodity prices would shift forecasts. Forecasts reflect documented assumptions regarding market drivers and restraints. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
India Chocolate Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Milk Chocolate Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Low-Fat Candy Market
Confectionery
Gummy Candy Market
Confectionery
UK Compound Chocolate Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
South America Compound Chocolate Market
Confectionery
Low Calorie Nutella Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Buttercream Frosting Market
Confectionery
Premium Chocolate Market