
 UK Chocolate Market | 2026-2036
UK Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
UK Chocolate Market Insights
Subscription-based chocolate delivery and membership models is pivoting how UK brands monetize recurring relationships beyond single transactions. Hotel Chocolat Group Plc leverages its Velvetiser ecosystem and in-store tasting clubs to sustain high-margin direct engagement. Mars Incorporated anchors mass-market penetration through dominant supermarket shelf presence and seasonal promotional cycles. Ferrero International SA differentiates via premium gifting formats that occupy distinct price tiers during holiday windows.
Chocolate comprises roasted and ground cacao seeds combined with sugar, cocoa butter, and emulsifiers, typically containing 10-70% cocoa solids depending on classification, with conching and tempering processes determining final texture and shelf stability. Its primary commercial purpose spans indulgent confectionery, premium gifting, and functional food applications where cocoa flavonoid content supports health-positioned product lines. Milk chocolate retains volume leadership across UK supermarket aisles, though dark chocolate segments with elevated cocoa percentages capture expanding margin pools as consumers trade up for provenance credentials. Online shoppers represent the fastest-growing customer type, with specialty shops and direct distribution channels capturing disproportionate value from gift set packaging configurations.
The Food Standards Agency enforces compositional standards and allergen labelling that constrain formulation flexibility and shape packaging information requirements. DEFRA's extended producer responsibility regulations and Plastic Packaging Tax directly increase cost burdens for manufacturers reliant on non-recycled materials. FSSAI-aligned import checks post-EU transition add compliance layers for cacao sourcing from non-UK origins. Stakeholders must monitor how evolving eco-modulation fees and deposit return scheme implementations reshape cost structures and channel economics.
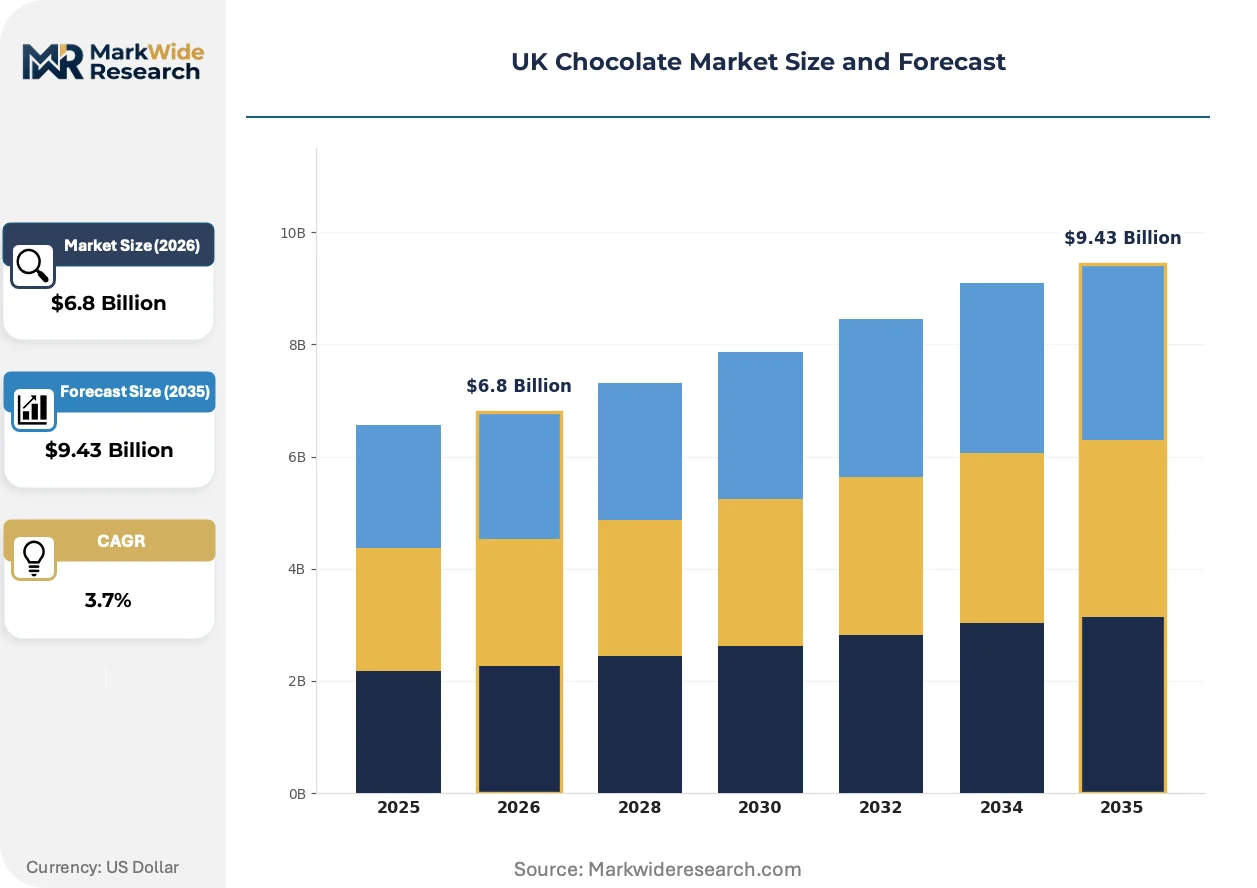
Market Dynamics
Extended producer responsibility frameworks and the Plastic Packaging Tax are compressing margins for manufacturers while accelerating investment in closed-loop material recovery systems across UK production facilities.
Growth Catalysts
- DEFRA Extended Producer Responsibility:Eco-modulation fees incentivize lightweight packaging redesign and recycled content integration, rewarding early movers with lower compliance costs.
- Velvetiser-style home preparation systems:Premium appliance ecosystems lock consumers into proprietary consumable refills, generating recurring revenue streams beyond conventional retail.
- South East England consumption clusters:Affluent urban demographics concentrated in London and commuter belts sustain disproportionate demand for artisanal and provenance-positioned products.
Market Restraints
- Cacao price volatility:West African supply concentration exposes UK manufacturers to weather-driven crop failures and currency fluctuations in Ghana and Ivory Coast.
- Plastic Packaging Tax friction:The GBP 200 per tonne levy on non-recycled plastic directly inflates flexible film costs for seasonal gift packaging formats.
- Substitution by plant-based confections:Oat and nut-based alternatives capture health-conscious trial among flexitarian consumers reducing dairy intake.
Strategic Opportunities
- Deposit Return Scheme preparation:Early infrastructure investment in reverse logistics positions brands for competitive advantage when DEFRA mandates activate.
- Functional cocoa flavonoid positioning:Health claims supported by EFSA-aligned substantiation open pharmacy and wellness channel expansion.
- Direct-to-consumer subscription layering:Tasting clubs and curated delivery boxes penetrate underexploited regional markets outside London metropolitan concentration.
Industry Challenges
- Confectionery technologist scarcity:Specialized expertise in tempering, conching, and shelf-life extension commands premium compensation, constraining R&D throughput.
- Legacy ERP integration with traceability platforms:Batch-level cacao provenance tracking requires costly middleware development to connect farm-origin data with manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Chocolate Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Customer Type: Retail Consumers, Food Service, Wholesalers, Online Shoppers Distribution Channel: Supermarkets, Convenience Stores, Specialty Shops, Online Retailers Packaging Type: Boxes, Pouches, Bars, Gift Sets |
| Companies Covered | Chocoladefabriken Lindt & Sprüngli AG, Hotel Chocolat Group Plc, Mars Incorporated, Charbonnel et Walker, Barry Callebaut AG, Ferrero International SA, Mondelēz International Inc., Artisan du Chocolat Ltd, Nestlé SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Chocolate Market Trends and Innovations
Digital traceability infrastructure and reformulated clean-label recipes are redrawing competitive boundaries between heritage brands and agile challengers.
Blockchain-enabled farm-to-bar verification is decentralizing provenance authentication, allowing smaller UK bean-to-bar producers to compete with multinational heritage claims. Specialty retailers and direct channels adopt these systems fastest. This transparency architecture is decentralizing trust formation away from established brand equity toward immutable supply chain records.
DEFRA's evolving packaging waste regulations are mandating recycled content minimums and modulated fee structures based on recyclability performance. Manufacturers reformulating flexible laminates into mono-material alternatives face 18-24 month validation cycles. Gift set and seasonal formats bear disproportionate compliance burden due to complex multi-component construction.
Subscription-based replenishment models are displacing pantry-stocking behaviors among urban professional households. Curated monthly deliveries from direct channels capture trial budgets previously allocated to supermarket impulse purchases. This channel rotation concentrates in London and South East corridors where delivery density optimizes logistics economics.
UK Chocolate Market Segmentation
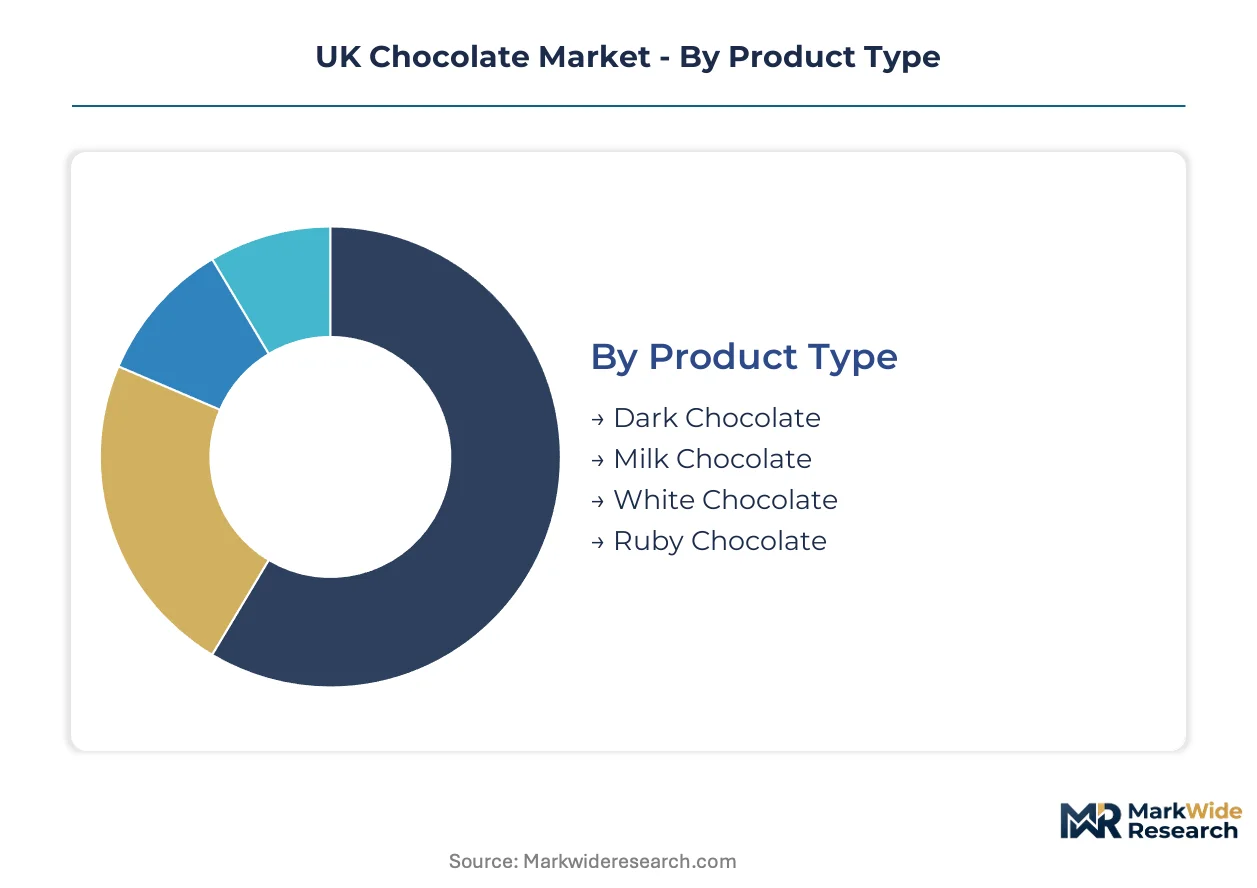
Segmentation reveals where capital deployment and margin capture diverge across the UK chocolate landscape. Manufacturers must align production infrastructure with the specific technical and channel requirements of each slice.
Product Type:
Capital intensity varies sharply with cocoa solids percentage and processing complexity.
- Milk Chocolate:Standard 10-50% cocoa solids combined with milk powder demand continuous conching equipment and tempering lines. Volume concentrates in supermarket aisles where seasonal promotional cycles drive manufacturing scale requirements.
- Dark Chocolate:Elevated 50-70% cocoa solids require extended conching durations and precise temperature control during tempering. London and South East specialty shops command premium positioning for provenance-credentials and bean-origin claims.
- White Chocolate:Cocoa butter base without cocoa solids necessitates specialized fat crystallization control and shorter shelf-life management.
- Ruby Chocolate:Proprietary ruby cocoa bean processing requires licensed technology access and dedicated production lines.
Milk chocolate absorbs the bulk of installed capacity; dark chocolate is expanding most quickly.
Customer Type:
Margin structure and order predictability shift dramatically across buyer categories.
- Retail Consumers:Impulse-driven purchases through supermarkets and convenience stores generate high-volume, low-margin throughput with heavy promotional dependence.
- Online Shoppers:Subscription models and curated delivery boxes capture recurring revenue with superior customer lifetime value metrics in London metropolitan corridors.
- Food Service:Hotels, restaurants, and cafés require bulk formats and consistent supply reliability with negotiated contract terms.
- Wholesalers:Intermediate distribution layers aggregate fragmented demand from independent retailers and regional accounts.
Retail consumers anchor volume throughput; online shoppers deliver the steepest expansion trajectory.
Distribution Channel:
Channel selection determines packaging format, margin retention, and regulatory exposure.
- Supermarkets:Dominant shelf presence requires slotting fee investments and promotional fund participation. Mars Incorporated anchors mass-market penetration here through seasonal cycles.
- Specialty Shops:Direct engagement and tasting experiences support premium pricing and provenance storytelling in affluent urban clusters.
- Convenience Stores:Grab-and-go formats favor single-serve bars and immediate consumption positioning.
- Online Retailers:Direct-to-consumer logistics enable gift set configurations and subscription layering with superior margin capture.
Supermarkets command the largest revenue share; specialty shops and online retailers are gaining share fastest.
Packaging Type:
DEFRA compliance burden and material cost exposure vary substantially across format complexity.
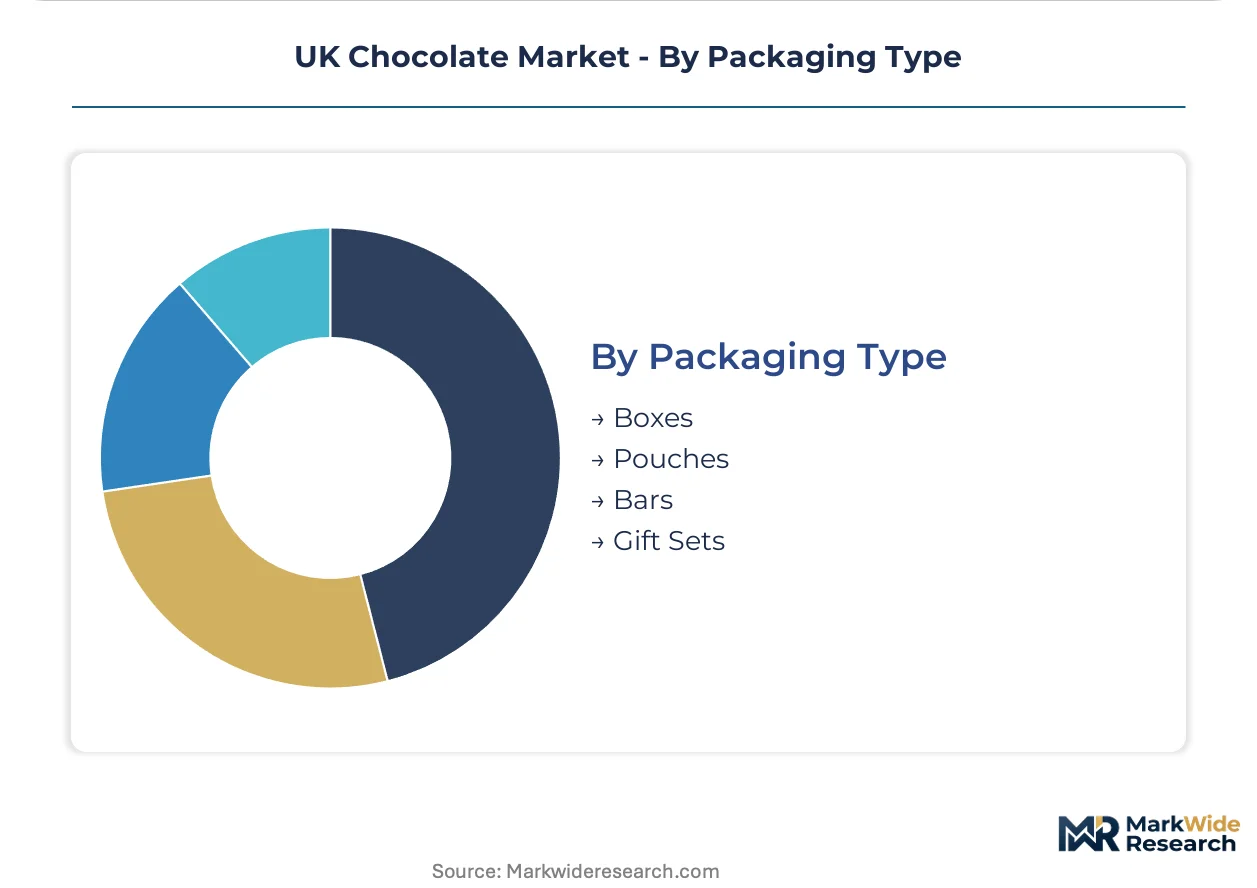
- Gift Sets:Multi-component construction with rigid boxes, inserts, and decorative elements faces disproportionate Plastic Packaging Tax exposure and extended producer responsibility fees.
- Bars:Standard flexible film or paper wrapping offers simplest compliance pathway with mono-material redesign options.
- Boxes:Rigid paperboard formats align with established recycling streams and lower eco-modulation penalties.
- Pouches:Flexible laminate construction requires significant reformulation investment to meet recycled content minimums.
Bars dominate production volume; gift sets command the highest per-unit value and regulatory scrutiny.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London and the South East corridor concentrate over half of UK chocolate consumption value, with affluent urban households driving demand for artisanal and provenance-positioned products through specialty shops and direct-to-consumer channels.
London and South East
Velvetiser-style home preparation systems and subscription tasting clubs capture recurring revenue from professional households in Greater London and commuter belt counties. DEFRA's Plastic Packaging Tax compliance costs hit gift set manufacturers headquartered in Berkshire and Surrey. Heathrow logistics clusters enable rapid direct-to-consumer fulfillment across metropolitan postcodes.
Midlands
Industrial-scale conching and tempering facilities in Birmingham and Leicester supply supermarket private-label programs nationwide. The Food Standards Agency's allergen labelling requirements shape formulation protocols at manufacturing sites across Staffordshire and Derbyshire. Burton-upon-Trent maintains heritage chocolate processing infrastructure serving contract manufacturing accounts.
North England
Bean-to-bar craft producers in Manchester and Leeds exploit lower commercial rents to establish tasting room operations. Extended producer responsibility fees incentivize packaging lightweighting investments at Yorkshire-based facilities. Sheffield's advanced manufacturing heritage supports specialized moulding equipment fabrication for regional chocolatiers.
Scotland
Edinburgh and Glasgow specialty retailers command premium positioning for high-cocoa-percentage dark chocolate formats among affluent urban consumers. Scottish Government circular economy regulations accelerate mono-material packaging transitions at Highland production sites. Aberdeen's food service procurement networks distribute couverture to hospitality accounts across the central belt.
Wales
Artisan producers in Cardiff and Swansea leverage Welsh provenance branding for export positioning into English specialty channels. Natural Resources Wales waste reduction frameworks shape local authority packaging collection requirements. Pembrokeshire tourism corridors sustain seasonal demand for souvenir-format chocolate confectionery.
UK Chocolate Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the UK chocolate landscape. The market structure tiers between multinational heritage brands with dominant supermarket shelf presence and agile craft specialists exploiting direct-to-consumer channels. Three archetypes dominate: mass-market volume players, premium gifting specialists, and bean-to-bar craft operators. Competitive moves concentrate on seasonal promotional cycles and subscription-based customer retention mechanics.
Within the premium gifting tier, Hotel Chocolat Group Plc and Charbonnel et Walker exemplify archetypes leveraging in-store experience and heritage positioning respectively. Mars Incorporated anchors the mass-market vector through supermarket distribution scale. Among Swiss-headquartered conglomerates, Chocoladefabriken Lindt & Sprüngli AG and Barry Callebaut AG occupy positions spanning consumer-facing and business-to-business supply. These entities represent the structural spectrum from vertically integrated cacao processors to brand-led retail operators.
| Leading Market Players |
|---|
| Chocoladefabriken Lindt & Sprüngli AG |
| Hotel Chocolat Group Plc |
| Mars Incorporated |
| Charbonnel et Walker |
| Barry Callebaut AG |
| Ferrero International SA |
| Mondelēz International Inc. |
| Artisan du Chocolat Ltd |
| Nestlé SA |
| Others |
Pricing and Supply Chain Analysis
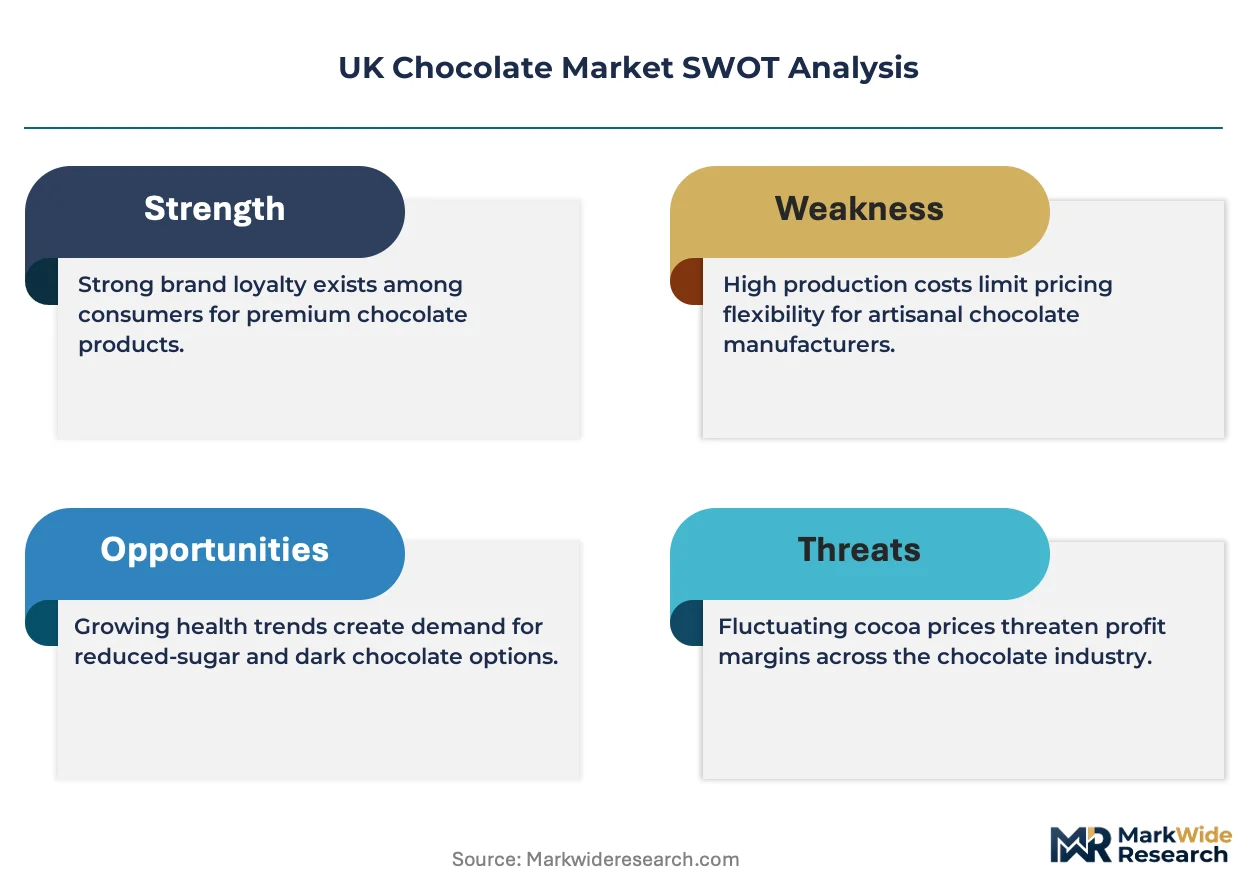
Provenance-credential tiering between bean-to-bar craft and commodity-sourced mass market anchors divergent margin structures across UK chocolate, with DEFRA's Plastic Packaging Tax amplifying cost differentials and reshaping supplier selection toward mono-material compliant vendors.
Pricing Analysis
Margin tightening in gift set formats traces to the GBP 200 per tonne Plastic Packaging Tax levy on non-recycled content, compressing returns on multi-component seasonal packaging. Three-tier pricing structure across premium, standard, and economy levels separates Hotel Chocolat's Velvetiser ecosystem from supermarket private-label bars. Price differentiation hinges on cocoa solids percentage and provenance authentication, with dark chocolate segments commanding 40-60% premiums over milk chocolate equivalents. Retail consumers demonstrate highest price sensitivity, while subscription-based online shoppers accept recurring premiums for curated delivery convenience.
Supply Chain Analysis
Direct-to-consumer channels handle premium buyer demand through Heathrow logistics clusters, while supermarket distribution runs through Midlands manufacturing hubs serving nationwide private-label programs. Cacao sourcing concentrates in Ghana, Ivory Coast, and Ecuador, with UK manufacturers drawing from West African supply pools vulnerable to weather-driven crop failures. Cocoa butter, milk powder, and cane sugar constitute critical input dependencies. Single-source vulnerability in West African supply regions exposes processors to currency fluctuations and port congestion at Tema and Abidjan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DEFRA's Extended Producer Responsibility framework creates a compliance moat favoring early movers with closed-loop material recovery systems, elevating capital requirements for market participation.
For Market Incumbents: Extend proprietary appliance ecosystems like Velvetiser-style home preparation systems to lock consumers into recurring consumable refills. Invest in mono-material packaging redesign ahead of deposit return scheme activation. Channel control through direct-to-consumer subscription layering defends margin position against supermarket promotional cycles. For New Entrants and Emerging Players: The mid-market price-point gap between Hotel Chocolat premium tiers and Mars mass-market positioning offers white-space opportunity. Target bean-to-bar craft positioning in underexploited regional markets outside London metropolitan concentration. Partner with specialty retailers for tasting room presence before scaling direct distribution infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated craft operators given blockchain-enabled provenance authentication attracting ESG-mandated capital. Long-term viability favors acquisition targets with in-house conching capacity and established direct-to-consumer subscription bases. Monitor DEFRA eco-modulation fee schedules as inflection indicator for packaging compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Transition | DEFRA compliance cost reduction enables margin recovery on gift set formats. |
| Direct-to-Consumer Subscription Launch | Curated delivery boxes capture recurring revenue from London professional households. |
| Blockchain Provenance Integration | Farm-to-bar verification decentralizes trust formation from heritage brand equity. |
| Velvetiser-Style Appliance Ecosystem | Proprietary consumable refills generate recurring revenue beyond conventional retail. |
| Regional Tasting Room Expansion | Lower commercial rents in Manchester and Leeds support experiential retail economics. |
Research Methodology
Document review covered trade association filings, DEFRA regulatory consultations, and customs import records, complemented by interviews with chocolate category buyers at major UK supermarkets, supply chain directors at Midlands manufacturing facilities, and sustainability officers at packaging converters. Secondary validation drew from Food Standards Agency compositional standards documentation, Nielsen retail audit data, and extended producer responsibility impact assessments. Bottom-up demand modeling and top-down market sizing triangulated volume estimates.
Segmentation outputs across product type, customer category, distribution channel, and packaging format dimensions informed revenue allocation. Cacao price volatility indices and DEFRA fee schedule projections fed scenario-based CAGR derivation. The analytical framework incorporated cocoa solids percentage tiers, regional consumption clustering, and subscription penetration rates across the analysis window.
Inputs from supermarket procurement teams and specialty retailer operators were available through the study window; gaps in real-time cacao futures positioning data introduce uncertainty bands around commodity cost assumptions. Forecasts reflect documented base-case assumptions regarding regulatory implementation timelines and consumer subscription adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Gummy Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
North America Confectionery Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Confectionery Coating Market
Confectionery
Low-Fat Sweets Market
Confectionery
Premium Chocolate Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Sugar Confectionery Market
Confectionery
Global Compound Chocolate Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
South America Compound Chocolate Market