
 Functional Confectionery Market | 2026-2036
Functional Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Confectionery Market Analysis
China is tilting toward expanded functional confectionery capacity with new manufacturing clusters in Zhejiang and Jiangsu provinces targeting both domestic consumption and export markets. Mars Inc. leverages its global chocolate infrastructure to anchor fortified product lines across Asian markets. Nestlé SA sustains R&D intensity in micronutrient delivery systems through its Swiss research hub. Ferrero Group differentiates via premium positioning of hazelnut-based functional formats in European pharmacies.
Functional confectionery encompasses edible products formulated with bioactive ingredients—vitamins, minerals, proteins, probiotics, or botanical extracts—delivered through candy, chocolate, or chewable matrices with specified nutrient payloads per serving unit. Manufacturers employ cold-extrusion gelling and enrobing processes to preserve heat-sensitive actives like B-vitamins and live cultures during production. Gummy vitamins occupy the largest margin pool due to pediatric acceptance and adult pill fatigue, while protein bars command premium pricing in fitness-oriented channels. Fortified chocolates compete on indulgence-positioned health claims, though sugar-reduction formulation costs compress margins in mass-market tiers. Natural sweeteners and organic ingredient sourcing are reshaping procurement requirements across all product categories.
The FDA regulates health claim substantiation for confectionery-positioned supplements under DSHEA enforcement discretion, while EFSA's Article 13 health claims register constrains permissible marketing language for fortified chocolates in European Union member states. China's SAMR mandates blue-hat registration for functional food products crossing into therapeutic positioning, creating dual-track compliance for multinational portfolios. Stakeholders must monitor evolving probiotic strain-specific approval pathways, as regulatory clarity on live culture stability claims will determine which product formats secure sustained shelf placement versus delisting risk.
Market Dynamics
The FDA's updated dietary supplement labeling rules are tightening permissible health claims on confectionery-positioned products, forcing manufacturers to restructure formulation and marketing strategies around substantiation requirements rather than aspirational positioning.
Growth Catalysts
- Pediatric pill fatigue:Parents in Germany and the United States actively seek chewable vitamin formats for children, displacing traditional tablet supplements in household purchasing patterns.
- EFSA Article 13 framework:Clarified health claim registers in European Union member states enable compliant marketing language for fortified chocolates, reducing regulatory uncertainty for cross-border product launches.
- Protein fortification:Sports nutrition channels in North American retail chains absorb rising volumes of protein-fortified confectionery formats, creating dedicated shelf space previously reserved for conventional supplements.
Market Restraints
- Heat-sensitive active degradation:B-vitamins and live probiotic cultures require cold-extrusion gelling and enrobing processes that elevate capital equipment requirements and constrain production scalability.
- Blue-hat registration burden:China's SAMR mandates therapeutic-grade registration for functional foods crossing into health positioning, creating dual-track compliance costs for multinational portfolios seeking domestic market access.
- Sugar-reduction formulation costs:Natural sweetener substitution in mass-market chocolate tiers compresses margins while organic ingredient sourcing reshapes procurement requirements across all product categories.
Strategic Opportunities
- Pharmacy channel expansion:European pharmacies increasingly stock premium-positioned hazelnut-based functional formats, creating higher-margin placement opportunities distinct from mass retail.
- Zhejiang and Jiangsu manufacturing clusters:New production capacity in these Chinese provinces targets both domestic consumption and export markets, enabling integrated supply chain control for Asia-Pacific distribution.
- Probiotic strain-specific approvals:Regulatory clarity on live culture stability claims will determine which product formats secure sustained shelf placement versus delisting risk, creating first-mover advantages for substantiated strains.
Industry Challenges
- DSHEA enforcement discretion variability:FDA health claim substantiation standards for confectionery-positioned supplements shift based on regional inspector interpretation, creating compliance inconsistency across US distribution territories.
- Micronutrient delivery system R&D intensity:Sustained investment in bioactive preservation technologies strains mid-tier manufacturer R&D budgets relative to diversified food conglomerates with captive research infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Confectionery Market |
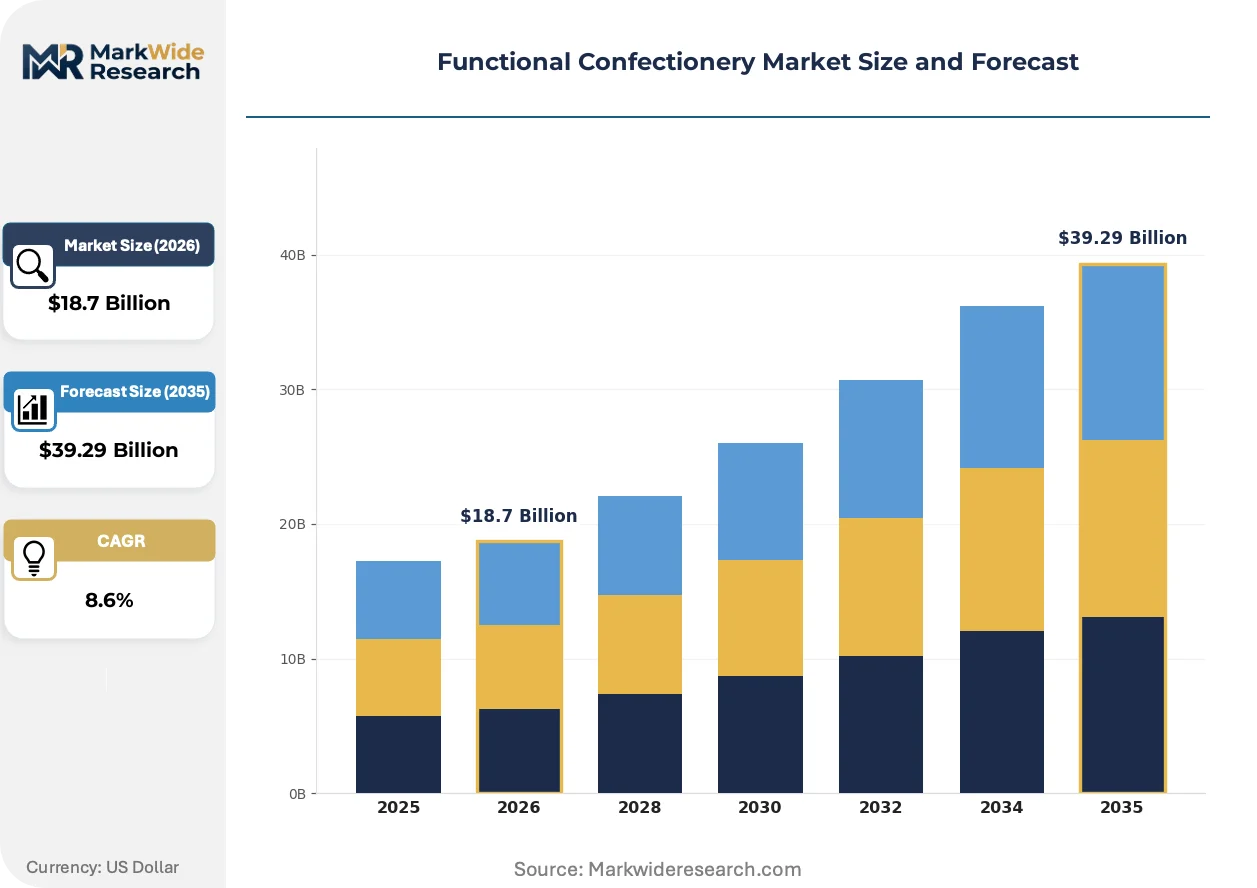
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummy Vitamins, Protein Bars, Sugar-Free Candy, Fortified Chocolates Catering Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Shops Target Audience: Fitness Enthusiasts, Parents, Seniors, Health-Conscious Consumers Ingredient Source: Organic, Non-GMO, Gluten-Free, Natural Sweeteners |
| Companies Covered | The Hershey Company, Lindt & Sprüngli, Mars Inc., Perfetti Van Melle, Haribo GmbH & Co. KG, Mondelez International, Nestlé SA, Meiji Holdings Co. Ltd., Ferrero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Confectionery Market Emerging Trajectories
Formulation science is actively reshaping how bioactive ingredients survive processing environments, with preservation technologies determining which manufacturers can deliver stated nutrient payloads through palatable candy and chocolate matrices.
Cold-extrusion gelling technology is hybridizing conventional confectionery production with pharmaceutical-grade active protection. Pediatric and adult wellness segments adopt these formats at accelerating rates as pill fatigue spreads across demographic cohorts. This convergence is compressing the traditional boundary between indulgence-oriented candy and efficacy-positioned supplements, forcing retailers to reclassify shelf space allocation.
EFSA's Article 13 health claims register constrains permissible marketing language for fortified chocolates in European Union member states. Industrial consequence includes reformulation of product portfolios to align with approved claim databases rather than proprietary health positioning. Premium chocolate segments in Germany and France respond by emphasizing indulgence-adjacent wellness narratives that operate within regulatory guardrails.
Adult pill fatigue is driving channel migration from pharmacy supplement aisles to mainstream confectionery retail placements. Fitness-oriented buyers and time-constrained parents replace traditional vitamin purchasing with grab-and-go functional gummy formats. This behavioral shift concentrates in German private-label markets and North American sports nutrition retail chains, where shelf space reallocation accelerates format experimentation.
Functional Confectionery Market Segmentation
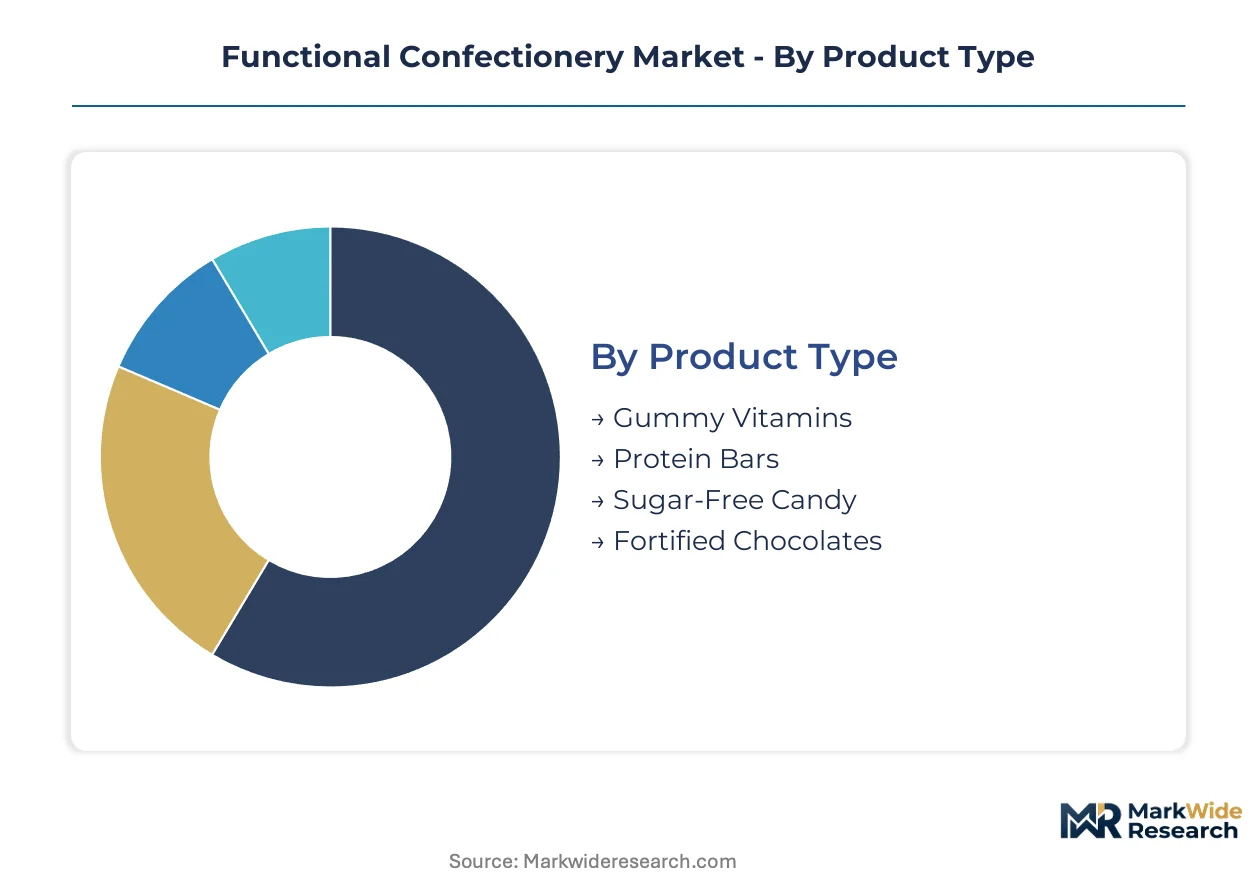
Segmentation in functional confectionery determines manufacturing equipment selection, cold-chain requirements, and regulatory compliance pathways. Each product format carries distinct bioactive preservation challenges that reshape procurement priorities and channel placement strategies.
Product Type:
After-sales service intensity varies dramatically across formats, with probiotic gummies requiring stability monitoring and protein bars demanding freshness guarantees that reshape distributor relationships.
- Gummy Vitamins:Cold-extrusion gelling preserves heat-sensitive B-vitamins and live cultures during production. Demand concentrates in German private-label markets where pediatric pill fatigue displaces traditional tablets.
- Protein Bars:Sports nutrition channels in North American retail chains absorb rising volumes, creating dedicated shelf space previously reserved for conventional supplements.
- Sugar-Free Candy:Natural sweetener substitution elevates formulation costs while organic sourcing reshapes procurement requirements.
- Fortified Chocolates:EFSA Article 13 constraints force reformulation toward approved health claims rather than proprietary positioning.
By volume, gummy vitamins lead. By growth pace, protein bars are expanding most quickly.
Catering Channel:
Cost tier stratification separates premium pharmacy placements from mass-market retail, with each channel demanding distinct margin structures and compliance documentation.
- Supermarkets:Mass-market placement absorbs standard-tier fortified chocolates and sugar-free formats with conventional shelf-life requirements.
- Health Food Stores:Premium positioning captures organic and non-GMO certified lines with higher service intensity for ingredient traceability.
- Online Retail:Direct-to-consumer subscription models concentrate in protein bars and gummy vitamins where repeat purchase patterns dominate.
- Specialty Shops:European pharmacies increasingly stock hazelnut-based functional formats, creating higher-margin placement opportunities.
By volume, supermarkets lead. By margin capture, specialty shops are climbing the fastest.
Target Audience:
Application-specific formulation requirements separate pediatric acceptance drivers from adult fitness positioning, reshaping active ingredient selection and packaging formats.
- Fitness Enthusiasts:Protein fortification commands premium pricing in sports nutrition channels with efficacy-focused nutrient payloads.
- Parents:Pediatric pill fatigue drives chewable vitamin adoption in German and United States households, displacing tablet supplements.
- Seniors:Micronutrient delivery systems target bioavailability concerns with pharmaceutical-grade active protection technologies.
- Health-Conscious Consumers:Sugar-reduction demands compress margins in mass-market tiers while natural sweetener sourcing reshapes procurement.
By volume, parents lead. By growth pace, fitness enthusiasts are gaining share fastest.
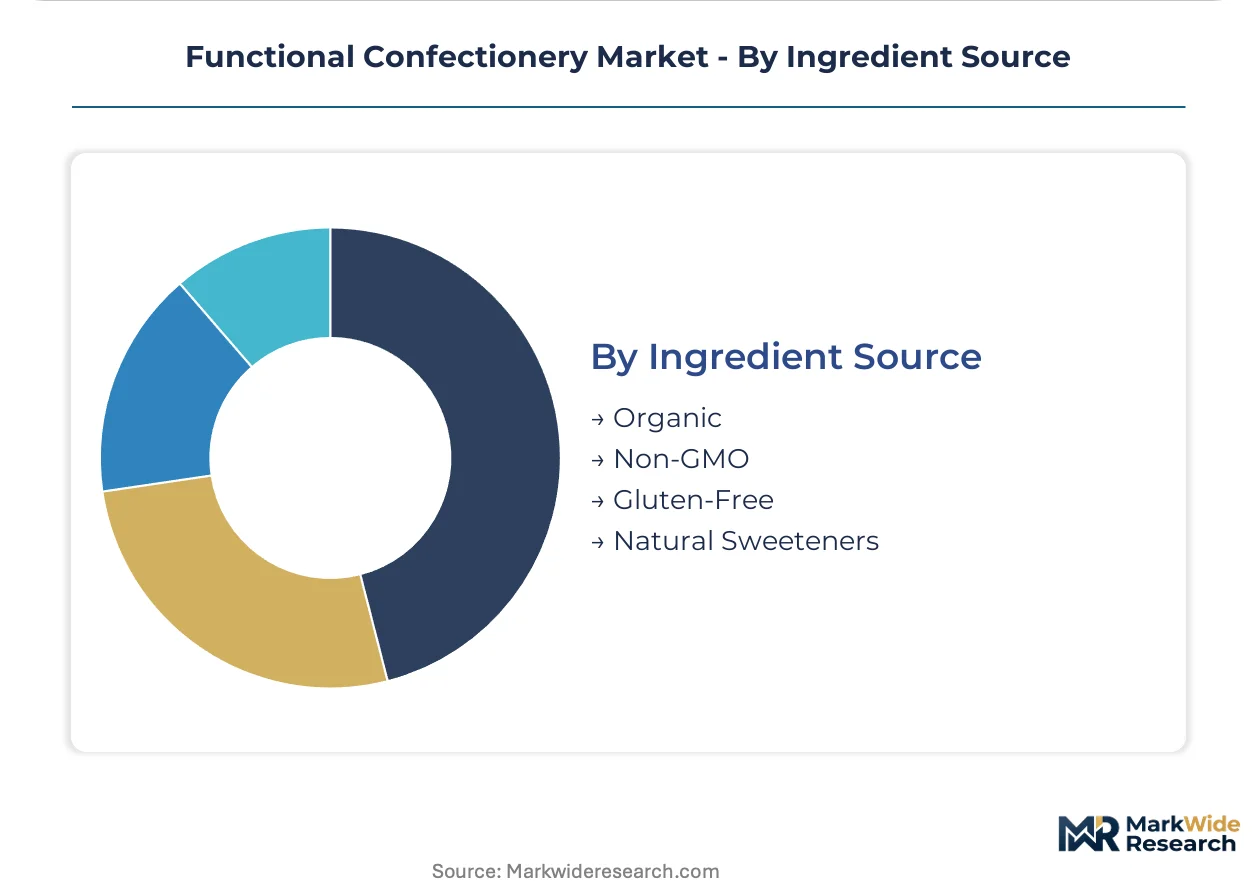
Ingredient Source:
Supply concentration for certified organic inputs and natural sweeteners determines which manufacturers secure sustained production capacity versus reformulation delays.
- Organic:Certification requirements elevate procurement costs and constrain supplier pools, particularly for chocolate and gummy base materials.
- Non-GMO:Labeling standards vary by geography, creating dual-track compliance for multinational portfolios seeking cross-border placement.
- Gluten-Free:Manufacturing line segregation requirements add capital equipment burdens for mid-tier producers.
- Natural Sweeteners:Stevia and monk fruit substitution reshapes formulation science while compressing margins in price-sensitive tiers.
By volume, natural sweeteners lead. By growth pace, organic certification is on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling enforcement in the United States sets the regulatory baseline that shapes health claim substantiation across export-dependent manufacturing networks. Market concentration varies sharply by geography, with distinct regulatory pathways determining which product formats achieve sustained shelf placement.
United States
Pediatric pill fatigue and sports nutrition channel expansion drive format experimentation in gummy vitamins and protein-fortified bars. FDA DSHEA enforcement discretion creates regional compliance inconsistency across inspector jurisdictions. Manufacturing gravity concentrates in Pennsylvania and Illinois chocolate corridors where cold-extrusion capabilities anchor fortified product lines.
Germany
Private-label functional gummy lines displace traditional vitamin tablets in pharmacy and mass retail channels. EFSA Article 13 health claim registers constrain permissible marketing language, forcing reformulation toward approved claim databases. Baden-Württemberg and Bavaria host concentrated R&D infrastructure for micronutrient delivery systems serving EU-wide distribution.
China
Domestic consumption growth and export market targeting accelerate capacity buildout in functional confectionery manufacturing. SAMR blue-hat registration mandates create dual-track compliance costs for therapeutic-grade positioning. Zhejiang and Jiangsu provinces anchor new production clusters integrating supply chain control for Asia-Pacific distribution networks.
Switzerland
Premium hazelnut-based functional formats capture pharmacy channel placement at higher margin tiers than mass-market alternatives. Swissmedic oversight of borderline food-supplement products shapes formulation strategies for cross-border EU launches. The Swiss research corridor sustains concentrated R&D intensity in bioactive preservation technologies and chocolate matrix engineering.
Japan
Functional food specificity traditions support consumer acceptance of efficacy-positioned confectionery formats with substantiated health claims. PMDA and Ministry of Health, Labour and Welfare guidance on Foods with Function Claims creates structured approval pathways distinct from supplement regulation. Kanto and Kansai manufacturing belts concentrate production of probiotic and vitamin-fortified chewing gums for domestic and regional export markets.
Functional Confectionery Market Vendor Landscape
Diversified food conglomerates and specialized confectionery houses split the market between scale-driven portfolio breadth and focused format expertise. Tiered competitive positioning separates premium pharmacy-channel specialists from mass-market private-label suppliers. Three archetypes dominate: global chocolate infrastructure operators leveraging existing manufacturing networks; dedicated gummy and chewable supplement formulators with pharmaceutical-grade active protection capabilities; and private-label contract manufacturers serving retail chain exclusive lines. Competitive dynamics center on cold-extrusion technology access and regulatory submission capacity for strain-specific probiotic approvals.
Within the diversified conglomerate tier, Mars Inc. and Nestlé SA represent global infrastructure operators with integrated research and manufacturing footprints spanning multiple continents. Ferrero Group occupies a premium-positioned archetype focused on hazelnut-based functional formats with pharmacy-channel placement. Among specialized players, Haribo GmbH & Co. KG exemplifies gummy format expertise translated into vitamin delivery applications. Meiji Holdings Co. Ltd. anchors Asia-Pacific functional chocolate development with regional regulatory navigation capabilities.
| Leading Market Players |
|---|
| The Hershey Company |
| Lindt & Sprüngli |
| Mars Inc. |
| Perfetti Van Melle |
| Haribo GmbH & Co. KG |
| Mondelez International |
| Nestlé SA |
| Meiji Holdings Co. Ltd. |
| Ferrero Group |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific freight corridors connecting Zhejiang and Jiangsu manufacturing clusters to North American distribution hubs transmit cost volatility directly into landed pricing for protein-fortified formats, compressing margins for mid-tier suppliers while amplifying differentiation premiums for cold-extrusion-capable producers.
Pricing Analysis
Geographic price spreads between German pharmacy channels and North American mass retail exceed factor-of-two differentials for equivalent probiotic gummy SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and active payload substantiation. Pricing pressure stems from natural sweetener substitution costs in sugar-reduction formulations. Parents purchasing pediatric vitamins show highest price elasticity, while fitness enthusiasts in sports nutrition channels accept premium positioning.
Supply Chain Analysis
Organic cocoa butter and natural sweetener feedstock procurement draws from Côte d'Ivoire, Ghana, and Indonesian palm operations with escalating sustainability certification requirements. Cold-extrusion equipment and pharmaceutical-grade enrobing lines concentrate manufacturing in Germany, Switzerland, and Pennsylvania chocolate corridors. Single-source vulnerability pervades live probiotic culture supply with limited qualified strain suppliers. Distribution runs through refrigerated logistics partnerships for stability-guaranteed formats, direct-to-consumer subscription models for repeat-purchase gummy vitamins, and pharmacy wholesale networks for premium hazelnut-based positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stability monitoring and freshness guarantee services for probiotic gummies and protein bars are expanding faster than base product sales, creating recurring revenue attachment opportunities that reshape manufacturer-distributor relationships.
For Market Incumbents: Entrench cold-extrusion technology access through captive equipment partnerships or in-house production of enrobing lines, defending against specialized gummy formulators with pharmaceutical-grade capabilities. Consolidate strain-specific probiotic approval submissions to preempt regulatory delisting risks from FDA DSHEA enforcement variability. For New Entrants and Emerging Players: White-space concentration in Chinese domestic private-label functional gummy lines represents the most penetrable entry point, given SAMR blue-hat registration complexity deterring multinational expansion. Target Zhejiang and Jiangsu manufacturing cluster partnerships for integrated Asia-Pacific supply chain control. Pursue direct-to-consumer subscription models with stability-guaranteed logistics as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized gummy and chewable supplement formulators with pharmaceutical-grade active protection capabilities over diversified chocolate infrastructure operators. Long-term viability hinges on regulatory submission capacity for strain-specific probiotic approvals and cold-extrusion technology access. Watch EFSA Article 13 health claim register expansions and FDA probiotic stability guidance clarifications as inflection indicators for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold-Extrusion Equipment | Captive production of enrobing lines secures pharmaceutical-grade active protection capabilities against equipment scarcity. |
| Strain-Specific Probiotic Regulatory Submission | First-mover substantiation through FDA or EFSA pathways preempts competitor shelf placement in stability-guaranteed formats. |
| Pharmacy Channel Expansion | Premium positioning in European pharmacies captures higher-margin placement distinct from mass retail price compression. |
| Direct-to-Consumer Subscription Launch | Repeat purchase patterns in gummy vitamins and protein bars build predictable revenue streams with lower customer acquisition costs. |
| Zhejiang-Jiangsu Manufacturing Cluster Partnership | Integrated supply chain control for Asia-Pacific distribution reduces freight cost volatility and SAMR compliance coordination. |
Methodological Framework
Operator-level perspectives from brand managers, category buyers at North American and German retail chains, cold-extrusion equipment specialists, and regulatory affairs leads anchored the qualitative base. Secondary validation drew from FDA DSHEA enforcement discretion documentation, EFSA Article 13 health claim registers, SAMR blue-hat registration filings, and Nielsen retail audit data for sports nutrition and pharmacy channels. Bottom-up SKU-level volume modeling and top-down category expenditure analysis were triangulated against manufacturer capacity disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product format, channel placement, target audience application, and ingredient certification tier. CAGRs were derived from trend-line extrapolation of pediatric pill fatigue adoption curves, protein fortification penetration in fitness channels, and pharmacy-format migration patterns. Forecast inputs incorporated cold-extrusion capacity buildout timelines and probiotic strain approval pathway clarity assumptions.
Practitioners should monitor SAMR registration backlog changes, EFSA health claim register expansion decisions, and live culture stability testing standard developments for early signals of forecast revision necessity. Cross-checking against customs records for functional confectionery trade flows and retail audit data for shelf space reallocation trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Non-Chocolate Candy Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Sugar Confectionery Market
Confectionery
Gummy Candy Market
Confectionery
Gummy Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
Saudi Arabia Chocolate Market
Confectionery
Low Calorie Nutella Market
Confectionery
Europe Confectionery Market
Confectionery
Europe Chocolate Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Jellies and Gummies Market
Confectionery
Low-Fat Candy Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Japan Chocolate Market