
 Chocolate Confectionery Market | 2026-2036
Chocolate Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Confectionery Market Intelligence
A shift from single-source to multi-source cocoa procurement is rebalancing supply chain risk for major manufacturers. This strategy helps mitigate climate-related volatility in key growing regions. Mondelēz International leverages its scale to secure diverse cocoa contracts. Ferrero Group sustains its premium positioning through control over hazelnut and cocoa supply chains, while The Hershey Company competes on brand recognition and extensive distribution in North America.
Chocolate confectionery refers to food products derived from cocoa beans, processed into cocoa solids and cocoa butter, and often mixed with sugar and milk. The final texture and flavor profile are refined through processes like conching, which reduces bitterness. While milk chocolate remains a mature, high-volume product type, dark chocolate with high cocoa content represents the fastest-growing segment due to perceived health benefits. Personal consumption drives the majority of sales, but the corporate gifting application provides significant margin opportunities.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate stringent standards for ingredient labeling and allergen declarations. New EU regulations on deforestation-free supply chains are adding significant compliance costs and traceability requirements for cocoa importers. Navigating the trade-offs between ethical sourcing, price sensitivity, and premium product formulation remains the central strategic challenge for all manufacturers.
Market Dynamics
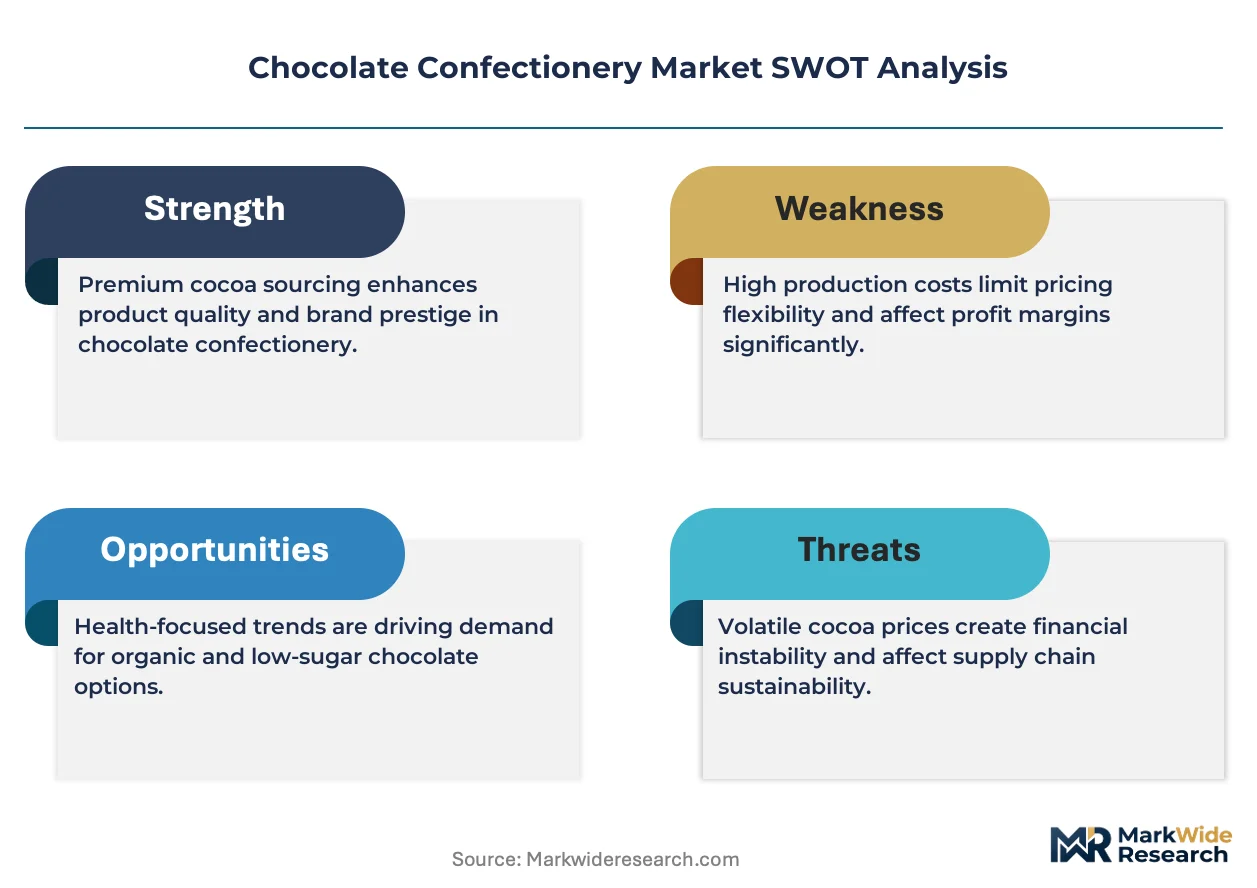
The central tension in the chocolate confectionery market is the collision between rising consumer demand for ethically sourced, transparent supply chains and the persistent price sensitivity of the mass market, a conflict intensified by new EU regulations.
Growth Catalysts
- Premiumization Trend:Consumer preference for high-cacao dark chocolate, driven by perceived health benefits, is expanding the premium segment in markets like Switzerland and Japan.
- Corporate Gifting Channel:The corporate gifting application provides significant margin uplift through customization and personalized packaging, separating it from high-volume retail.
- Clean Label Movement:Demand for simple, recognizable ingredients pushes manufacturers to remove artificial additives, aligning with broader consumer wellness trends.
Market Restraints
- Cocoa Price Volatility:Climate instability in key West African nations introduces significant raw material cost fluctuations, complicating financial planning and pricing for manufacturers.
- Regulatory Compliance Costs:The EU's deforestation-free supply chain rules impose substantial traceability and verification expenses, compressing margins for cocoa importers.
- Sugar Taxation Policies:Government-imposed sugar taxes in markets across Europe and the Americas increase production costs and pressure manufacturers to reformulate products.
Strategic Opportunities
- Functional Ingredients Integration:Incorporating ingredients like probiotics, vitamins, or adaptogens into chocolate bars creates new product categories targeting health and wellness consumers.
- Plant-Based Innovation:Developing high-quality vegan milk chocolates using oat, almond, or soy milk opens access to a growing demographic seeking dairy-free alternatives.
- Direct-to-Consumer Models:E-commerce platforms enable brands to build direct relationships with consumers, offering subscriptions, limited editions, and personalized products.
Industry Challenges
- Supply Chain Traceability:Implementing robust, auditable systems to track cocoa from farm to factory is a complex and costly challenge mandated by new EU regulations.
- Energy-Intensive Processing:Optimizing the conching process requires balancing high energy consumption against the flavor development and texture refinement demanded by premium products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Confectionery Market |
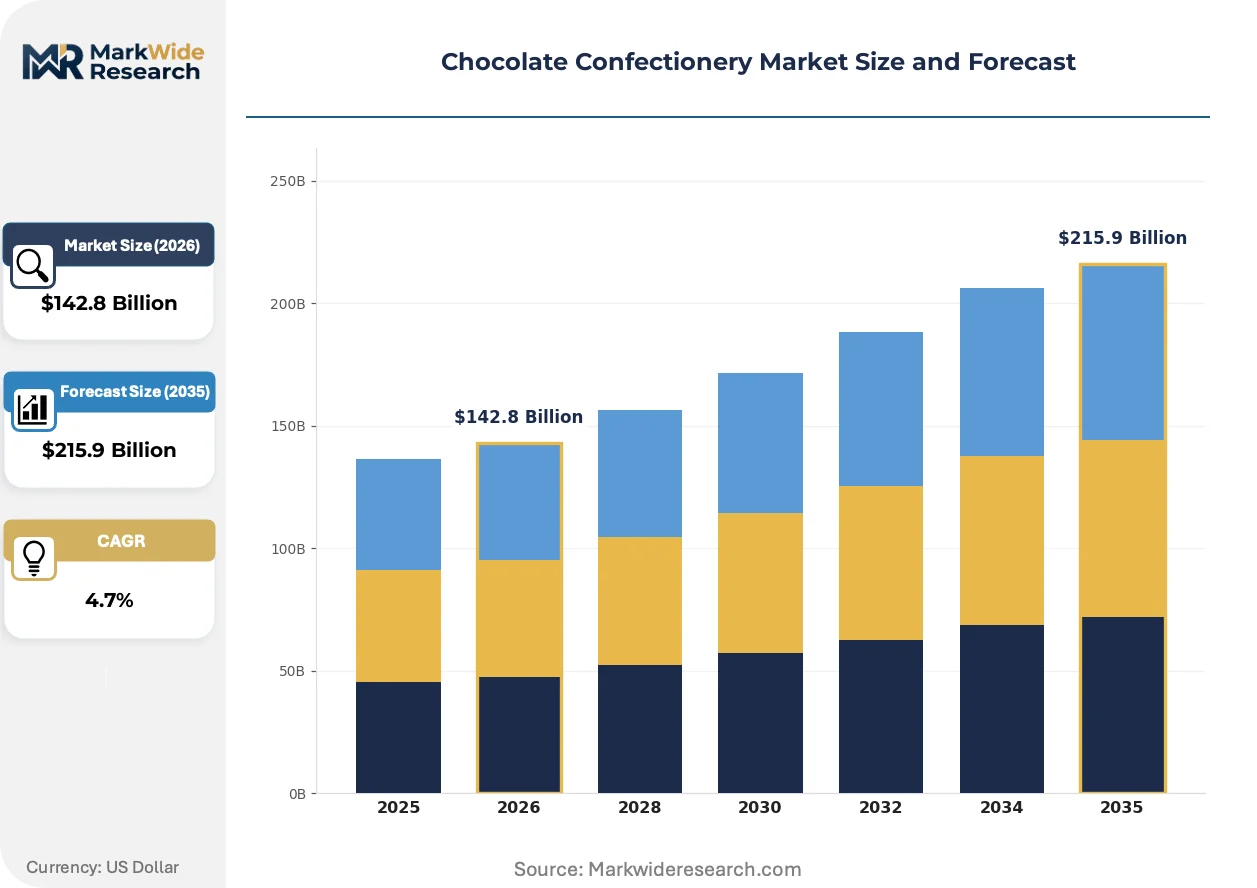
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $215.9 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Couverture Chocolate, Compound Chocolate Application: Personal Consumption, Gift Items, Baking Ingredients, Seasonal Pack, Event Catering, Corporate Gifting Packaging Type: Boxes, Wrappers, Tins, Bottles, Tubes, Sachets Customer Type: Retailers, Wholesalers, Food Service Providers, E-commerce Platforms, Specialty Stores |
| Companies Covered | Nestlé SA, Lindt & Sprüngli, Mars, Incorporated, Meiji Co., Ltd., Pladis, Mondelēz International, The Hershey Company, Haribo GmbH & Co. KG, Ferrero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Confectionery Market Strategic Shifts & Innovations
The market is being reshaped by a convergence of technological accessibility and stringent ethical oversight. This dynamic forces innovation in both product formulation and supply chain transparency, altering how value is created and communicated to the consumer.
Small-scale grinding and conching equipment provides the core technology for artisanal chocolate making. Adoption is accelerating among specialty food producers and high-end cafes seeking to differentiate their offerings. This accessibility is decentralizing flavor development, shifting innovation from large industrial processors to a network of craft-focused businesses.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is forcing a new level of supply chain scrutiny. This regulation requires large companies to provide audited reports on social and environmental impacts, including cocoa sourcing. The premium dark chocolate segment is most affected, as brand narratives built on ethical sourcing must now be backed by verifiable data.
A behavioral shift toward conscious consumption is altering purchasing decisions, with consumers actively seeking out third-party certifications like Fair Trade or Rainforest Alliance. This disrupts the traditional impulse-buy model at mass-market checkouts, redirecting sales toward specialty retailers. This trend is most visible in European markets like Germany and the Netherlands.
Chocolate Confectionery Market Segmentation
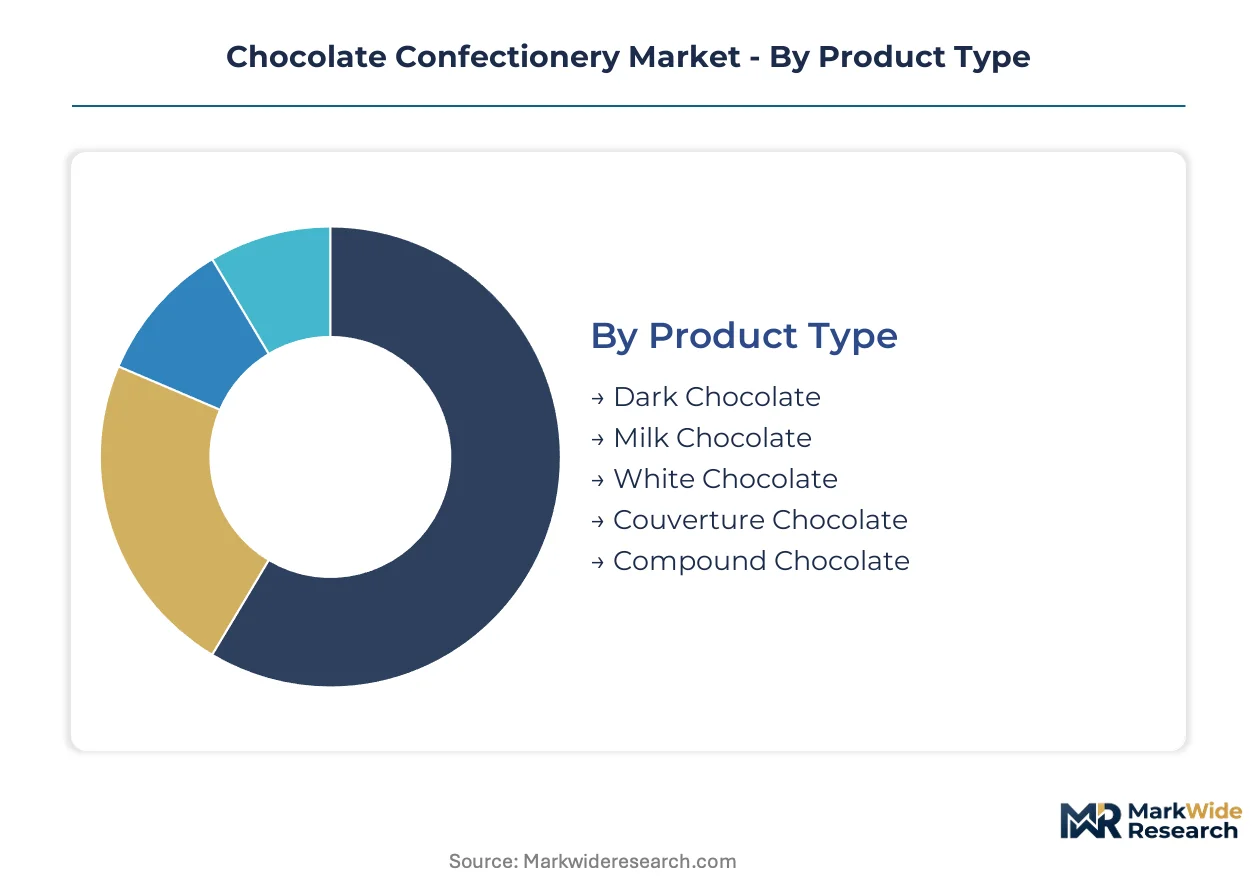
The chocolate confectionery market exhibits a complex structure, segmented by product type, application, packaging, and customer channels. Understanding these divisions is critical for manufacturers to align product development and distribution strategies with evolving consumer preferences and regulatory demands. Each segment presents distinct opportunities and challenges, influencing pricing and competitive dynamics across the value chain.
Product Type:
The technical specifications of chocolate confectionery products dictate their sensory profiles and suitability for various consumer preferences.
- Dark Chocolate:This product type contains a high percentage of cocoa solids, typically with less sugar and no milk solids. Demand concentrates in Switzerland and Japan, driven by perceived health benefits and a premiumization trend.
- Milk Chocolate:Characterized by the inclusion of milk powder or condensed milk, offering a creamy texture and sweeter taste. This product type maintains high-volume sales globally, particularly in mass-market retail channels.
- White Chocolate:Composed of cocoa butter, sugar, and milk solids, this variety lacks cocoa solids. It appeals to consumers seeking a milder, dairy-rich flavor profile.
- Couverture Chocolate:High-quality chocolate with extra cocoa butter, providing a smooth, glossy finish for professional confectionery and baking. It is favored by artisan chocolatiers for its superior workability.
- Compound Chocolate:This type uses vegetable fats instead of cocoa butter, offering cost-effectiveness and heat resistance. It is widely used in industrial applications and budget-friendly products.
Mature deployment sits with Milk Chocolate. Newer deployment is concentrated in Dark Chocolate.
Application:
Value capture varies significantly across the diverse applications for chocolate confectionery, reflecting different consumer motivations.
- Personal Consumption:This category involves individual purchases for immediate enjoyment or regular household use, representing the largest volume driver in the market. Consumers often prioritize convenience and familiar brand recognition for these purchases.
- Corporate Gifting:This application focuses on customized and personalized chocolate products presented by businesses to clients or employees. It provides significant margin opportunities due to bespoke packaging and premium product selection.
- Gift Items:This segment includes chocolates purchased for special occasions, holidays, or as tokens of appreciation. Packaging and presentation are critical for driving sales in this segment.
- Baking Ingredients:This category encompasses chocolate in various forms, such as chips, blocks, or powders, used by home bakers and professional patisseries. Product quality and melting characteristics are key considerations.
- Seasonal Pack:This refers to limited-edition chocolate assortments or novelty shapes released for holidays like Christmas, Easter, or Valentine's Day. These products drive impulse purchases during specific periods.
- Event Catering:This application supplies chocolates for weddings, parties, conferences, and other social or corporate gatherings. Bulk purchasing and elegant presentation are often required.
The largest sales volumes are generated by Personal Consumption, while Corporate Gifting provides substantial margin uplift.
Packaging Type:
Consumer interaction with chocolate confectionery is heavily influenced by its packaging format, which ranges from individual portions to bulk presentations.
- Wrappers:These are individual portions of chocolate bars or candies encased in flexible film or foil, common for impulse purchases. They offer convenience and protection for single-serve items in retail environments.
- Boxes:These containers hold assortments of chocolates, often presented as gifts or premium offerings, emphasizing aesthetic appeal. This packaging type supports higher price points and conveys luxury to consumers.
- Tins:Durable and reusable containers for chocolates, frequently used for seasonal collections or long-shelf-life products. Tins add a premium feel and can be kept as souvenirs.
- Bottles:Less common, this format is used for chocolate liqueurs or novelty chocolate drinks. This format targets adult consumers and specialized beverage markets.
- Tubes:Cylindrical packaging, often for chocolate coins, mini-candies, or spreadable chocolate. Tubes provide a playful or convenient dispensing method.
- Sachets:These are small, sealed pouches typically for individual servings of chocolate powder, hot chocolate mix, or small candies. These are prevalent in travel and convenience retail.
Wrappers dominate the impulse purchase segment, while Boxes are essential for premium and gifting occasions.
Customer Type:
The distribution channels for chocolate confectionery determine market reach and the final point of sale to consumers.
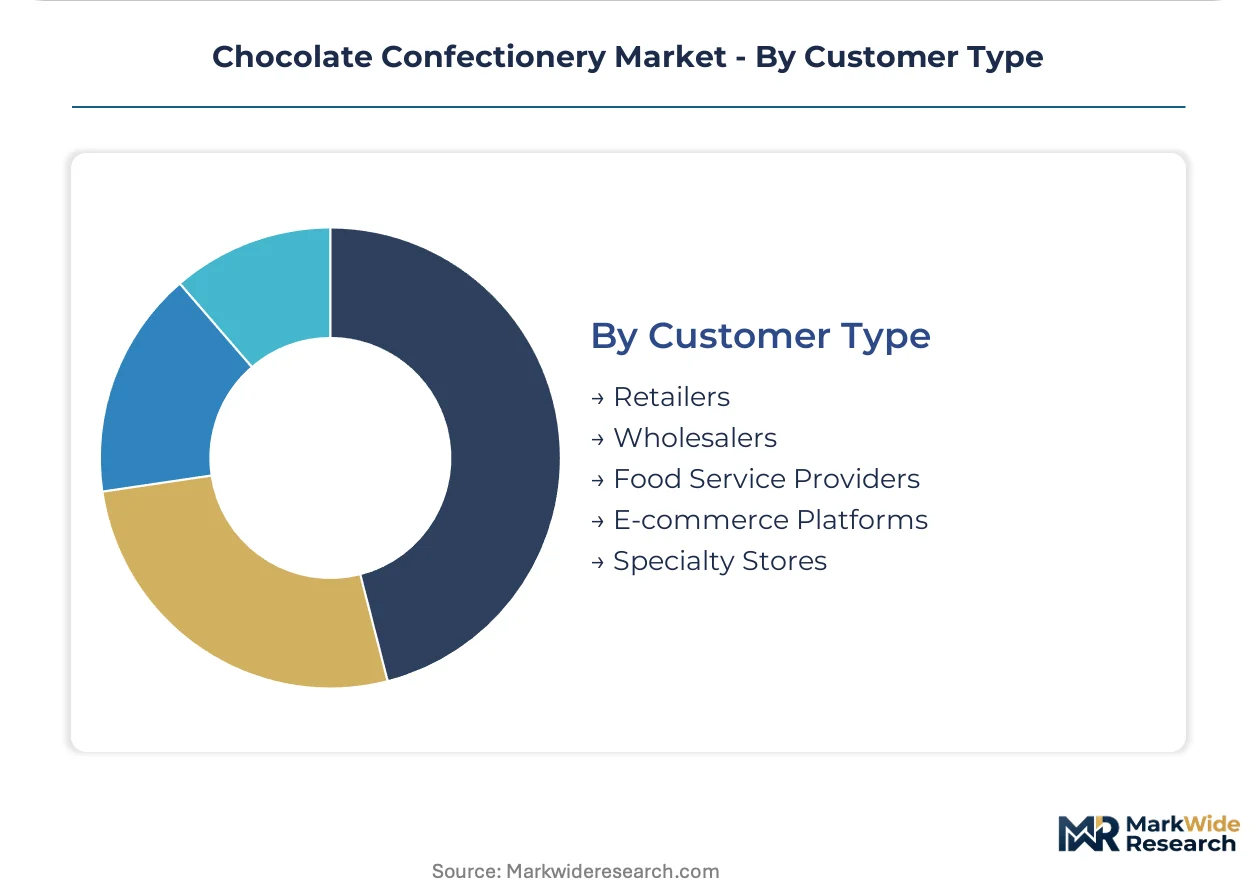
- Retailers:This category includes supermarkets, hypermarkets, convenience stores, and drugstores that sell chocolate confectionery directly to end consumers. This channel accounts for the vast majority of market volume due to broad accessibility.
- E-commerce Platforms:These online marketplaces and brand-specific websites facilitate direct sales and delivery of chocolate products to consumers. This channel enables personalized offerings and direct-to-consumer relationships.
- Wholesalers:These intermediaries purchase large quantities of chocolate from manufacturers for distribution to smaller retailers or food service providers. They play a crucial role in logistics and supply chain efficiency.
- Food Service Providers:This segment includes restaurants, cafes, hotels, and caterers that use or sell chocolate confectionery as desserts, ingredients, or accompaniments. Quality and bulk supply are important for these customers.
- Specialty Stores:These boutiques, artisan chocolate shops, and gourmet food stores focus on premium, handcrafted, or unique chocolate products. These outlets cater to discerning consumers seeking high-end experiences.
Traditional Retailers capture the majority of volume, with E-commerce Platforms expanding their share of direct consumer engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cocoa cultivation in West Africa underpins global chocolate confectionery supply, influencing raw material costs and sustainability initiatives worldwide. Consumer demand patterns vary significantly across continents, driven by cultural preferences and economic factors.
Switzerland
Swiss consumers prioritize premiumization, driving demand for high-cacao dark chocolate products. Swissmedic ensures stringent food safety and quality standards for all confectionery items. Zurich's specialized chocolatiers continue to innovate in flavor profiles and artisanal techniques.
Germany
German mass-market consumption remains strong, with a growing preference for clean label products. EFSA regulations heavily influence ingredient transparency and allergen declarations on confectionery packaging. Cologne hosts leading confectionery trade shows, driving significant product innovation.
Japan
Japanese consumers seek artisanal dark chocolate and unique flavor combinations, often influenced by seasonal ingredients. METI promotes ethical sourcing initiatives for imported food products, including cocoa. Tokyo's high-end retail districts showcase luxury chocolate brands and limited-edition releases.
United States
American demand centers on established brand recognition and extensive distribution, particularly for milk chocolate. The FDA sets comprehensive standards for ingredient labeling and allergen declarations across the confectionery sector. Hershey, Pennsylvania, remains a central hub for chocolate manufacturing and product development.
Ghana
Ghana contributes significantly to global cocoa supply, focusing on sustainable production practices. The Ghana Cocoa Board oversees quality control and farmer support programs, ensuring export standards. Kumasi's cocoa processing facilities manage substantial volumes for international markets.
Chocolate Confectionery Market Key Industry Players
Supply chain diversification dominates the current landscape, as manufacturers seek to mitigate raw material volatility and secure ethical sourcing. The market exhibits a tiered structure, from global mass-market producers to specialized premium brands and artisanal craft chocolatiers. Strategic archetypes include scale-focused manufacturers, vertically integrated specialists, and innovation-driven niche players. Dominant competitive moves involve securing diverse cocoa contracts, enhancing brand recognition, and developing premium product lines.
Large-scale manufacturers like Mondelēz International exemplify the volume-driven segment, leveraging extensive distribution networks for broad market reach. Ferrero Group, a privately held Italian company, represents the archetype focused on premium positioning through tight control over key ingredient supply chains. The Hershey Company, based in the United States, anchors the North American mass market, competing on strong brand equity and widespread retail presence.
| Leading Market Players |
|---|
| Nestlé SA |
| Lindt & Sprüngli |
| Mars, Incorporated |
| Meiji Co., Ltd. |
| Pladis |
| Mondelēz International |
| The Hershey Company |
| Haribo GmbH & Co. KG |
| Ferrero Group |
| Others |
Cost & Logistics Intelligence
Cocoa price volatility, driven by climate instability in West Africa, directly impacts manufacturing costs and translates into higher consumer pricing across all tiers, particularly affecting mass-market affordability.
Pricing Analysis
Ethical sourcing certifications and premium packaging features are often bundled into the final price for high-end chocolate confectionery, contrasting with the unbundled, basic product offerings in the mass market. Pricing stratifies across premium, standard, and economy tiers, with quality grade and brand recognition serving as primary differentiation drivers. Pricing pressure stems from rising raw material costs and increasing regulatory compliance expenses. Mass-market consumers exhibit high price sensitivity, while buyers of premium dark chocolate demonstrate lower sensitivity.
Supply Chain Analysis
Cocoa bean supply primarily rests on West African nations like Ghana and Côte d'Ivoire, forming the critical upstream input. The industry relies heavily on cocoa beans, sugar, and milk solids for its core products. Climate instability in key growing regions introduces significant raw material price volatility, a major structural risk. Distribution runs through a dual model, with traditional retailers handling mass volumes and e-commerce platforms enabling direct-to-consumer engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chocolate confectionery market is navigating a technology-driven transition, where small-scale grinding and conching equipment is displacing traditional large-scale industrial processing.
For Market Incumbents: To counter disruptive craft-focused businesses and rising ethical sourcing demands, incumbent manufacturers must reinforce their supply chain diversification strategies. Investment in robust traceability systems, mandated by the EU's CSRD, will solidify brand narratives built on ethical sourcing. Leveraging established brand recognition and extensive distribution networks will help maintain market share against niche players.
For New Entrants and Emerging Players: The EU's Corporate Sustainability Reporting Directive (CSRD) in Europe opens a window for new entrants to differentiate through verifiable ethical sourcing. Target the premium dark chocolate segment and plant-based innovation, where consumers seek novel experiences and healthier alternatives. A direct-to-consumer e-commerce model, offering subscriptions and personalized products, provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Increased adoption of third-party certifications like Fair Trade is the leading indicator that consumer values are fundamentally reshaping market dynamics. The market shifts towards premium, ethical, and functional offerings over the next decade. Acquisition targets should include niche brands with strong ethical sourcing credentials, functional ingredient expertise, or robust direct-to-consumer channels. Growth rate of plant-based chocolate sales is a specific signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Supply Chain Diversification | Mitigates raw material volatility and strengthens ethical sourcing claims for major manufacturers. |
| Premium Product Line Expansion | Captures higher margins and aligns with consumer preference for high-cacao dark chocolate. |
| Plant-Based Product Development | Addresses a growing demographic seeking dairy-free alternatives in the confectionery market. |
| Direct-to-Consumer Channel Buildout | Enables personalized offerings and fosters direct relationships with engaged consumers. |
| Ethical Sourcing Certification | Builds consumer trust and meets stringent regulatory demands for supply chain transparency. |
Research Approach
Multi-period observation of consumer purchasing patterns and cocoa price fluctuations anchored the trend analysis, supplemented by interviews with key industry stakeholders. Primary interviews with confectionery brand managers, cocoa farmers' cooperatives, retail category buyers, and food safety regulators provided qualitative insights. Secondary validation utilized FDA filings, EFSA reports, trade association publications, and corporate sustainability reports, triangulating data for robust market sizing.
A segment-weighting approach was applied to project market expansion across the analysis window, integrating volume and value drivers. Segmentation dimensions modeled included product type, application, packaging, customer type, and cocoa origin. Compound Annual Growth Rates were derived through regression analysis on historical data and expert consensus. Industry-specific forecast inputs included cocoa yield forecasts and sugar pricing trends.
The model assumes a particular technology adoption path; alternative pathways for plant-based milk alternatives would alter the outlook for dairy-free chocolate. Forecasts reflect assumptions regarding economic stability and regulatory enforcement. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Dietary Chocolate Products Market
Confectionery
Citrus Gummies Market
Confectionery
South Africa Confectionery Market
Confectionery
North America Compound Chocolate Market
Confectionery
North America Premium Chocolate Market
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Caramel Chocolate Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
Gum Base Candy Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Bangladesh Candy Market
Confectionery
Low Calorie Nutella Market