
 Confectionery Coating Market | 2026-2036
Confectionery Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Confectionery Coating Market Outlook
North America is reconfiguring its confectionery coating supply base as manufacturers respond to shifting cocoa butter alternatives demand. Barry Callebaut leverages its integrated bean-to-coating infrastructure across Wisconsin and Pennsylvania to sustain North American bakery and confectioner supply chains. Cargill anchors regional palm oil coating production through its processing network, while ADM competes on specialty lipid formulations for industrial candy manufacturers.
Confectionery coating denotes a fat-based exterior layer applied to confections, typically comprising cocoa butter equivalents, palm kernel oil, or sugar-based matrices with melting points between 32°C and 36°C to ensure snap and mouthfeel stability. The primary commercial purpose is to provide moisture barriers, visual finish, and controlled flavor release for mass-produced sweets and baked goods. Chocolate coatings occupy the largest value share among product types due to their ubiquity in enrobing applications, while palm oil coatings represent the fastest-growing category as manufacturers reformulate to manage cocoa price volatility. Liquid coatings dominate the form segment for industrial throughput efficiency, though powder coatings are gaining traction in artisanal bakery channels where portion control and shelf stability matter.
The FDA governs coating composition through its standards of identity for chocolate and chocolate alternatives, while EPA regulations on palm oil supply chain traceability shape sourcing decisions for US-based manufacturers. REACH compliance in Europe restricts certain emulsifier chemistries, compelling reformulation investments among exporters serving EU confectioners. Stakeholders must monitor evolving deforestation-free supply mandates and their cascading impact on coating fat procurement strategies.
Market Dynamics
Cocoa butter price volatility is compressing formulation margins and accelerating palm kernel oil substitution across industrial confectionery production. Manufacturers face simultaneous pressure from EU deforestation-free supply mandates and bakery sector demands for snap-stable coatings at lower input cost.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon propellants in coating spray applications is driving investment in mechanical enrobing equipment upgrades across German and Polish production facilities.
- Palm kernel oil fractionation advances:Crystallization control technology now yields cocoa butter equivalents with sharper melting profiles, expanding adoption in enrobed biscuit and ice cream bar segments.
- Industrial bakery clusters:Concentrated demand from automated production lines in Cologne, Hamburg, and Milan creates dedicated coating formulation partnerships with regional fat processors.
Market Restraints
- Cocoa butter price volatility:Futures market swings in Côte d'Ivoire and Ghana origin beans force quarterly reformulation cycles that disrupt long-term supply contracts with confectionery manufacturers.
- REACH emulsifier restrictions:ECHA classification of certain polyglycerol polyricinoleate variants as substances of very high concern limits import options for Asian coating suppliers serving EU buyers.
- Sugar reduction mandates:UK Soft Drinks Industry Levy extension into confectionery categories forces coating manufacturers to rebuild sweetness delivery systems without compromising shell integrity.
Strategic Opportunities
- Clean-label coating systems:Removal of titanium dioxide and synthetic emulsifiers opens premium positioning for sunflower lecithin and carnauba wax formulations in Nordic markets.
- Artisanal bakery powder coatings:Dry-form products with extended ambient stability address portion-control needs in independent patisseries across France and Belgium.
- EU Deforestation Regulation compliance services:Geolocation traceability for palm oil sourcing creates advisory revenue streams for coating compounders with established supply chain documentation systems.
Industry Challenges
- Emulsifier reformulation timelines:Replacement of restricted chemistries under REACH requires 18-24 month stability testing cycles that delay new product launches.
- Tempering equipment retrofit costs:Migration to lower-melting palm-based coatings demands heat-exchange system upgrades in legacy enrobing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confectionery Coating Market |
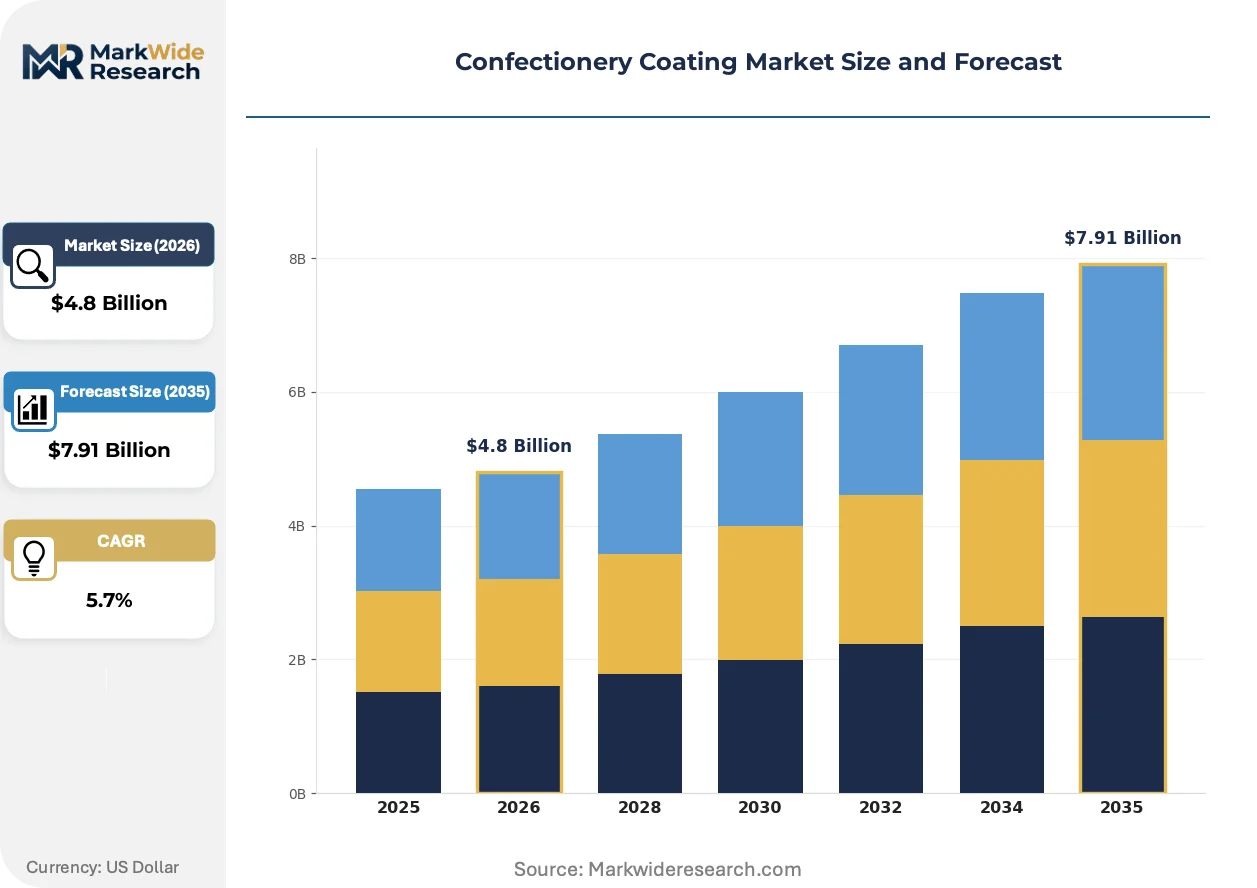
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Coatings, Caramel Coatings, Palm Oil Coatings, Sugar Coatings End User: Food Manufacturers, Bakeries, Confectioners, Retailers Application: Candy Coating, Dessert Topping, Snack Food, Baking Ingredient Form: Solid Coatings, Liquid Coatings, Powder Coatings, Granulated Coatings |
| Companies Covered | Barry Callebaut, Cargill, Blommer Chocolate Company, Clasen Quality Coatings, ADM, Fuji Oil Holdings, Olam Food Ingredients, AAK, Puratos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confectionery Coating Market Strategic Shifts
Formulation science is diverging along two paths: precision-engineered palm fractions for cost-sensitive mass production, and clean-label botanical waxes for premium positioning. Equipment manufacturers are responding with modular tempering systems that accommodate both trajectories.
High-pressure interesterification is collapsing the performance gap between palm kernel stearin and cocoa butter in snap and gloss metrics. Industrial chocolate manufacturers in Germany and Switzerland are adopting this enzymatic process at commercial scale. The technology is collapsing premium pricing tiers that previously separated cocoa butter coatings from compound alternatives.
REACH authorization requirements for specific emulsifier chemistries are forcing coating compounders to rebuild formulation portfolios from base lipids upward. ECHA's 2024 updates to substance restrictions have eliminated several long-used polyglycerol esters from EU-bound products. Specialty fat processors with in-house emulsifier synthesis capabilities are capturing reformulation contracts from commodity suppliers lacking vertical chemical production.
Bakery procurement teams are consolidating coating suppliers to reduce qualification overhead and secure deforestation-free documentation. Multi-site bakery groups in the Netherlands and Denmark now mandate single-source coating contracts with geolocation-verified palm supply chains. This concentration is displacing spot-market purchasing and elevating compounders with integrated sustainability audit systems.
Confectionery Coating Market Segmentation
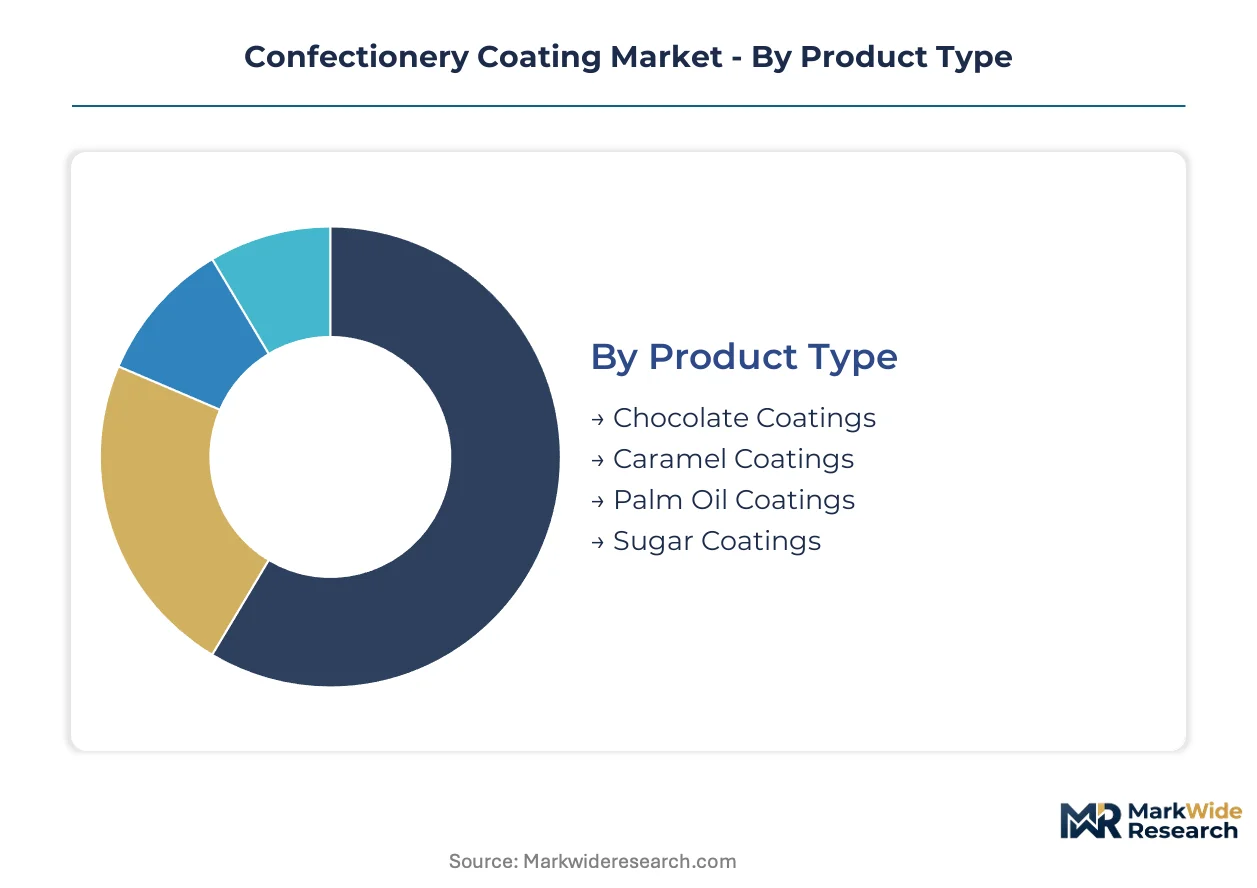
Confectionery coating procurement patterns diverge sharply across end-use channels, with industrial bakeries demanding bulk liquid formats while artisanal confectioners prioritize portion-controlled powders. Technical specifications for snap, gloss, and melting profile vary by application, forcing suppliers to maintain parallel formulation portfolios.
Product Type:
After-sales technical support intensity tracks inversely with product sophistication—chocolate coatings demand tempering calibration services, while palm oil alternatives require sustainability documentation.
- Chocolate Coatings:Cocoa butter-based matrices with 32-34°C melting points deliver controlled snap and glossy finish. Demand concentrates in German industrial enrobing operations where Barry Callebaut maintains bean-to-coating infrastructure; cocoa price volatility forces quarterly reformulation cycles.
- Palm Oil Coatings:Fractionated palm kernel stearin achieves cocoa butter equivalence through high-pressure interesterification. Adoption accelerates in Milan and Hamburg bakery clusters seeking deforestation-free supply chains under EU Regulation compliance mandates.
- Caramel Coatings:Sugar-dairy matrices with amorphous glass transition properties for chewy centers.
- Sugar Coatings:Crystalline sucrose shells for hard-panned candies and dragée applications.
Chocolate coatings hold the largest share; momentum sits with palm oil coatings as fractionation technology collapses performance premiums.
End User:
Customer scale determines service model—food manufacturers negotiate multi-year supply agreements while retailers demand just-in-time replenishment.
- Food Manufacturers:Integrated confectionery producers operating automated enrobing lines at throughput volumes exceeding 10,000 kg hourly. Cologne and Hamburg clusters anchor European demand for standardized coating specifications with batch-to-batch consistency guarantees.
- Bakeries:Automated production lines in Denmark and the Netherlands consolidate suppliers to reduce qualification overhead. Procurement teams now mandate geolocation-verified palm documentation, displacing spot-market purchasing.
- Confectioners:Artisanal producers in Belgium and France requiring small-batch flexibility and custom color matching.
- Retailers:Private-label brands sourcing finished coated products through co-manufacturing arrangements.
Food manufacturers command the dominant volume position; bakeries are gaining share fastest through supplier consolidation mandates.
Application:
Functional requirements separate premium coating tiers—candy applications prioritize shell integrity while baking ingredients emphasize heat stability.
- Candy Coating:Enrobed chocolate bars and panned confections requiring moisture barriers and controlled flavor release. German and Swiss manufacturers deploy high-pressure interesterification to achieve cocoa butter parity in snap metrics.
- Baking Ingredient:Inclusion coatings for cookies and muffins requiring oven-stable fat crystallization. Demand from automated bakery lines in Milan favors palm-based formulations with sharper melting profiles for post-bake texture.
- Dessert Topping:Decorative finishes for ice cream and pastries with glossy aesthetic requirements.
- Snack Food:Nut and fruit coatings with extended shelf-life stability for retail distribution.
Candy coating maintains the largest application share; baking ingredient applications are expanding most quickly through industrial bakery automation.
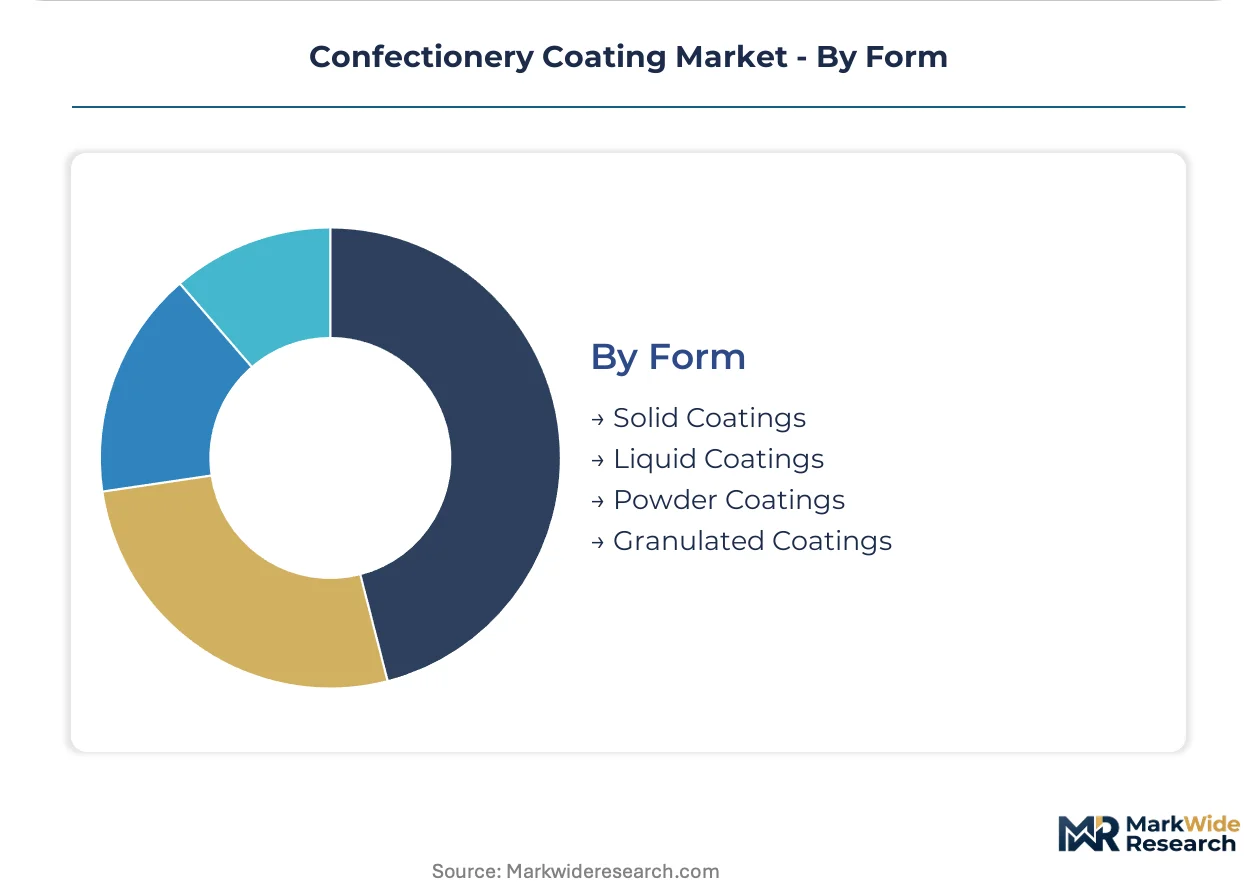
Form:
Physical state dictates equipment compatibility and inventory economics—liquid formats suit continuous production while powders address intermittent usage patterns.
- Liquid Coatings:Pre-tempered or untempered bulk deliveries for industrial enrobing lines. Wisconsin and Pennsylvania processing facilities supply North American bakery chains with tanker-delivered product, minimizing handling labor.
- Powder Coatings:Dry-form products with extended ambient stability for artisanal patisseries in France and Belgium. Portion control and reduced spoilage risk drive adoption among independent bakers lacking refrigerated storage capacity.
- Solid Coatings:Block or chip formats for manual melting operations in small-scale confectionery.
- Granulated Coatings:Free-flowing particles for specialized dusting and decorative applications.
Liquid coatings dominate industrial throughput; powder coatings are climbing the fastest through artisanal channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's liquid bulk terminals anchor European coating fat import flows, while the Rhine-Main-Danube waterway network distributes refined palm fractions to industrial bakery clusters across Central Europe.
Germany
Industrial enrobing demand from Cologne and Hamburg bakery clusters drives palm kernel oil fractionation capacity expansion. The F-Gas Regulation mandates mechanical equipment upgrades across chocolate processing facilities. North Rhine-Westphalia hosts Europe's densest concentration of compound coating production lines.
United States
Midwest dairy and confectionery corridors sustain demand for cocoa butter alternatives in enrobed ice cream bars. FDA standards of identity govern chocolate labeling while EPA traceability rules reshape palm oil procurement. Wisconsin and Pennsylvania processing infrastructure supplies tanker-delivered coatings to automated bakery chains.
Netherlands
Rotterdam's edible oil refining hub processes Southeast Asian palm shipments for distribution to Benelux bakery groups. ECHA REACH restrictions on emulsifier chemistries force reformulation partnerships with specialty fat processors. Randstad-based procurement teams now mandate geolocation-verified supply chain documentation.
Switzerland
Premium chocolate manufacturers deploy high-pressure interesterification to achieve cocoa butter parity in snap metrics. Swissmedic and federal food safety frameworks govern additive approvals for coating exports. The Lake Geneva corridor anchors precision lipid research facilities serving German and French confectioners.
United Kingdom
Sugar reduction mandates extending from soft drinks into confectionery categories force sweetness system rebuilds without shell integrity compromise. The Food Standards Agency oversees coating composition standards for retail private-label products. Greater Manchester and West Midlands industrial zones concentrate contract manufacturing for coated biscuit exports.
Confectionery Coating Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying fractionated fats and emulsifier packages. The vendor base separates into three strategic tiers: integrated bean-to-coating processors with captive supply chains, regional compounders serving single-country bakery clusters, and specialty emulsifier houses with in-house synthesis capabilities. Dominant competitive moves include backward integration into palm oil refining assets and geographic expansion through toll-processing partnerships in high-growth bakery corridors.
Among integrated processors, Barry Callebaut exemplifies the bean-to-coating archetype with infrastructure spanning multiple continents, while Cargill occupies a position anchoring North American palm oil coating production through processing network scale. ADM represents the specialty lipid formulation tier, competing on tailored emulsifier systems for industrial candy manufacturers.
| Leading Market Players |
|---|
| Barry Callebaut |
| Cargill |
| Blommer Chocolate Company |
| Clasen Quality Coatings |
| ADM |
| Fuji Oil Holdings |
| Olam Food Ingredients |
| AAK |
| Puratos Group |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Main-Danube waterway network's barge freight rates directly shape coating fat cost structures, concentrating pricing power among Rotterdam-based refiners while forcing downstream differentiation between tanker-delivered bulk contracts and artisanal powder formats.
Pricing Analysis
Volume-discount tiering separates food manufacturers purchasing 10,000 kg hourly throughput commitments from independent patisseries buying palletized powder quantities. Certification grade under EU Deforestation Regulation compliance mandates creates premium positioning for geolocation-verified palm documentation, while standard tiers compete on crystallization control technology. Pricing pressure stems from cocoa butter futures volatility forcing quarterly reformulation cycles. Food manufacturers exhibit highest price sensitivity due to contract renegotiation frequency; premium confectioners show lowest sensitivity given brand positioning requirements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize contracts between German bakery clusters and Southeast Asian palm kernel oil suppliers, reflecting working capital pressure across the value chain. Supply concentrates in Indonesia and Malaysia for crude palm oil, Germany and the Netherlands for fractionation and compounding, with cocoa butter sourcing anchored in Côte d'Ivoire and Ghana. Raw material dependencies span palm kernel stearin, cocoa butter equivalents, and sunflower lecithin emulsifier systems. Single-source vulnerability around Rotterdam's edible oil refining hub creates concentration risk. Distribution runs through liquid bulk terminals at Hamburg and tanker deliveries to automated bakery lines across North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Confectionery coating incumbents face a substitution defense against high-pressure interesterification technology collapsing the performance premium between palm-based compounds and cocoa butter matrices.
For Market Incumbents: Entrench deforestation-free supply chain documentation as a competitive moat by investing in geolocation traceability systems that satisfy EU Regulation mandates. Secure backward integration into palm oil refining assets to control input cost volatility and maintain margin position against cocoa butter price swings. Prioritize certification investment for REACH-compliant emulsifier synthesis capabilities. For New Entrants and Emerging Players: Artisanal bakery powder coatings in France and Belgium represent the most penetrable entry point, addressing portion-control needs among independent patisseries lacking refrigerated storage infrastructure. Clean-label botanical wax formulations for Nordic premium markets offer second white-space opportunity. Position through direct technical service partnerships with regional patisserie supply distributors rather than competing on bulk liquid volume. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty fat processors with in-house emulsifier synthesis capabilities, as REACH authorization requirements eliminate commodity suppliers lacking vertical chemical production. Long-term viability hinges on reformulation contract capture from displaced Asian coating exporters. Watch ECHA substance restriction updates as inflection indicator for consolidation acceleration among compounders with compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Refining | Captures margin from Rotterdam's edible oil processing hub while securing deforestation-free documentation. |
| High-Pressure Interesterification Scale-Up | Collapses cocoa butter equivalence premiums for German and Swiss industrial chocolate manufacturers. |
| REACH-Compliant Emulsifier Synthesis | Eliminates import restrictions for Asian suppliers serving EU-bound coating formulations. |
| Geolocation Traceability System Deployment | Satisfies EU Deforestation Regulation mandates for Benelux bakery procurement consolidation. |
| Artisanal Powder Coating Formulation | Addresses portion-control demand from independent French and Belgian patisseries. |
Study Parameters
Desk research of customs trade databases, ECHA substance restriction filings, and edible oil industry association reports preceded structured interviews with compound coating plant managers, bakery procurement leads, specialty fat R&D directors, and emulsifier supply chain coordinators. Primary fieldwork validated secondary findings on palm kernel oil fractionation technology adoption and REACH compliance cost structures. Bottom-up volume estimates from individual production facility throughput combined with top-down market sizing from trade flow analysis.
Fixed assumptions held cocoa butter price volatility patterns and EU regulatory enforcement timelines constant across the projection horizon, while varying industrial bakery automation penetration and clean-label formulation adoption rates. Segmentation modeling tracked product type, end-user scale tier, application function, and physical form state. CAGRs derived from weighted average of historical volume trajectories and forward-looking capacity expansion announcements. Forecast inputs included Rhine-Main-Danube freight cost indices and F-Gas Regulation equipment upgrade cycles.
Macroeconomic conditions sit as an overlay; deviation in energy costs, currency exchange rates, or trade policy would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Infused Fruits Jellies Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Low-Fat Sweets Market
Confectionery
Sugar Free Mints Market
Confectionery
South America Chocolate Market
Confectionery
US Confectionery Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
Licorice Candy Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Europe Chocolate Market
Confectionery
Diet Candy Market
Confectionery
Europe Premium Chocolate Market
Confectionery
Milk Chocolate Market
Confectionery
Europe Compound Chocolate Market
Confectionery
North America Compound Chocolate Market