
 Low Fat Nut Butter Market | 2026-2036
Low Fat Nut Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Nut Butter Market Analytics
North American specialty nut processing capacity is consolidating as co-manufacturers invest in cold-press and defatting equipment to serve branded label demand. The J.M. Smucker Company leverages its peanut sourcing infrastructure to maintain cost discipline across retail channels. Hormel Foods Corporation sustains portfolio relevance through shelf-stable spreads positioned for protein-seeking households. Kraft Heinz competes on distribution density, securing endcap placement in conventional supermarkets nationwide.
Low fat nut butter denotes ground nut pastes with fat content reduced through mechanical pressing or aqueous extraction to approximately 25-40% below conventional equivalents, yielding spreadable textures with preserved protein density for dietary applications. Peanut butter retains volume leadership due to commodity-scale supply and price accessibility, while almond butter commands premium positioning among health-conscious consumers seeking monounsaturated fat profiles. Squeeze pack formats represent the fastest-growing packaging segment, addressing portable consumption occasions among fitness enthusiasts and athletic end users.
The FDA governs nutritional labeling claims and allergen declarations that constrain formulation transparency, while USDA organic certification shapes ingredient sourcing requirements for premium-tier entrants. The EPA regulates wastewater discharge from aqueous fat-extraction facilities, elevating capital costs for processing expansion. Stakeholders must monitor evolving clean-label enforcement thresholds and defatting technology licensure as determinants of scalable market access.
Market Dynamics
Mechanical pressing and aqueous extraction technologies are compressing fat content thresholds while preserving protein density, forcing processors to retool equipment or cede shelf space to co-manufacturers with defatting capabilities.
Growth Catalysts
- FDA nutritional labeling transparency:Clean-label claims for reduced-fat spreads attract health-conscious grocery shoppers seeking verified macronutrient profiles. Premium positioning accelerates as label scrutiny intensifies.
- Fitness enthusiast demand:Protein-conscious dietary patterns among athletic end-users pull squeeze-pack formats into gym bags and post-workout consumption occasions. Portable packaging innovations capture this cohort.
- Cold-press processing:Co-manufacturers deploying defatting equipment enable branded label entrants to launch without capital-intensive infrastructure. Processing access democratizes market entry.
Market Restraints
- Peanut commodity price volatility:Input cost swings for runner peanuts compress margin stability for volume-positioned spreads. Price hedging remains underdeveloped among mid-tier processors.
- USDA organic certification timelines:Ingredient sourcing requirements for premium-tier entrants extend product development cycles by 8-14 months. Certification bottlenecks constrain pipeline velocity.
- Almond water intensity:California drought exposure elevates sustainability scrutiny for almond butter positioning. Water footprint disclosures pressure monounsaturated fat marketing claims.
Strategic Opportunities
- India FSSAI clean-label enforcement:Emerging regulatory thresholds for processed nut spreads create first-mover advantage for transparent formulation entrants. Premium import positioning opens as domestic supply lags.
- Subscription direct-to-consumer channels:Recurring revenue models bypass conventional supermarket slotting fees. Custom flavor rotations capture household loyalty outside retail gatekeepers.
- Sports nutrition cross-merchandising:Protein bar adjacent placement in specialty fitness retail elevates low fat nut butter from pantry staple to performance nutrition. Category boundary blurring unlocks trial.
Industry Challenges
- Defatting equipment operator scarcity:Cold-press and aqueous extraction technician training pipelines remain underdeveloped. Talent gaps throttle capacity expansion at co-manufacturing facilities.
- EPA wastewater discharge compliance:Aqueous fat-extraction facilities face capital-intensive effluent treatment upgrades. Permitting timelines extend project payback periods beyond investor thresholds.
- Allergen cross-contamination protocols:Shared processing lines for peanut and tree nut spreads demand rigorous sanitation validation. Facility segregation requirements elevate operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Nut Butter Market |
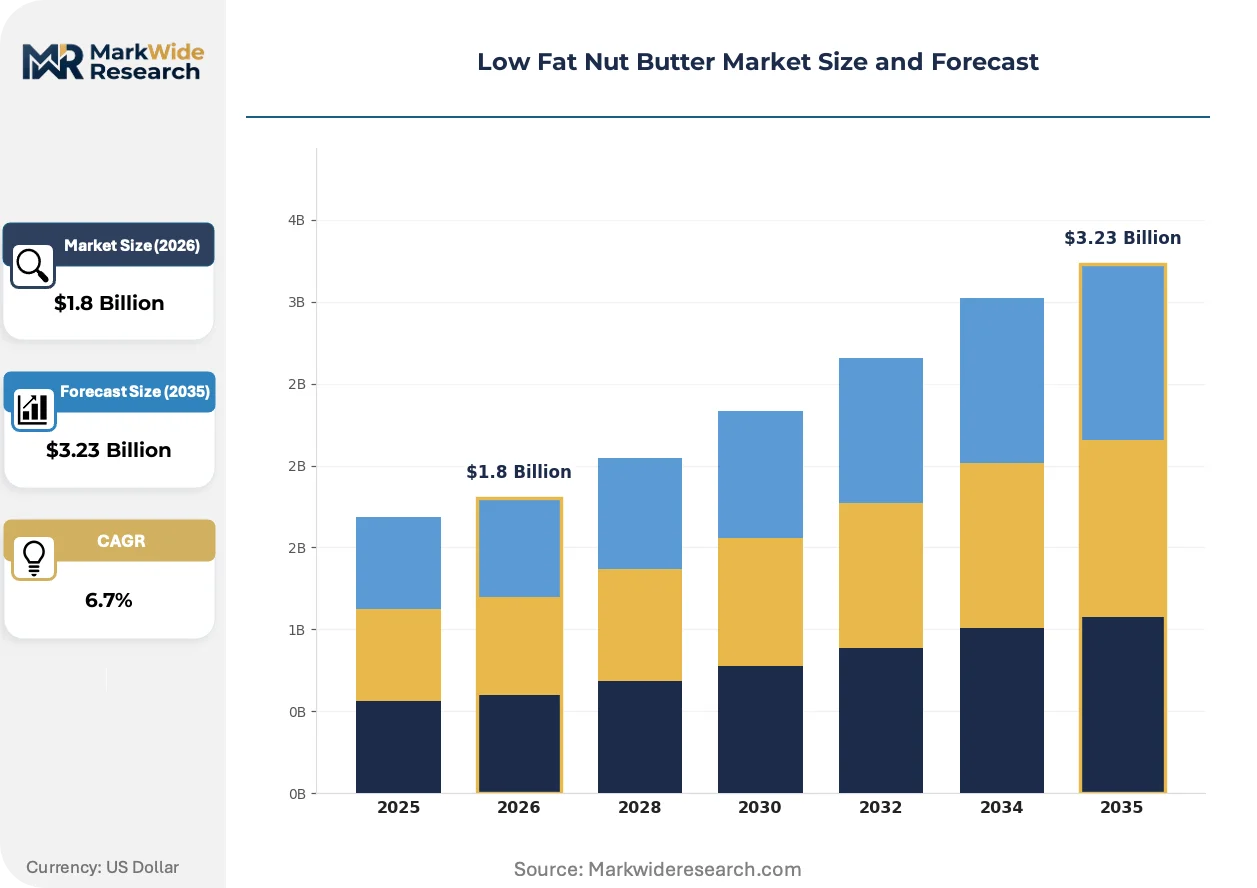
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Butter, Peanut Butter, Cashew Butter, Hazelnut Butter Packaging Type: Jar, Squeeze Pack, Pouch, Bulk Container Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores End User: Fitness Enthusiasts, Health Conscious Consumers, Children, Athletes |
| Companies Covered | The J.M. Smucker Company, Hormel Foods Corporation, Unilever, Procter & Gamble, Kraft Heinz, Conagra Brands, The Hain Celestial Group, Justin's, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Nut Butter Market Evolving Landscape
Product development pipelines are bifurcating between ultra-clean label minimalism and functional fortification, with processing technology investments determining which path processors can credibly pursue.
Supercritical CO2 defatting is electrifying the separation of oil from nut paste without thermal degradation, preserving volatile flavor compounds that aqueous methods strip. Equipment manufacturers in Germany and Switzerland are scaling commercial units for North American co-manufacturers. This technology is compressing the quality gap between reduced-fat and conventional spreads, enabling premium pricing parity.
REACH chemical safety registrations in Europe are tightening emulsifier and stabilizer approvals for imported nut spreads, forcing reformulation toward lecithin-free or native protein-stabilized systems. EFSA novel food consultations for emerging nut sources (tigernut, watermelon seed) are extending approval timelines. Premium private label entrants targeting EU distribution are front-loading regulatory dossier investments.
Gym-adjacent retail placement is displacing conventional grocery aisle dependence for fitness-positioned brands. Boutique fitness chains with captive cafés are negotiating exclusive flavor collaborations, extracting margin through controlled distribution rather than slotting fee competition. This channel pivot is most visible in coastal US metropolitan markets where studio density supports localized supply contracts.
Low Fat Nut Butter Market Segmentation
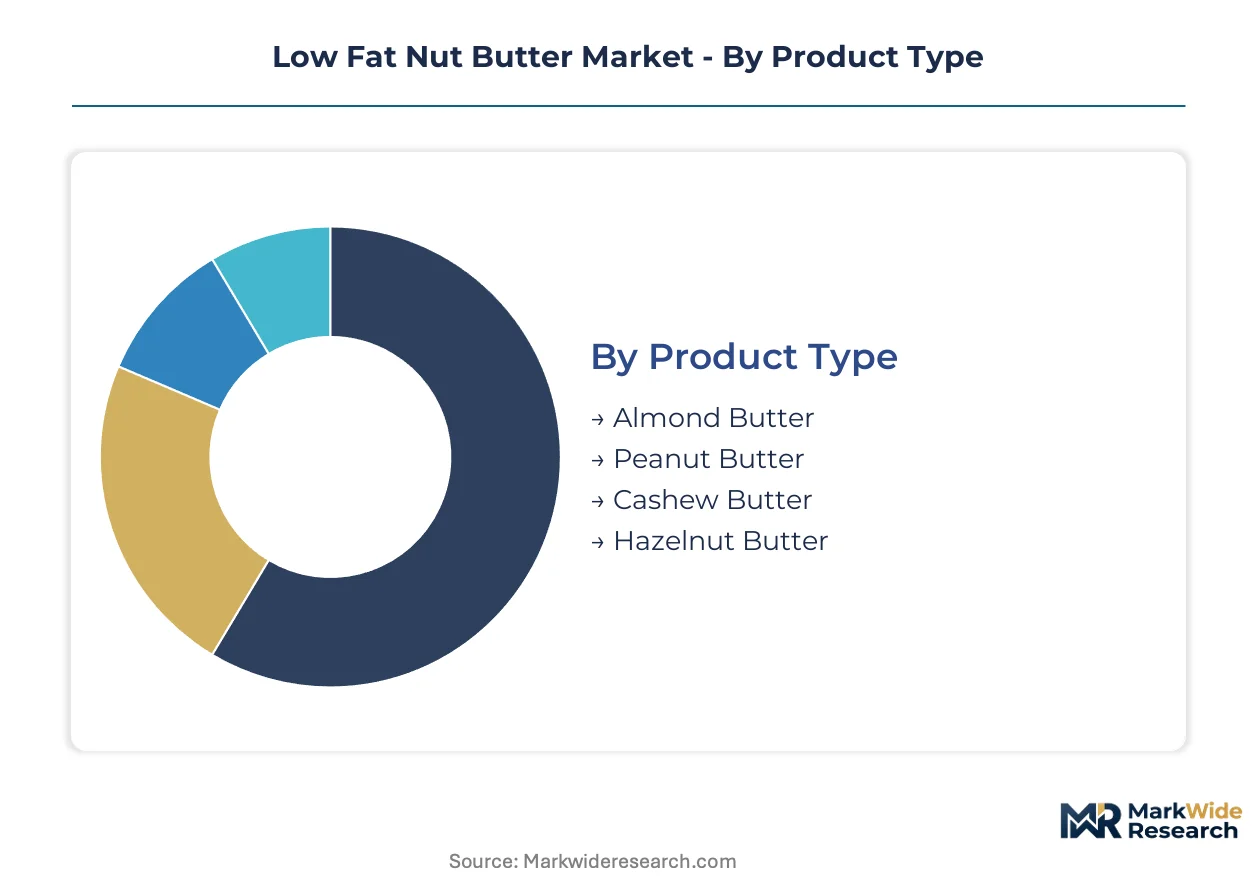
Low fat nut butter purchasing patterns diverge sharply across product format, channel access, and user lifestyle. Understanding these fault lines enables processors to align defatting investments with margin-rich placement opportunities rather than commodity volume plays.
Product Type:
Upgrade cycles in reduced-fat spreads track protein-per-calorie optimization and monounsaturated fat marketing claims, with consumers trading conventional varieties for mechanically pressed alternatives.
- Peanut Butter:Runner peanut supply chains deliver commodity-scale defatted paste at 25-40% fat reduction through aqueous extraction. Volume demand concentrates in conventional supermarkets where price-sensitive households prioritize protein density per dollar spent.
- Almond Butter:Cold-press processing preserves volatile flavor compounds that aqueous methods strip, commanding premium shelf positioning among health-conscious consumers seeking monounsaturated fat profiles. California drought exposure elevates sustainability scrutiny for water-intensive cultivation.
- Cashew Butter:Creamier mouthfeel from higher native starch content suits clean-label minimalism without added stabilizers.
- Hazelnut Butter:European import positioning leverages supercritical CO2 defatting equipment for flavor preservation in premium tier spreads.
Volume placements concentrate in peanut butter; the faster expansion belongs to almond butter.
Packaging Type:
Consumption occasion fragmentation is forcing parallel packaging investments across at-home pantry storage and portable single-serve formats.
- Squeeze Pack:Single-serve pouches capture gym bag and post-workout consumption among athletic end-users. Fitness enthusiast demand pulls this format into specialty retail adjacent to protein bars.
- Jar:Conventional glass and PET containers dominate household pantry replenishment through supermarket center-store placement.
- Pouch:Flexible stand-up formats reduce shipping cube for direct-to-consumer subscription channels.
- Bulk Container:Foodservice and co-manufacturing ingredient supply bypass retail packaging overhead.
Jar formats anchor current volume; squeeze packs are climbing the fastest.
Distribution Channel:
Channel access determines clean-label credibility verification and price realization, with divergent slotting fee structures shaping margin architecture.
- Supermarkets:Endcap placement in conventional grocery secures impulse trial among health-conscious grocery shoppers. Kraft Heinz distribution density competes on shelf space rather than formulation differentiation.
- Health Food Stores:Independent natural retailers validate organic certification and cold-press processing claims for premium positioning.
- Online Retailers:Subscription direct-to-consumer models bypass slotting fees through recurring revenue and custom flavor rotations.
- Convenience Stores:Grab-and-go squeeze pack placement captures unplanned portable consumption.
Supermarket channels dominate current placements; online retailers are gaining share fastest.
End User:
User cohorts segment by protein consciousness intensity and occasion specificity, from performance nutrition to pediatric palatability.
- Fitness Enthusiasts:Protein-conscious dietary patterns drive squeeze pack adoption for post-workout macronutrient targeting. This cohort expands most quickly as athletic lifestyle marketing penetrates mainstream wellness.
- Health Conscious Consumers:Label scrutiny and clean-label claims attract verified macronutrient profile seekers in premium supermarket tiers.
- Children:Reduced-fat formulations address parental concerns about early dietary fat exposure while maintaining spreadability for school lunch applications.
- Athletes:Sports nutrition cross-merchandising elevates low fat nut butter from pantry staple to performance nutrition in specialty fitness retail.
Health conscious consumers anchor current volume; fitness enthusiasts show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Runner peanut cultivation in the southeastern United States anchors supply security for defatted paste production. California almond orchards face water stress that reshapes sourcing economics for premium cold-press processors. Indian groundnut farming regions are scaling aqueous extraction infrastructure to serve export demand.
United States
Fitness enthusiasts in coastal metropolitan markets pull squeeze-pack formats into gym-adjacent retail channels. FDA nutritional labeling transparency requirements enforce verified macronutrient disclosure for reduced-fat claims. Georgia and Alabama processing clusters concentrate mechanical pressing capacity to serve branded label demand.
Canada
Health-conscious consumers in Toronto and Vancouver validate organic certification for premium almond butter positioning. Health Canada allergen declaration protocols constrain shared processing line configurations for peanut and tree nut spreads. Prairie provinces supply conventional peanut butter volume through established retail distribution networks.
Germany
REACH chemical safety registrations tighten emulsifier approvals for imported nut spreads, forcing lecithin-free reformulation. EFSA novel food consultations extend approval timelines for emerging nut sources entering premium tiers. Stuttgart and Munich co-manufacturing hubs deploy supercritical CO2 defatting equipment for flavor preservation.
India
FSSAI clean-label enforcement thresholds create first-mover advantage for transparent formulation entrants in processed nut spreads. Gujarat and Maharashtra groundnut processing belts scale aqueous extraction infrastructure to capture export demand. Domestic supply lags behind regulatory ambition, opening premium import positioning.
Australia
Sports nutrition cross-merchandising elevates low fat nut butter from pantry staple to performance nutrition in specialty fitness retail. TGA therapeutic claims oversight constrains protein marketing language for athletic positioning. Sydney and Melbourne boutique fitness chains negotiate exclusive flavor collaborations through controlled distribution.
Low Fat Nut Butter Market Competitive Landscape
Global majors compete with regional champions across distribution density and processing technology access. The vendor base stratifies between commodity-scale peanut butter suppliers and premium almond butter specialists with cold-press capabilities. Three archetypes dominate: diversified food conglomerates with sourcing infrastructure, natural foods specialists with clean-label credibility, and co-manufacturers with defatting equipment access. Competitive moves center on co-manufacturing partnerships to bypass capital-intensive processing investments and subscription channel development to escape supermarket slotting fees.
Among diversified food conglomerates, The J.M. Smucker Company and Kraft Heinz occupy positions anchored by peanut sourcing infrastructure and retail distribution density. Hormel Foods Corporation exemplifies the shelf-stable portfolio extension archetype targeting protein-seeking households. These three represent scale-driven positioning that competes on shelf space rather than formulation differentiation.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| Hormel Foods Corporation |
| Unilever |
| Procter & Gamble |
| Kraft Heinz |
| Conagra Brands |
| The Hain Celestial Group |
| Justin's |
| Nestlé |
| Others |
Value Network & Pricing Analysis
Defatting equipment technician scarcity in Georgia and Alabama processing clusters compresses labor-cost differentials that separate premium cold-press almond butter from economy-tier aqueous-extracted peanut spreads. This workforce concentration tightens margin architecture for mid-tier processors caught between commodity pricing floors and premium positioning ceilings.
Pricing Analysis
Warranty coverage for processing equipment uptime separates bundled service contracts from bare-metal capital sales in co-manufacturing negotiations. Three-tier pricing structure across premium, standard, and economy levels tracks USDA organic certification status and cold-press versus aqueous extraction method. Price erosion runs through conventional peanut butter as runner peanut commodity volatility destabilizes input cost forecasting. Health-conscious grocery shoppers in supermarket premium tiers show least price sensitivity; volume-positioned conventional households exhibit highest elasticity.
Supply Chain Analysis
USDA organic certification and FDA nutritional labeling compliance gate market access for branded label entrants sourcing from co-manufacturers. Runner peanut supply concentrates in Georgia, Alabama, and Texas; almond cultivation centers on California's Central Valley; Indian groundnut processing scales in Gujarat and Maharashtra. Raw material flows draw from agricultural commodity markets, defatting equipment fabrication in Germany and Switzerland, and flexible packaging films. Single-source vulnerability in California almond orchards from drought exposure threatens premium tier supply security. Distribution runs through conventional supermarket center-store, health food specialty retail, and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Low Fat Nut Butter Market operates as a cost-of-compliance story where EPA wastewater discharge regulations for aqueous extraction facilities erect capital barriers that protect incumbent co-manufacturers with permitted infrastructure.
For Market Incumbents: Deploy co-manufacturing partnership leverage to capture branded label demand without additional capital deployment. Secure exclusive supply agreements with boutique fitness chains before subscription entrants scale direct-to-consumer channels. Cold-press equipment access represents the critical defensive moat against aqueous-extraction commodity competitors. For New Entrants and Emerging Players: The squeeze pack premium-to-jar economy price-point gap creates entry latitude for portable-format specialists targeting gym-adjacent retail. White space concentrates in India FSSAI clean-label enforcement windows where domestic supply lags regulatory ambition. Sports nutrition cross-merchandising adjacent to protein bars offers the most penetrable go-to-market vector. For Investors and Strategic Acquirers: Re-rating potential sits with co-manufacturers possessing permitted aqueous extraction capacity given EPA regulatory tightening that extends new entrant payback periods beyond investor thresholds. Long-term viability favors processors with backward integration into runner peanut sourcing or captive almond orchard relationships. The signal to watch is FSSAI enforcement acceleration in India triggering premium import demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Manufacturing Partnership Expansion | Branded label entrants bypass EPA permitting timelines by accessing permitted defatting infrastructure. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models escape supermarket slotting fees that compress margin for conventional placement. |
| Cold-Press Equipment Investment | Supercritical CO2 defatting from German and Swiss manufacturers preserves volatile flavor compounds for premium positioning. |
| Sports Nutrition Channel Pivot | Boutique fitness chain exclusive collaborations extract margin through controlled distribution rather than slotting competition. |
| India Import Positioning | FSSAI clean-label enforcement gaps create first-mover advantage before domestic aqueous extraction capacity scales. |
Research Methodology
Independent corroboration across co-manufacturing facility operators, branded label product managers, and retail category buyers underwrites the qualitative findings in this analysis. Primary interviews with defatting equipment technicians, FDA regulatory affairs consultants, and health food store procurement directors combined with secondary validation from USDA organic certification databases, EPA discharge permit records, and FSSAI enforcement circulars. Bottom-up volume modeling from processor capacity utilization and top-down demand triangulation from retail channel placement data anchored the market sizing.
Comparable-period anchoring to historical runner peanut commodity cycles and almond orchard yield patterns established baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user protein consciousness intensity. CAGRs were derived from trend extrapolation of fitness enthusiast cohort expansion and clean-label claim penetration. Industry-specific forecast inputs incorporated California drought stress indices and co-manufacturing capacity expansion timelines.
Inputs from EPA permit filings and USDA organic certification records were available through the study window; gaps in real-time co-manufacturing capacity utilization data introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented assumptions regarding FSSAI enforcement acceleration and boutique fitness chain expansion rates. A model refresh is warranted upon material change in California water allocation policy affecting almond butter supply economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
China Fox Nuts Market
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Soy Nut Market
Nuts and Seeds
Cashew Nut Butter Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Asia-Pacific Grape Seed Extract Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Almond Butter Market