
 Europe Caramel Chocolate Market | 2026-2036
Europe Caramel Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Caramel Chocolate Market Intelligence
Asset-light contract manufacturing and co-packing arrangements are reshaping competitive entry in European caramel chocolate, allowing niche brands to scale without capital-heavy production facilities. Barry Callebaut AG leverages its industrial chocolate platform to supply private-label caramel formulations across multiple countries. Ferrero International SA sustains premium positioning through tightly controlled in-house production of hazelnut-caramel blends. Mondelēz International Inc. anchors volume competitiveness through established distribution networks spanning Central and Eastern Europe.
Europe caramel chocolate denotes confectionery combining caramelized sugar and dairy with cocoa-based coatings, typically requiring controlled Maillard reaction temperatures between 110°C and 140°C to achieve characteristic flavor depth without scorching. The product serves both impulse retail purchase and gift-oriented consumption occasions across seasonal and everyday demand cycles. Milk chocolate variants dominate volume given their accessibility to children and mass-market positioning, while dark chocolate caramel formats capture expanding margin pools among health-conscious adults reducing sugar intake. Specialty stores channel premium boxed assortments with higher per-unit economics, whereas online retailers accelerate trial-size pouch growth through subscription and direct-to-consumer fulfillment models.
EFSA guidelines on acrylamide mitigation in thermally processed foods directly shape caramel production protocols, pushing manufacturers toward lower-temperature cooking methods or recipe reformulation. The EU Deforestation Regulation compels documented traceability for cocoa supply chains, raising compliance costs particularly for mid-tier producers lacking established farm-level partnerships. REACH chemical safety standards govern flavoring substances and packaging material migration limits, influencing ingredient selection and wrapper specification decisions. Stakeholders must monitor evolving EUDR enforcement timelines and acrylamide threshold revisions to calibrate sourcing investments and product development pipelines accordingly.
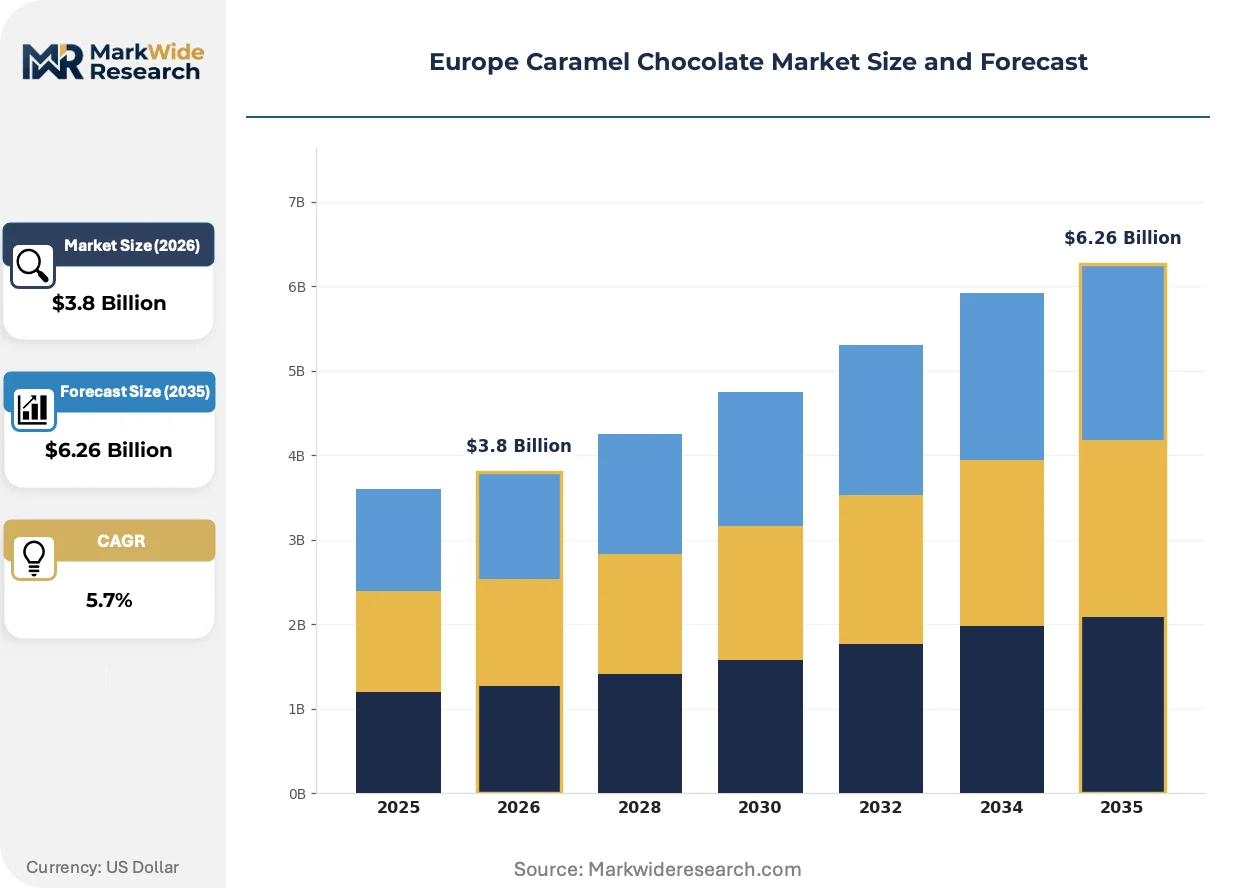
Market Dynamics
The EU Deforestation Regulation (EUDR) is forcing European caramel chocolate manufacturers to rebuild traceable cocoa supply chains from farm to finished product, restructuring procurement relationships and compliance investments across the value chain.
Growth Catalysts
- ESG-driven premiumization:Young adult consumers in Germany and France prioritize ethically sourced caramel chocolates with verified farm-level traceability, expanding margin pools for compliant producers.
- REACH-compliant flavor innovation:ECHA guidelines on chemical safety are accelerating clean-label caramel formulations using natural vanilla and sea salt substitutes.
- Poland:Rising disposable incomes and Western European retail format adoption are creating new addressable demand for mid-tier boxed assortments in Central Europe.
Market Restraints
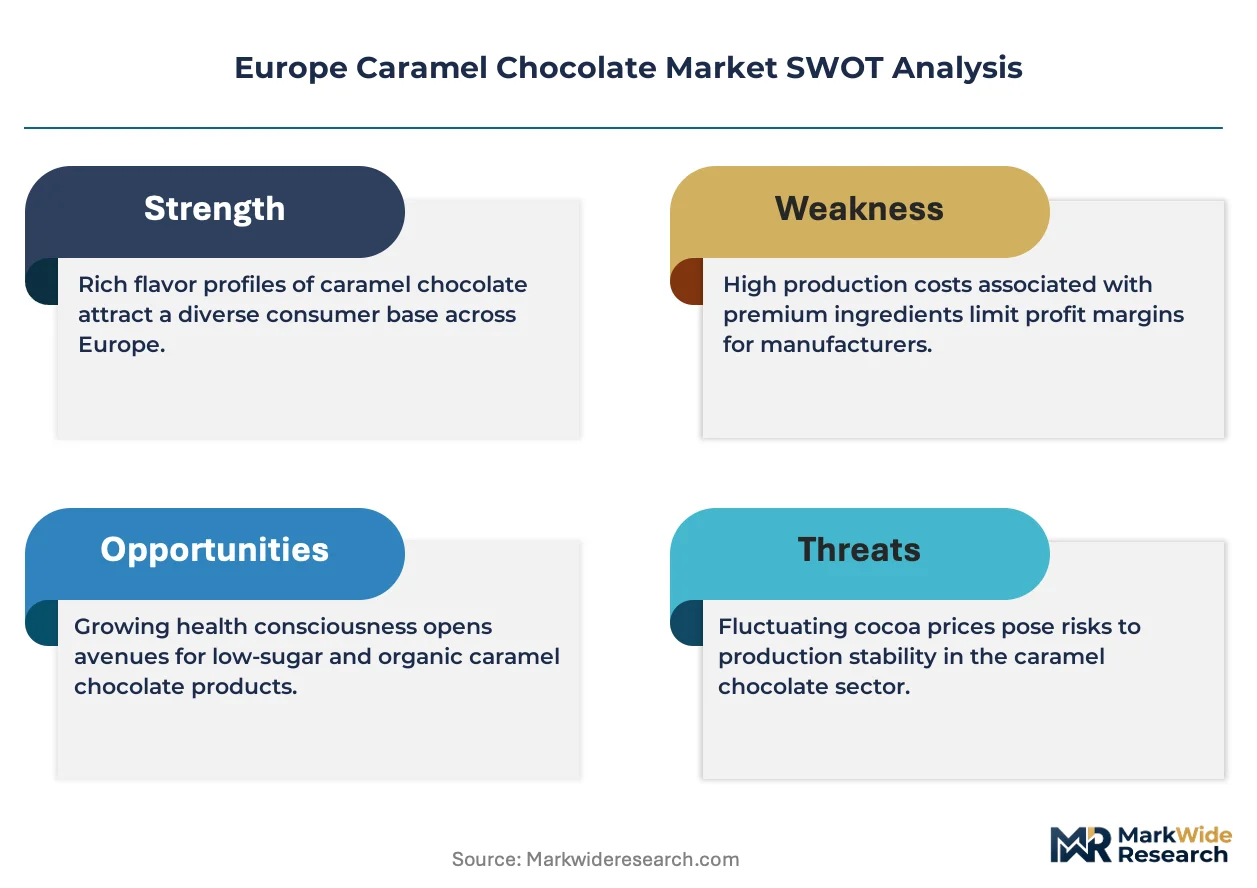
- Cocoa price volatility:Concentrated West African sourcing exposes European processors to weather-driven input cost swings and currency risk.
- Acrylamide thresholds:EFSA mitigation guidelines constrain traditional high-temperature caramelization methods, requiring capital-intensive process reengineering.
- Plant-based substitutes:Oat milk and date-sweetened confections capture health-conscious consumers reducing dairy and refined sugar intake.
Strategic Opportunities
- Romania and Bulgaria:Underdeveloped premium confectionery penetration offers first-mover advantage for direct-to-consumer subscription models targeting urban professionals.
- EU Green Deal alignment:Carbon-neutral production certifications unlock preferential shelf placement and public procurement channels in Scandinavian markets.
- Cold-extraction caramel:Convergence of enzymatic processing and precision fermentation enables lower-temperature flavor development without Maillard reaction risks.
Industry Challenges
- Maillard reaction expertise:Scarcity of food scientists trained in controlled thermal processing complicates workforce scaling for artisanal producers.
- EUDR documentation systems:Farm-level geolocation and chain-of-custody IT infrastructure demands significant capital deployment from mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Caramel Chocolate Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Chocolate, Dark Chocolate, White Chocolate, Ruby Chocolate Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores End User: Children, Young Adults, Adults, Seniors Packaging Type: Bar, Box, Pouch, Bulk |
| Companies Covered | Lindt & Sprüngli AG, Ferrero International SA, Mars Incorporated, Mondelēz International Inc., Nestlé SA, Barry Callebaut AG, August Storck KG, Guylian N.V., Cemoi Chocolatier, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Caramel Chocolate Market Strategic Shifts & Innovations
Precision thermal control technologies and regulatory compliance automation are redefining production economics and competitive differentiation across European caramel chocolate manufacturing.
Enzymatic caramelization systems using amylase and invertase enzymes operate below 80°C to develop color and flavor without acrylamide formation. Premium artisanal producers in Belgium and Switzerland are adopting these systems to meet EFSA guidelines while preserving traditional taste profiles. Batch-scale enzymatic processing is rendering obsolete conventional open-kettle cooking methods in health-positioned product lines.
REACH chemical safety standards now govern migration limits from packaging materials into fatty confectionery matrices. Manufacturers are reformulating wrapper specifications and accelerating transition to paper-based laminates with barrier coatings. Dark chocolate caramel formats with higher cocoa butter content face the most stringent testing protocols and are driving supplier qualification investments.
Direct-to-consumer subscription models bypass traditional wholesale and retail intermediaries, capturing recurring revenue and first-party consumption data. Urban millennials in German metropolitan areas dominate these channels, replacing seasonal gift purchasing with monthly curated assortments. This behavioral pivot concentrates customer acquisition spending on digital platforms rather than trade promotion.
Europe Caramel Chocolate Market Segmentation
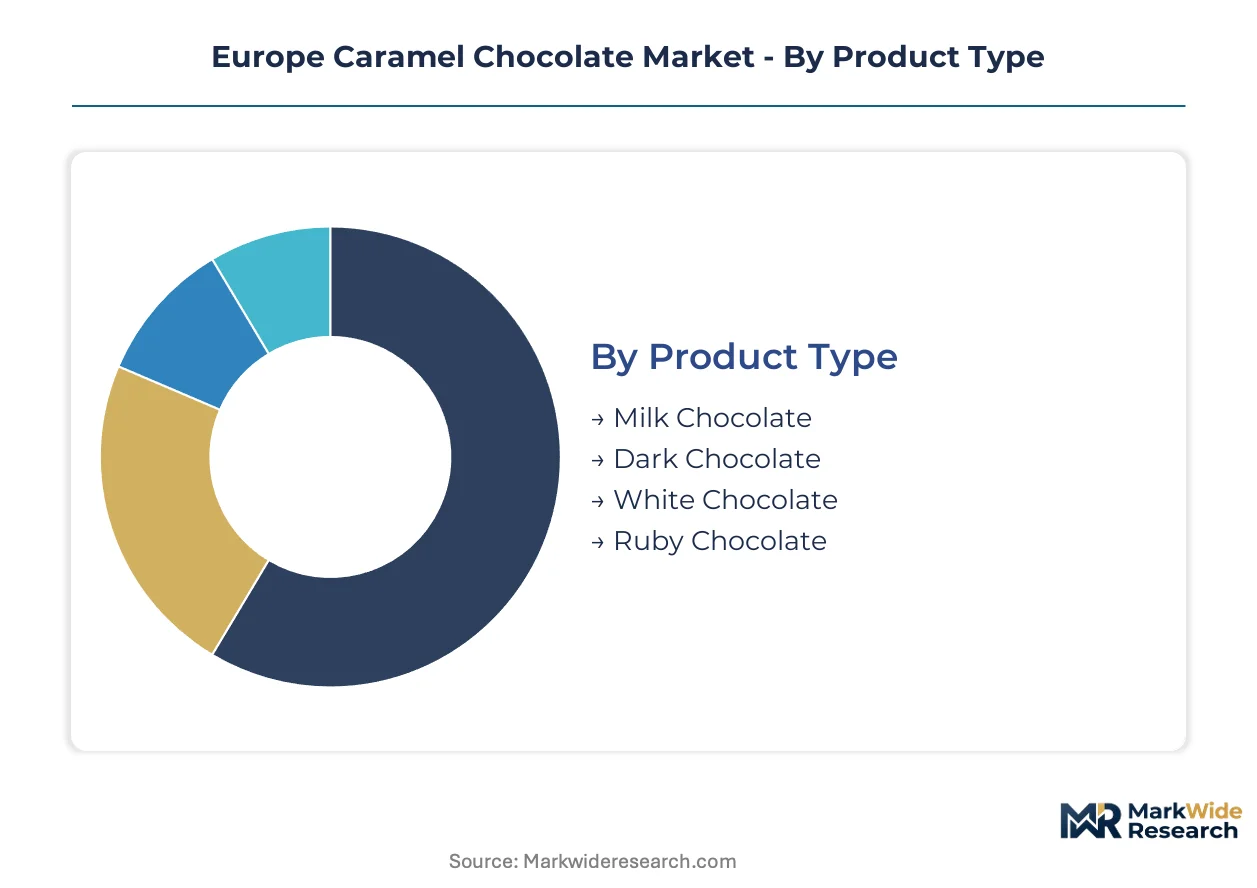
Caramel chocolate segmentation in Europe tracks divergent consumption rhythms across product formats, channel velocities, and demographic cohorts. Understanding these turnover differentials helps manufacturers calibrate production scheduling, inventory positioning, and promotional investment across the region's heterogeneous markets.
Product Type:
Milk chocolate variants turn inventory fastest through impulse channels, while dark chocolate formats rotate more slowly through premium gift occasions. Ruby chocolate, the newest addition, exhibits the most volatile velocity as trial-driven demand fluctuates seasonally.
- Milk Chocolate:Standard formulations with 30-40% cocoa content and high dairy ratios dominate German and French supermarket volumes. Children and family households in these markets drive repeat purchase frequency through everyday snacking occasions.
- Dark Chocolate:Cocoa percentages above 50% with reduced sugar profiles attract health-conscious adults in Belgium and Switzerland. EFSA acrylamide guidelines favor these lower-temperature production methods, aligning regulatory compliance with consumer preference shifts.
- White Chocolate:Cocoa butter-based formulations without cocoa solids serve as carrier for flavored caramel infusions in seasonal assortments.
- Ruby Chocolate:Ruby cocoa bean varieties deliver natural pink coloration and berry notes, capturing novelty-seeking young adults in UK urban centers.
Milk chocolate anchors the volume base while dark chocolate gains share at the steepest rate.
Distribution Channel:
Channel segmentation reveals a cost-tier structure where specialty stores command premium shelf economics and online retailers compress margins through subscription scale. Convenience stores occupy the middle tier with location-driven pricing power.
- Supermarkets:High-velocity self-service formats in Germany and Poland move standard bar formats through promotional cycles. Retailers here negotiate annual listing fees that favor multinational suppliers with broad SKU portfolios.
- Online Retailers:Direct-to-consumer platforms in Amsterdam and Berlin metropolitan areas enable curated subscription boxes with personalized flavor profiles. Data capture capabilities allow manufacturers to bypass traditional wholesale markups and build recurring revenue streams.
- Convenience Stores:Small-format urban locations in France and Italy specialize in single-serve impulse purchases with extended evening hours.
- Specialty Stores:Artisanal chocolatiers in Brussels and Zurich command premium pricing through controlled temperature display cases and staff-guided sampling.
Supermarkets retain the largest transaction volume while online retailers demonstrate the most rapid expansion trajectory.
End User:
Demographic segmentation maps to distinct margin profiles, with young adults accepting price premiums for ethical sourcing credentials that seniors disregard in favor of familiar brands.
- Children:Preference for milk chocolate varieties with character licensing drives seasonal peak demand around school holidays. Parents in Scandinavian markets prioritize EUDR-compliant products, influencing purchase decisions through sustainability framing.
- Young Adults:Experiential consumption in Germany and France favors limited-edition collaborations and Instagram-optimized packaging designs. This cohort substitutes traditional gift-giving with monthly subscription deliveries.
- Adults:Dark chocolate caramel combinations appeal to reduced-sugar dietary preferences in Switzerland and Austria.
- Seniors:Brand loyalty and texture familiarity sustain demand for traditional milk chocolate bar formats in Southern European markets.
Young adults command the highest per-capita spending growth while children provide the most predictable volume foundation.
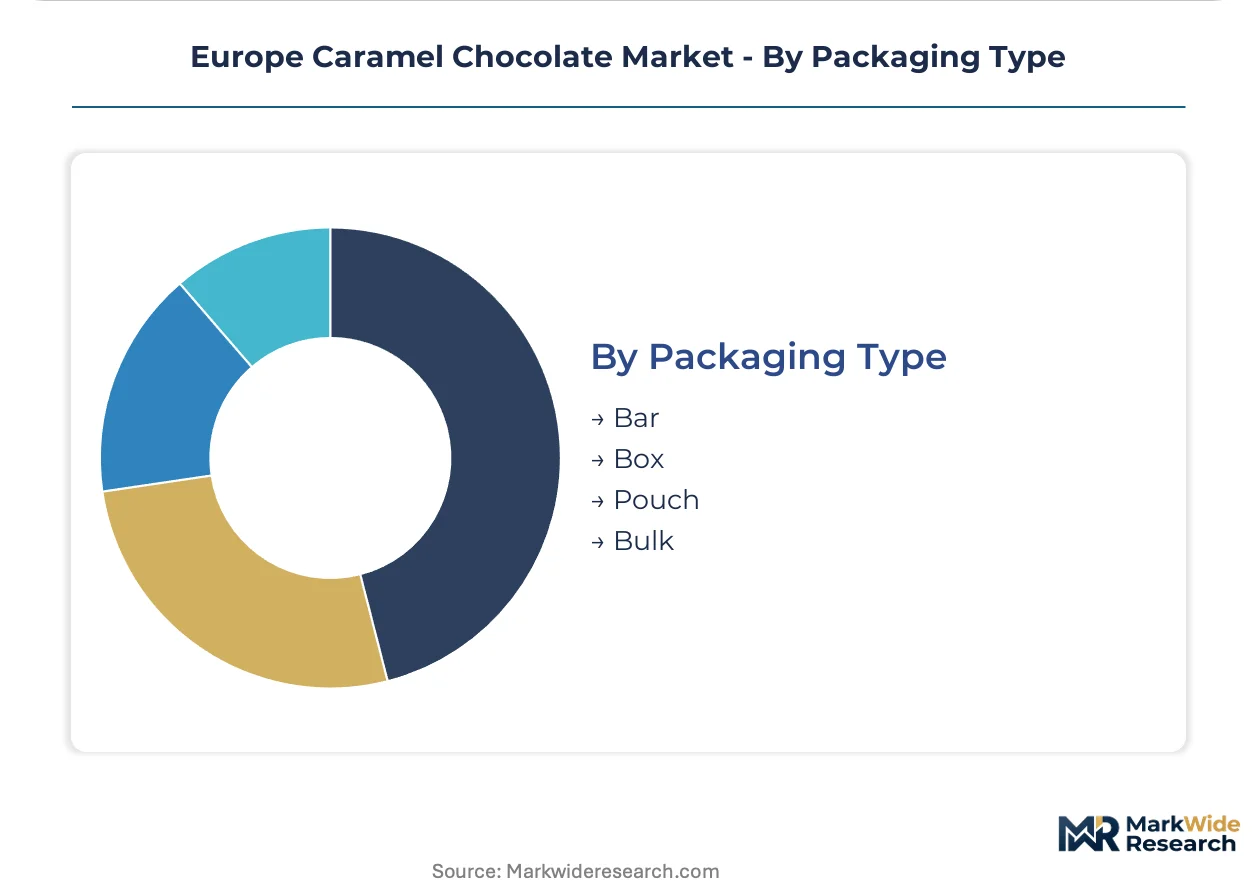
Packaging Type:
Packaging segmentation reflects supply concentration in folding carton production for boxed assortments versus flexible film dominance in pouch formats. REACH migration limits increasingly differentiate material specifications across these formats.
- Bar:Standard 100g wrapped formats utilize aluminum-laminate barriers to prevent fat bloom during temperature fluctuations in Central European distribution.
- Box:Rigid presentation packaging for Belgian praline assortments requires precision-molded PET trays and paperboard outer shells. ECHA compliance costs for adhesive and coating migration testing concentrate production among qualified converters.
- Pouch:Stand-up flexible formats with resealable zippers serve trial-size portions in UK online subscription channels.
- Bulk:Foodservice and ingredient supply to confectionery manufacturers in Italy and Spain utilizes modified atmosphere packaging for extended shelf stability.
Boxed formats capture the highest margin per kilogram while pouch packaging expands most quickly through digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European caramel chocolate trade flows reveal a structural export surplus concentrated in Swiss and Belgian processing clusters, while import dependence for raw cocoa persists through Rotterdam and Hamburg port gateways. Germany absorbs the largest intra-regional shipment volumes, re-exporting finished assortments to Nordic and Eastern European markets.
Germany
Artisanal caramel chocolate traditions in Cologne and Bonn sustain premium consumption frequency unmatched elsewhere in Europe. EUDR compliance deadlines are accelerating farm-level geolocation investments among mid-sized processors. The Cologne-Chocolate Museum industrial corridor anchors specialized Maillard reaction expertise transfer between research institutes and regional manufacturers.
Switzerland
High per-capita spending on dark chocolate caramel formats reflects health-conscious aging demographics in Zurich and Geneva. Swissmedic food safety protocols exceed baseline EFSA requirements, creating regulatory export advantages for compliant producers. The Lake Geneva cluster concentrates precision thermal control equipment manufacturing serving enzymatic caramelization system adopters.
Belgium
Brussels-based praline houses command gift-oriented price premiums through controlled temperature retail display infrastructure. REACH chemical safety enforcement by ECHA drives packaging material migration testing investments among folding carton converters. The Flanders region hosts Europe's densest concentration of specialty cocoa bean roasting and conching facilities.
France
Parisian young adults substitute traditional seasonal gifting with monthly subscription caramel chocolate deliveries. ANSM oversight of food contact materials complements EU-wide ECHA standards for wrapper specification compliance. The Île-de-France region concentrates direct-to-consumer platform development and digital customer acquisition capability.
Poland
Rising disposable incomes in Warsaw and Kraków expand addressable demand for mid-tier boxed assortments previously unavailable in Central Europe. EU Green Deal carbon-neutral production certifications unlock preferential retail shelf placement negotiations with Scandinavian-owned supermarket chains. The Silesian industrial zone attracts contract manufacturing investment from Western European brands seeking labor cost arbitrage.
Europe Caramel Chocolate Market Key Industry Players
On the supply side, the industry is consolidating around industrial chocolate platforms and premium in-house production capabilities, with mid-tier processors facing margin compression from compliance cost escalation. Three strategic archetypes dominate: integrated cocoa processors with private-label supply scale, heritage premium houses with controlled manufacturing traditions, and asset-light niche brands leveraging contract manufacturing for rapid geographic expansion. Competitive moves concentrate on EUDR-compliant supply chain restructuring and enzymatic process technology licensing to mitigate acrylamide exposure.
Within the industrial supply tier, Barry Callebaut AG and Mondelēz International Inc. exemplify divergent scale strategies, with the former anchoring private-label formulation supply across multiple countries and the latter sustaining volume competitiveness through established Central and Eastern European distribution networks. Ferrero International SA occupies a premium positioning archetype through tightly controlled in-house production of hazelnut-caramel blends, representing heritage manufacturing continuity against contract manufacturing trends.
| Leading Market Players |
|---|
| Lindt & Sprüngli AG |
| Ferrero International SA |
| Mars Incorporated |
| Mondelēz International Inc. |
| Nestlé SA |
| Barry Callebaut AG |
| August Storck KG |
| Guylian N.V. |
| Cemoi Chocolatier |
| Others |
Cost & Logistics Intelligence
The Cologne-Chocolate Museum industrial corridor anchors European caramel chocolate production capacity, concentrating Maillard reaction expertise that translates into pricing power for artisanal processors serving German and Swiss premium channels. EUDR compliance investments are restructuring procurement economics, with traceability costs compressing mid-tier margins while certified producers capture shelf placement premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in European caramel chocolate. Price differentiation separates EUDR-certified artisanal assortments from private-label supermarket formats and bulk ingredient supply. Pricing pressure stems from cocoa price volatility and enzymatic process capital requirements, with mid-tier boxed assortments experiencing the tightest margin compression. Supermarket procurement teams exhibit highest price sensitivity, while specialty store buyers prioritize provenance credentials over unit cost.
Supply Chain Analysis
Extended payment terms from Swiss and Belgian processors are reshaping supplier-financing dynamics across West African cocoa sourcing networks. Supply concentrates in Côte d'Ivoire, Ghana, and Cameroon for bean procurement, with European refining clustered in Belgium, Switzerland, and Germany. Raw material dependencies span cocoa butter, dairy powders, and natural vanilla extracts. Single-source vulnerability in West African bean supply creates structural risk exposure. Distribution runs through Rotterdam and Hamburg port gateways into Central and Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European caramel chocolate is evolving into a service-attach opportunity where direct-to-consumer subscription platforms generate recurring revenue streams growing faster than conventional wholesale volume. Personalized flavor curation and replenishment automation are expanding customer lifetime value beyond transactional bar and box sales.
For Market Incumbents: Harden EUDR-compliant farm-level partnerships to defend against mid-tier private-label encroachment. Deepen enzymatic caramelization capabilities through precision thermal control equipment licensing. Channel control through captive specialty retail networks in Brussels and Zurich preserves margin architecture against subscription-model disruption.
For New Entrants and Emerging Players: Pursue underdeveloped premium penetration in Romanian and Bulgarian urban markets where Western retail formats are expanding. Direct-to-consumer subscription models targeting Warsaw and Kraków professionals offer lowest competitive density. Carbon-neutral production certification unlocks preferential Scandinavian supermarket negotiations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer platforms with first-party data capabilities and subscription retention above industry benchmarks. Long-term viability favors asset-light brands with contract manufacturing relationships and EUDR-compliant supply chain documentation already deployed. Monitor EFSA acrylamide threshold revisions as inflection indicator for process technology replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Supply Chain Certification | Farm-level geolocation systems satisfy Brussels compliance deadlines and unlock premium shelf placement. |
| Enzymatic Caramelization Adoption | Precision fermentation partnerships with Swiss equipment manufacturers mitigate EFSA acrylamide exposure. |
| Direct-to-Consumer Platform Launch | Bypassing wholesale markups in Amsterdam and Berlin captures recurring revenue and consumption data. |
| Carbon-Neutral Production Certification | EU Green Deal alignment secures preferential negotiations with Scandinavian-owned supermarket chains. |
| Contract Manufacturing Expansion | Asset-light scaling through Silesian zone partnerships reduces capital intensity for geographic expansion. |
Research Approach
Initial hypotheses were tested against primary input from caramel chocolate brand managers, specialty store buyers, cocoa procurement leads, and EUDR compliance officers and refined through secondary validation. Primary fieldwork encompassed processors in Cologne, Brussels, and Zurich alongside retail channel partners in Warsaw and Bucharest. Secondary sources included EFSA guidance documents, ECHA REACH substance databases, EU customs trade records, and Nielsen retail audit data for confectionery categories. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Demand-supply balance dynamics shaped the analytical framework, with segmentation modeled across product type, distribution channel, end-user demographic, and packaging format dimensions. CAGRs were derived from volume trajectory analysis calibrated to pricing elasticity parameters. Forecast inputs incorporated EUDR enforcement timeline scenarios and enzymatic process adoption curves for acrylamide mitigation.
Macroeconomic conditions sit as an overlay; deviation in cocoa commodity prices, euro exchange rates, or West African harvest yields would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Premium Chocolate Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
China Chocolate Market
Confectionery
Low Calorie Hard Candy Market
Confectionery
Ice Cream Coating Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Europe Compound Chocolate Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Truffle Chocolate Market
Confectionery
Saudi Arabia Chocolate Market
Confectionery
Vegan Gummy Candy Market
Confectionery
UK Compound Chocolate Market
Confectionery
Liquorice Shellac Market
Confectionery
Sugar Confectionery Market
Confectionery
Gum Base Candy Market