
 Structural Wood Screws Market | 2026-2036
Structural Wood Screws Market Size, Share, and Industry Trends Forecast 2026-2036
Structural Wood Screws Market Intelligence
A persistent shortage of skilled carpenters and jobsite labor is redrawing the value proposition for engineered fasteners. This shift benefits manufacturers producing high-performance screws that reduce installation time and skill requirements. Simpson Strong-Tie leverages its deep integration with structural engineers and building code bodies. Meanwhile, Würth sustains its market position through an extensive direct sales network targeting professional contractors across Europe and North America.
Structural wood screws are hardened fasteners engineered to handle specific shear and withdrawal loads in wood construction. They often feature specialized thread geometries and polymer coatings, designed to replace traditional lag bolts in load-bearing applications. Self-tapping screws represent the fastest-growing product type, driven by efficiency gains in both construction and furniture assembly. Coated steel remains the dominant material choice, offering a superior balance of strength and corrosion resistance for most building projects.
Product specifications are shaped by stringent building codes and standards. In the United States, ICC-ES acceptance criteria define performance requirements, while in Europe, CE marking under the Construction Products Regulation is mandatory for market access. These regulations enforce minimum load-bearing capacities and corrosion resistance. The primary challenge for manufacturers is to innovate on material and coating technologies to meet evolving structural demands without compromising affordability.
Market Dynamics
The push for greater construction site productivity, driven by a persistent shortage of skilled labor, is the central force shaping the market. This elevates the value proposition for engineered fasteners that reduce installation complexity and assembly time on job sites.
Growth Catalysts
- Mass Timber Construction:The adoption of engineered wood like CLT requires high-strength fasteners for structural assembly, creating a primary demand category.
- Building Code Evolution:Revisions to standards like the ICC-ES in the U.S. formally approve engineered screws, displacing traditional methods in structural applications.
- Prefabrication Growth:The rise of modular construction in markets like Germany prizes the speed and consistency afforded by high-performance, self-tapping screws.
Market Restraints
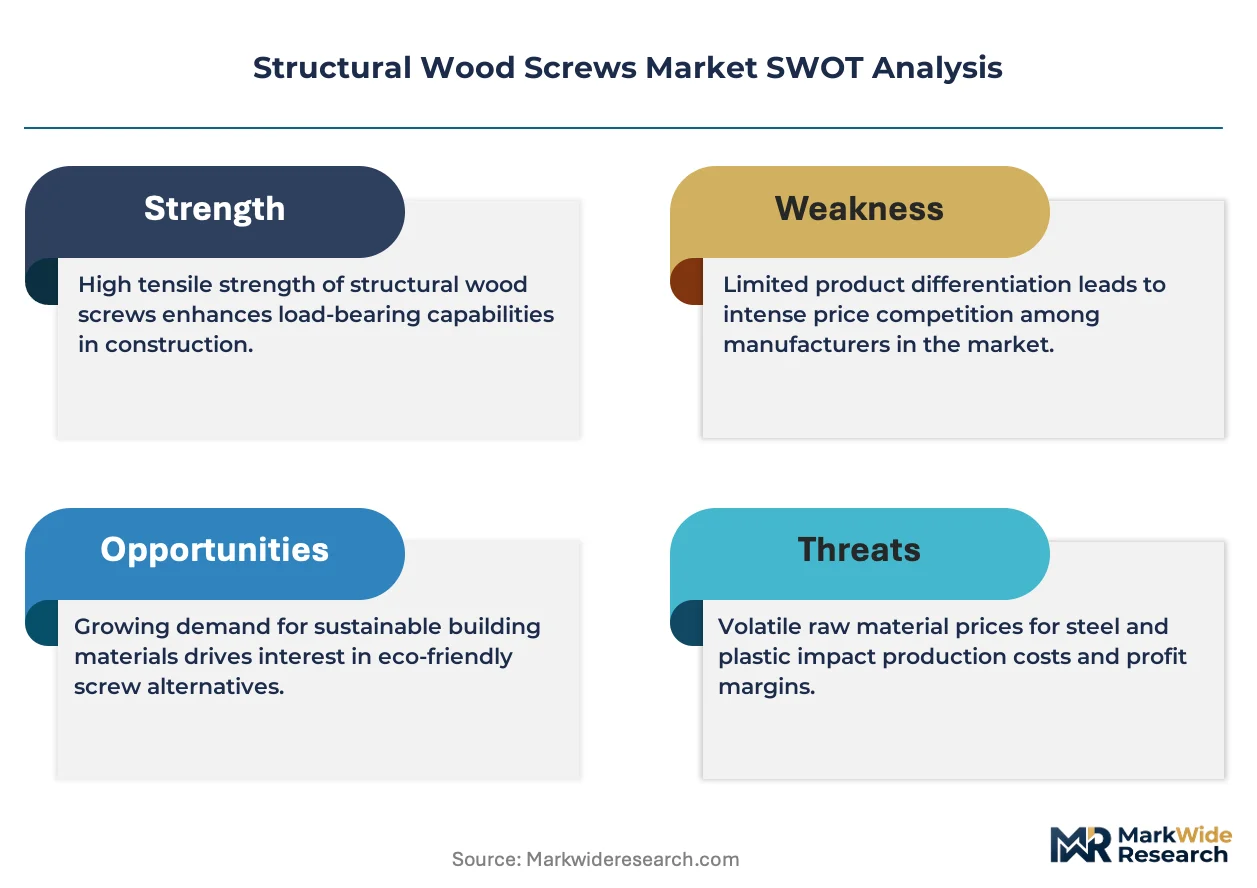
- Input Cost Volatility:Price fluctuations for high-grade steel and polymer coatings directly impact manufacturer margins and product affordability.
- Legacy Fastener Substitution:In non-critical applications, lower-cost traditional lag bolts and nails remain a significant competitive threat to engineered screws.
- Burdensome Certification:The lengthy process to achieve mandatory approvals like CE marking in Europe deters new product innovation and market entry.
Strategic Opportunities
- Seismic Retrofitting:Specialized screws for reinforcing existing timber structures in earthquake-prone regions represent a new application segment.
- Emerging Market Entry:Untapped demand exists in regions like Latin America, where wood construction is expanding but advanced fastener adoption is nascent.
- Smart Fastener Development:Integrating sensors into screws for structural health monitoring in mass timber buildings is a key technological opportunity.
Industry Challenges
- Contractor Education Gap:A primary challenge is training the construction workforce on the specific installation requirements and structural benefits of engineered screws versus traditional fasteners.
- Regulatory Compliance Overhead:Manufacturers face the operational burden of continuously tracking and adapting to evolving building codes and standards across different national and regional markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structural Wood Screws Market |
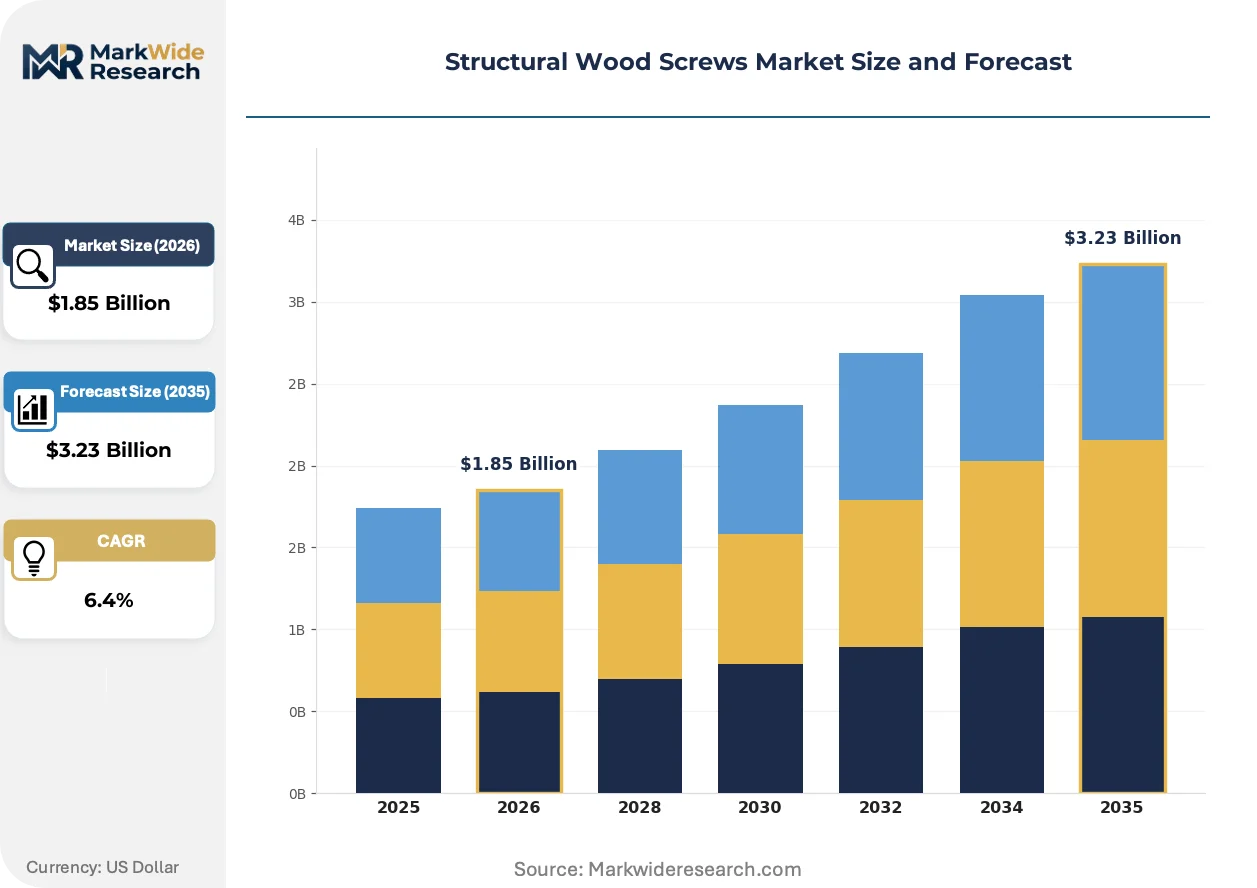
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Screws, Self-Tapping Screws, Deck Screws, Lag Screws Material: Steel, Stainless Steel, Brass, Composite Coating Type: Galvanized, Zinc-Plated, Phosphate, Polymer Application: Construction, Furniture Assembly, Decking, Cabinet Making |
| Companies Covered | Fastenal, Hilti, Simpson Strong-Tie, SPAX, Würth, GRK Fasteners, SFS Group, ITW, Grip-Rite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structural Wood Screws Market Strategic Shifts & Innovations
Material science advancements and a construction industry pivot towards off-site manufacturing are fundamentally altering fastener requirements. These shifts demand components that offer documented performance, higher installation efficiency, and compatibility with engineered wood products.
Advanced thread geometries and polymer coatings reduce driving torque and increase withdrawal resistance. Prefabricated housing and mass timber constructors are rapidly adopting these self-tapping screws for efficiency. This specialization in screw design for specific wood types and applications is fragmenting the once-monolithic lag screw category into numerous high-performance niches.
Europe’s Construction Products Regulation mandates CE marking for structural fasteners, requiring declared performance based on harmonized standards. This forces a focus on documented load-bearing capacity and corrosion resistance. The coated steel segment is most affected, with suppliers investing in extensive testing and documentation to secure market access across the European Union.
A shift is occurring in how contractors source fasteners, moving from generic bulk buys to specification-driven procurement. This model disrupts traditional distributors by favoring manufacturers who provide detailed engineering data directly to architects. This behavior is most visible in North American commercial construction, especially for large-scale mass timber projects.
Structural Wood Screws Market Segmentation
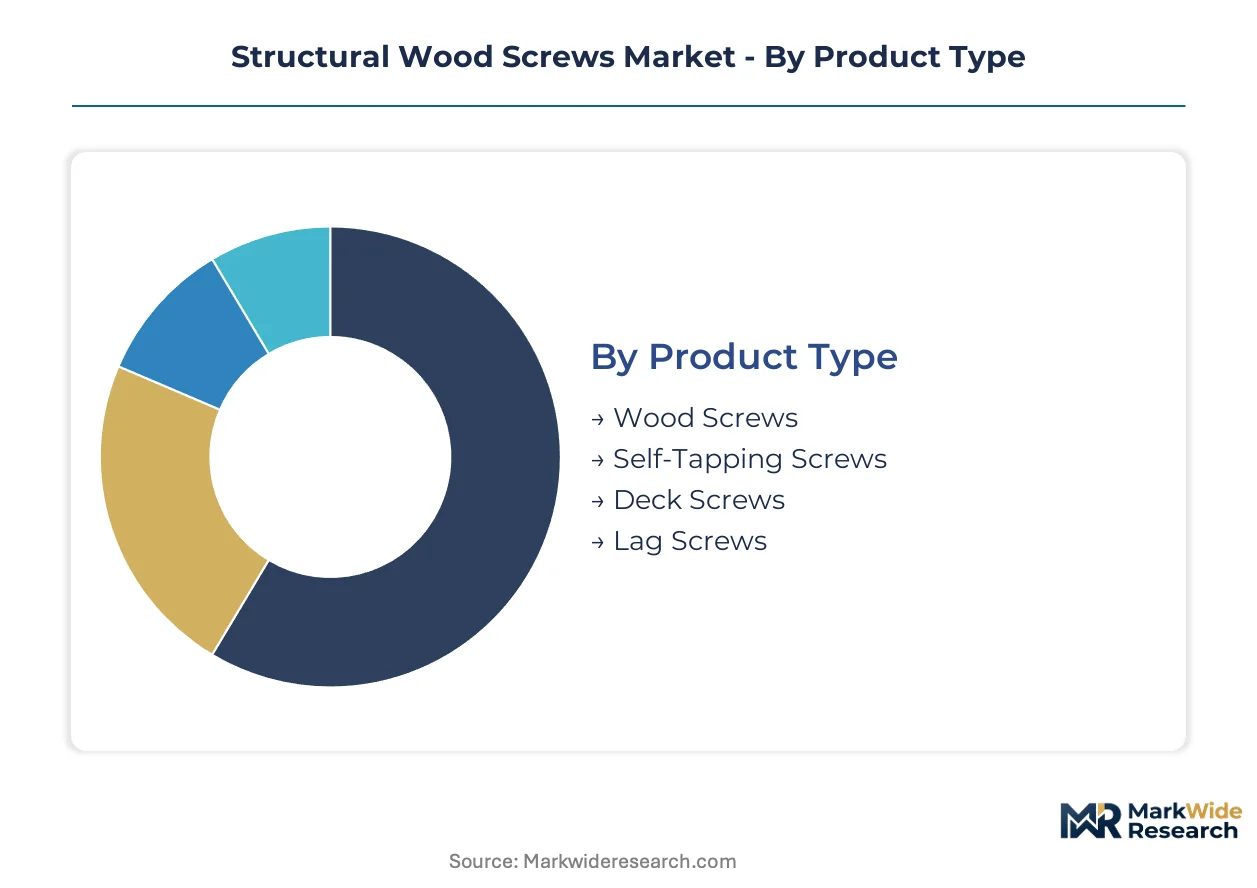
The structural wood screws market is highly differentiated by technical specifications and application requirements, necessitating a granular segmentation to understand demand drivers. Each segment reflects distinct performance criteria, material compositions, and regulatory compliance pathways.
Product Type:
Product type differentiation in structural wood screws is heavily influenced by regional building codes and acceptance criteria, which dictate performance requirements for load-bearing applications.
- Self-Tapping Screws:These fasteners incorporate a specialized tip that cuts its own thread, often eliminating pre-drilling in many wood species. Demand concentrates in Germany and the United States, driven by prefabrication and modular construction efficiency.
- Lag Screws:Traditional lag screws are heavy-duty fasteners requiring pre-drilled pilot holes, typically used in high-load structural connections. Demand remains significant in developing markets where cost-effectiveness often outweighs installation speed.
- Wood Screws:These general-purpose fasteners feature tapered shanks and coarser threads, primarily for joining wood components in non-structural contexts.
- Deck Screws:Designed for exterior use, deck screws typically feature corrosion-resistant coatings and specific thread patterns for securing decking boards.
Lag Screws handle the majority of throughput in non-engineered timber applications; Self-Tapping Screws are the fastest mover on share.
Material:
Material selection for structural wood screws often balances cost considerations against the required strength, durability, and corrosion resistance for specific project environments.
- Steel:Carbon steel forms the core of most structural wood screws, providing high tensile strength and load-bearing capacity when properly hardened. Demand is concentrated in general construction across North America and Europe, valued for its balance of performance and affordability.
- Stainless Steel:Offering superior corrosion resistance, stainless steel screws are crucial for exterior applications or environments with high moisture and chemical exposure. North American coastal construction and marine applications drive significant demand for these specialized fasteners.
- Composite:Composite screws integrate advanced polymers and fibers, offering lightweight solutions with specific insulation or non-conductive properties for niche applications.
- Brass:Brass screws are primarily used in decorative or non-structural applications where aesthetics and corrosion resistance are prioritized over sheer strength.
Performance-driven decisions often favor Stainless Steel for critical applications, while Steel remains the dominant choice for overall cost-efficiency in general construction.
Coating Type:
Coating types are selected based on the fastener's intended environment and the level of corrosion protection required, directly impacting longevity and structural integrity.
- Polymer:Polymer coatings provide enhanced corrosion resistance, reduced driving torque, and sometimes color-coding for specific applications or wood types. Mass timber construction in Germany and the United States increasingly specifies these advanced coatings for efficiency and durability.
- Galvanized:Hot-dip galvanized coatings offer a thick layer of zinc, providing robust corrosion protection suitable for outdoor and treated wood applications. Demand remains strong in heavy outdoor construction projects across Europe and North America.
- Zinc-Plated:Zinc-plated coatings offer basic corrosion resistance for interior or sheltered applications, serving as a cost-effective solution for many general-purpose screws.
- Phosphate:Phosphate coatings provide a dark, matte finish that offers moderate corrosion resistance and improves paint adhesion for interior applications.
Regulatory compliance for outdoor use drives demand for Galvanized coatings, while performance demands in engineered wood are increasingly shifting towards Polymer solutions.
Application:
Application segments for structural wood screws are defined by the specific construction methodology and the structural demands placed on the assembled wood components.
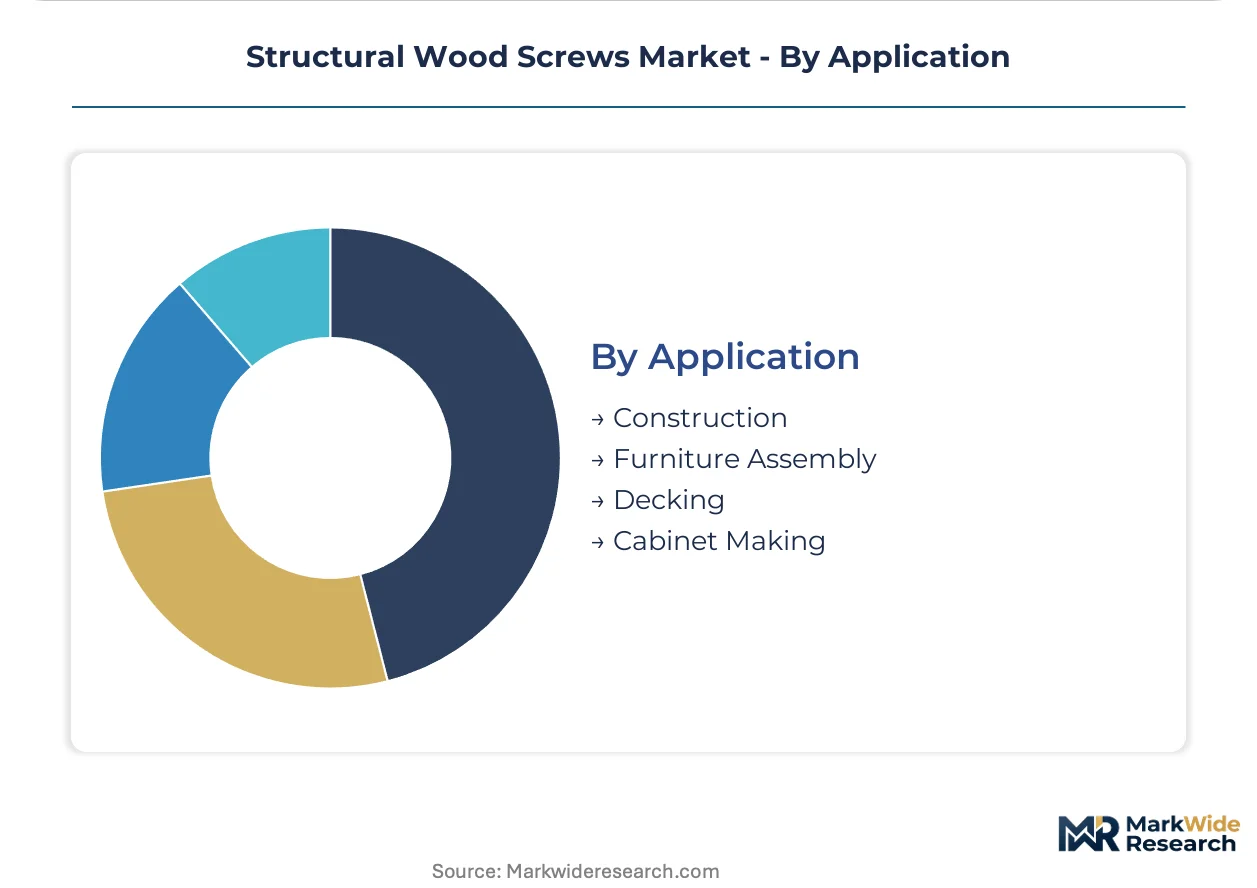
- Construction:This broad segment encompasses all structural and non-structural uses in residential, commercial, and industrial building projects. The adoption of mass timber and prefabrication methods in Germany and the United States significantly drives demand for high-performance screws.
- Furniture Assembly:Fasteners in furniture assembly prioritize ease of use, aesthetic integration, and sufficient holding power for non-load-bearing connections. European furniture manufacturers increasingly utilize specialized screws for efficient, high-volume production.
- Decking:Decking applications require fasteners with high corrosion resistance and strong withdrawal resistance to secure exterior timber boards against weathering and foot traffic.
- Cabinet Making:Cabinet making utilizes screws for joining panels, securing hardware, and constructing internal structures, emphasizing precise fit and minimal visual impact.
The Construction segment accounts for the highest volume consumption, while Furniture Assembly demonstrates consistent innovation in specialized fastener design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CE marking under the Construction Products Regulation anchors the European structural wood screws market, influencing product specifications and market access. Demand is concentrating in countries with advanced construction practices and a growing emphasis on engineered wood solutions. These regions demonstrate strong adoption of innovative fastening technologies.
Germany
Germany's demand for structural wood screws stems from its leadership in mass timber construction and advanced prefabrication techniques. CE marking under the Construction Products Regulation ensures product compliance for these applications. The Bavarian region, with its strong manufacturing base, drives innovation in engineered fastening solutions.
United States
United States construction projects increasingly adopt engineered wood products and modular building methods, driving demand for high-performance fasteners. ICC-ES acceptance criteria define the performance requirements for structural screws in these applications. The Pacific Northwest, a hub for sustainable timber construction, demonstrates strong adoption.
Canada
Canadian building initiatives prioritize sustainable construction and engineered wood, boosting demand for specialized structural screws. The National Building Code of Canada (NBCC) provides guidelines for timber structures, impacting fastener specifications. British Columbia, with its robust forestry sector, leads in mass timber innovation.
Japan
Japanese construction focuses on seismic retrofitting and expanding wood construction, creating specific demand for advanced fasteners. JIS standards for construction materials ensure quality and safety in these applications. The Tokyo metropolitan area, with its dense urban development, sees high demand for disaster-resistant building solutions.
Structural Wood Screws Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the structural wood screws market. These dominant firms often provide comprehensive fastening systems, while numerous niche players focus on specific application areas. Strategic archetypes include those specializing in high-performance engineered fasteners and others maintaining extensive direct sales networks. Geographic expansion and continuous material innovation represent dominant competitive moves.
Specialists in high-performance fasteners like Simpson Strong-Tie and Würth occupy a strong market position, leveraging deep integration with industry standards and extensive distribution. SPAX, a German-based manufacturer, represents another key player, emphasizing innovative thread geometries and polymer coatings for European and North American markets.
| Leading Market Players |
|---|
| Fastenal |
| Hilti |
| Simpson Strong-Tie |
| SPAX |
| Würth |
| GRK Fasteners |
| SFS Group |
| ITW |
| Grip-Rite |
| Others |
Cost & Logistics Intelligence
The displacement of traditional lag bolts by high-performance self-tapping screws reshapes both the supply geography and pricing economics for structural wood fasteners. This shift prioritizes specialized manufacturing capabilities over commodity production.
Pricing Analysis
Price disparities for structural wood screws emerge across geographic markets, reflecting varied regulatory requirements and construction practices. A hybrid pricing model prevails, combining value-based contracts for engineered fasteners with transactional sales for general-purpose types. Price differentiation stems from certification level, such as ICC-ES acceptance, and specialized polymer coatings. Margins are tightening due to input cost volatility for high-grade steel and advanced coatings. Buyers in non-critical applications exhibit high price sensitivity, while mass timber developers prioritize performance over cost.
Supply Chain Analysis
Volatility in global steel markets presents a significant chokepoint for structural wood screw manufacturers, impacting input costs. Supply chain concentration for finished goods centers in Germany and the United States, with raw material processing often drawing from China. The industry relies heavily on high-grade steel and specialized polymer coatings. Commodity price volatility for these inputs poses a structural risk to manufacturer margins. Distribution runs through a dual model, combining extensive direct sales networks with specification-driven procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The structural wood screws market presents a fragmentation opportunity, driven by the shift towards mass timber construction demanding specialized, high-performance fasteners. This creates distinct niches for innovation and tailored solutions.
For Market Incumbents:Consolidate market share by deepening integration with structural engineers and building code bodies, reinforcing a specification-driven market. Expand direct sales networks to counter legacy fastener substitution in non-critical segments. Invest in certification processes like CE marking to ensure regulatory compliance and differentiate high-performance products. Develop advanced polymer coatings to meet evolving structural demands without compromising affordability.
For New Entrants and Emerging Players:The contractor education gap represents a significant service-layer opportunity where incumbents under-serve. Target specialized niches like seismic retrofitting or smart fastener development for structural health monitoring. Penetrate nascent markets such as Latin America, where advanced fastener adoption is low. Provide comprehensive training and engineering support to differentiate offerings and build trust with the construction workforce.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors specialized manufacturers with strong intellectual property in fastener design and materials. Long-term viability remains strong over the next 5-10 years, driven by mass timber adoption and prefabrication trends. Target acquisition profiles should focus on high-performance fastener specialists with robust R&D capabilities and established regulatory acceptance. The signal to watch is the continuous evolution of building codes, particularly ICC-ES and CE marking, which dictates performance standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Manufacturing Capacity | Supports growing demand for high-performance screws in mass timber construction. |
| Invest in Advanced Material R&D | Develops polymer coatings and steel alloys for superior strength and corrosion resistance. |
| Strengthen Regulatory Affairs | Ensures compliance with evolving building codes like ICC-ES and CE marking for market access. |
| Pilot Smart Fastener Technologies | Explores integrating sensors for structural health monitoring in engineered wood buildings. |
| Develop Contractor Training Programs | Addresses the education gap regarding engineered screw installation and structural benefits. |
Research Approach
Cross-validation between primary interviews and extensive secondary research anchors the qualitative findings and quantitative projections for this study. Primary data collection involved conversations with structural engineers, building code officials, mass timber contractors, and fastener manufacturers. Secondary validation drew from ICC-ES reports, CE marking documentation, construction industry association publications, and academic studies on engineered wood. This approach ensured robust bottom-up and top-down triangulation.
Sensitivity analysis informed the development of the forecast framework across the analysis window, evaluating multiple market scenarios. The study modeled segmentation dimensions including product type, material, coating type, application, and regional regulatory frameworks. Compound annual growth rates were derived by analyzing historical growth trends and projecting future demand drivers. Key industry-specific inputs included mass timber adoption rates and skilled labor availability in construction.
Forecasts assume regulatory continuity in key regimes like the EU Construction Products Regulation and US ICC-ES criteria; material policy shifts would require re-modeling. The projections reflect current assumptions regarding input cost volatility and global economic stability. Practitioners should keep alternative scenarios live as these macroeconomic and regulatory conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Adjustable Gripping Hand Tools Market
Tools
Industrial Cleaning Equipment Market
Tools
Global Table Saws Market
Tools
Global Cordless Power Tools Market
Tools
Global Construction Camera Market
Tools
Gear Honing Machines Market
Tools
Pneumatic Marking Machines Market
Tools
Extensometer Market
Tools
Floor Saw Market
Tools
Bearing Installation Tool Kit Market
Tools
US Chalk Reel and Line Market
Tools
Stationary Wood Planer Market
Tools
Oxy-Fuel Torches Market
Tools
Edge Bending Machine Market
Tools
Tool Setting Gauges Market
Tools
Bar Clamp Market