
 Global Table Saws Market | 2026-2036
Global Table Saws Market Size, Share, and Industry Trends Forecast 2026-2036
Global Table Saws Market Outlook
Specialty woodworking retail is tilting toward direct-to-contractor fulfillment models as professional buyers prioritize specification support over shelf availability. Bosch leverages its European service network to sustain aftermarket parts revenue. Makita competes through battery-platform interoperability across its portable table saw line. Stanley Black & Decker anchors North American mass-market distribution with contractor-grade positioning at price-accessible tiers.
A table saw is a stationary or semi-portable cutting machine employing a circular blade mounted on an arbor, driven by electric motors ranging from 1.5 to 5 horsepower, designed to rip or crosscut lumber and sheet goods with precision fences and miter gauges. The machine serves furniture manufacturing, finish carpentry, and structural framing operations where dimensional accuracy determines assembly fit. Cabinet saws occupy the premium tier with cast-iron trunnions and three-phase power options that command margin pools among industrial users. Portable electric models represent the fastest-expanding technology pairing as cordless lithium-ion platforms displace corded jobsite equipment. Hybrid configurations are gaining share among serious woodworking shops seeking cabinet-grade accuracy without full industrial electrical requirements.
FCC electromagnetic emissions standards govern variable-frequency drive controllers in electronically stabilized models sold in the United States. OSHA machine guarding regulations mandate riving knives and blade covers on workplace installations, directly shaping product design for contractor and cabinet categories. The EU Machinery Directive and CE marking requirements enforce emergency stop functionality and noise emission thresholds for European market access. Stakeholders must monitor evolving silica dust exposure limits from EPA and OSHA, as integrated dust collection ports become a specification differentiator rather than an accessory option.
Market Dynamics
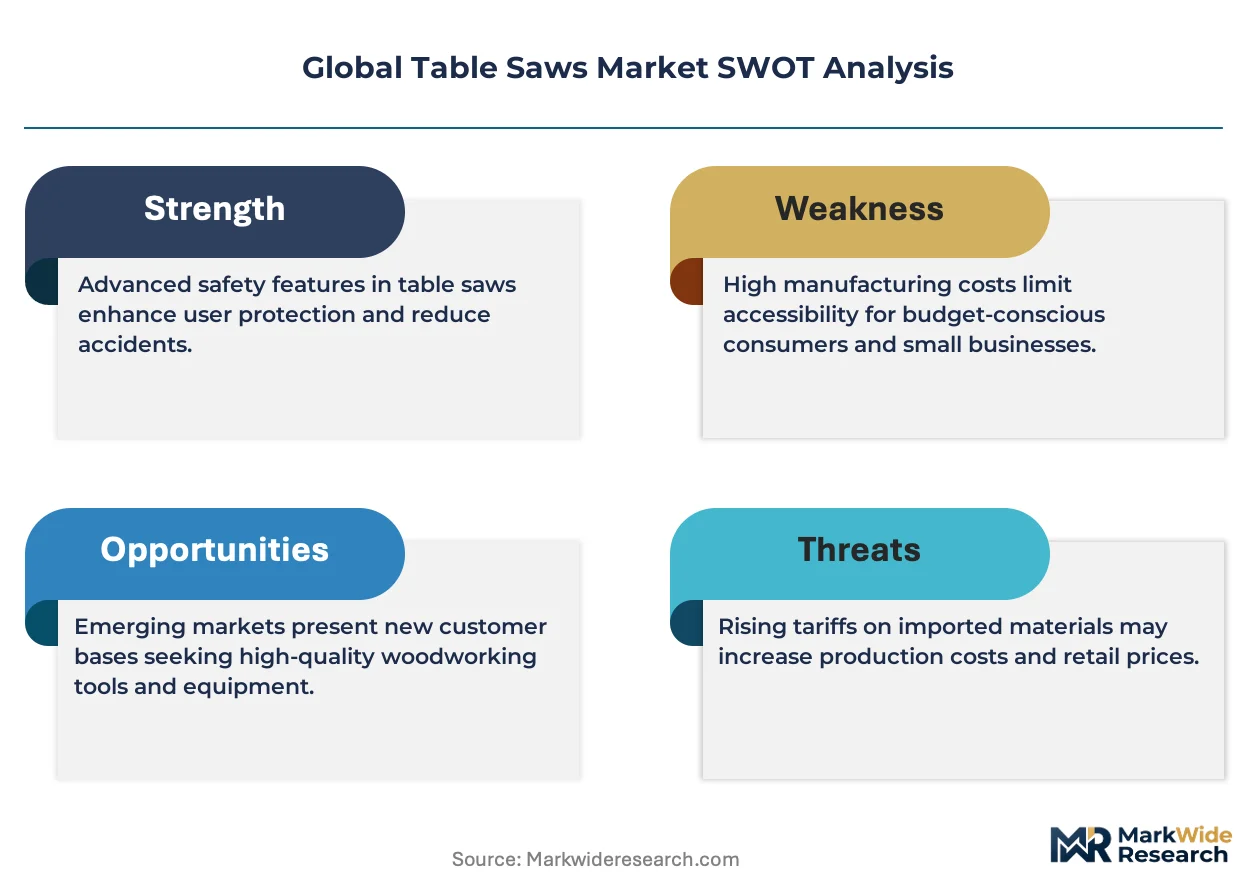
OSHA workplace safety directives and SawStop's flesh-sensing technology are compressing specification standards across contractor and cabinet saw categories, forcing incumbent manufacturers to absorb royalty costs or exit premium segments.
Growth Catalysts
- Residential Construction Surge:Single-family housing starts in the United States and Germany are amplifying procurement of contractor-grade table saws for framing and finish carpentry crews.
- OSHA Machine Guarding Mandates:Workplace safety regulations mandating riving knives and blade covers are accelerating replacement cycles among commercial woodworking shops.
- Cordless Lithium-Ion Platforms:Battery interoperability across portable power tool ecosystems is virtualizing jobsite equipment preferences away from corded models.
Market Restraints
- Cast-Iron Input Volatility:Foundry capacity concentration in China and India exposes cabinet saw manufacturers to freight cost spikes and alloy price swings.
- Flesh-Sensing Patent Licensing:SawStop's proprietary brake cartridge technology creates royalty burdens that compress margins for mid-tier producers lacking vertical integration.
- Three-Phase Power Infrastructure:Industrial electrical requirements for premium cabinet saws limit addressable market penetration in residential workshops and small commercial facilities.
Strategic Opportunities
- India Woodworking SME Expansion:The country's furniture manufacturing cluster around Jodhpur and Pune remains underpenetrated by precision saw equipment relative to manual tooling prevalence.
- Silica Dust Collection Integration:EPA and OSHA exposure limit tightening positions integrated dust ports as specification differentiators rather than accessory add-ons.
- Hybrid Saw Configuration Demand:Serious woodworking shops seek cabinet-grade fence accuracy without industrial electrical requirements, opening mid-premium price tiers.
Industry Challenges
- Calibration Technician Scarcity:Precision fence alignment and trunnion setup require specialized skills that vocational programs in Germany and the United States are failing to replenish at replacement rates.
- CE Marking Compliance Timelines:EU Machinery Directive emergency stop and noise emission testing extends product launch cycles by 8-14 months for non-European manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Table Saws Market |
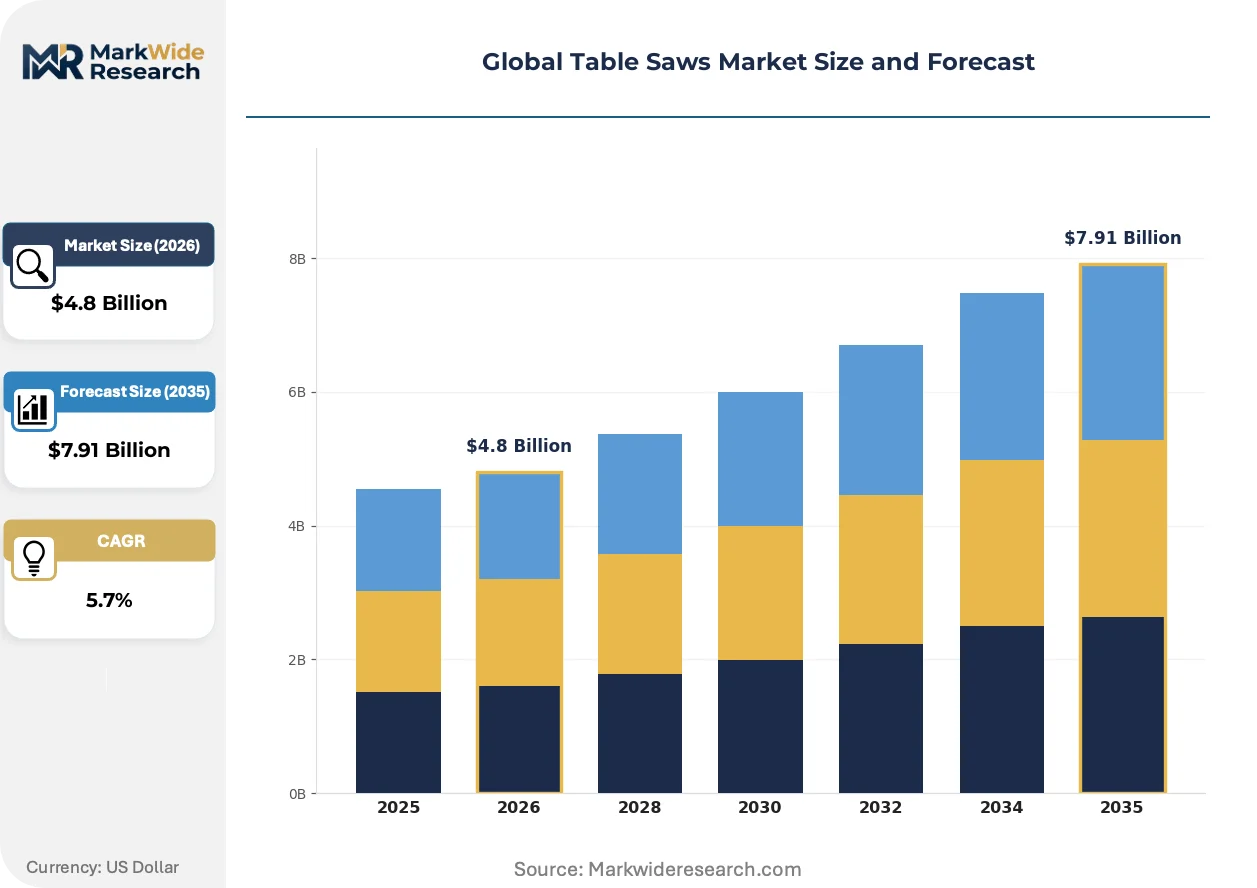
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contractor, Cabinet, Hybrid, Portable Technology: Electric, Diesel, Pneumatic, Hydraulic End User: Woodworking Shops, Construction, DIY Enthusiasts, Manufacturing Size: Compact, Standard, Large, Heavy-Duty |
| Companies Covered | Stanley Black & Decker, Bosch, Makita, Felder Group, SawStop, SCM Group, Altendorf, Powermatic, Techtronic Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Table Saws Market Strategic Shifts
Digital control interfaces and connectivity modules are penetrating table saw architectures, shifting competitive differentiation from mechanical precision to data-enabled workflow integration.
Brushless DC motor controllers with variable-frequency drive stabilization are virtualizing blade speed management for load-compensated cutting through dense hardwoods and engineered composites. High-end furniture manufacturers in Italy and Denmark are specifying these electronically stabilized models for batch consistency. The technology is virtualizing traditional mechanical governor systems into software-defined performance envelopes that reduce thermal stress and extend motor service intervals.
REACH substance restrictions on chromium plating and solvent-based coatings are forcing European manufacturers to reformulate table surface finishes and blade guard materials. The regulation compresses supplier qualification timelines and elevates compliance documentation burdens. Cabinet saw producers serving German and French markets are accelerating powder-coat and ceramic conversion coating adoption to maintain CE marking eligibility.
Direct-to-contractor fulfillment models are displacing traditional woodworking retail distribution as professional buyers prioritize specification support and rapid parts availability over physical showroom inspection. Specialty distributors in the United States and United Kingdom are unbundling after-sales service from equipment sales to compete with manufacturer-direct portals. This channel compression is most visible among commercial framing contractors and custom millwork shops with centralized procurement functions.
Global Table Saws Market Segmentation
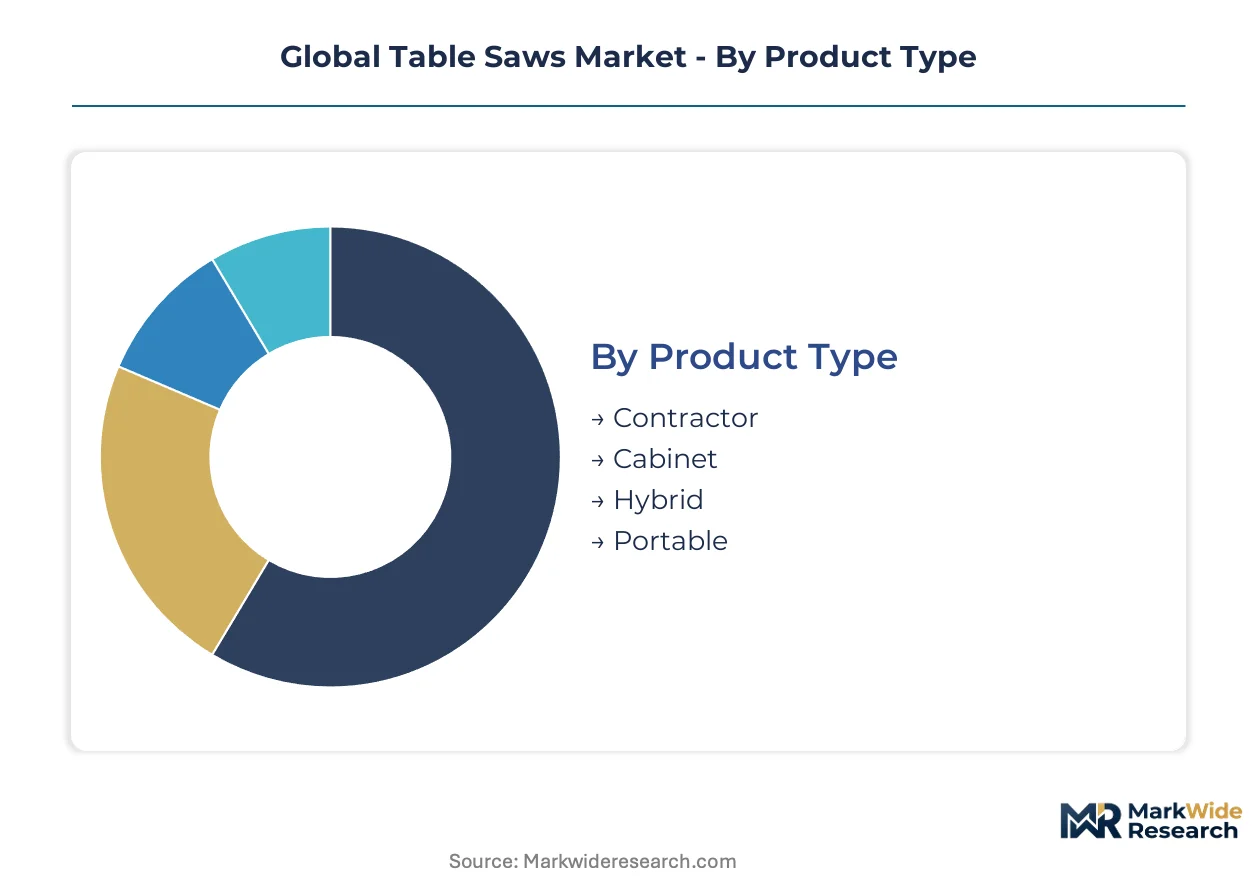
Table saw procurement patterns diverge sharply across user sophistication, power infrastructure, and dimensional capacity requirements. Segmentation reveals how specification standards, safety mandates, and jobsite mobility reshape manufacturer portfolio priorities.
Product Type:
Contractor crews through industrial furniture plants demand distinct accuracy, power, and portability trade-offs.
- Contractor:These saws pair belt-driven motors with lighter trunnion assemblies for transport between jobsites. Framing contractors in the United States and Germany favor them for dimensional lumber processing where fence precision matters less than throughput speed.
- Cabinet:Cast-iron enclosures and three-phase motor options deliver vibration-dampened accuracy for batch production. Italian and Danish furniture manufacturers specify these for engineered hardwood and composite panel work where cut tolerances determine assembly fit.
- Hybrid:Single-phase power compatibility with cabinet-grade fence systems targets serious woodworking shops lacking industrial electrical infrastructure.
- Portable:Cordless lithium-ion platforms and collapsible stands dominate renovation contractors prioritizing rapid deployment over cutting capacity.
The dominant share belongs to Contractor saws, while Portable configurations are closing the gap fastest.
Technology:
Power delivery architectures segment by energy access, emissions constraints, and torque control requirements.
- Electric:Brushless DC controllers with variable-frequency drive stabilization now penetrate premium cabinet installations. These systems enable load-compensated blade speed management that reduces thermal stress during dense hardwood cutting cycles.
- Diesel:Self-contained power generation serves remote construction sites lacking grid connectivity, particularly in infrastructure projects across India and Southeast Asia where temporary electrical infrastructure remains unavailable.
- Pneumatic:Compressed air drive systems eliminate electrical spark hazards in explosive dust environments such as solvent-based finishing facilities.
- Hydraulic:Fluid power transmission delivers sustained torque for industrial metal-cutting adaptations and continuous production environments.
Electric systems command the installed base, though brushless DC variants are climbing the fastest among new specifications.
End User:
Professional credentialing and procurement centralization create divergent specification authority patterns.
- Woodworking Shops:Custom millwork and architectural millwork operations prioritize fence accuracy and dust collection integration. OSHA silica exposure mandates accelerate specification upgrades among commercial shops in the United States.
- Construction:Framing and finish carpentry crews favor contractor-grade portability with rapid blade change capability. Single-family housing starts in Germany and the United States directly correlate with procurement volume in this segment.
- DIY Enthusiasts:Entry-level hybrid and portable configurations dominate hobbyist purchases through mass-market retail channels.
- Manufacturing:Batch furniture and fixture producers specify cabinet saws with automated feed systems and connectivity modules for production line integration.
Construction claims the largest volume, while Manufacturing is gaining specification sophistication fastest.
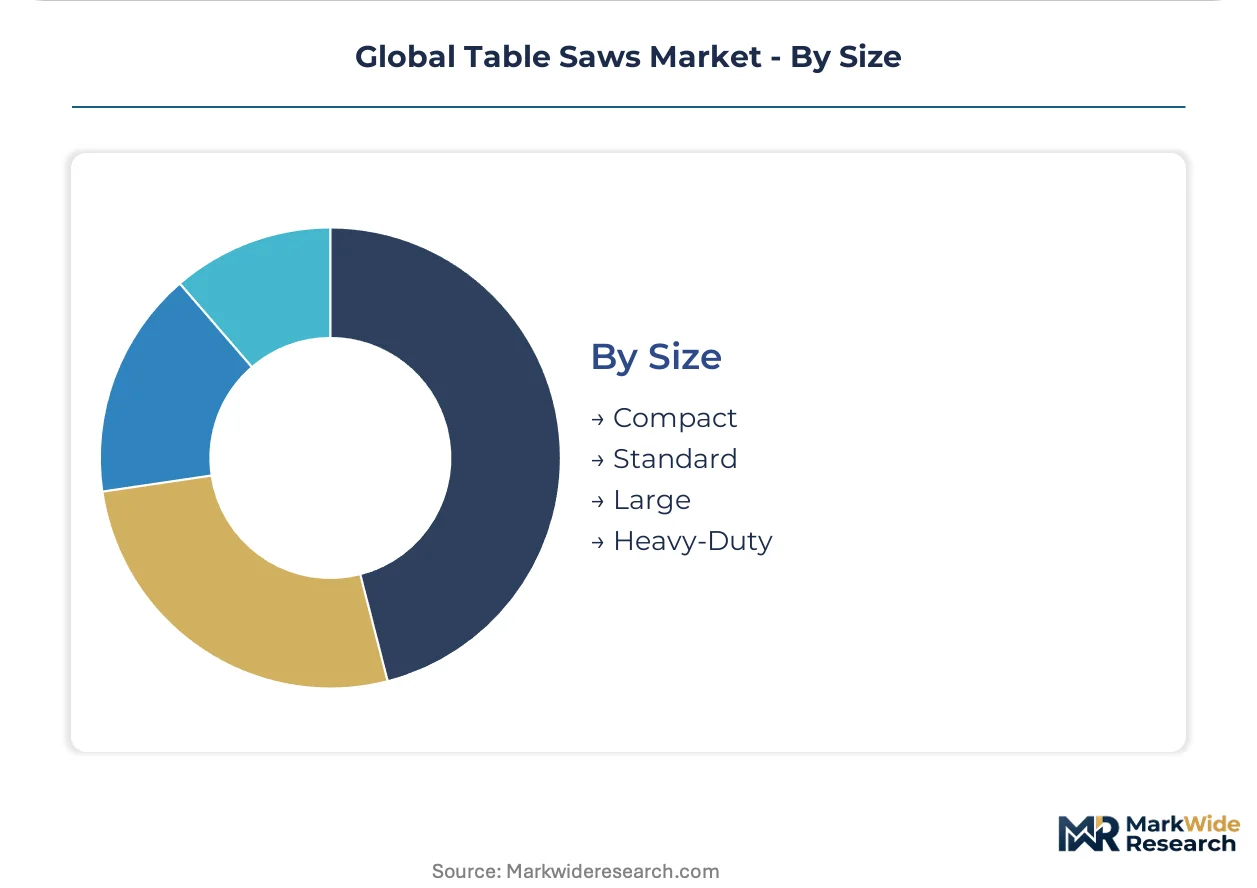
Size:
Dimensional capacity constraints map directly to material handling infrastructure and workshop footprint limitations.
- Compact:Benchtop configurations with reduced rip capacity serve apartment-based hobbyists and mobile repair technicians. These units sacrifice cutting depth for storage convenience.
- Standard:30-inch rip fences and 1.5-2 horsepower motors balance capacity with single-phase power compatibility. Residential workshops and small commercial facilities in the United States standardize around this configuration.
- Large:Extended table surfaces and 3-5 horsepower options accommodate sheet goods processing for cabinet shops and fixture manufacturers.
- Heavy-Duty:Industrial three-phase installations with 50-inch rip capacity and power feeders serve high-volume production environments.
Standard sizes anchor procurement volume, though Compact units are expanding most quickly among urban DIY segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's woodworking machinery export corridor, channeling precision equipment through the North Sea to furniture manufacturers across Northern Europe and North America.
United States
Single-family housing starts in Texas and Florida drive contractor-grade saw procurement among framing crews. OSHA machine guarding regulations mandate riving knives and blade covers on commercial installations, accelerating replacement cycles. The Southeast construction corridor from Atlanta to Charlotte concentrates demand among regional millwork distributors.
Germany
Italian and Danish furniture manufacturers source cabinet saws from Baden-Württemberg fabricators for engineered hardwood processing. The EU Machinery Directive enforces emergency stop functionality and noise emission thresholds through CE marking requirements. The Black Forest cluster around Stuttgart maintains precision metalworking heritage that feeds trunnion assembly supply chains.
China
Foundry capacity in Hebei and Shandong provinces supplies cast-iron enclosures for global cabinet saw assembly. GB standards govern electromagnetic compatibility in electronically stabilized models sold domestically. The Yangtze River Delta machinery belt around Shanghai exports portable configurations to Southeast Asian construction markets.
India
Furniture manufacturing clusters around Jodhpur and Pune remain underpenetrated by precision saw equipment relative to manual tooling prevalence. BIS certification requirements extend product launch timelines for European and North American manufacturers. The Maharashtra woodworking SME sector shows accelerating specification sophistication as export quality standards tighten.
Japan
Compact urban workshops in Tokyo and Osaka drive demand for benchtop configurations with reduced rip capacity. METI industrial standards emphasize precision measurement integration in digitally enabled models. The Nagoya manufacturing corridor supplies brushless DC motor controllers to premium saw producers across East Asia.
Global Table Saws Market Competitive Environment
On the supply side, the industry is tiered across premium industrial specialists, mass-market power tool conglomerates, and regional machinery fabricators. The upper tier concentrates among German and Italian precision manufacturers with captive foundry relationships. Mid-tier competition fragments across battery-platform power tool ecosystems and contractor-grade equipment specialists. Dominant competitive moves include strategic partnerships for flesh-sensing technology licensing and geographic expansion into underpenetrated woodworking SME clusters.
Among the named players, Stanley Black & Decker occupies a position exemplifying mass-market scale advantages, while Bosch represents European service network integration. SawStop anchors the safety-technology premium tier through proprietary brake cartridge architecture. These three companies illustrate how competitive positioning diverges across price-accessible, aftermarket-sustained, and patent-protected strategic vectors.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Bosch |
| Makita |
| Felder Group |
| SawStop |
| SCM Group |
| Altendorf |
| Powermatic |
| Techtronic Industries |
| Others |
Value Chain & Pricing Dynamics
Hebei Province foundry capacity concentration supplies cast-iron enclosures for cabinet saw assembly, translating upstream metalworking dominance into pricing power for precision manufacturers serving German and Italian furniture producers. This geographic lock on critical inputs shapes margin structures across contractor and portable tiers where alloy cost pass-through varies by buyer sophistication.
Pricing Analysis
Volume-discount tiering structures separate cabinet-grade precision equipment from mass-market portable configurations, with pricing stratifying across premium, standard, and economy tiers based on motor horsepower ratings and fence accuracy certifications. Brand premiums attach most strongly to German and Italian heritage manufacturers serving Danish furniture producers, while price erosion runs through cordless lithium-ion portable segments where battery-platform interoperability commoditizes hardware. Commercial woodworking shops in the United States demonstrate lowest price sensitivity due to OSHA-mandated replacement cycles, whereas DIY enthusiasts through mass-market retail channels drive hardest bargain.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for cast-iron component sourcing, forcing manufacturers to qualify secondary foundry relationships in India. Component dependencies center on brushless DC motor controllers from Japan's Nagoya corridor, lithium-ion battery cells from South Korean suppliers, and precision trunnion assemblies from Germany's Black Forest cluster. Distribution runs through direct-to-contractor portals displacing traditional woodworking retail, with aftermarket parts fulfillment anchoring recurring revenue relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from calibration technician networks and brake cartridge replacement programs expands faster than hardware unit sales, repositioning equipment vendors as ongoing maintenance partners rather than transactional suppliers.
For Market Incumbents: Entrench proprietary safety technology licensing as a defensive moat against cordless platform competitors, while captive foundry relationships in Hebei or Baden-Württemberg insulate margin pools from alloy price volatility. SawStop's flesh-sensing patent architecture demonstrates how royalty streams outlast hardware refresh cycles. For New Entrants and Emerging Players: Establish a beachhead in India's Jodhpur and Pune furniture manufacturing clusters where manual tooling prevalence leaves precision saw penetration below structural potential. BIS certification complexity deters rushed market entry, rewarding patient compliance investment with first-mover positioning among export-quality woodworking SMEs. For Investors and Strategic Acquirers: Long-term, this sits as a safety-regulation compounding play because OSHA silica exposure mandates and EU Machinery Directive tightening accelerate specification upgrade cycles regardless of construction volume fluctuations. Acquisition targets should demonstrate installed base density in commercial woodworking shops with recurring parts revenue. The signal to watch is EPA dust collection standard advancement converting integrated ports from accessory to mandatory specification.| Strategic Initiative | Industry Significance |
|---|---|
| Flesh-Sensing Technology Licensing | SawStop's brake cartridge patents generate royalty streams that outlast hardware replacement demand. |
| Direct-to-Contractor Portal Launch | Bosch's European service network demonstrates how specification support displaces showroom distribution. |
| Hybrid Saw Configuration Development | Single-phase power compatibility opens cabinet-grade accuracy to residential workshops lacking industrial infrastructure. |
| Integrated Dust Collection Engineering | EPA exposure limit tightening positions dust ports as specification differentiators rather than accessory add-ons. |
| Battery Platform Interoperability | Makita's cordless ecosystem strategy virtualizes jobsite equipment preferences away from corded models. |
Study Parameters
A standing panel of maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided ongoing calibration against operating reality, supplemented by customs records, SEC filings from power tool conglomerates, and machinery trade association datasets. Primary fieldwork across German, United States, and Chinese manufacturing clusters combined with secondary validation from OSHA enforcement records and EU Machinery Directive implementation reports. Bottom-up unit shipment modeling and top-down construction spending allocation were triangulated for coherence.
Scenario-bracketing framed projections across low, base, and high construction volume assumptions throughout the forecast period. Segmentation dimensions spanned product type, power delivery architecture, end-user credentialing, and dimensional capacity tier. CAGRs were derived from housing start correlations, replacement cycle analysis, and technology diffusion curves for electronically stabilized and cordless platforms.
Stress conditions across cast-iron alloy pricing, lithium-ion cell supply, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about OSHA rulemaking timelines and REACH substance restriction implementation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
CNC Leather Cutting Machine Market
Tools
Impact Sockets Market
Tools
Caulking Gun Market
Tools
Auger Drill Bits Market
Tools
Adoption of Benelux Power Tools Market
Tools
Industrial Floor Scrubber Market
Tools
Cutting Equipment, Accessories and Consumables Market
Tools
Global Flange Fasteners Market
Tools
Deburring Tool Market
Tools
Cordless Bandsaw Sander Market
Tools
Edging Tool Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Floor Saw Market
Tools
L Allen Wrench Market
Tools
Sanding Machine Market
Tools
Hydraulic Tools Market