
 Pneumatic Marking Machines Market | 2026-2036
Pneumatic Marking Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Marking Machines Market Analytics
Automotive tier suppliers is bifurcating from general metal fabrication shops as the primary demand vector. Gravotech Group leverages its engraving heritage to dominate European distribution channels. SIC Marking anchors its position through deep specialization in dot-peen and scribing configurations for aerospace and defense contractors. Telesis Technologies competes on laser-pneumatic hybrid architectures that blur traditional technology boundaries.
Pneumatic marking machines employ compressed air to drive hardened pins or styluses into metal, plastic, or composite surfaces, creating permanent alphanumeric codes, logos, or 2D Data Matrix patterns at depths ranging from 0.05 mm to 1.0 mm depending on material hardness and application requirements. Industrial-grade units command the largest installed base due to their integration with automated production lines and programmable logic controllers. Handheld configurations represent the fastest-growing product type as field-service contractors and on-site construction teams adopt portable traceability tools. Metal fabrication applications generate the deepest margin pools because of recurring consumable sales and calibration service contracts tied to ISO 9001 quality systems.
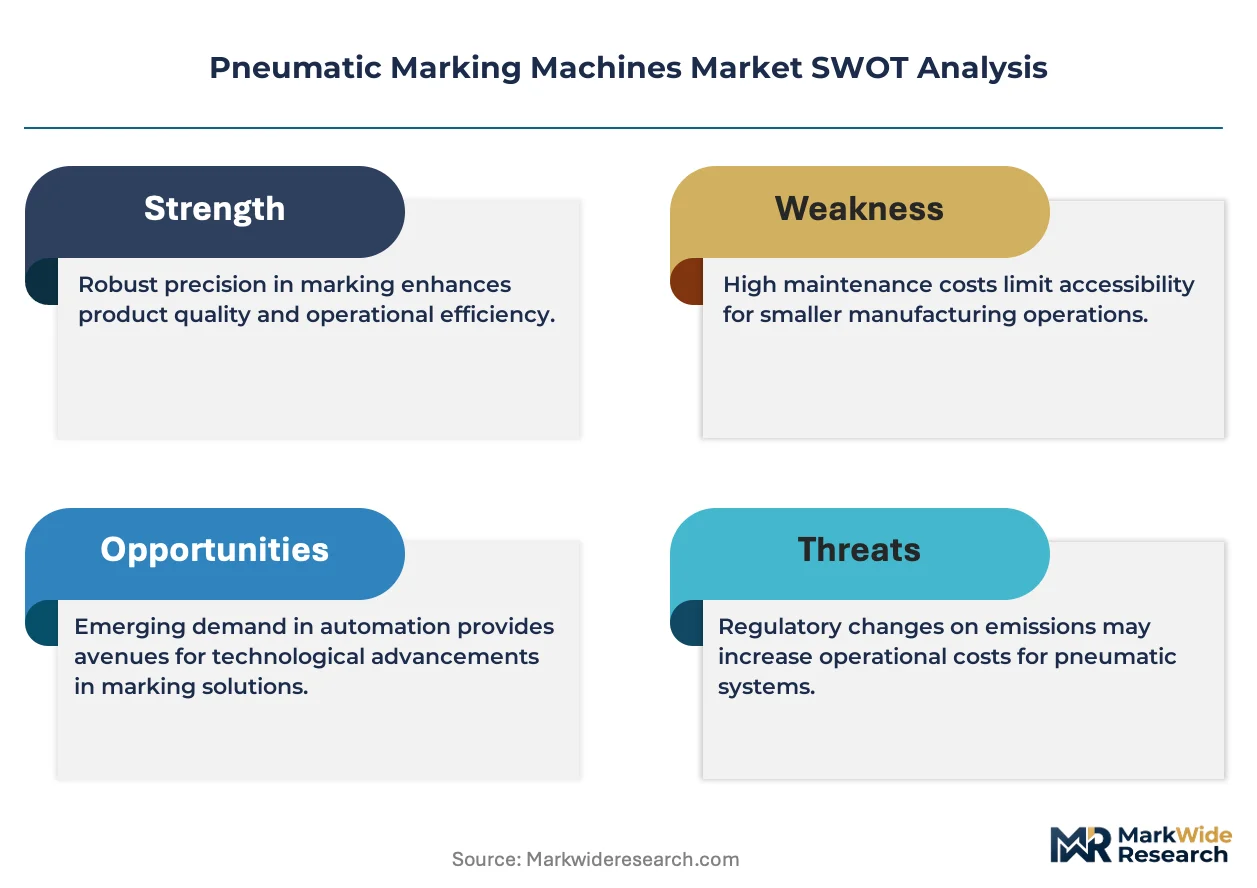
FDA 21 CFR Part 820 quality system regulations govern marking depth and legibility standards for surgical instruments and implantable devices sold in the United States. CE marking under the EU Machinery Directive mandates emergency-stop integration and operator safety guarding for industrial pneumatic marking equipment deployed across European manufacturing plants. Stakeholders must monitor evolving harmonized EN ISO standards for machine safety and assess whether hybrid electric-pneumatic architectures will trigger reclassification under emerging EU Ecodesign requirements.
Market Dynamics
Compressed air system electrification and hybrid actuator architectures are fragmenting the traditional pneumatic marking equipment landscape, forcing incumbents to recalibrate R&D roadmaps around energy efficiency mandates.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for emergency-stop integration and operator safety guarding compel European manufacturers to upgrade legacy marking stations.
- Automotive traceability systems:Tier suppliers embed dot-peen markers directly into engine block and transmission housing production lines to satisfy OEM part serialization protocols.
- Portable field-service tools:Handheld pneumatic configurations enable on-site construction teams and heavy equipment servicers to apply permanent identification codes without workshop infrastructure.
Market Restraints
- Compressed air energy costs:Industrial electricity tariffs and compressor maintenance burdens elevate total cost of ownership for high-volume pneumatic marking operations.
- Laser marking substitution:Fiber and CO2 laser systems penetrate aerospace and medical device applications where non-contact processing eliminates mechanical wear on delicate substrates.
- Steel pin supply concentration:Hardened tungsten carbide stylus manufacturing clusters in Central European tooling corridors expose buyers to extended lead times during raw material shortages.
Strategic Opportunities
- Medical device serialization:FDA 21 CFR Part 820 quality system regulations create compliance-driven replacement cycles for surgical instrument marking equipment across US hospital supply chains.
- Electric-pneumatic hybrid architectures:Servo-controlled pin actuation converges with traditional compressed air systems to deliver programmable depth control with reduced energy consumption.
- Rental and leasing channels:Equipment-as-a-service models penetrate job shop metal fabrication segments that resist capital expenditure for intermittent marking requirements.
Industry Challenges
- Mechatronics technician scarcity:Integration of programmable logic controllers and pneumatic actuators demands cross-trained maintenance personnel rarely available in regional industrial labor pools.
- ISO 9001 calibration protocols:Recurring service contract obligations strain distributor technical support capacity and compress margin structures on entry-level equipment sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Marking Machines Market |
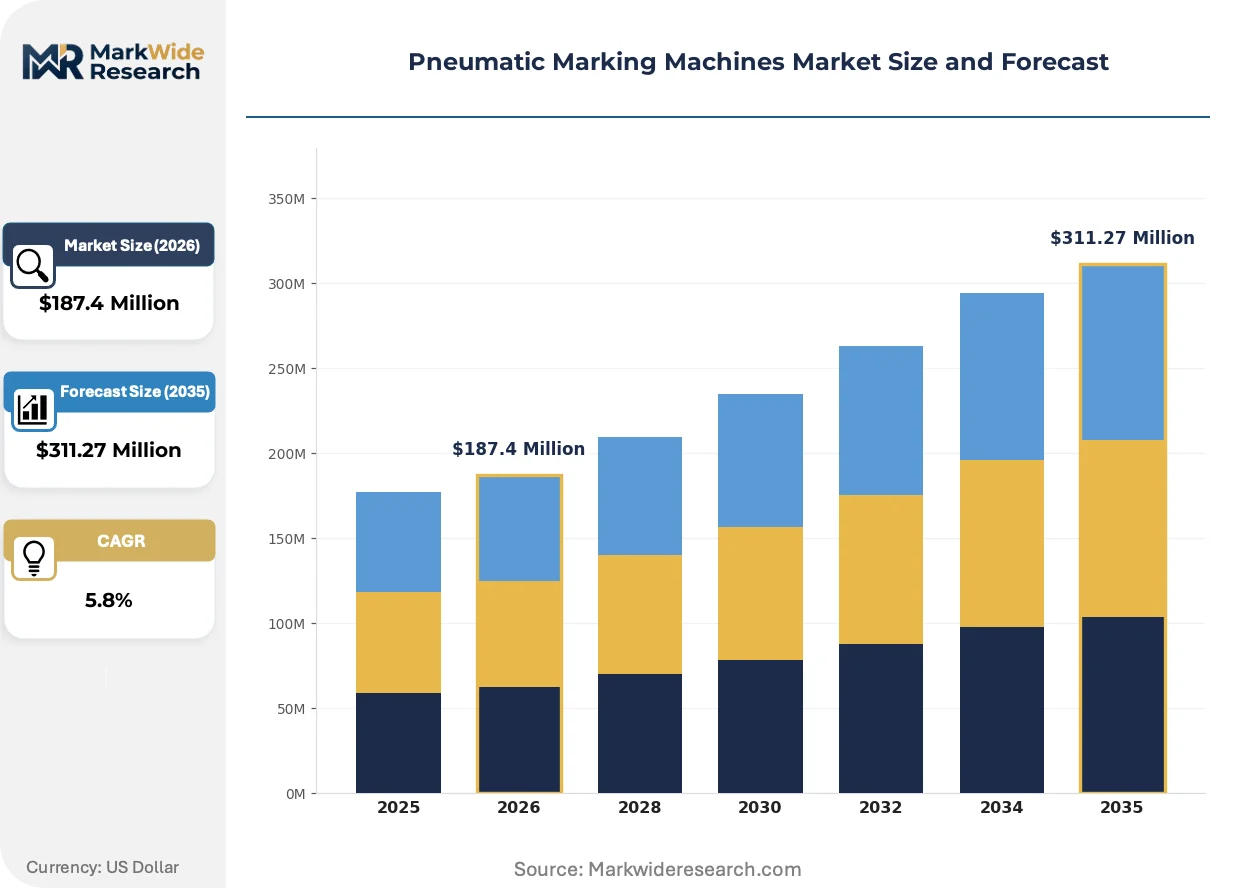
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Handheld, Portable, Industrial Application: Metal Fabrication, Woodworking, Automotive Parts, Construction End User: Manufacturers, Contractors, Suppliers, Service Providers Technology: Pneumatic, Hydraulic, Electric, Hybrid |
| Companies Covered | Gravotech Group, SIC Marking, Technomark, Columbia Marking Tools, MECCO, Borries Markier-Systeme, Pryor Technology, Ostling Etchmark, Telesis Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Marking Machines Market Evolving Landscape
Actuator miniaturization and control system digitization are compressing equipment footprints while expanding programmable functionality, reshaping how manufacturers deploy marking assets across distributed production networks.
Hybrid electric-pneumatic pin drivers are bifurcating the installed base between legacy compressed-air-only systems and next-generation servo-assisted configurations. Aerospace contractors and precision medical device manufacturers adopt these hybrid units for depth-repeatability-critical applications. The technology is bifurcating competitive positioning between energy-efficient premium tiers and cost-optimized conventional equipment.
EU Ecodesign requirements for energy-related products are tightening standby power consumption limits and mandating efficiency disclosures for industrial machinery sold across member states. Pneumatic marking equipment with integrated variable-frequency drives and intelligent compressor coupling satisfy these thresholds. German automotive suppliers and Italian machinery builders face the steepest compliance timelines under the phased implementation schedule.
After-sales service unbundling is accelerating as buyers separate equipment procurement from calibration and consumables contracts. Metal fabrication job shops and independent contract manufacturers negotiate standalone maintenance agreements with third-party metrology providers. This pattern concentrates in North American and Western European markets where ISO 9001 audit frequency sustains recurring revenue streams for specialized service organizations.
Pneumatic Marking Machines Market Segmentation
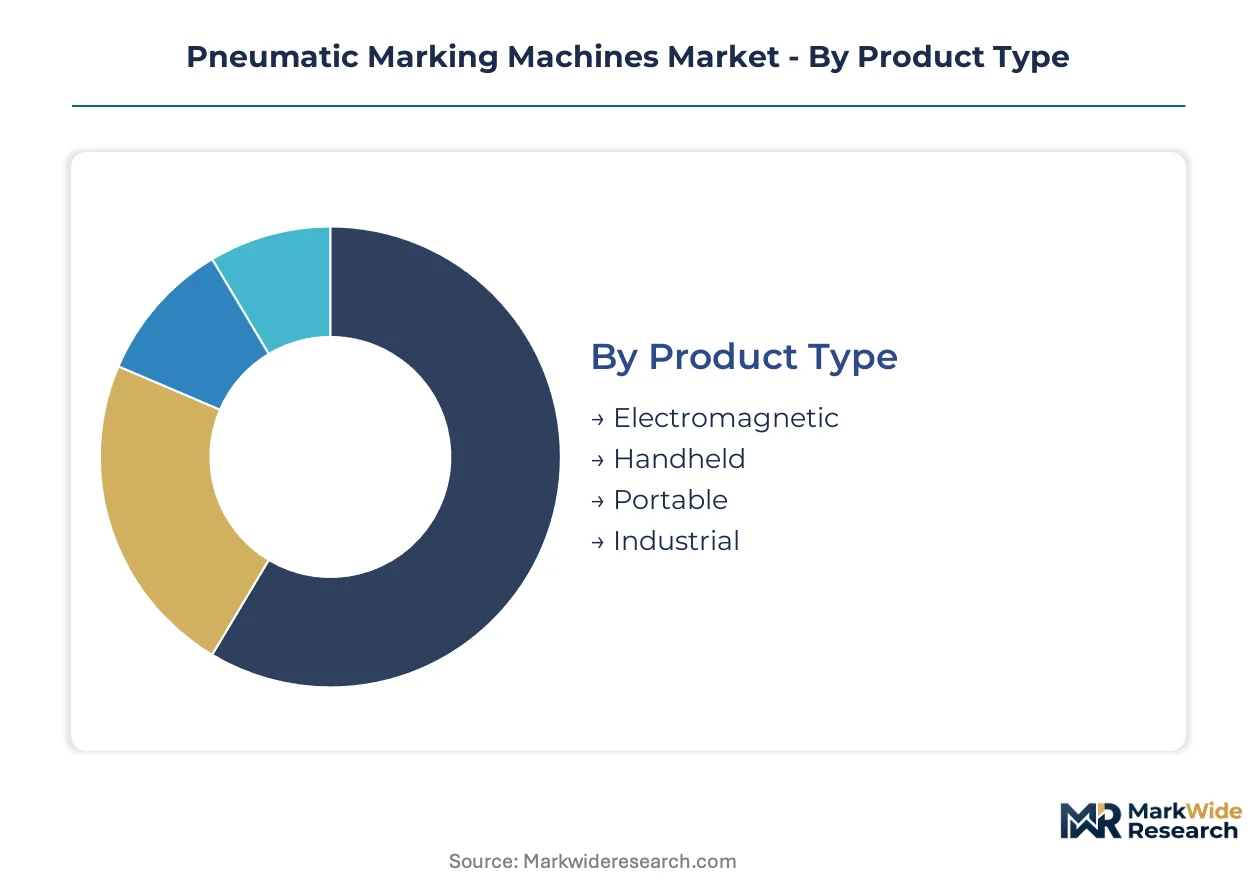
Pneumatic marking machine segmentation reveals divergent margin architectures across product configurations and end-use applications. Equipment type and application context determine service contract attach rates, consumable replenishment cycles, and compliance-driven replacement timelines.
Product Type:
Margin pools concentrate in industrial-grade configurations with integrated automation and calibration service contracts, while handheld units capture volume through lower price points and reduced aftermarket attachment.
- Industrial:Stationary floor-mounted units integrate with programmable logic controllers and automated production lines. German automotive suppliers and Italian machinery builders deploy these for engine block serialization under EU Machinery Directive mandates. Recurring ISO 9001 calibration contracts generate sustained service revenue streams.
- Handheld:Battery-assisted portable configurations enable field-service contractors to apply permanent marks without compressed air infrastructure. On-site construction teams and heavy equipment servicers in North American and Western European markets drive procurement for distributed traceability requirements.
- Portable:Compact cart-mounted systems bridge workshop and field applications with wheeled mobility and quick-connect pneumatic couplings.
- Electromagnetic:Solenoid-actuated pin drivers eliminate compressed air dependency for cleanroom and medical device manufacturing environments.
Industrial holds installed capacity. Handheld is rotating up the share rankings.
Application:
Application segmentation tracks regulatory exposure and material hardness requirements that dictate equipment specification and consumable wear rates.
- Metal Fabrication:Steel, aluminum, and alloy processing generates the deepest margin pools through tungsten carbide stylus replenishment and depth-verification services tied to quality system audits. Job shops and contract manufacturers across US industrial corridors sustain recurring calibration obligations.
- Automotive Parts:Engine block, transmission housing, and chassis component serialization demands dot-peen systems with programmable depth control and Data Matrix readability verification. Tier suppliers embed markers directly into transfer lines to satisfy OEM traceability protocols.
- Construction:Structural steel identification and rebar marking for infrastructure projects require weather-resistant portable configurations.
- Woodworking:Soft-material marking with reduced pin force settings serves pallet, crate, and finished goods identification in packaging operations.
Metal Fabrication commands the aftermarket revenue base. Automotive Parts is climbing the fastest on compliance-driven replacement cycles.
End User:
End-user categories reflect capital deployment capacity and service contract negotiation leverage that fragment pricing architectures across the installed base.
- Manufacturers:Capital-intensive production facilities with dedicated maintenance departments negotiate bundled equipment-service agreements and multi-site calibration contracts. FDA-regulated medical device producers and FAA-registered aerospace suppliers impose stringent depth-repeatability specifications.
- Contractors:Project-based procurement patterns favor rental and leasing channels over capital expenditure, concentrating demand in equipment-as-a-service models for intermittent marking requirements.
- Suppliers:Component and raw material distributors require marking capability for inventory control and shipment traceability without full production integration.
- Service Providers:Independent marking bureaus and mobile identification specialists operate across customer sites with portable equipment fleets.
Manufacturers anchor the premium tier. Contractors are expanding most quickly through rental channel penetration.
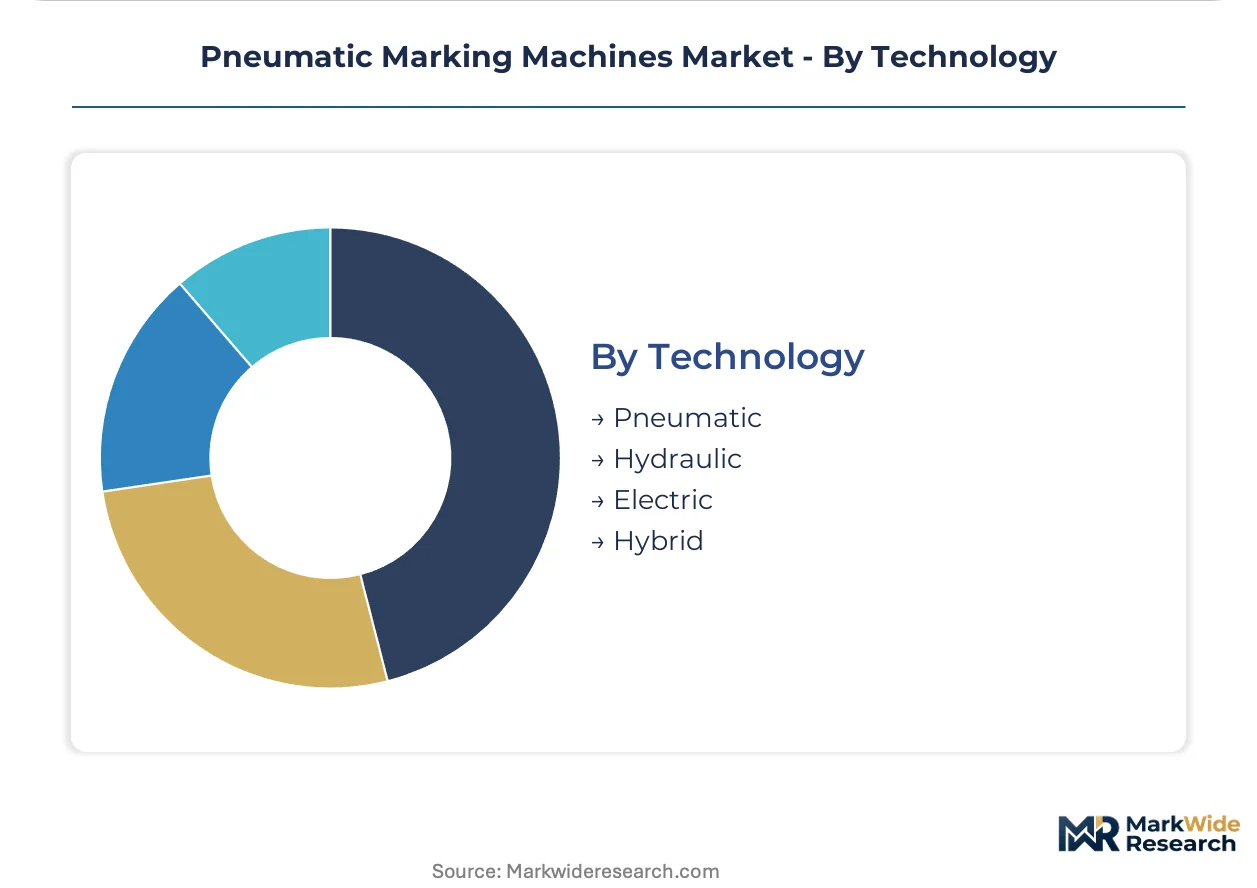
Technology:
Technology segmentation captures the transition from conventional pneumatic architectures toward hybrid and alternative actuation systems under energy efficiency mandates.
- Pneumatic:Compressed air-driven pin actuation dominates legacy installations with proven reliability and lower capital cost, though electricity tariffs and compressor maintenance elevate total cost of ownership in high-volume operations.
- Hybrid:Servo-controlled electric actuation converges with pneumatic backup systems to deliver programmable depth control with reduced energy consumption. Aerospace contractors and precision medical device manufacturers adopt these configurations for critical repeatability applications.
- Electric:Fully electromechanical marking eliminates compressed air infrastructure for cleanroom and noise-sensitive environments.
- Hydraulic:High-force actuation serves specialized deep-marking applications in heavy forging and casting operations.
Pneumatic retains the largest installed base. Hybrid is gaining share fastest on EU Ecodesign compliance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network underwrites Germany's centrality to European pneumatic marking equipment flows. Automotive component plants and machinery builders along this logistics spine consume industrial-grade dot-peen systems for traceability compliance. The corridor's density shapes procurement patterns across the continent.
Germany
Automotive tier suppliers in Stuttgart and Munich embed marking stations directly into powertrain production lines. CE marking under the EU Machinery Directive mandates emergency-stop integration for all new industrial equipment deployments. The Baden-Württemberg manufacturing belt concentrates demand from precision engineering firms serving Mercedes-Benz and BMW supply chains.
United States
FDA-regulated medical device producers in Minneapolis and Boston drive replacement cycles for surgical instrument marking equipment. OSHA workplace safety standards govern operator guarding requirements for pneumatic systems deployed across Midwest metal fabrication corridors. The Great Lakes industrial belt sustains deep aftermarket revenue through ISO 9001 calibration contracts tied to automotive and aerospace supplier audits.
China
MIIT industrial upgrading programs accelerate adoption of automated traceability systems in Yangtze River Delta automotive plants. GB standards for machinery safety create compliance baselines for domestic and imported marking equipment. The Shanghai-Suzhou manufacturing corridor concentrates demand from EV battery housing and electric motor producers implementing part serialization protocols.
Japan
METI carbon neutrality roadmaps pressure manufacturers to evaluate hybrid electric-pneumatic architectures against conventional compressed-air systems. JIS standards for industrial machinery safety influence specification requirements for automotive and electronics sector procurement. The Nagoya industrial zone anchors demand from Toyota and Honda supplier networks implementing zero-defect traceability programs.
India
PLI scheme incentives for automotive and electronics manufacturing expand addressable market for industrial marking equipment in Tamil Nadu and Gujarat. BIS certification requirements for imported machinery create compliance thresholds for European and East Asian equipment suppliers. The Chennai-Bengaluru industrial corridor concentrates demand from two-wheeler and commercial vehicle component manufacturers.
Pneumatic Marking Machines Market Competitive Landscape
Listed leaders compete with private specialists across capitalization and geographic coverage dimensions. The vendor base clusters into three tiers: diversified industrial technology conglomerates with engraving heritage, dedicated marking equipment specialists with deep configuration expertise, and regional fabricators serving price-sensitive job shop segments. Consolidation pressure concentrates at the mid-market boundary where hybrid technology investments strain R&D budgets. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into laser-pneumatic hybrid architectures.
Within the heritage-engraving tier, Gravotech Group exemplifies European distribution dominance built on decades of marking technology lineage. SIC Marking occupies a specialist position focused on dot-peen and scribing configurations for aerospace and defense contractor specifications. Telesis Technologies represents the hybrid-technology vector, competing on architectures that blur traditional pneumatic and laser system boundaries. These three anchors illustrate how competitive positioning fragments across technology heritage, application depth, and actuator innovation vectors.
| Leading Market Players |
|---|
| Gravotech Group |
| SIC Marking |
| Technomark |
| Columbia Marking Tools |
| MECCO |
| Borries Markier-Systeme |
| Pryor Technology |
| Ostling Etchmark |
| Telesis Technologies |
| Others |
Value Network & Pricing Analysis
Hybrid electric-pneumatic actuator substitution for legacy compressed-air-only systems simultaneously redraws component sourcing geography from Central European pneumatic corridors toward East Asian servo-motor manufacturing clusters and compresses pricing premiums on conventional equipment tiers. This dual displacement forces incumbents to recalibrate margin structures across energy-efficiency-compliant and legacy product lines while buyers arbitrage total cost of ownership calculations.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy equipment levels, with premium hybrid configurations commanding 40-60% uplifts over conventional pneumatic units based on CE marking compliance and ISO 9001 calibration bundling. Price differentiation hinges on energy efficiency certification grade and after-sales service contract depth. Pricing pressure stems from laser marking substitution in aerospace and medical device applications. Metal fabrication job shops exhibit highest price sensitivity, while FDA-regulated medical device manufacturers demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Tungsten carbide stylus manufacturing concentration in Germany's Baden-Württemberg tooling corridor and China's Zhejiang province creates single-source vulnerability for hardened pin supply. Component sourcing draws from Italian pneumatic valve specialists, Japanese servo-motor producers, and Taiwanese control system fabricators. Tariff exposure on precision electromechanical components imported into North American assembly plants elevates landed cost volatility. Distribution runs through Gravotech's European dealer network, SIC Marking's aerospace-direct sales force, and regional job shop distributors serving intermittent-demand segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pneumatic marking equipment incumbents confront a substitution defense imperative as fiber and CO2 laser systems capture aerospace and medical device applications where non-contact processing eliminates mechanical stylus wear. Defending installed base relevance demands strategic repositioning around hybrid architectures and service unbundling.
For Market Incumbents: Secure calibration service contract exclusivity with ISO 9001-audited metal fabrication networks to lock in recurring revenue streams against laser marking erosion. Secure backward integration into tungsten carbide stylus production to mitigate Central European supply concentration risk and compress lead times during raw material shortages. Hybrid R&D investment represents the critical lever for maintaining premium tier positioning.
For New Entrants and Emerging Players: Lead with rental and leasing channel penetration targeting North American and Western European contract manufacturers resisting capital expenditure for intermittent marking requirements. Lead with electromagnetic cleanroom configurations for FDA-regulated surgical instrument producers seeking compressed-air-free alternatives. Lead with portable battery-assisted units for field-service contractors in infrastructure and heavy equipment maintenance segments.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors hybrid-capable mid-cap specialists with established aerospace certification pathways. Long-term viability centers on electric-pneumatic servo integration expertise and EU Ecodesign compliance positioning. Watch FDA 21 CFR Part 820 enforcement intensity as the inflection signal for surgical instrument marking equipment replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Electric-Pneumatic Platform Development | Servo-controlled pin actuation satisfies EU Ecodesign mandates while penetrating aerospace depth-repeatability specifications. |
| Calibration Service Network Expansion | Third-party metrology partnerships capture ISO 9001 audit-driven recurring revenue from metal fabrication job shops. |
| Cleanroom Electromagnetic Product Line Launch | Solenoid-actuated configurations eliminate compressed air dependency for FDA-regulated medical device manufacturers. |
| Equipment-as-a-Service Model Deployment | Rental channels penetrate project-based contractor procurement patterns resistant to capital expenditure. |
| Backward Integration into Stylus Manufacturing | In-house tungsten carbide production mitigates German-Chinese supply concentration and compresses lead times. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads at pneumatic marking equipment deployers across automotive, aerospace, and metal fabrication verticals; and secondary validation through customs/trade data, SEC 10-K filings of listed industrial technology conglomerates, EU Machinery Directive implementation guidance, and FDA 21 CFR Part 820 quality system documentation. Bottom-up equipment shipment tallies and top-down industrial automation spend estimates were triangulated to anchor market sizing.
Across the analysis window, forecasts modeled segmentation dimensions spanning product configuration (industrial, handheld, portable, electromagnetic), application context (metal fabrication, automotive parts, construction, woodworking), end-user archetype (manufacturers, contractors, suppliers, service providers), and actuation technology (pneumatic, hybrid, electric, hydraulic). CAGRs derived from equipment replacement cycle analysis, regulatory compliance timeline phasing, and energy efficiency mandate adoption curves. Industry-specific inputs included EU Ecodesign standby power consumption thresholds and FDA medical device serialization enforcement patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU Machinery Directive compliance timelines or accelerated laser marking cost reduction curves would require recalibration. Practitioners should keep alternative scenarios live as hybrid technology cost parity and carbon neutrality roadmap pressures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Mortiser Market
Tools
Orbital Sanders Market
Tools
Striking Tools Market
Tools
Caulking Gun Market
Tools
Nail Gun Market
Tools
Global Metal Forming Machine Tools Market
Tools
Cordless Long Neck Grinder Market
Tools
Concrete Saw Market
Tools
GCC Machine Tools Market
Tools
Portable Milling Machine Market
Tools
Leather Embossing Machine Market
Tools
US Chalk Reel and Line Market
Tools
Global Cutting Discs Market
Tools
Power Drill Market
Tools
Cordless Wood Planer Market
Tools
Belt File Sander Market