
 Bar Clamp Market | 2026-2036
Bar Clamp Market Size, Share, and Industry Trends Forecast 2026-2036
Bar Clamp Market Analytics
Chinese forging and casting capacity for hand-tool steel is broadening the upstream supply base for bar clamp production. BESSEY Tool leverages its German engineering heritage to dominate premium quick-release mechanisms for professional woodworkers. DEWALT anchors its position through deep distribution in North American big-box retail, while Stanley Black & Decker sustains volume leadership via brand consolidation across multiple clamp sub-brands.
A bar clamp is a linear clamping device comprising a steel or iron bar with a fixed jaw at one end and a sliding jaw actuated by screw, trigger, or ratchet mechanism, designed to apply uniform pressure across glued joints or held workpieces during assembly, curing, or machining operations. Quick-release clamps command the widest professional user base due to speed advantages in repetitive production settings, while composite-material variants represent the fastest-expanding segment as manufacturers seek weight reduction for extended handheld use. Metal fabrication end users generate the most stable replacement demand cycle, whereas DIY enthusiasts drive seasonal volume spikes through hardware store and online retail channels.
ISO 9001 quality management standards govern production consistency for export-oriented manufacturers, while REACH compliance in Europe restricts certain surface coatings and handle plastics, effectively filtering lower-cost Asian suppliers from premium EU distribution channels. The US Consumer Product Safety Commission monitors clamp mechanical failure reports, shaping product liability exposure and warranty terms for brands serving the North American market. Stakeholders must monitor evolving sustainability disclosure requirements under the EU Green Deal, as carbon footprint documentation becomes a procurement gate for large European woodworking cooperatives and industrial buyers.
Market Dynamics
The US EPA's tightened volatile organic compound regulations for wood adhesives and finishes are forcing manufacturers toward longer open-time formulations that demand more sophisticated clamping protocols and precision pressure control systems.
Growth Catalysts
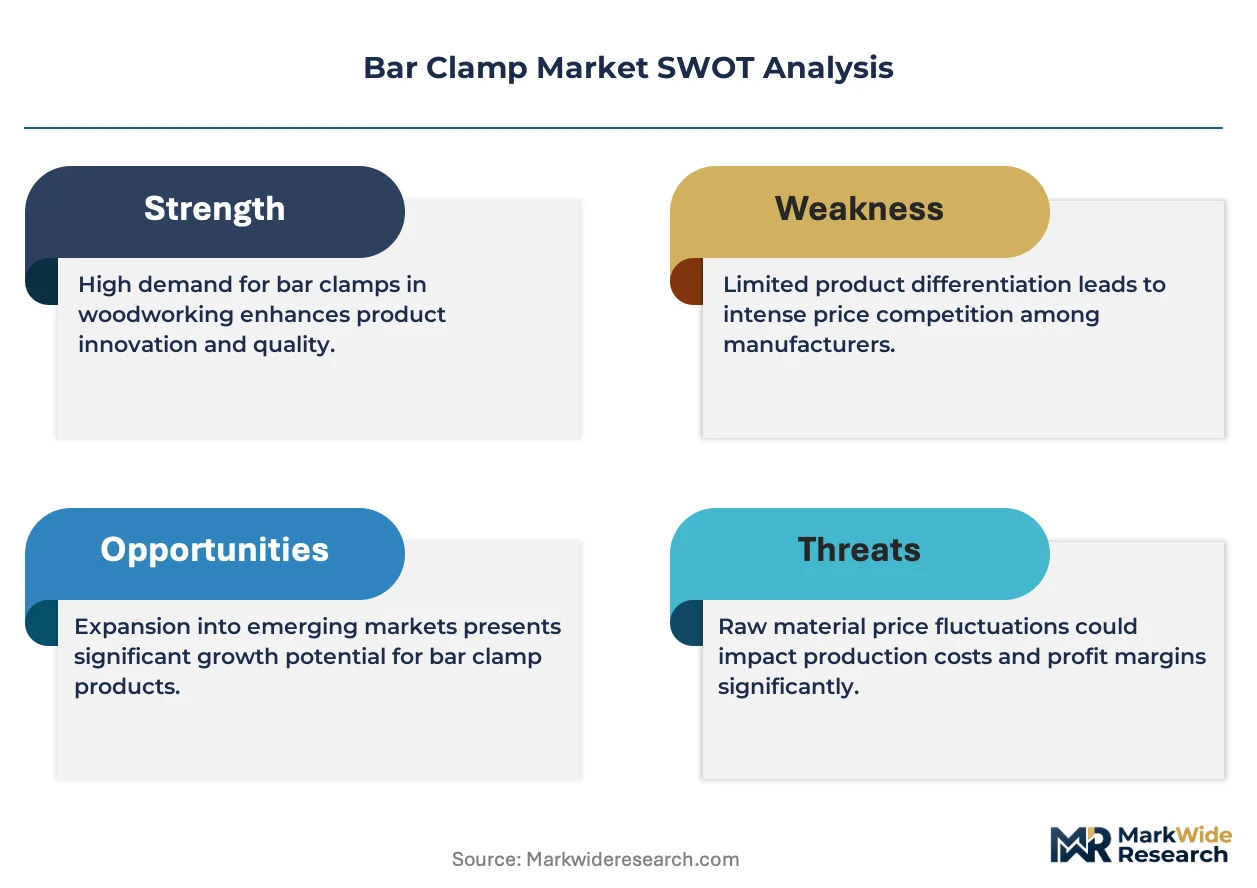
- REACH compliance in Europe:The regulation restricts certain surface coatings and handle plastics, filtering lower-cost Asian suppliers from premium EU distribution channels and opening margin expansion for compliant manufacturers.
- Composite material adoption:Manufacturers are integrating carbon-fiber reinforced polymers and glass-filled nylons to reduce clamp weight for extended handheld use in assembly line environments.
- German precision tooling standards:The country's dense network of mid-sized woodworking enterprises sustains premium clamp procurement through DIN-certified quality requirements.
Market Restraints
- Hand-tool steel price volatility:Chinese forging capacity expansion has created input cost instability for bar and jaw production, compressing margins for non-integrated assemblers.
- Technical limitation in quick-release durability:Trigger mechanisms suffer wear failure under sustained industrial duty cycles, limiting adoption in heavy fabrication beyond woodworking.
- Substitution by vacuum pressing systems:Panel manufacturers above certain volume thresholds are displacing mechanical clamps with pneumatic membrane presses for glue-up operations.
Strategic Opportunities
- EU Green Deal carbon documentation:Sustainability disclosure requirements are becoming procurement gates for large European woodworking cooperatives, rewarding early compliance investment.
- Online direct-to-contractor channels:E-commerce platforms are disintermediating traditional hardware distribution for professional-grade tool procurement in North America.
- Smart clamp integration:Force-sensor embedded jaws converging with IoT connectivity are enabling real-time pressure monitoring for quality-critical bonding operations.
Industry Challenges
- ISO 9001 certification timeline:Export-oriented manufacturers face 12-18 month quality management system implementation periods that delay market entry.
- Skill gap in composite manufacturing:Injection molding expertise for fiber-reinforced handles remains scarce in traditional metalworking supply bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bar Clamp Market |
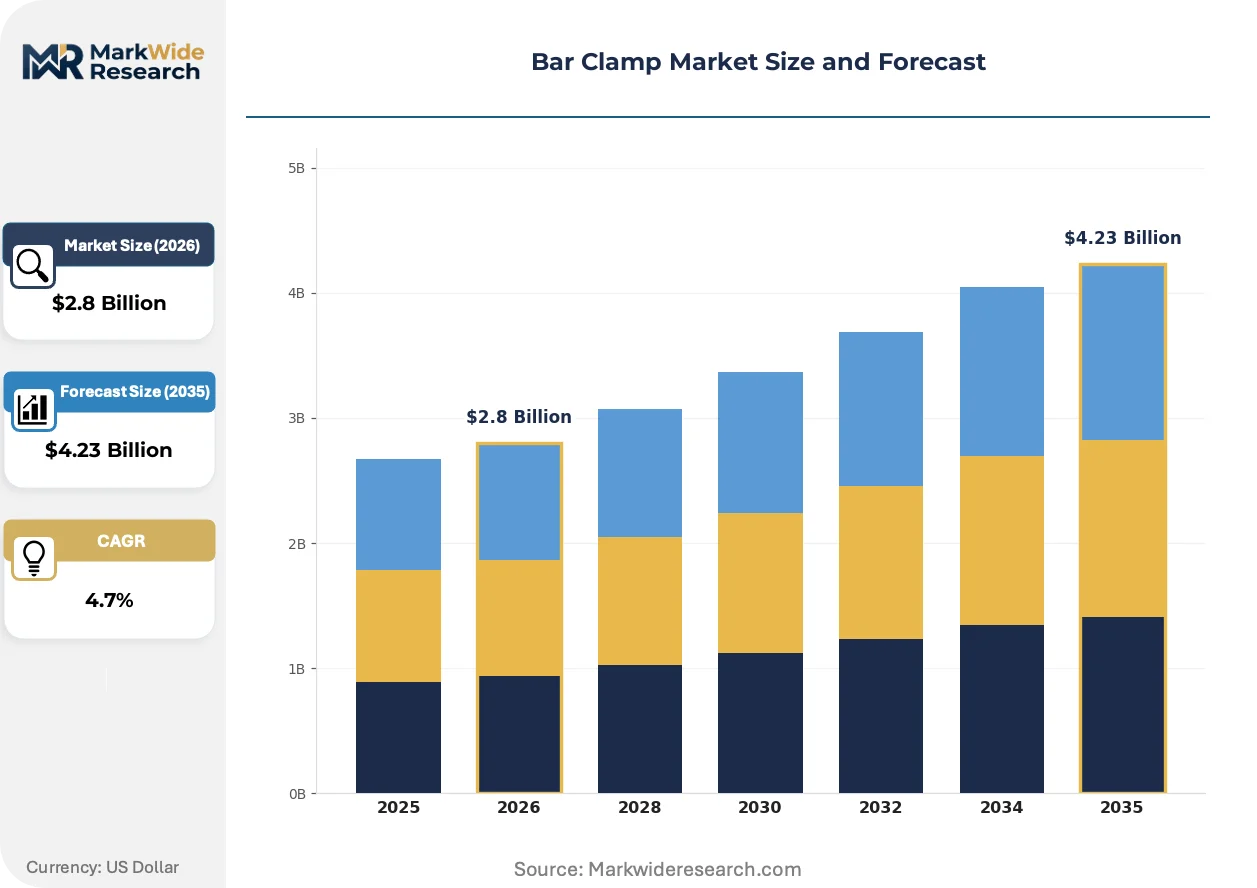
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Clamps, Quick-Release Clamps, Adjustable Clamps, Spreader Clamps Material: Metal, Plastic, Composite, Wood End User: Woodworking, Metal Fabrication, Construction, DIY Enthusiasts Distribution Channel: Online Retailers, Hardware Stores, Specialty Shops, Distributors |
| Companies Covered | BESSEY Tool, DEWALT, Irwin Tools, Pony Jorgensen, Stanley Black & Decker, Metalmech, J F Tools, Power Tech India, Baweja Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bar Clamp Market Evolving Landscape
Clamp technology is pivoting toward intelligent force management and material lightweighting as professional users demand faster setup cycles and reduced operator fatigue during extended production runs.
Ratchet-actuated sliding jaw mechanisms are automating repetitive clamping sequences in high-volume furniture assembly. Mid-sized German woodworking shops have adopted these systems at accelerating rates since 2022. The technology is automating throughput gains that previously required dedicated pneumatic fixture investment.
REACH surface coating restrictions are eliminating hexavalent chromium finishes from EU-bound clamp production. Manufacturers serving Germany and France have shifted to zinc-nickel and ceramic-based alternatives. Premium quick-release product lines bear the highest compliance cost burden, reshourcing plating operations to certified European subcontractors.
Professional buyers are consolidating supplier relationships around single-source clamp portfolios with unified warranty terms. Hardware distributors in the US Midwest report shrinking vendor counts per store from twelve to four major lines. This concentration is most visible among commercial cabinet shops purchasing through industrial supply cooperatives rather than retail channels.
Bar Clamp Market Segmentation
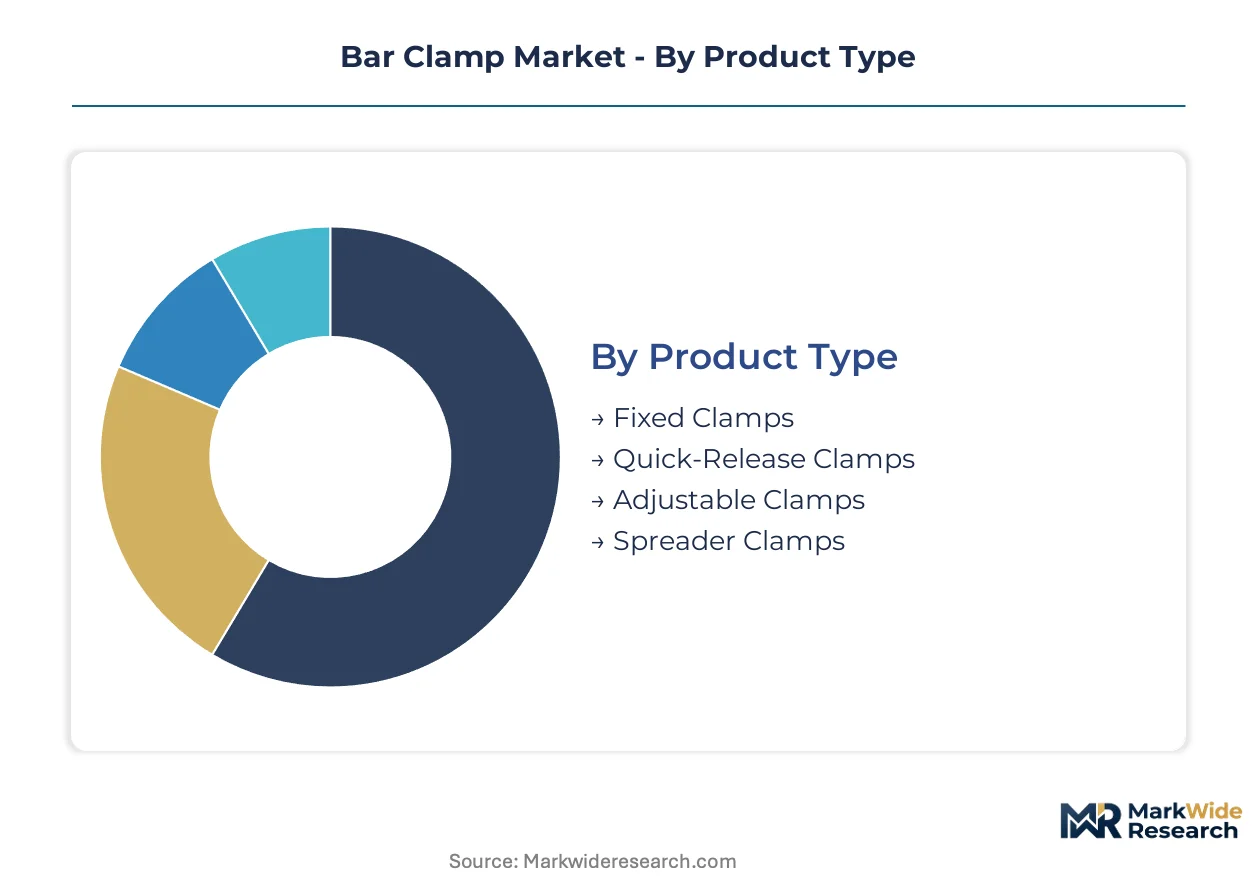
Bar clamp procurement patterns diverge sharply across user workflows, material durability requirements, and channel access economics. Manufacturers configure product portfolios around these fracture lines to defend margin tiers and capture replacement cycles.
Product Type:
Speed of operation separates professional buyers from occasional users in this category.
- Quick-Release Clamps:Trigger-actuated sliding jaws enable single-handed pressure adjustment and rapid repositioning. German mid-sized furniture workshops and North American commercial cabinet shops concentrate demand here, driven by throughput targets in repetitive glue-up sequences.
- Fixed Clamps:Traditional screw-threaded mechanisms deliver sustained pressure without mechanical drift. Metal fabrication end users in the US Midwest and Ruhr Valley industrial clusters favor these for welding fixture applications where trigger durability fails under sustained duty cycles.
- Adjustable Clamps:Modular jaw spacing accommodates irregular workpiece dimensions through interchangeable components.
- Spreader Clamps:Reverse-acting jaws apply outward pressure for frame squaring and door assembly tasks.
Volume sits with Fixed Clamps; growth tilts toward Quick-Release Clamps.
Material:
Weight tolerance and corrosion exposure dictate material selection across end-use environments.
- Composite:Carbon-fiber reinforced polymers and glass-filled nylons reduce mass by 40-60% versus steel equivalents. Assembly line operators in Scandinavian prefabricated housing plants and Japanese automotive interior shops drive steepest expansion trajectory, prioritizing operator fatigue reduction during eight-hour production runs.
- Metal:Forged steel and ductile iron construction dominates heavy fabrication and outdoor construction exposure. German DIN-certified workshops and Australian mining equipment repair facilities specify these for load-bearing applications where polymer creep risks joint failure.
- Plastic:Injection-molded structural polymers serve light-duty hobbyist and educational market tiers.
- Wood:Traditional wooden screw clamps persist in heritage furniture restoration and craft education segments.
Metal captures current revenue concentration; composite materials are climbing the fastest.
End User:
Replacement cycle predictability and specification stringency separate commercial from consumer demand pools.
- Woodworking:Custom furniture makers and architectural millwork shops generate the most stable replacement demand through continuous glue-up operations. US EPA volatile organic compound regulations for extended open-time adhesives are forcing these users toward precision pressure control systems.
- Metal Fabrication:Structural steel workshops and pressure vessel manufacturers specify heavy-duty fixed clamps for welding pre-assembly. German industrial Mittelstand and US Gulf Coast petrochemical fabricators sustain premium procurement through DIN and AWS certification requirements.
- Construction:Site-based formwork and temporary bracing applications drive seasonal volume spikes.
- DIY Enthusiasts:Hardware store and online retail channels serve intermittent project-based purchasing with price-sensitive specification thresholds.
Woodworking anchors procurement value; metal fabrication delivers replacement regularity.
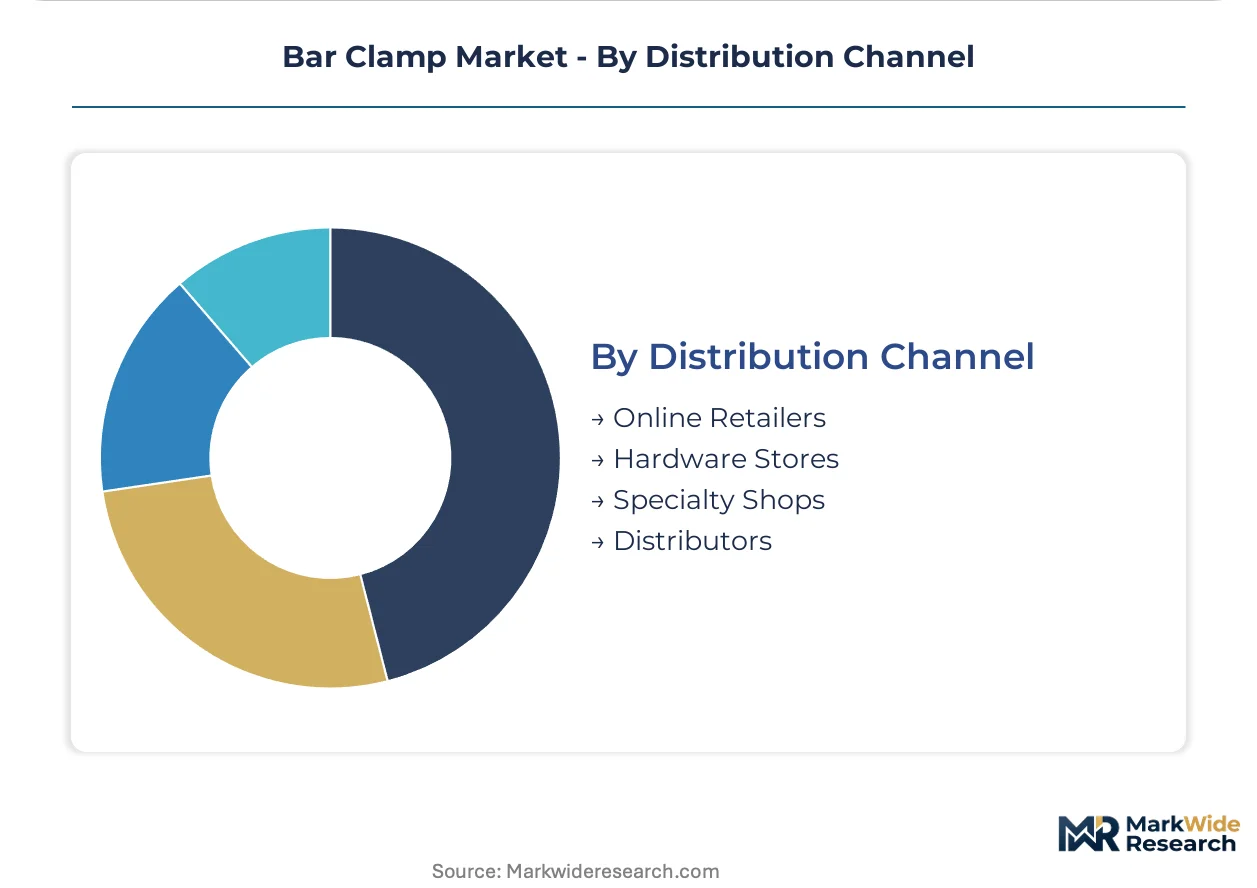
Distribution Channel:
Specification support requirements and order fragmentation determine channel economics.
- Online Retailers:Direct-to-contractor platforms are disintermediating traditional distribution for professional-grade procurement. US Midwest industrial supply cooperatives and UK trade-only e-commerce portals concentrate volume growth, enabled by bulk pricing transparency and unified warranty documentation.
- Hardware Stores:Big-box retail chains anchor DIY and light professional volume through immediate availability. DEWALT's North American distribution depth exemplifies this channel's margin compression dynamics.
- Specialty Shops:Dedicated woodworking and metalworking retailers provide application engineering support for specification-intensive buyers.
- Distributors:Industrial supply houses manage multi-brand portfolios for commercial accounts with consolidated procurement processes.
Hardware Stores retain transaction volume; Online Retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hand-tool steel from Chinese forging centers feeds clamp production worldwide, while demand concentrates in precision manufacturing clusters across Germany, the United States, and Japan.
Germany
DIN-certified woodworking enterprises in the Black Forest and Ruhr Valley sustain premium quick-release clamp procurement. REACH surface coating restrictions filter non-compliant Asian suppliers from distribution channels. Stuttgart's mid-sized furniture workshops drive adoption of ratchet-actuated mechanisms for throughput gains.
United States
Commercial cabinet shops in the Midwest and Gulf Coast petrochemical fabricators generate divergent demand pools for woodworking and metal fabrication clamps. EPA volatile organic compound regulations push adhesive formulators toward extended open-time products requiring precision pressure control. Chicago-area industrial supply cooperatives consolidate vendor relationships around unified warranty terms.
China
Expanding forging and casting capacity for hand-tool steel broadens upstream supply availability for bar and jaw production. The country's national environmental regulator enforces emissions standards on metal finishing operations that reshape plating subcontractor networks. Yangtze River Delta tool assemblers serve export markets through ISO 9001-certified production lines.
Japan
Automotive interior manufacturers and prefabricated housing plants prioritize composite-material clamps for operator fatigue reduction during extended production runs. METI industrial standards govern quality benchmarks for professional-grade hand tools. Nagoya-area assembly line operators drive steepest expansion trajectory for carbon-fiber reinforced polymer variants.
United Kingdom
Heritage furniture restoration workshops and craft education segments sustain niche demand for traditional wooden screw clamps. Trade-only e-commerce portals disintermediate traditional hardware distribution for professional-grade procurement. Midlands-based millwork shops concentrate specification-intensive purchasing through consolidated supplier relationships.
Bar Clamp Market Competitive Landscape
Global majors compete with regional champions across distribution depth and certification compliance, producing a tiered structure where premium quick-release mechanisms sit apart from volume-standard lines. The vendor base organizes around three archetypes: German-engineered precision specialists, North American big-box retail anchors, and Asian forging-integrated assemblers. Consolidation moves concentrate brand portfolios under umbrella entities, while sustainability certification investments filter non-compliant suppliers from European procurement channels.
Among the named players, BESSEY Tool and DEWALT occupy distinct positioning vectors that exemplify the premium-versus-volume archetype split, with Stanley Black & Decker representing portfolio consolidation strategy through multi-brand clamp line aggregation. These three entities anchor competitive dynamics across German engineering heritage, North American retail distribution depth, and brand architecture consolidation respectively.
| Leading Market Players |
|---|
| BESSEY Tool |
| DEWALT |
| Irwin Tools |
| Pony Jorgensen |
| Stanley Black & Decker |
| Metalmech |
| J F Tools |
| Power Tech India |
| Baweja Industries |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon footprint documentation gates both qualified supply and premium-tier pricing access, filtering non-compliant Asian assemblers from European woodworking cooperative procurement while rewarding REACH-certified manufacturers with margin expansion. This sustainability mandate reshapes supplier qualification timelines and pricing power distribution across the bar clamp market.
Pricing Analysis
Warranty bundling separates professional-grade procurement from economy-tier transactions, with DIN-certified German manufacturers including extended service terms and replacement guarantees that justify 40-60% premiums over unbundled Asian imports. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales support depth, with ISO 9001-certified production commanding sustained premiums. Cost compression in the economy tier intensifies because Chinese forging capacity expansion floods export markets with undifferentiated steel bar stock. DIY enthusiasts through big-box retail channels exhibit highest price sensitivity, while German mid-sized furniture workshops demonstrate lowest sensitivity due to throughput-critical reliability requirements.
Supply Chain Analysis
Freight cost volatility from Yangtze River Delta forging centers to North American distribution hubs compresses margins for non-integrated assemblers sourcing hand-tool steel. Supply concentrates in China, Germany, and India, with Chinese forging capacity feeding bar and jaw production, German engineering centers supplying quick-release mechanism components, and Indian metalmech operations serving price-sensitive regional markets. Raw material dependencies rest on high-carbon tool steel, zinc-nickel plating chemicals, and glass-filled nylon polymers for composite handles. Single-source vulnerability in Chinese forging capacity creates structural risk for brands without diversified steel procurement. Distribution runs through industrial supply cooperatives, big-box retail chains, and direct-to-contractor e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bar clamp market sits in a technology-transition phase as force-sensor embedded jaws with IoT connectivity displace legacy mechanical-only designs in quality-critical bonding operations.
For Market Incumbents: Cement certification leadership by accelerating ISO 9001 and REACH compliance investments before EU Green Deal procurement gates harden, insulating premium positioning from Asian cost competition. Deepen backward integration into hand-tool steel forging to secure input cost stability against Chinese capacity volatility. Control distribution depth in North American industrial supply cooperatives where vendor consolidation is shrinking supplier counts from twelve to four major lines.
For New Entrants and Emerging Players: Smart clamp integration with real-time pressure monitoring offers the most penetrable wedge into German precision tooling standards and Japanese automotive interior manufacturing, where DIN and METI certification requirements filter established competitors. Target Scandinavian prefabricated housing plants and Nagoya-area assembly operators with carbon-fiber reinforced polymer variants addressing operator fatigue reduction. Pursue direct-to-contractor e-commerce channels disintermediating traditional hardware distribution for professional-grade procurement.
For Investors and Strategic Acquirers: Ratchet-actuated mechanism adoption rates in Stuttgart's mid-sized furniture workshops are the leading indicator that automation-ready clamp portfolios will command acquisition premiums over legacy screw-threaded product lines. Long-term viability favors vertically integrated assemblers with captive forging capacity and certified European plating operations. Watch REACH surface coating compliance timelines as the inflection signal for which Asian suppliers can sustain European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging | Captive hand-tool steel production insulates margin from Chinese capacity volatility. |
| REACH Compliance Certification | Zinc-nickel plating investment filters competitors from German and French distribution. |
| Smart Clamp R&D Partnership | Force-sensor IoT convergence targets Japanese automotive interior manufacturers. |
| Direct-to-Contractor E-commerce Launch | Disintermediation captures US Midwest industrial supply cooperative consolidation. |
| Composite Material Manufacturing Scale-Up | Carbon-fiber polymer production serves Scandinavian prefabricated housing operator fatigue priorities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant engineers at German DIN-certified workshops, procurement leads at North American commercial cabinet shops, aftermarket service heads at industrial supply cooperatives, and technical R&D directors at forging-integrated manufacturers. Bottom-up demand modeling triangulated against top-down macroeconomic indicators ensured cross-validation of volume and value outputs.
Granularity-level modeling disaggregated the bar clamp market by product type, material composition, end-user industry, and distribution channel across the analysis window, with additional segmentation by certification tier and regional regulatory cluster. CAGRs derived from trend extrapolation of historical procurement patterns adjusted for technology substitution effects and regulatory compliance timelines. Forecast inputs incorporated EPA volatile organic compound regulation impacts on adhesive open-time requirements and consequent clamping protocol sophistication.
Several conditions sit outside the modeled scope, including potential vacuum pressing system displacement thresholds in high-volume panel manufacturing and unannounced REACH restriction expansions beyond hexavalent chromium finishes. Forecasts reflect documented assumptions about Chinese forging capacity utilization rates and European woodworking cooperative procurement consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Power Tool Gears Market
Tools
Global Cordless Power Tools Market
Tools
Workholding Tools Market
Tools
Gear Cutting Machines Market
Tools
Boring-Milling Machines Market
Tools
Dumpy Level Market
Tools
Thickness Planers Market
Tools
Manual Cutting Equipment Market
Tools
Level Floats Market
Tools
Cutting Tool Inserts Market
Tools
Step Ladder Market
Tools
Telescopic Tool Boxes Market
Tools
Pneumatic Bolting Tools Market
Tools
Striking Tools Market
Tools
Cordless Wood Planer Market
Tools
Coil Fed Punching and Cutting Machines Market