
 Industrial Cleaning Equipment Market | 2026-2036
Industrial Cleaning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Cleaning Equipment Market Outlook
Multi-source procurement for component subsystems is expanding across the industrial cleaning equipment supply base. Nilfisk A/S leverages its Nordic engineering heritage to anchor premium vacuum and scrubber lines in European manufacturing facilities. Alfred Kärcher SE & Co. KG sustains broad product differentiation through captive motor production and direct channel control in commercial cleaning segments. Tennant Company competes aggressively on robotic and autonomous floor care platforms for warehouse and logistics end users.
Industrial cleaning equipment encompasses mechanized systems engineered to remove contaminants, debris, and residues from production environments, operating across pressure ranges from 1,500 to 4,000 PSI in washer configurations and airflow velocities exceeding 100 cubic feet per minute in industrial vacuum designs. These systems serve primary purposes of maintaining operational uptime, ensuring regulatory compliance, and protecting worker safety in continuous-use industrial settings. Floor scrubbers and pressure washers represent mature volume categories where replacement cycles and aftermarket parts generate stable margin pools. Automated and IoT-enabled technology segments are capturing disproportionate growth as manufacturing facilities integrate predictive maintenance and remote monitoring into capital planning.
OSHA workplace sanitation standards, FDA food safety modernization requirements, and EU REACH chemical restriction frameworks collectively elevate baseline specifications for equipment materials and cleaning chemistry compatibility. EPA effluent guidelines in the United States and ECHA substance restrictions in Europe are forcing redesigns of wastewater recovery systems and detergent delivery mechanisms. Stakeholders must weigh regulatory trajectory against automation payback periods when allocating R&D budgets across manual, robotic, and connected product architectures.
Market Dynamics
The migration from standalone cleaning units to integrated facility management systems is compressing replacement cycles and elevating software-embedded equipment specifications across manufacturing verticals.
Growth Catalysts
- MEE environmental compliance in China:Manufacturing clusters in Jiangsu and Guangdong provinces face escalating wastewater discharge standards that mandate closed-loop cleaning systems with real-time effluent monitoring.
- Food safety modernization:FDA enforcement of sanitary transport rules and hazard analysis protocols is compelling US food processors to automate clean-in-place procedures for production line integrity.
- Predictive maintenance integration:IoT sensor networks on scrubber-dryers and pressure washers enable condition-based servicing that reduces unplanned downtime in automotive and logistics facilities.
Market Restraints
- Stainless steel and specialty polymer input costs:Equipment housings and chemical-resistant components face price volatility from nickel supply concentration in Indonesian and Russian mining operations.
- High-voltage motor supplier concentration:Premium efficiency drive systems for industrial vacuums and sweepers rely on a narrow base of German and Japanese component manufacturers.
- REACH chemical authorization delays:ECHA substance restrictions on certain surfactants and solvents force equipment redesigns for detergent compatibility, extending product development timelines.
Strategic Opportunities
- India's pharmaceutical manufacturing corridors:CDSCO good manufacturing practice upgrades and export-oriented production growth create demand for validated cleaning systems in Hyderabad and Ahmedabad clusters.
- Electrolyzed water technology:On-site generation of cleaning and sanitizing solutions eliminates chemical logistics and aligns with corporate sustainability targets in Nordic and German facilities.
- Autonomous mobile robot integration:Warehouse operators in the United States and Germany are piloting collaborative floor care platforms that operate during active shifts without facility shutdown.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of robotic scrubbers and connected pressure systems requires cross-trained personnel fluent in both mechanical systems and network diagnostics.
- CE marking and FDA validation concurrency:Dual-certification requirements for equipment serving multinational food and pharmaceutical accounts create documentation bottlenecks and testing cost duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Cleaning Equipment Market |
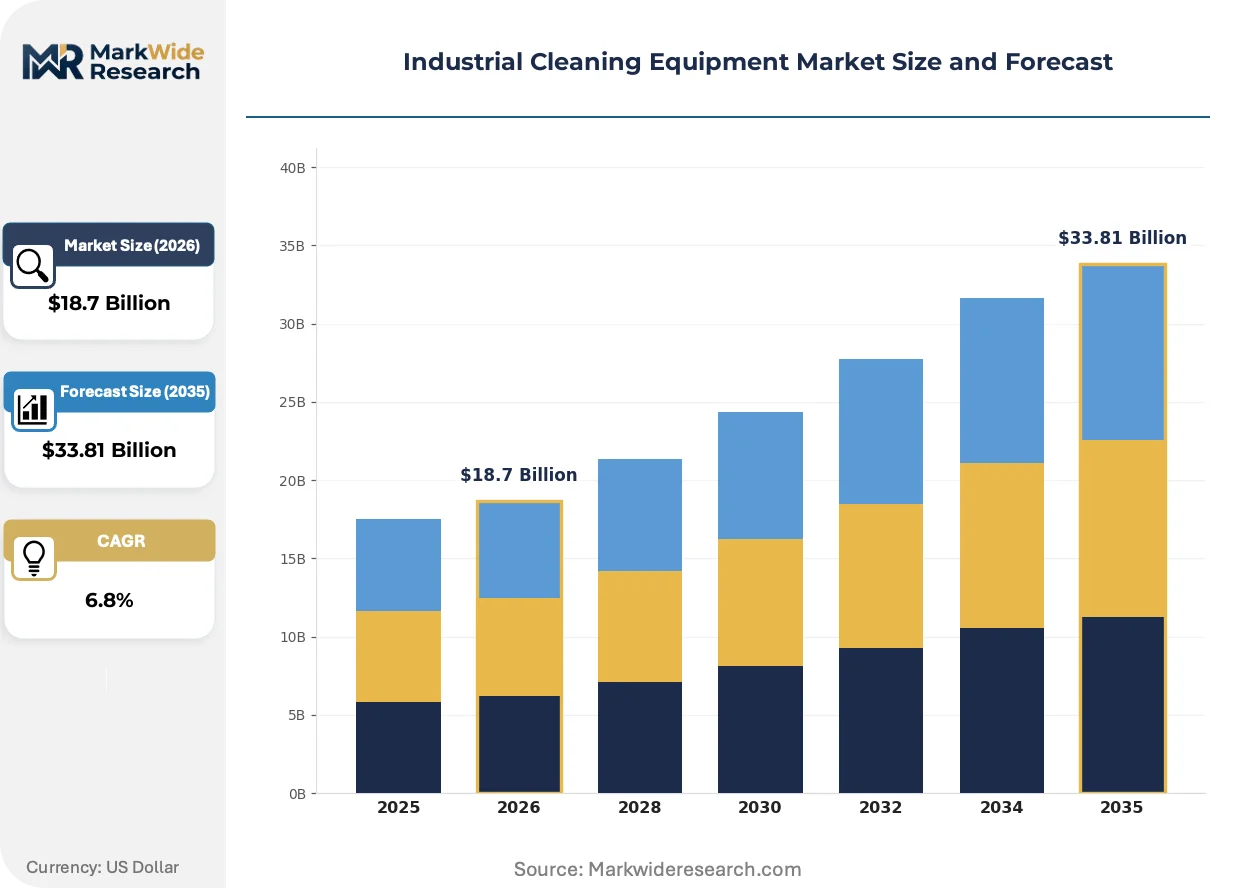
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Washers, Floor Scrubbers, Vacuums, Steam Cleaners Application: Manufacturing Facilities, Warehouses, Food Processing, Automotive Workshops End User: Commercial, Industrial, Government, Residential Technology: Manual, Automated, Robotic, IoT-Enabled |
| Companies Covered | Nilfisk A/S, SBS Ecoclean Group, Ecolab Inc., Fives Group, Rösler, Alfred Kärcher SE & Co. KG, Cleaning Technologies Group, PROCECO, Tennant Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Cleaning Equipment Market Strategic Shifts
Equipment intelligence and chemical minimization are converging to redefine competitive specifications, with connectivity and on-site generation technologies capturing disproportionate engineering investment.
Lithium-ion battery packs with integrated battery management systems are consolidating power architecture across walk-behind scrubbers and ride-on sweepers. Third-party logistics operators and airport maintenance departments are standardizing on these platforms to eliminate engine exhaust in enclosed facilities and reduce acoustic disturbance. The shift is consolidating aftermarket revenue toward battery replacement and electronics servicing rather than combustion engine rebuilds.
EPA effluent guidelines for industrial laundries and food processing facilities are mandating wastewater heat recovery and solids separation in cleaning equipment design. Equipment manufacturers serving US meatpacking and dairy processing plants must engineer integrated recovery modules that capture cleaning water for reuse or controlled discharge. The regulation is compressing equipment footprints and elevating stainless steel fabrication requirements for corrosion resistance.
Leasing and managed service contracts are displacing capital purchase models for high-utilization fleet deployments. Facility management providers in German automotive manufacturing and US distribution centers are bundling equipment, consumables, and maintenance into per-square-meter pricing. The restructuring concentrates procurement authority with national account teams and reduces distributor influence in local specification decisions.
Industrial Cleaning Equipment Market Segmentation
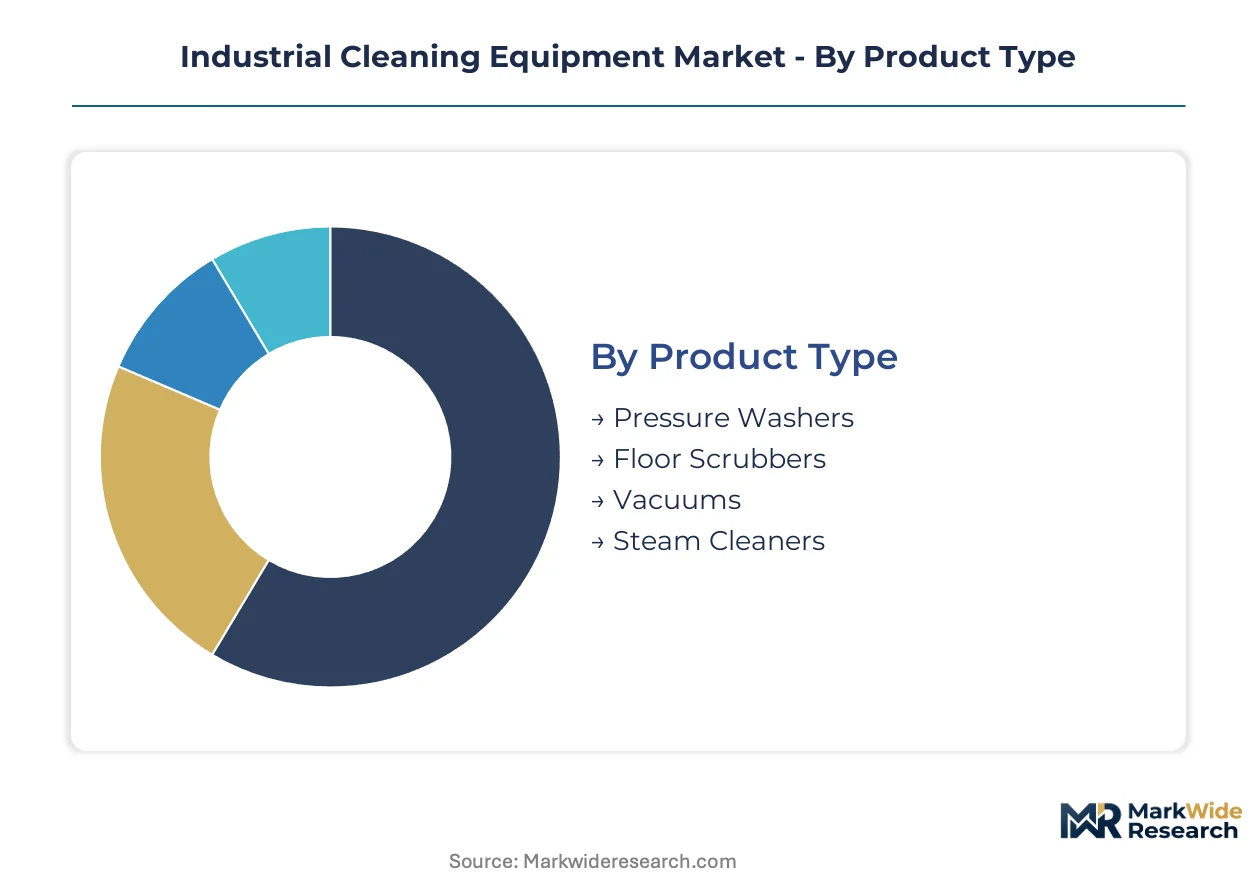
Industrial cleaning equipment segmentation reflects divergent capital deployment strategies across facility types, with automation readiness and regulatory exposure determining specification tiers. Procurement patterns in this market split sharply between cost-driven replacement cycles and technology-forward integrated systems.
Product Type:
Customization intensity varies from standardized pressure washer platforms to application-engineered vacuum architectures requiring subsystem integration.
- Pressure Washers:Cold and hot water configurations span 1,500 to 4,000 PSI operating ranges with diesel, electric, and gasoline power options. Demand concentrates in automotive workshops across Germany and the United States where OSHA surface preparation standards mandate high-pressure removal of chemical residues and coatings.
- Floor Scrubbers:Walk-behind and ride-on configurations integrate cylindrical or disc brush systems with solution recovery tanks. Manufacturing facilities in China's Jiangsu province are retrofitting fleets with lithium-ion battery packs to satisfy MEE emissions compliance in enclosed production environments.
- Vacuums:Wet-dry and HEPA-filtered industrial designs address combustible dust hazards and cleanroom protocols.
- Steam Cleaners:Saturated vapor systems eliminate chemical detergent requirements for facilities targeting REACH-aligned sustainability metrics.
Leading the category by volume: Floor Scrubbers. Expanding most quickly: IoT-Enabled configurations across all product types.
Application:
Facility-specific contamination profiles dictate equipment specification, from heavy debris tolerance to sanitary surface validation requirements.
- Manufacturing Facilities:Continuous-use environments demand equipment with 10,000+ hour duty cycles and modular component access for line-side maintenance. Automotive stamping plants in Michigan and Bavaria are standardizing on predictive maintenance-enabled scrubber fleets to minimize unplanned downtime during multi-shift operations.
- Warehouses:Third-party logistics operators prioritize autonomous navigation and fleet management software integration. Distribution centers in the United States are piloting collaborative robotic scrubbers that operate during active picking shifts without facility shutdown.
- Food Processing:Sanitary design specifications require 3-A SSI-compliant materials and clean-in-place compatibility.
- Automotive Workshops:Oil and solvent exposure drives specification of chemical-resistant housings and explosion-proof electrical components.
Dominant by installed base: Manufacturing Facilities. Steepest expansion trajectory: Food Processing driven by FDA modernization enforcement.
End User:
Procurement authority and payback period expectations separate capital-intensive industrial deployments from service-contract commercial models.
- Commercial:Facility management providers and contract cleaning services dominate volume, with leasing and per-square-meter service contracts displacing equipment ownership. German automotive manufacturing campuses are consolidating procurement authority with national account teams bundling equipment, consumables, and maintenance.
- Industrial:In-house maintenance departments specify integrated systems with OEM service agreements and guaranteed uptime clauses. Pharmaceutical manufacturers in Hyderabad and Ahmedabad are validating cleaning systems against CDSCO good manufacturing practice upgrades for export-oriented production.
- Government:Municipal and defense procurement emphasizes domestic content requirements and extended warranty terms.
- Residential:Light-duty pressure washers and compact steam cleaners serve homeowner and small contractor segments.
Revenue concentration sits with: Industrial. Gaining share fastest: Commercial through managed service contract expansion.
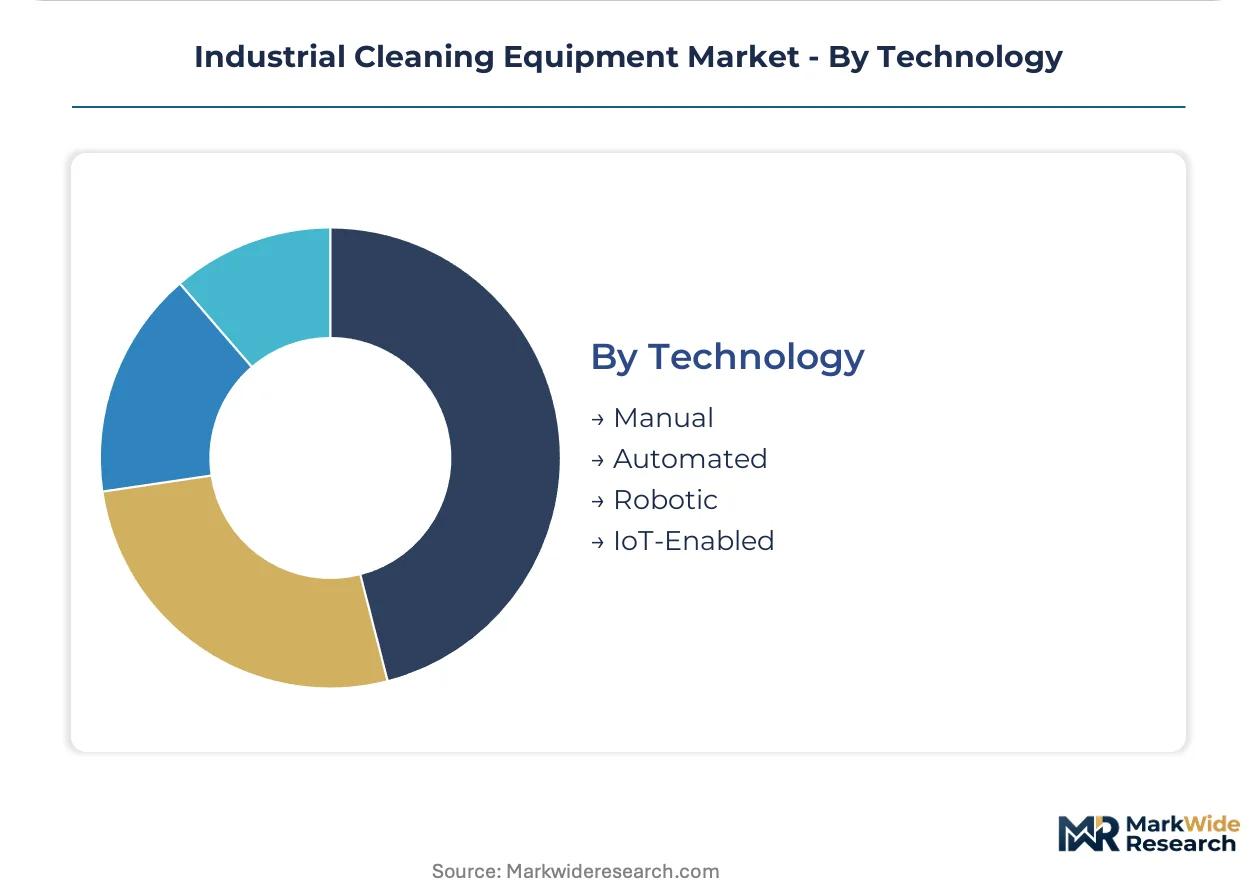
Technology:
Control architecture sophistication determines pricing tiers and aftermarket revenue composition across the technology spectrum.
- Automated:Programmable logic controller-driven systems with preset cleaning paths and chemical dosing reduce labor dependency. Food processors in the United States are automating clean-in-place procedures to satisfy FDA sanitary transport rule enforcement and hazard analysis protocol requirements.
- IoT-Enabled:Sensor networks transmit equipment health, location, and utilization data to cloud-based fleet management platforms. Logistics operators in Germany are deploying connected scrubber-dryers with condition-based servicing algorithms that optimize maintenance scheduling across distributed facility networks.
- Manual:Operator-dependent systems without electronic control modules serve cost-sensitive replacement markets.
- Robotic:Autonomous mobile platforms with LiDAR navigation and collaborative safety systems operate without human supervision.
Highest volume segment: Manual. Technology investment is concentrating in: IoT-Enabled systems with predictive maintenance integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian nickel mining districts supply the stainless steel feedstock that shapes equipment housing economics across manufacturing clusters in Germany, China, and the United States. Raw material price volatility propagates through component costs for corrosion-resistant vacuum housings and pressure washer frames.
United States
Food processing plants in Wisconsin and California are retrofitting clean-in-place systems under FDA sanitary transport rule enforcement. OSHA workplace sanitation standards mandate high-pressure surface preparation in automotive workshops across Michigan and Ohio. Third-party logistics operators in Dallas-Fort Worth and Chicago are piloting autonomous floor care platforms during active warehouse shifts.
Germany
Automotive stamping facilities in Bavaria and Baden-Württemberg standardize on predictive maintenance-enabled scrubber fleets to minimize multi-shift downtime. ECHA REACH chemical restrictions force equipment redesigns for surfactant compatibility in detergent delivery systems. Manufacturing campuses in Stuttgart and Wolfsburg consolidate procurement authority with national account teams bundling equipment and maintenance services.
China
Manufacturing corridors in Jiangsu and Guangdong provinces face escalating MEE wastewater discharge standards mandating closed-loop cleaning systems. IoT-enabled equipment with real-time effluent monitoring captures disproportionate capital expenditure in Shanghai and Shenzhen industrial zones. Domestic battery pack integration is displacing combustion engine architectures in walk-behind scrubber fleets.
India
Pharmaceutical manufacturers in Hyderabad and Ahmedabad validate cleaning systems against CDSCO good manufacturing practice upgrades for export-oriented production. Contract cleaning services in Mumbai and Delhi-NCR are transitioning from capital purchase models to per-square-meter managed service contracts. Leasing structures concentrate procurement decisions with facility management providers rather than end-user maintenance departments.
Japan
Precision manufacturing facilities in Aichi and Kanagawa prefectures demand HEPA-filtered vacuum systems for cleanroom protocols in semiconductor and electronics assembly. METI energy efficiency guidelines accelerate lithium-ion battery adoption in ride-on sweeper fleets. Equipment suppliers in Nagoya and Yokohama are integrating sensor networks for condition-based servicing algorithms across distributed facility networks.
Industrial Cleaning Equipment Market Competitive Environment
Global majors compete with regional champions across automation readiness and regulatory compliance capabilities. The vendor base stratifies between premium-tier engineering specialists and volume-driven fleet operators. Three archetypes dominate: Nordic heritage premium equipment fabricators, captive-motor integrated manufacturers, and robotic platform specialists. Consolidation pressures concentrate around M&A activity targeting IoT software capabilities and strategic partnerships for battery supply security.
Among European heritage manufacturers, Nilfisk A/S and Alfred Kärcher SE & Co. KG exemplify contrasting scale positions within premium-tier vacuum and scrubber lines. Tennant Company occupies a position on the automation vector for warehouse and logistics end users. These three anchors illustrate how geographic origin and company structure correlate with strategic emphasis on either engineering depth or fleet management platform development.
| Leading Market Players |
|---|
| Nilfisk A/S |
| SBS Ecoclean Group |
| Ecolab Inc. |
| Fives Group |
| Rösler |
| Alfred Kärcher SE & Co. KG |
| Cleaning Technologies Group |
| PROCECO |
| Tennant Company |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA-validated pharmaceutical systems and standard manufacturing equipment manifests in both pricing architecture and supply chain sourcing strategies. Premium-tier suppliers anchor pricing through captive service networks and guaranteed uptime clauses, while commodity equipment flows through distributor channels with unbundled aftermarket terms. Stainless steel grade specifications and IoT module integration separate pricing bands across German automotive and Chinese electronics manufacturing corridors.
Pricing Analysis
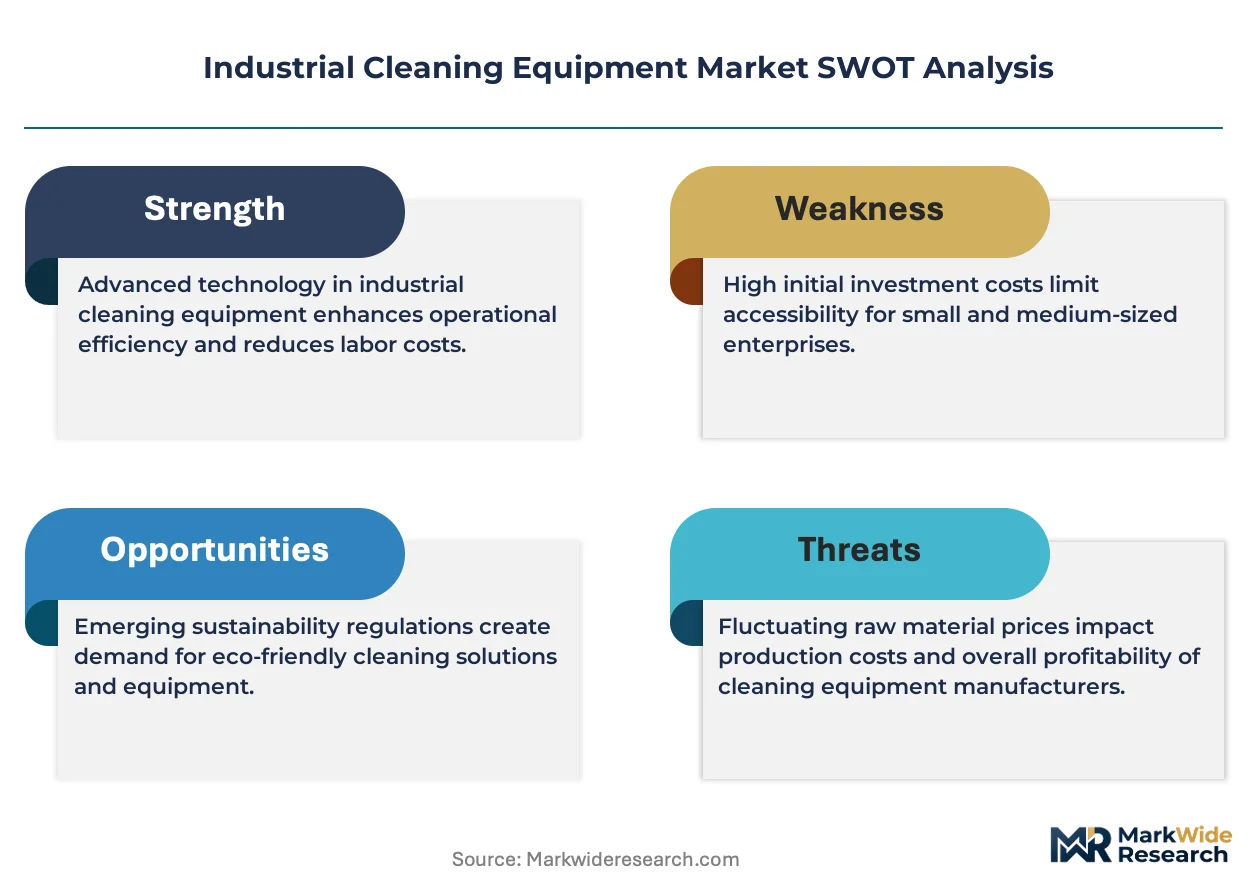
Warranty and service-bundling terms separate equipment procurement models across end-user segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with FDA-validated systems commanding substantial premiums over CE-marked alternatives. Price differentiation hinges on predictive maintenance software inclusion and guaranteed response time commitments. Cost compression in standard-tier walk-behind scrubbers is intensifying because lithium-ion battery pack commoditization erodes hardware margins. Third-party logistics operators exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize validation documentation over unit economics.
Supply Chain Analysis
Refurbishment and remanufacturing flows for industrial vacuum motors and pressure washer pumps concentrate aftermarket value recovery in Germany and Japan. Primary manufacturing draws from China for battery pack assembly, Indonesia for nickel-bearing stainless steel, and Germany for high-voltage drive systems. Supply chain risk centers on single-source vulnerability for premium efficiency motors from Japanese and German component specialists. Distribution runs through national account teams for fleet deployments and specialized industrial distributors for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial cleaning equipment supply is tightening around certified component capacity, with battery management system integration and REACH-compliant material sourcing propping pricing power for qualified suppliers.
For Market Incumbents: Lock in battery supply agreements with South Korean and Chinese cell manufacturers before capacity allocation tightens further. Secure backward integration into stainless steel fabrication for corrosion-resistant housings to defend against nickel price volatility from Indonesian mining concentration. Prioritize CE-FDA dual-certification engineering teams to reduce documentation bottlenecks for multinational pharmaceutical accounts. For New Entrants and Emerging Players: Capture managed service contract white space in Indian pharmaceutical corridors where CDSCO validation requirements outpace local equipment supply. Target electrolyzed water technology deployment in Nordic facilities seeking REACH-aligned chemical elimination. Pursue autonomous mobile robot partnerships with warehouse operators in Dallas-Fort Worth and Chicago distribution clusters. For Investors and Strategic Acquirers: Re-rating potential sits with IoT software specialists given predictive maintenance integration accelerating across automotive and logistics end users. Long-term viability favors platforms with fleet management data assets and condition-based servicing algorithms. Monitor MEE enforcement intensity in Jiangsu and Guangdong provinces as inflection indicator for closed-loop system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Production | Captive lithium-ion supply secures margins against cell price volatility in Jiangsu manufacturing zones. |
| Dual-Certification Engineering Investment | Concurrent CE-FDA validation capability reduces time-to-revenue for multinational pharmaceutical accounts. |
| Electrolyzed Water Technology Licensing | On-site generation eliminates REACH-regulated chemical logistics for German food processing facilities. |
| Autonomous Mobile Robot Fleet Partnerships | Collaborative navigation platforms capture warehouse uptime value in Dallas-Fort Worth distribution centers. |
| Managed Service Contract Expansion | Per-square-meter pricing concentrates procurement authority with national account teams in Stuttgart automotive campuses. |
Study Parameters
Trade databases, regulatory filings, and equipment manufacturer technical specifications formed the secondary backbone of this analysis. Primary interviews with maintenance directors at automotive stamping plants, pharmaceutical facility engineers in Hyderabad, and aftermarket service heads at European OEMs validated demand assumptions. Bottom-up and top-down triangulation cross-checked segment sizing against customs data for pressure washer and scrubber-dryer imports.
Bottom-up modeling anchored volume projections to facility-level equipment replacement cycles and automation adoption curves. Segmentation dimensions spanned product type, application vertical, technology tier, and regional regulatory cluster. CAGRs were derived from weighted average of replacement demand and greenfield installation trajectories across the projection horizon. Forecast inputs incorporated MEE compliance timelines, FDA enforcement intensity, and battery cost decline curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel supply disruption and REACH chemical authorization delays. Forecasts reflect documented assumptions on regulatory trajectory and automation payback period acceptance. Practitioners should monitor CDSCO inspection intensity in Indian pharmaceutical corridors and EPA effluent guideline expansion scope for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Striking Tools Market
Tools
Parting-Off Blades Market
Tools
Global Swaging Machine Market
Tools
Cordless Impact Wrench Market
Tools
Structural Wood Screws Market
Tools
Global Diamond Tools Market
Tools
Shredder Blades Market
Tools
Global Sandblasting Media Market
Tools
Auger Drill Bits Market
Tools
Surface Levelling Equipment Market
Tools
Laser Engraving Machine Market
Tools
Drilling Tools Market
Tools
Woodworking Sanders Market
Tools
Cutting Equipment Market
Tools
Turning Tools Market
Tools
Floor Scraper Market