
 Stationary Wood Planer Market | 2026-2036
Stationary Wood Planer Market Size, Share, and Industry Trends Forecast 2026-2036
Stationary Wood Planer Market Insights
Spiral and helical cutterhead technology is reshaping how stationary wood planers deliver surface finish and reduce noise in production workshops. DeWalt leverages its cordless-to-corded brand extension to sustain presence in mid-market carpentry workshops. Grizzly Industrial anchors its position through direct-to-fabricator distribution and broad SKU coverage across benchtop and floor-standing formats. Powermatic competes on cast-iron construction heritage and precision-adjustment mechanisms that appeal to custom woodworking shops.
A stationary wood planer is a fixed-base machine that removes material from timber surfaces through rotating cutterheads, typically operating at cutter speeds between 4,000 and 10,000 RPM with bed widths ranging from 12 to 24 inches for industrial units; its primary purpose is dimensioning lumber to precise thickness and smoothness for downstream manufacturing. Thickness planers occupy the highest volume position because furniture OEMs and flooring mills require consistent dimensional reduction across high-throughput lines. Spiral cutterhead technology leads replacement demand as carbide-insert systems extend edge-life intervals and reduce sharpening downtime compared to traditional HSS straight knives. Multi-blade configurations retain dominance in European cabinetry workshops where finish quality requirements exceed North American construction-grade tolerances.
OSHA machine guarding standards in the United States and CE machinery directives under European regulation shape cutterhead enclosure designs and emergency-stop configurations, while China's GB standards for woodworking machinery safety influence export-platform manufacturing decisions. Compliance with these frameworks determines market access for equipment imported into regulated jurisdictions. Stakeholders must monitor evolving blade-guard interoperability requirements and energy-efficiency labeling expansions that could segment procurement criteria between premium and standard equipment tiers.
Market Dynamics
Spiral cutterhead technology is compressing replacement cycles across furniture OEMs and flooring mills as carbide-insert systems extend operational intervals and reduce sharpening downtime.
Growth Catalysts
- Workshop Automation Mandates:Furniture OEMs in Germany and the United States are retrofitting production lines with automated thickness planers to reduce labor dependency and dimensional variance.
- OSHA Machine Guarding Standards:Updated cutterhead enclosure requirements in the United States are accelerating equipment replacement among commercial carpentry shops seeking compliance certification.
- Spiral Cutterhead Adoption:Carbide-insert cutterheads are penetrating North American and European production environments as operators prioritize noise reduction and surface finish consistency.
Market Restraints
- Cast-Iron Input Volatility:Foundry capacity constraints in China and India are pressuring bed and frame production costs for floor-standing industrial units.
- CE Machinery Directive Compliance:European emergency-stop and blade-guard interoperability requirements are extending certification timelines for equipment imported from non-EU manufacturing platforms.
- Used Equipment Substitution:Secondary markets for refurbished straight-knife planers are absorbing price-sensitive demand from entry-level carpentry workshops in Eastern Europe and Southeast Asia.
Strategic Opportunities
- India Woodworking Cluster Expansion:Furniture export zones in Gujarat and Tamil Nadu are underpenetrated by precision planer distributors serving medium-scale fabricators.
- EU Green Deal Incentives:Energy-efficiency labeling expansions are creating procurement preference shifts toward premium-tier equipment with variable-frequency drive motors.
- Direct-to-Fabricator E-Commerce:Digital channels are bypassing traditional machinery dealers to reach custom woodworking shops with configurable benchtop and floor-standing formats.
Industry Challenges
- Cutterhead Alignment Specialist Shortage:Precision-adjustment mechanics capable of calibrating spiral insert systems are scarce in North American service networks.
- Legacy Control System Integration:Workshop management software in established European cabinetry shops requires middleware development to interface with modern planer feedback sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stationary Wood Planer Market |
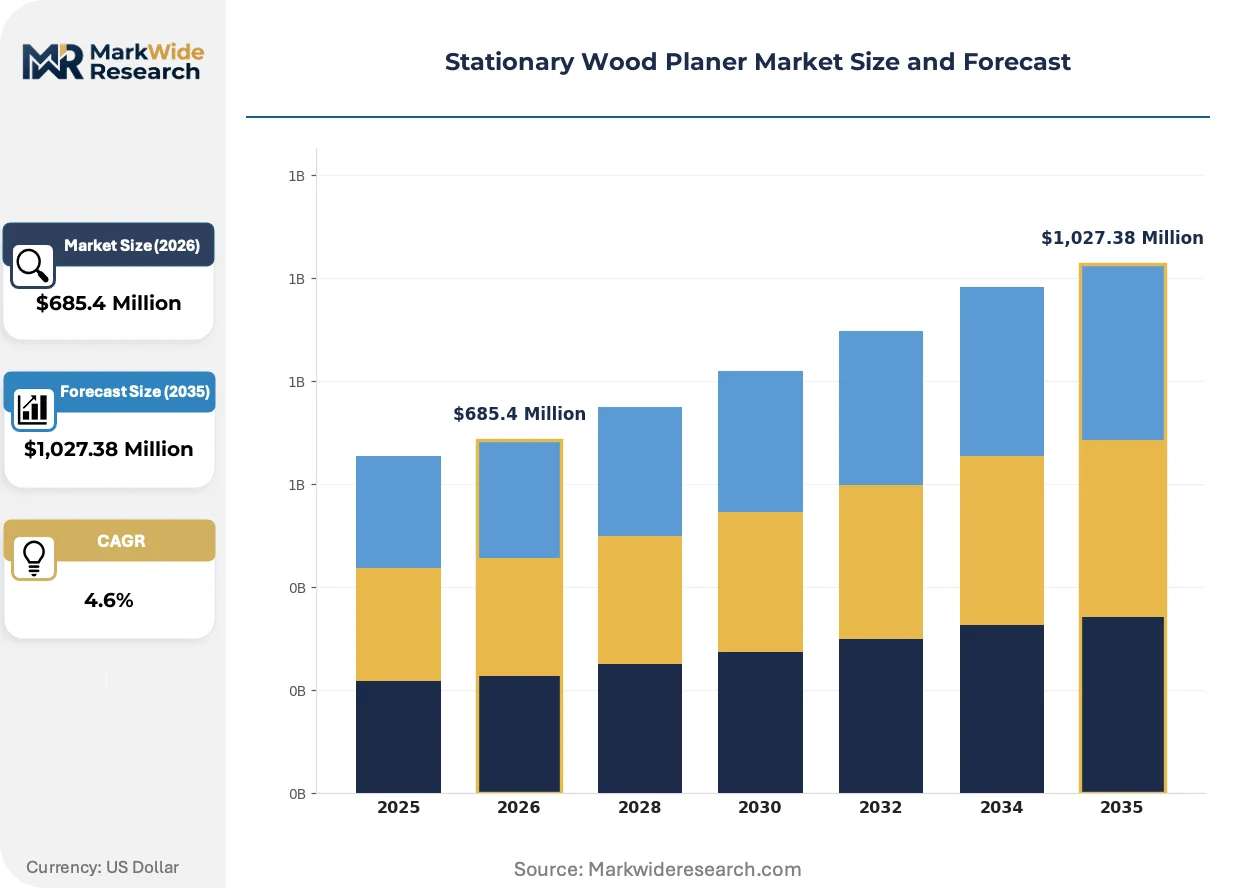
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,027.38 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Blade, Multi-Blade, Combination Planer, Thickness Planer, Surface Planer Technology: Cutterhead, Spiral Cutterhead, Helical Cutterhead, Carbide-Tipped Blades, Abrasive Belt Application: Furniture Manufacturing, Cabinetry, Wooden Flooring, Boat Building, Musical Instrument Production End User: Carpentry Workshops, Wood Fabricators, Custom Woodworking Shops, Educational Institutions, Furniture OEMs |
| Companies Covered | DeWalt, JET, Grizzly Industrial, Powermatic, Baileigh Industrial, Delta, Bosch, Makita, RIDGID, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stationary Wood Planer Market Trends and Innovations
Equipment manufacturers are converging on cutterhead geometries and control interfaces that reduce operator skill requirements while tightening dimensional tolerances for downstream manufacturing.
Spiral cutterhead technology is migrating from high-end custom woodworking shops into mid-market furniture OEMs. Carbide-insert systems with four-sided cutting edges deliver 30-50x edge life versus high-speed steel straight knives. The technology is migrating from premium-positioned equipment into standard industrial tiers as insert costs decline and sharpening service networks contract.
REACH chemical restrictions on chromium plating processes are forcing European manufacturers toward alternative bed surface treatments. Hard-anodized aluminum and ceramic-coated steel beds are replacing traditional chrome-plated castings in equipment destined for EU markets. German and Italian producers are accelerating plasma-spray coating investments to maintain surface durability compliance.
Buying committees at flooring mills are consolidating vendor relationships around full-line machinery suppliers. Single-source procurement contracts covering planers, jointers, and sanders are displacing best-of-breed equipment selection. This concentration is most visible in United States hardwood flooring production clusters where capital approval authority has shifted from plant managers to regional procurement directors.
Stationary Wood Planer Market Segmentation
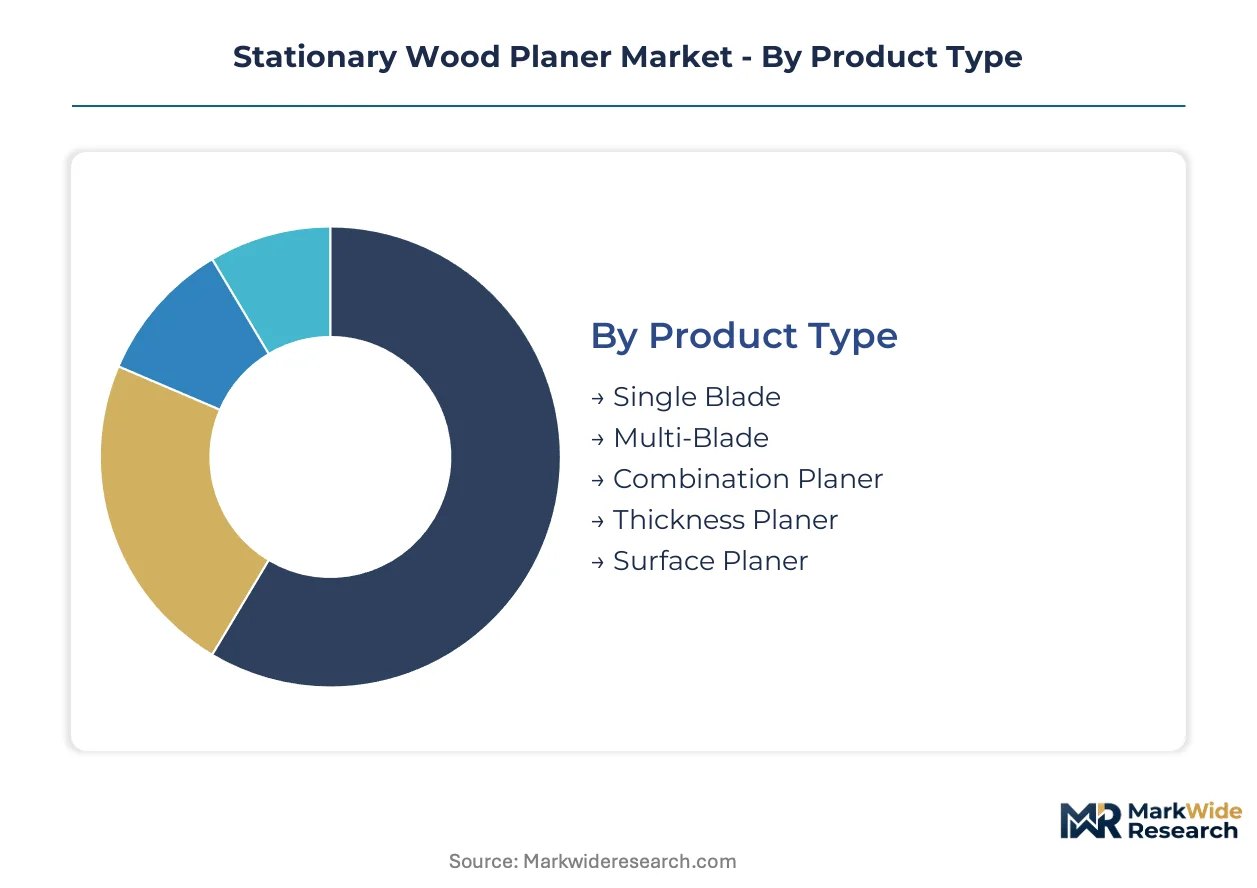
Segmentation in stationary wood planers reveals how cutterhead technology and end-use specialization drive equipment replacement cycles. Workshop automation mandates and regulatory compliance requirements create divergent demand patterns across product tiers and customer categories.
Product Type:
Thickness planers turn over fastest in high-volume flooring mills, while combination units cycle slowest in small custom shops. Replacement intervals compress where dimensional tolerances tighten.
- Thickness Planer:These machines dominate furniture OEM throughput lines with bed widths spanning 12 to 24 inches. Flooring mills in the United States and Germany drive replacement demand as automated infeed systems reduce labor dependency and dimensional variance. Thickness planers anchor the volume base while spiral cutterhead variants gain share at the steepest rate.
- Multi-Blade:European cabinetry workshops specify these units where finish quality requirements exceed North American construction-grade tolerances. German and Italian producers prioritize four-sided machining capability for high-end millwork. Multi-blade configurations retain dominance in precision segments despite slower replacement cycles.
- Single Blade:Entry-level carpentry workshops in Eastern Europe deploy these units for rough dimensioning tasks.
- Combination Planer:Custom woodworking shops favor dual-purpose machines integrating jointer and planer functions.
- Surface Planer:Timber mills use these for initial rough sizing before secondary thickness processing.
Thickness planers command the highest installed base while combination formats expand most quickly among mid-market fabricators.
Technology:
Cost tiers separate premium carbide-insert systems from standard high-speed steel configurations. Capital deployment concentrates where edge-life economics justify upfront premiums.
- Spiral Cutterhead:Carbide-insert systems deliver 30-50x edge life versus traditional straight knives. North American furniture OEMs accelerate adoption as sharpening service networks contract and noise reduction mandates intensify. Spiral cutterhead technology is compressing replacement cycles across production environments.
- Helical Cutterhead:These configurations optimize shear angles for figured hardwoods in custom musical instrument production. Premium woodworking shops in Germany and the United States specify helical geometries where tear-out elimination justifies higher capital outlay. Helical systems climb the fastest in high-value segments.
- Carbide-Tipped Blades:Flooring mills specify these for abrasive composite materials that degrade standard steel edges.
- Cutterhead:Conventional straight-knife systems persist in price-sensitive markets through lower initial acquisition cost.
- Abrasive Belt:Specialized applications in boat building use belt sanding heads for final surface preparation.
Spiral cutterheads anchor premium procurement budgets while helical variants penetrate custom segments at the steepest trajectory.
Application:
Customer type determines specification intensity, with OEMs demanding telemetry integration and workshops prioritizing mechanical simplicity.
- Furniture Manufacturing:Automated thickness planers with feedback sensors dominate high-volume upholstery and casegoods production. United States and Chinese OEMs retrofit lines to reduce dimensional variance and labor dependency. Furniture manufacturing commands the largest equipment installed base.
- Wooden Flooring:Hardwood flooring clusters in the United States consolidate vendor relationships around full-line machinery suppliers. Regional procurement directors now control capital approval, displacing plant-level best-of-breed selection. Wooden flooring applications show the steepest vendor consolidation.
- Cabinetry:European workshops specify multi-blade precision units for frame-and-panel construction.
- Boat Building:Marine-grade timber processors require corrosion-resistant bed surfaces and extended infeed tables.
- Musical Instrument Production:Figured tone-wood specialists demand helical cutterheads minimizing tear-out on curly maple and koa.
Furniture manufacturing anchors volume procurement while wooden flooring drives the fastest vendor relationship restructuring.
End User:
Volume scale separates industrial OEMs from artisan workshops, with educational institutions representing a distinct replacement cycle.
- Furniture OEMs:These manufacturers deploy automated infeed and outfeed systems across 24-inch industrial bed widths. OSHA machine guarding standards accelerate equipment replacement as certification requirements tighten. Furniture OEMs anchor the highest-value procurement tier.
- Custom Woodworking Shops:Direct-to-fabricator e-commerce channels now reach these operators with configurable benchtop and floor-standing formats. Grizzly Industrial and similar distributors bypass traditional machinery dealers. Custom woodworking shops expand most quickly as digital procurement penetrates mid-market segments.
- Carpentry Workshops:Commercial construction-focused operators face OSHA compliance-driven replacement cycles.
- Wood Fabricators:Secondary processors supplying construction materials prioritize throughput over finish quality.
- Educational Institutions:Vocational programs specify guarded, low-RPM units for student safety compliance.
Furniture OEMs anchor industrial procurement volume while custom woodworking shops gain digital channel access at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Furniture OEMs in Germany, the United States, and China concentrate the majority of precision woodworking equipment procurement, with spiral cutterhead technology penetration varying sharply by regulatory environment and labor cost structure.
United States
Hardwood flooring clusters in Tennessee and Kentucky drive thickness planer replacement cycles as automated infeed systems reduce labor dependency. OSHA machine guarding standards accelerate equipment turnover among commercial carpentry shops seeking compliance certification. Regional procurement directors now control capital approval authority, consolidating vendor relationships around full-line machinery suppliers.
Germany
Precision cabinetry workshops in Baden-Württemberg specify multi-blade configurations where finish quality requirements exceed construction-grade tolerances. EU Green Deal incentives and REACH chemical restrictions on chromium plating reshape bed surface treatment investments. Stuttgart-area producers accelerate plasma-spray coating adoption to maintain surface durability compliance.
China
Export-platform manufacturers serving regulated jurisdictions face GB standards compliance pressures for woodworking machinery safety. Foundry capacity constraints in Hebei and Shandong provinces pressure cast-iron bed production costs for floor-standing industrial units. Yangtze River Delta fabricators retrofit lines with spiral cutterhead variants as carbide-insert costs decline.
India
Furniture export zones in Gujarat and Tamil Nadu remain underpenetrated by precision planer distributors serving medium-scale fabricators. BIS certification requirements and state-level industrial incentives shape procurement timelines for woodworking clusters. Morbi and Jodhpur ceramics-to-furniture transition zones attract first-time automated planer installations.
Italy
High-end millwork producers in Veneto and Emilia-Romagna prioritize four-sided machining capability for frame-and-panel construction. CE machinery directive compliance extends certification timelines for equipment imported from non-EU manufacturing platforms. Bologna-area machinery districts specialize in helical cutterhead geometries for figured hardwood applications.
Stationary Wood Planer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where direct-to-fabricator e-commerce disrupts traditional machinery dealer networks. The vendor base separates into three strategic archetypes: heritage brands leveraging cast-iron construction credibility, direct-distribution specialists optimizing SKU breadth, and power-tool conglomerates extending cordless-to-corded brand equity. Competitive moves concentrate on geographic expansion through digital channels and portfolio diversification into automated infeed systems.
Among North American heritage-positioned manufacturers, Powermatic and Grizzly Industrial exemplify divergent channel strategies. Powermatic occupies a position within the premium-tier cast-iron construction segment. Grizzly Industrial anchors the direct-to-fabricator distribution archetype with broad format coverage. DeWalt represents the power-tool conglomerate extension model, leveraging brand equity from adjacent cordless equipment categories.
| Leading Market Players |
|---|
| DeWalt |
| JET |
| Grizzly Industrial |
| Powermatic |
| Baileigh Industrial |
| Delta |
| Bosch |
| Makita |
| RIDGID |
| Others |
Pricing and Supply Chain Analysis
Foundry capacity concentration in Hebei and Shandong provinces anchors cast-iron bed production costs, pushing margin pools toward carbide-insert cutterhead suppliers and spiral system assemblers who command pricing power through technical differentiation.
Pricing Analysis
Cost-plus contracts with iron ore indexation dominate floor-standing industrial unit procurement, tying final equipment pricing to volatile foundry input costs. Pricing stratifies across premium spiral-cutterhead tiers, standard helical configurations, and economy straight-knife systems based on certification grade and after-sales service bundling. Cost compression in entry-level benchtop segments is intensifying because refurbished equipment substitution absorbs price-sensitive demand. Custom woodworking shops exhibit highest price sensitivity, while furniture OEMs prioritize total cost of ownership over acquisition outlay.
Supply Chain Analysis
Export-control regimes on precision machining equipment limit cutterhead geometry transfers from German and Italian producers to Chinese manufacturing platforms. Supply draws from German cast-iron foundries, Chinese steel mills, and Taiwanese carbide-insert suppliers. Single-source vulnerability concentrates in spiral cutterhead bearing assemblies sourced from Japanese precision manufacturers. Distribution runs through direct-to-fabricator e-commerce channels and traditional machinery dealer networks serving distinct customer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stationary wood planer market tracks a cyclical recovery pattern tied to furniture OEM capital expenditure cycles, with replacement demand accelerating as OSHA compliance deadlines and workshop automation mandates converge.
For Market Incumbents: Entrench position through captive supply of carbide-insert cutterheads and backward integration into foundry partnerships that secure cast-iron bed allocation. Spiral cutterhead specialist acquisitions neutralize emerging entrant threats from Asian precision component suppliers. Channel control investments in direct-to-fabricator digital platforms lock in custom woodworking shop relationships before price erosion penetrates mid-market tiers. For New Entrants and Emerging Players: Mid-market furniture fabricators in Gujarat and Tamil Nadu export zones represent the most penetrable entry point, with BIS certification gaps creating temporary procurement windows for non-domestic equipment. Helical cutterhead geometries for figured hardwood applications offer technical differentiation against established straight-knife suppliers. Go-to-market execution through regional woodworking machinery trade associations bypasses entrenched dealer relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial equipment platforms holding dated straight-knife product portfolios and legacy distribution footprints. Long-term viability hinges on spiral cutterhead technology migration capability and e-commerce channel development over a five-to-ten year holding horizon. The signal to watch is OSHA machine guarding standard revision timing, which would force accelerated replacement cycles and valuation multiple expansion for compliant equipment manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Spiral Cutterhead Technology Migration | Carbide-insert systems extend edge-life intervals and reduce sharpening downtime for furniture OEMs. |
| Direct-to-Fabricator E-Commerce Expansion | Digital channels bypass traditional machinery dealers to reach custom woodworking shops with configurable formats. |
| Backward Integration into Foundry Operations | Captive cast-iron bed production secures supply allocation amid Hebei and Shandong capacity constraints. |
| CE Machinery Directive Certification Investment | European emergency-stop and blade-guard compliance opens regulated market access for export-platform manufacturers. |
| Automated Infeed System Development | Integrated material handling reduces labor dependency and dimensional variance in high-throughput flooring mills. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at furniture OEMs, maintenance directors at flooring mills, procurement leads at cabinetry workshops, and aftermarket service heads at machinery distributors. Secondary validation drew from OSHA machine guarding enforcement records, CE machinery directive compliance databases, customs and trade data on woodworking equipment imports, and foundry capacity reports from Hebei and Shandong provinces. Bottom-up equipment shipment tallies and top-down furniture production forecasts were triangulated to anchor market sizing.
Calibration against historical replacement cycles and regulatory compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include cutterhead technology tier, bed width specification, end-use application intensity, and regional regulatory cluster. CAGRs were derived from equipment shipment momentum and capital expenditure patterns across the analysis window. Forecast inputs incorporated spiral cutterhead adoption curves and workshop automation penetration rates by customer tier.
Practitioners should monitor OSHA standard revision announcements, EU Green Deal incentive expansions, and foundry capacity utilization rates for early signals of forecast deviation. Material shifts in cast-iron input costs or carbide-insert supply availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Set Screw Market
Tools
Spindle Shaper Market
Tools
Sanding Machine Market
Tools
Europe Machine Tools Market
Tools
Air Hammer Market
Tools
Europe Paint Spray Guns Market
Tools
Oxy-Fuel Torches Market
Tools
Stand Tile Saw Market
Tools
Asia Pacific Power Tools Market
Tools
Cordless Power Drill Market
Tools
Caulking Gun Market
Tools
Tapping Machine Market
Tools
Power Drill Market
Tools
Technical Drawing Tools Market
Tools
Drill Presses Market
Tools
Hydraulic Tools and Equipment Market