
 Bearing Installation Tool Kit Market | 2026-2036
Bearing Installation Tool Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Bearing Installation Tool Kit Market Insights
Chrome-vanadium steel is hardening as the dominant alloy in premium bearing installation tool kits, displacing older carbon-steel formulations that lacked fatigue resistance under high-torque industrial use. SKF leverages its integrated bearing-to-tool ecosystem to capture recurring aftermarket demand across European manufacturing plants. Timken anchors North American supply through specialized railway maintenance tool configurations. Schaeffler differentiates via precision-engineered hydraulic press sets targeting aerospace component fitting applications.
A bearing installation tool kit comprises calibrated sleeves, drivers, extractors, and alignment devices engineered to specific tolerance classes, typically manufactured through CNC machining of hardened alloy steels with surface treatments achieving 58-62 HRC for wear resistance. Its primary purpose is to eliminate axial misalignment and raceway damage during bearing mounting and dismounting operations across rotating equipment. Hydraulic tools command the widest application footprint in heavy machinery assembly due to force consistency requirements, while battery-powered motorized operation is gaining traction in maintenance shops where cord-free mobility reduces downtime. Pneumatic tools retain cost advantages in high-volume equipment overhaul facilities but face margin compression from electric alternatives.
FDA device-quality standards influence aerospace and medical-adjacent precision engineering firms through traceability mandates on tool calibration cycles. EPA metalworking fluid regulations and OSHA ergonomic directives shape material selection and handle design for US-based manufacturing plants. The EU Machinery Directive and CE marking requirements govern motorized tool safety interlocks for European distribution. Stakeholders must weigh battery-platform standardization against pneumatic infrastructure lock-in when configuring product portfolios for multi-regional deployment.
Market Dynamics
Chrome-free alloy mandates under REACH and RoHS are forcing rapid material transitions across European manufacturing plants, while battery-platform standardization debates split procurement committees between pneumatic infrastructure retention and cordless electric adoption.
Growth Catalysts
- Railway maintenance modernization:Heavy machinery overhaul facilities in Germany are expanding precision tool inventories to meet stricter wheel bearing service intervals mandated by national transport safety frameworks.
- REACH material compliance:European manufacturers are replacing chrome-plated steel components with polymer composite and ceramic-coated alternatives, generating replacement demand across existing tool fleets.
- Hydraulic precision systems:Aerospace component fitting operations are specifying calibrated press sets with force feedback sensors to eliminate raceway damage during high-value bearing mounting.
Market Restraints
- Alloy input cost volatility:Chrome-vanadium steel pricing fluctuates with ferroalloy commodity markets, compressing margins for tool manufacturers serving price-sensitive automotive tier-one suppliers.
- Specialized supplier concentration:Precision-machined sleeve production clusters in southern Germany and northern Italy, creating geographic vulnerability for kit assemblers dependent on just-in-time component flows.
- Manual tool substitution:Basic hammer-and-chisel methods persist in informal maintenance shops across emerging industrial regions, limiting addressable market expansion for calibrated installation systems.
Strategic Opportunities
- Medical device manufacturing:FDA traceability mandates for tool calibration cycles are opening premium segments for digitally-logged installation kits with automated certification documentation.
- Battery-electric convergence:Integration of torque-sensing smart handles with standardized battery platforms is creating cordless mobility advantages in aircraft hangar and wind turbine nacelle maintenance.
- OSHA ergonomic alignment:US-based manufacturing plants are retrofitting tool fleets with vibration-dampened polymer handles to preempt enforcement actions under federal workplace safety directives.
Industry Challenges
- Metrology technician scarcity:Qualified personnel for HRC hardness verification and dimensional tolerance auditing are concentrated among aging workforces in traditional machining centers.
- CE marking timeline compression:Motorized tool safety interlock documentation for European distribution requires extended third-party conformity assessment periods that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bearing Installation Tool Kit Market |
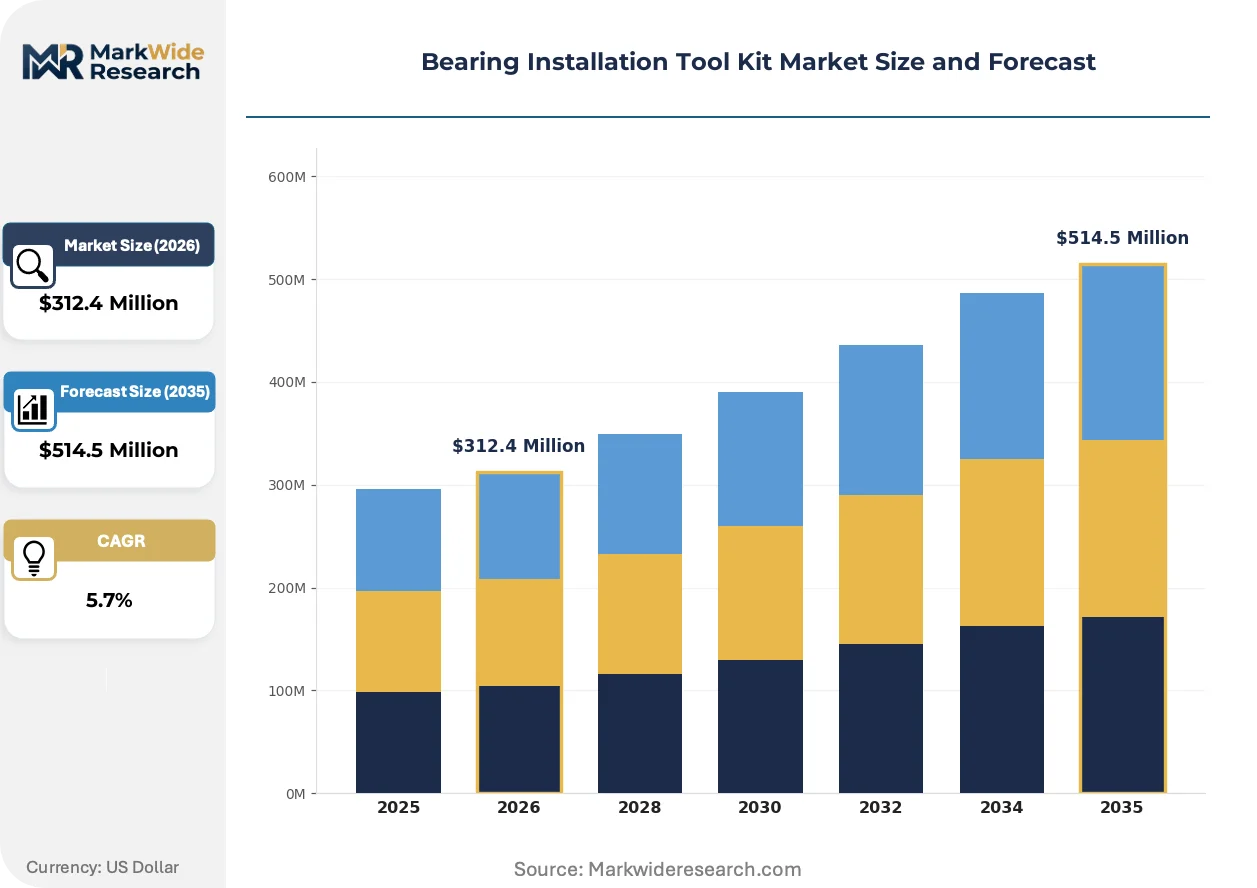
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $514.5 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Tools, Mechanical Tools, Pneumatic Tools, Electric Tools Technology: Manual Operation, Motorized Operation, Battery Powered, Air Pressure Driven Application: Heavy Machinery Assembly, Aerospace Component Fitting, Railway Equipment Maintenance, Marine Engine Repair End User: Manufacturing Plants, Maintenance Shops, Equipment Overhaul Facilities, Precision Engineering Firms |
| Companies Covered | SKF, NSK, FAG, Timken, NTN, Schaeffler, JTEKT, Gates, Powerbuilt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bearing Installation Tool Kit Market Trends and Innovations
Digital torque logging and predictive calibration alerts are embedding intelligence directly into hand tools, compressing the traditional separation between installation hardware and quality assurance systems.
Smart sensor-integrated drivers are decentralizing quality control from centralized metrology labs to the point of bearing installation. Automotive OEMs in Stuttgart and Wolfsburg are piloting Bluetooth-enabled torque wrenches that stream force curves to manufacturing execution systems. This distributed verification architecture is reducing rework rates while eliminating bottlenecks at final inspection stations.
EPA metalworking fluid regulations are restricting chlorinated paraffin formulations used in tool grinding operations, forcing manufacturers toward synthetic ester alternatives with shorter bath life cycles. Grinding shops in Michigan and Ohio are retooling coolant recovery systems to maintain surface finish specifications on hardened alloy sleeves. The compliance burden falls heaviest on mid-volume kit producers lacking captive finishing capabilities.
Maintenance departments are unbundling after-sales calibration contracts from original tool purchases, treating metrology services as separately sourced commodities. Railway operators in Chicago and Los Angeles are negotiating multi-vendor calibration pools rather than single-source dependencies. This procurement fragmentation is pressuring SKF and Timken service divisions to compete on turnaround speed rather than installed base lock-in.
Bearing Installation Tool Kit Market Segmentation
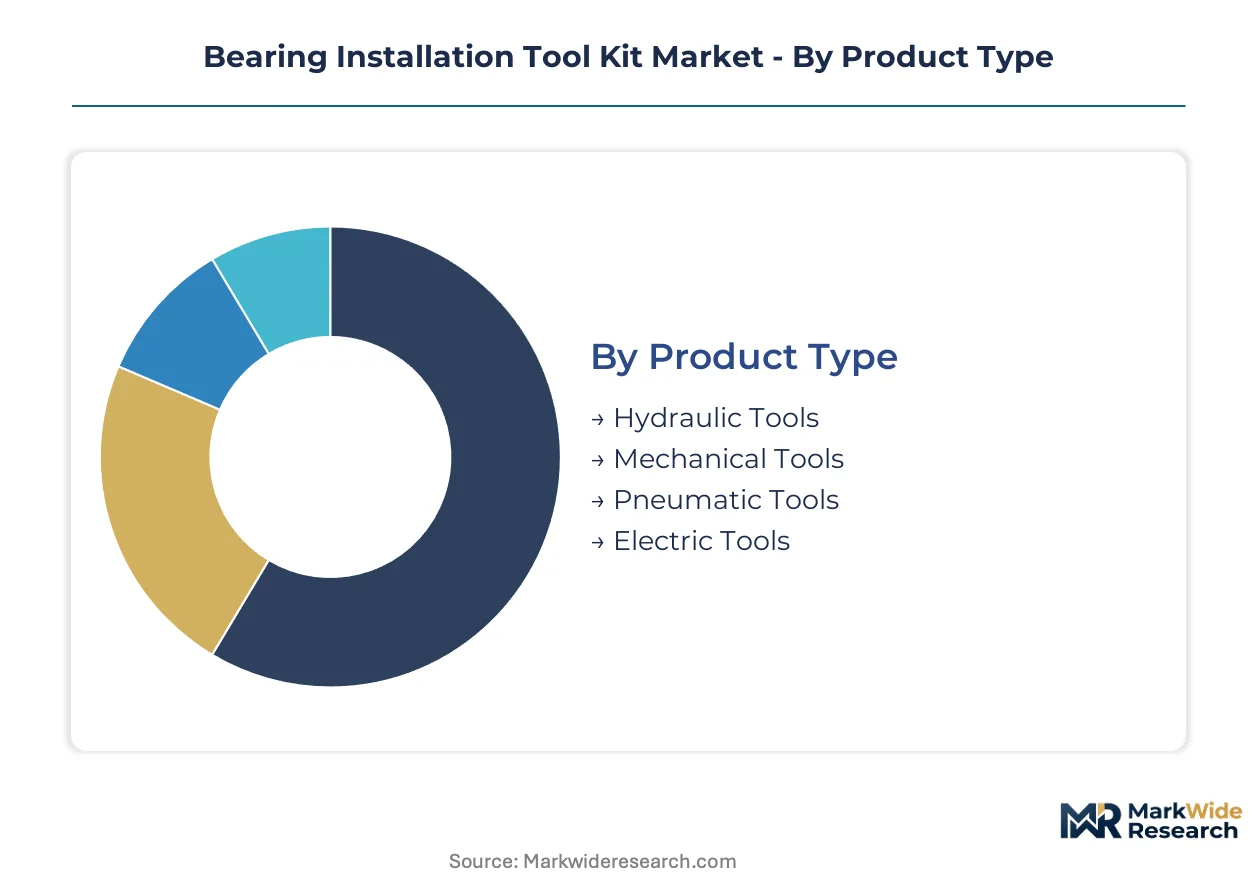
Segmentation in the bearing installation tool kit market reveals divergent procurement patterns between integrated production systems and standalone maintenance operations. Tool specification varies sharply across these boundaries, with hydraulic and motorized configurations dominating continuous assembly lines while mechanical tools persist in intermittent repair contexts.
Product Type:
Standalone installation tools serve discrete maintenance events, while embedded hydraulic systems integrate permanently into production line infrastructure.
- Hydraulic Tools:These systems deploy calibrated force through oil-pressure cylinders, achieving consistent axial loads up to 50 tons for large-diameter bearing mounting. Demand concentrates in German heavy machinery assembly plants where force feedback sensors eliminate raceway damage during high-value component fitting. REACH chrome-free mandates are redirecting European procurement toward polymer-composite housing variants.
- Mechanical Tools:Manual screw presses and impact drivers fabricated from chrome-vanadium steel deliver portable force application without power infrastructure. Railway maintenance shops across the United States retain these tools for field wheel bearing service where hydraulic power is unavailable. Basic hammer-and-chisel substitution in informal emerging-market shops limits addressable expansion.
- Pneumatic Tools:Compressed-air impact wrenches and presses offer rapid cycling in high-volume environments.
- Electric Tools:Corded and battery-powered motorized drivers are gaining traction in aircraft hangar and wind turbine nacelle maintenance where mobility reduces downtime.
Volume placements concentrate in hydraulic tools; the faster expansion belongs to electric tools.
Technology:
Cost tier stratification separates premium sensor-integrated motorized systems from economy manual alternatives.
- Manual Operation:Hand-powered screw mechanisms and impact drivers require no external energy source, minimizing capital outlay for small maintenance shops. Equipment overhaul facilities in emerging industrial regions default to these tools where calibration infrastructure is absent. OSHA ergonomic directives are forcing handle redesigns toward vibration-dampened polymer composites.
- Motorized Operation:Electric and pneumatic motor systems deliver consistent torque output through gear reduction, eliminating operator-dependent force variation. Aerospace component fitting operations in Stuttgart and Wolfsburg specify these for Bluetooth-enabled torque curve streaming to manufacturing execution systems. FDA traceability mandates are opening premium segments for digitally-logged variants.
- Battery Powered:Lithium-ion cordless platforms enable deployment in confined spaces without pneumatic infrastructure.
- Air Pressure Driven:Compressed-air systems retain cost advantages in high-volume facilities with existing compressor infrastructure.
Procurement volume clusters in manual operation; battery powered technology is climbing the fastest.
Application:
Application segmentation tracks customer maturity, with precision-engineered aerospace fitting commanding premium pricing against commodity-heavy machinery assembly.
- Heavy Machinery Assembly:Continuous production lines for mining equipment and industrial presses demand hydraulic press sets with force feedback integration. Manufacturing plants in China and Germany represent the densest demand concentrations. EPA metalworking fluid regulations are restricting chlorinated paraffin grinding formulations used in tool production.
- Aerospace Component Fitting:Aircraft engine and landing gear bearing installation requires calibrated press sets with 0.01mm alignment precision and full calibration documentation. Precision engineering firms serving Boeing and Airbus supply chains face FDA device-quality traceability mandates on tool certification cycles. Force consistency requirements eliminate manual tool substitution.
- Railway Equipment Maintenance:Wheel bearing service intervals mandated by national transport safety frameworks are expanding precision tool inventories in Chicago and Los Angeles.
- Marine Engine Repair:Shipboard maintenance operations prioritize corrosion-resistant tool coatings for saltwater environments.
Revenue concentration sits with heavy machinery assembly; aerospace component fitting shows the steepest expansion trajectory.
End User:
End user type determines procurement centralization, with manufacturing plants integrating tools into capital budgets while maintenance shops treat them as consumable expenses.
- Manufacturing Plants:OEM and tier-one supplier facilities specify integrated bearing-to-tool ecosystems with recurring aftermarket calibration contracts. Automotive assembly operations in Wolfsburg and Stuttgart pilot smart sensor-integrated drivers that decentralize quality control to installation points. Battery-platform standardization debates split procurement committees between pneumatic retention and cordless adoption.
- Maintenance Shops:Independent repair facilities prioritize tool portability and rapid turnaround over force precision, sourcing mid-tier mechanical and electric configurations. Railway operators are unbundling calibration contracts from original purchases, treating metrology services as separately sourced commodities. OSHA ergonomic alignment is retrofitting fleets with vibration-dampened handles.
- Equipment Overhaul Facilities:High-volume remanufacturing operations favor pneumatic tools for rapid cycling.
- Precision Engineering Firms:Medical-adjacent and aerospace subcontractors demand digitally-logged installation kits with automated certification documentation.
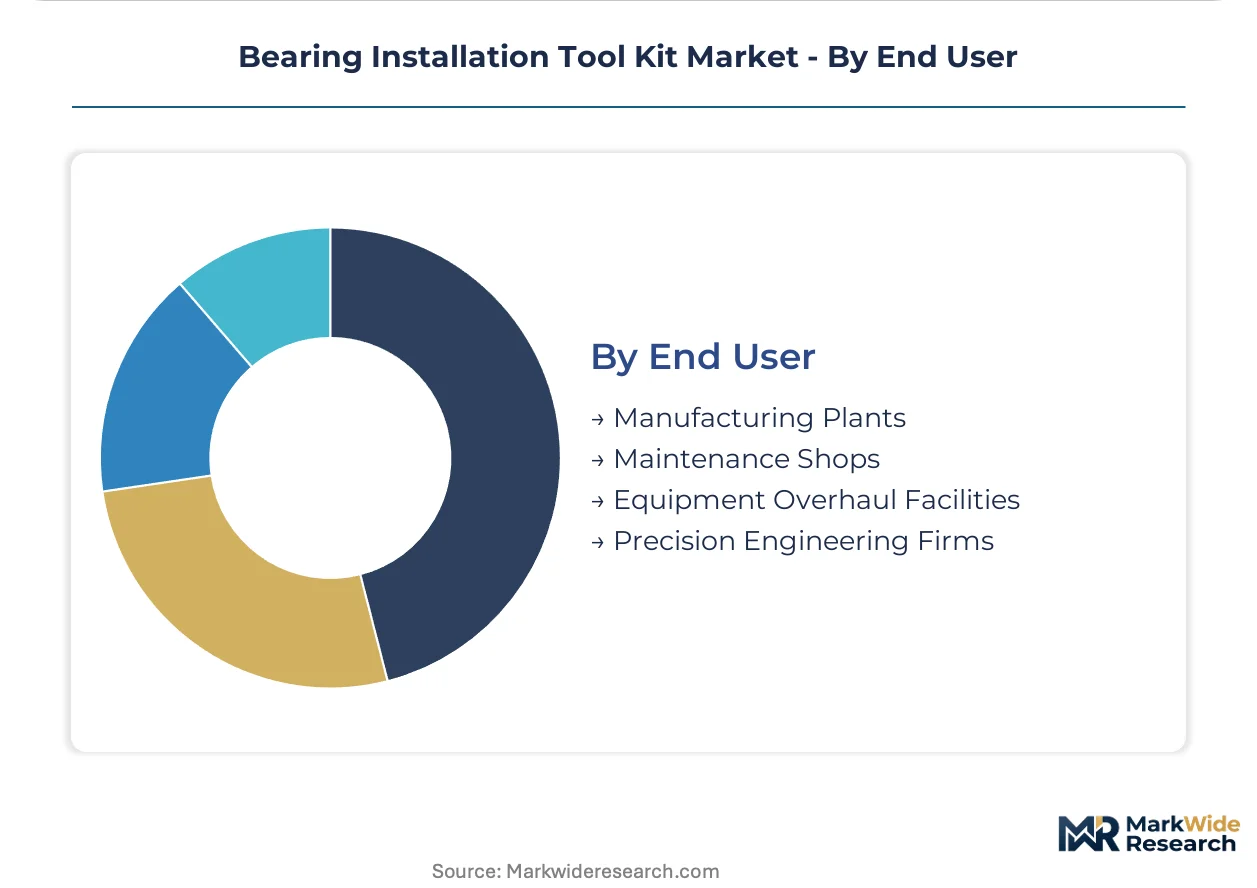
Procurement volume aggregates in manufacturing plants; precision engineering firms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the United States as these countries host the densest concentrations of heavy machinery assembly and railway maintenance operations.
United States
Railway maintenance shops in Chicago and Los Angeles are expanding precision tool inventories to meet stricter wheel bearing service intervals. OSHA ergonomic directives are forcing handle redesigns toward vibration-dampened polymer composites. Michigan and Ohio grinding shops are retooling coolant recovery systems to maintain surface finish specifications under EPA metalworking fluid regulations.
Germany
Heavy machinery overhaul facilities are adopting hydraulic press sets with force feedback sensors to eliminate raceway damage. REACH chrome-free mandates are redirecting procurement toward polymer-composite housing variants. Manufacturing plants in Stuttgart and Wolfsburg pilot Bluetooth-enabled torque wrenches that stream force curves to manufacturing execution systems.
China
Continuous production lines for mining equipment and industrial presses drive hydraulic tool demand. MIIT industrial upgrading programs are accelerating precision manufacturing capability investments. Manufacturing clusters in the Yangtze River Delta represent the densest demand concentrations for bearing installation systems.
Japan
Precision engineering firms serving aerospace supply chains face METI quality infrastructure requirements on tool certification cycles. JIS standards govern motorized tool safety specifications for domestic distribution. Industrial concentrations in Nagoya and Osaka anchor automotive tier-one supplier procurement.
India
Emerging equipment overhaul facilities default to mechanical tools where calibration infrastructure remains underdeveloped. BIS standards are gradually tightening dimensional tolerance requirements for imported tool kits. Manufacturing investments in Maharashtra and Gujarat are creating new demand pockets for mid-tier installation systems.
Bearing Installation Tool Kit Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated bearing-to-tool ecosystems commanding premium positioning in automotive OEM procurement. The vendor base organizes around three strategic archetypes: full-stack bearing manufacturers extending into installation hardware, dedicated tool fabricators serving maintenance shops, and regional machining houses supplying unbranded components. Competitive moves concentrate on battery-platform standardization alliances and REACH-compliant material transitions.
Within the integrated manufacturing tier, SKF leverages its bearing-to-tool ecosystem to capture recurring aftermarket demand, while Timken anchors North American supply through specialized configurations. Schaeffler occupies a precision-engineered position targeting aerospace component fitting applications. These three exemplify how vertical scope advantages translate into differentiated procurement relationships across manufacturing plants and maintenance operations.
| Leading Market Players |
|---|
| SKF |
| NSK |
| FAG |
| Timken |
| NTN |
| Schaeffler |
| JTEKT |
| Gates |
| Powerbuilt |
| Others |
Pricing and Supply Chain Analysis
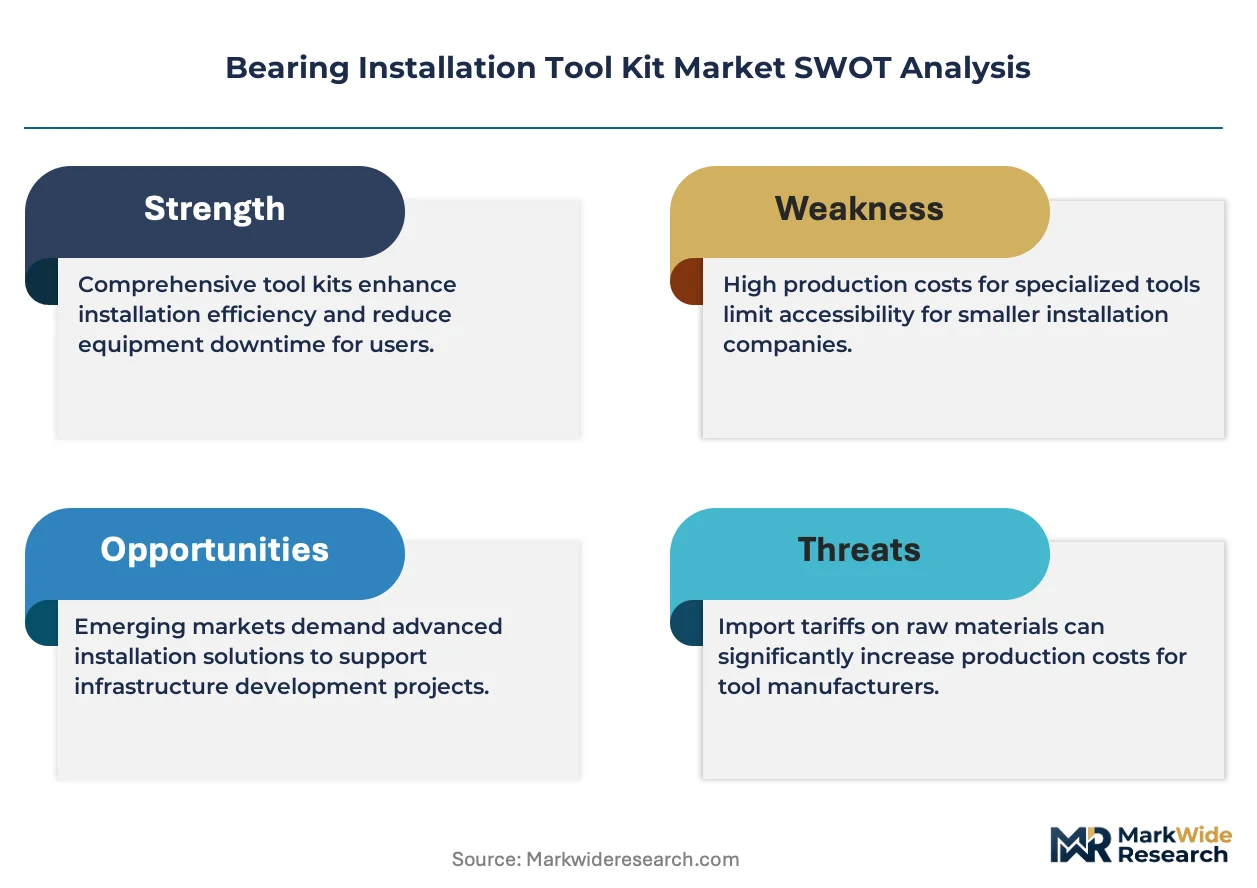
Battery-platform standardization debates are simultaneously compressing cost economics for cordless electric configurations and fragmenting procurement committees between pneumatic infrastructure retention and cordless adoption. Chrome-vanadium steel input volatility feeds directly into margin pressure across tier-one supplier contracts, while REACH-compliant material transitions in Europe force parallel cost absorption and sourcing diversification.
Pricing Analysis
High-volume placements cluster in hydraulic tools where force consistency commands premium positioning, while electric tools face sharper margin compression despite faster expansion. Pricing stratifies across premium sensor-integrated systems, standard motorized configurations, and economy manual alternatives. Cost compression in mid-tier mechanical tools intensifies as informal maintenance shops in emerging industrial regions default to basic hammer-and-chisel substitution. Automotive OEM procurement committees exhibit lowest price sensitivity given integration requirements, while independent maintenance shops treat tool acquisition as consumable expense with aggressive vendor negotiation.
Supply Chain Analysis
Single-source vulnerability sits with precision-machined sleeve production concentrated in southern Germany and northern Italy, creating geographic exposure for kit assemblers dependent on just-in-time component flows. Chrome-vanadium steel draws from ferroalloy commodity markets spanning South Africa, China, and Kazakhstan, while polymer composite housings source from specialized compounders in Germany and Japan. Tariff exposure runs through cross-border component flows between European machining centers and Asian assembly operations. Distribution runs through authorized dealer networks for branded ecosystems alongside direct procurement contracts for manufacturing plant integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bearing installation tool kit market sits in a technology-transition phase as battery-powered motorized operation displaces pneumatic infrastructure in maintenance mobility applications.
For Market Incumbents: Anchor aftermarket service revenue through unbundled calibration contracts that compete on turnaround speed rather than installed base lock-in. Deepen captive supply of precision-machined sleeves to offset geographic concentration risk in southern Germany and northern Italy. Defend against emerging electric tool specialists by accelerating battery-platform alliances with standardized torque-sensing smart handle integration.
For New Entrants and Emerging Players: Railway maintenance shops represent the most penetrable channel partner type given procurement fragmentation and multi-vendor calibration pool adoption in Chicago and Los Angeles. Target precision engineering firms serving aerospace supply chains where FDA traceability mandates open premium segments for digitally-logged installation kits. Pursue white-label manufacturing partnerships with mid-volume kit producers lacking captive finishing capabilities under EPA metalworking fluid compliance burdens.
For Investors and Strategic Acquirers: Re-rating potential sits with digitally-integrated tool specialists given battery-electric convergence catalysts in aircraft hangar and wind turbine nacelle maintenance. Long-term viability favors acquisition targets with established calibration service infrastructure and REACH-compliant material transition completion. Monitor battery-platform standardization alliance announcements as inflection indicators for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Platform Standardization Alliance | Torque-sensing smart handle integration with cordless mobility reduces aircraft hangar downtime. |
| REACH-Compliant Material Transition | Polymer-composite housing variants redirect European procurement away from chrome-plated steel. |
| Calibration Service Unbundling | Railway operators in Chicago negotiate multi-vendor pools treating metrology as commodity purchase. |
| Precision Sleeve Captive Production | In-house machining capability offsets geographic concentration risk in southern Germany supply. |
| Bluetooth-Enabled Torque Logging | Automotive OEMs in Stuttgart stream force curves to manufacturing execution systems for quality control. |
Research Methodology
Multi-period observation of bearing installation tool procurement patterns, regulatory compliance timelines, and alloy input cost movements anchored the trend analysis, supplemented by interviews with maintenance directors at heavy machinery assembly plants, procurement leads at automotive tier-one suppliers, aftermarket service heads at bearing manufacturers, and plant engineers at railway equipment overhaul facilities. Secondary validation drew from REACH substance restriction databases, EPA metalworking fluid enforcement records, OSHA ergonomic directive filings, and customs trade data on precision tool imports. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Input-output matrices modeled relationships between raw alloy pricing, machining capacity utilization, and end-user procurement cycles across the projection horizon. Segmentation dimensions included product type, technology tier, application precision requirements, and end-user procurement centralization. CAGRs derived from fitted growth curves applied to baseline expenditure estimates, with cross-validation against equipment investment cycles in heavy machinery and transport safety framework compliance deadlines in railway maintenance.
Caveats apply where ferroalloy commodity volatility, CE marking timeline compression for motorized tools, or metrology technician scarcity in traditional machining centers could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Hacksaw Blades Market
Tools
Spray Gun Market
Tools
End Milling Machine Market
Tools
Electric Power Tools Market
Tools
Leather Cutting Machine Market
Tools
Riveting Tools Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Saw Blades Market
Tools
Europe Paint Spray Guns Market
Tools
Striking Tools Market
Tools
Portable Milling Machine Market
Tools
Lathe Machines Market
Tools
Log Splitters Market
Tools
Cutting Tools Market
Tools
Portable Boring Machines Market
Tools
Wood-Sanding Machine Market