
 Screw Fastener Market | 2026-2036
Screw Fastener Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Fastener Market Analytics
Modular fastener kits bundled with torque-limiting accessories is restructuring how industrial buyers evaluate total cost of ownership. Fastenal leverages its branch network to control same-day delivery channels in North America. Illinois Tool Works sustains premium positioning through specialized automotive fastening systems. Würth Group anchors European aftermarket demand with its dense field sales organization.
A screw fastener is a threaded mechanical device manufactured through cold heading, thread rolling, or machining processes, typically specified by tensile strength class, thread pitch, and drive type, designed to clamp components through axial preload. Steel remains the dominant material by volume, though stainless steel commands margin pools in corrosive-environment applications. Self-tapping screws represent the fastest-growing product category, driven by thin-gauge metal joining in electronics and appliance housings. Construction end-use absorbs the largest volume share, while automotive fastener specifications are tightening toward lighter-weight, higher-strength grades.
ISO 898-1 governs carbon and alloy steel fastener mechanical properties, while REACH restricts hexavalent chromium in plating chemistries, forcing coating transitions toward zinc-flake and organic alternatives. China's SAMR enforces GB standards for structural bolt assemblies used in infrastructure and energy projects. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal reshape material certification requirements and supplier qualification timelines.
Market Dynamics
Electric vehicle battery pack architectures are forcing fastener suppliers to retool for high-torque stainless specifications, while REACH and China's GB standards simultaneously tighten material disclosure windows. This dual pressure is compressing supplier qualification timelines and fragmenting procurement across automotive and construction verticals.
Growth Catalysts
- EV battery assembly expansion:Battery pack manufacturers specify Grade A2-70 and A4-80 stainless fasteners for thermal cycling resistance. Automotive OEMs in Germany and South Korea are qualifying new suppliers for 800V platform architectures.
- REACH Annex XVII restrictions:ECHA's hexavalent chromium ban in plating chemistries is forcing coating transitions toward zinc-flake and organic alternatives. European construction equipment manufacturers are accelerating compliant fastener procurement.
- India's construction equipment corridor:Excavator and crane assembly plants in Pune and Chennai are absorbing high-volume carbon steel fastener shipments. BIS certification requirements are standardizing local supplier bases.
Market Restraints
- Alloy steel input volatility:Molybdenum and nickel price swings compress margin pools for high-tensile fastener grades. Cold heading mills face working capital pressure from 60-day raw material hedging windows.
- Supplier concentration in East Asia:Thread rolling capacity clusters in China's Zhejiang and Jiangsu provinces. Western buyers face extended lead times and tariff exposure on precision-machined specialty grades.
- Titanium substitution in aerospace:Solid rivets and blind bolts displace threaded fasteners in primary airframe joints. Boeing and Airbus specifications favor integral fastening for weight-critical assemblies.
Strategic Opportunities
- Modular torque-limiting kits:Bundled fastener and tool systems capture aftermarket service revenue. Industrial maintenance teams in US manufacturing belts are adopting subscription-based consumable replenishment.
- EU Green Deal material certification:EPD-compliant low-carbon steel fasteners command premium positioning in German automotive supplier corridors. Lifecycle assessment data is becoming a bid qualification requirement.
- Self-tapping screw penetration in electronics:Thin-gauge metal joining in appliance housings and server chassis is displacing riveted joints. Taiwanese contract manufacturers are specifying thread-forming variants for aluminum extrusions.
Industry Challenges
- Metallurgical talent scarcity:Cold heading process engineers with alloy optimization expertise are concentrated at retiring demographics. North American fastener producers face 18-month training pipelines for skilled setup technicians.
- Dual certification timeline compression:IATF 16949 automotive and ISO 14001 environmental audits now run in parallel. Supplier qualification costs for Tier 1 OEM entry have doubled since 2020.
- Legacy ERP integration with traceability systems:Batch-level material genealogy requirements for aerospace and medical fasteners conflict with decades-old shop floor data architectures. Mid-size producers face six-figure system replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Fastener Market |
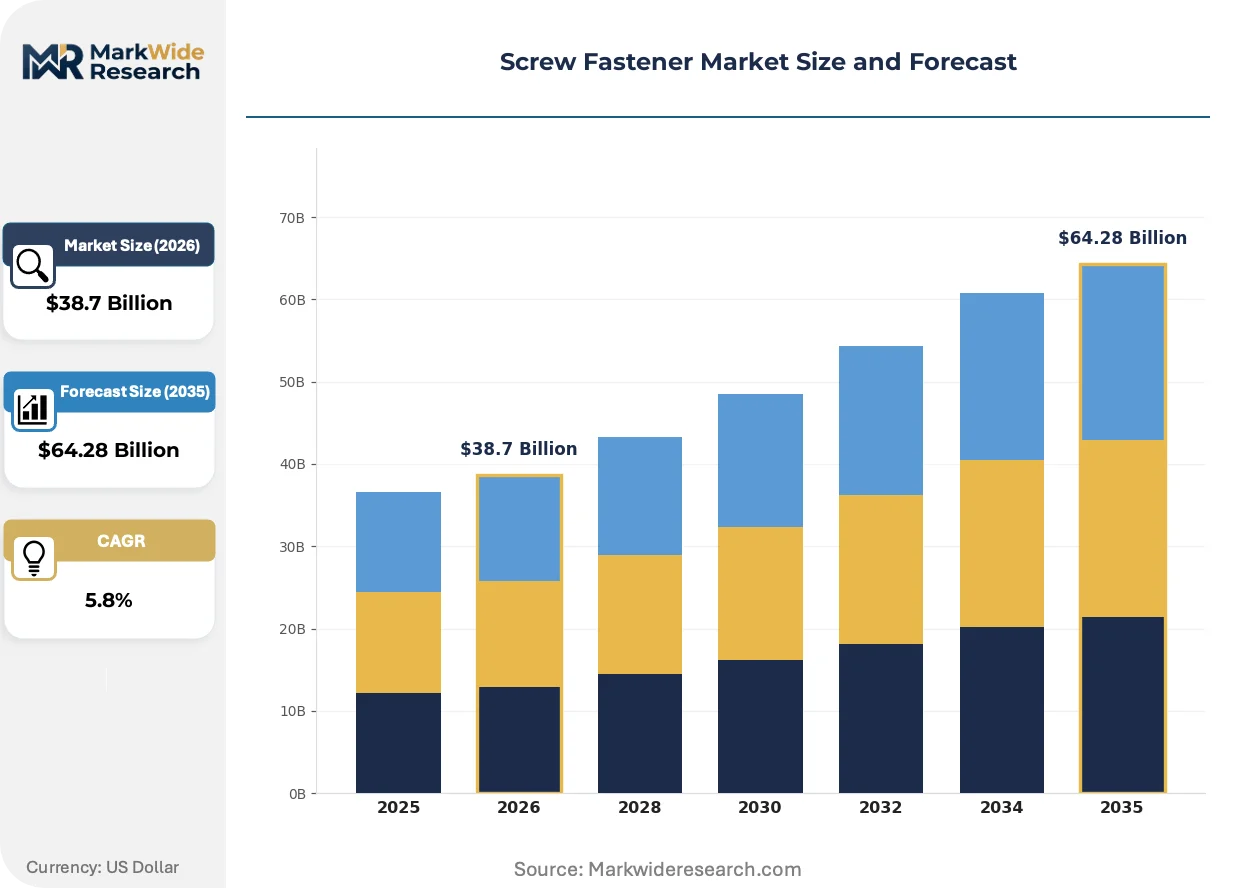
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Screws, Machine Screws, Self-Tapping Screws, Sheet Metal Screws Material: Steel, Stainless Steel, Brass, Plastic Coating Type: Galvanized, Zinc-Plated, Phosphate Coated, Black Oxide End User: Construction, Automotive, Electronics, Furniture |
| Companies Covered | Fastenal, Illinois Tool Works, Stanley Black & Decker, LISI Group, Hilti Corporation, Würth Group, Arconic, Acument, MW Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Fastener Market Evolving Landscape
Thread-forming and coating technologies are converging with digital torque verification systems, reshaping how industrial buyers evaluate total fastener lifecycle cost. Specification authority is shifting from procurement departments to engineering quality teams.
Advanced zinc-flake coating systems with integrated lubricant layers are electrifying corrosion protection performance in automotive underbody applications. German and Japanese OEMs are specifying these variants for 15-year warranty coverage. The technology is compressing demand for traditional hexavalent chromium platings in European supplier bases.
China's SAMR enforcement of updated GB/T 3098 structural bolt standards is tightening tensile property verification protocols. Infrastructure and wind energy projects now require third-party witnessed testing for high-strength assemblies. Domestic Chinese producers are consolidating to meet documentation and metallurgical consistency requirements.
Consolidated vendor-managed inventory programs are displacing spot purchasing in North American industrial distribution. Fastenal and Würth field sales organizations are embedding barcode-enabled bin replenishment systems at customer sites. The model is most visible in Midwest manufacturing belts where same-day delivery expectations have compressed safety stock holdings.
Screw Fastener Market Segmentation
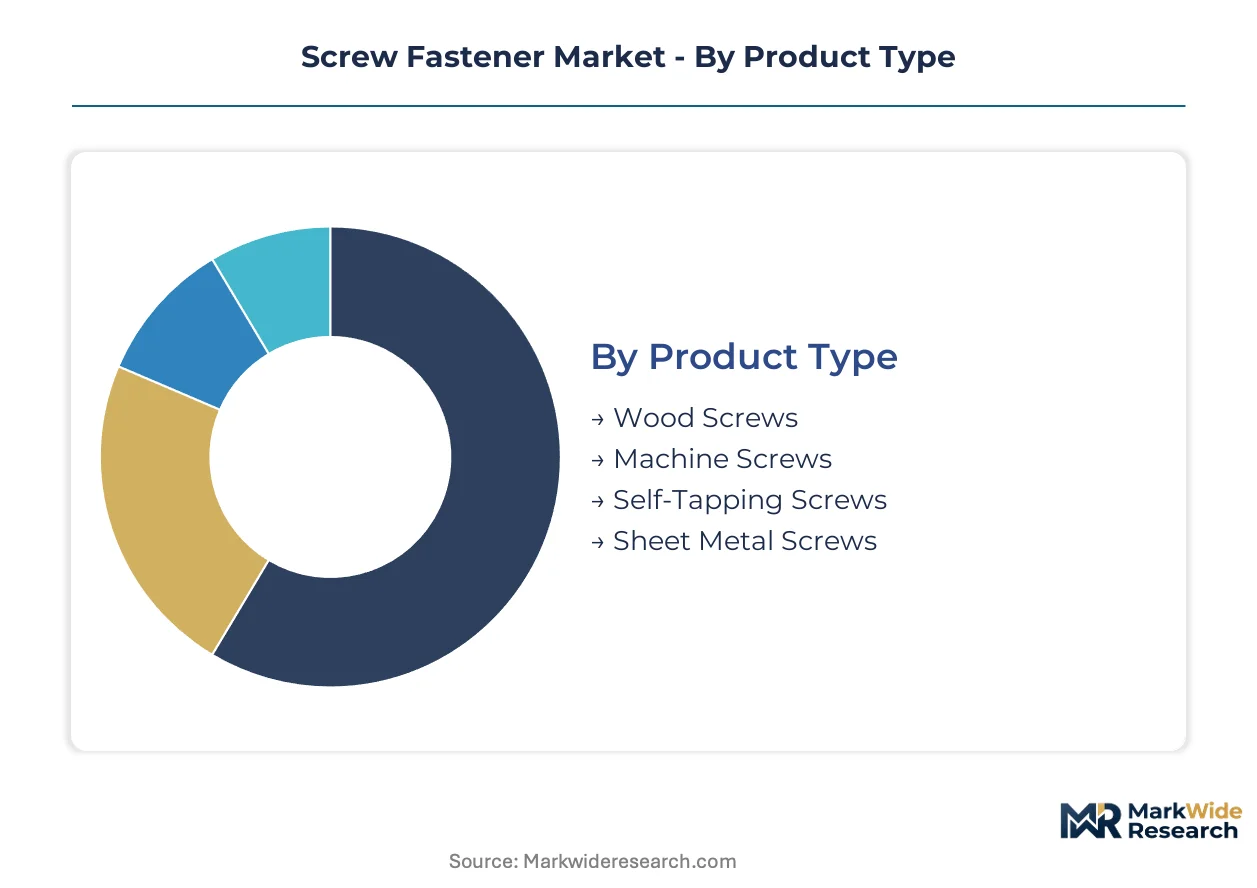
Screw fastener procurement patterns diverge sharply between commodity volume plays and specification-driven premium tiers. Understanding where each segment concentrates demand helps suppliers align capacity investments with margin pools.
Product Type:
Volume leadership sits with legacy threaded formats, while premium positioning clusters around specialty joining solutions for thin-gauge materials.
- Self-Tapping Screws:Thread-forming variants eliminate pre-drilling in aluminum extrusions and appliance housings. Taiwanese contract manufacturers and German automotive suppliers specify these for 15-year corrosion warranty coverage, displacing riveted joints in server chassis and EV battery trays.
- Machine Screws:Precision-machined or cold-headed variants with unified thread standards dominate industrial machinery and aerospace subassemblies. Demand concentrates in Germany's automotive supplier corridor where IATF 16949 certification gates procurement access.
- Wood Screws:Carbon steel variants with aggressive thread profiles serve residential and commercial construction framing. BIS-certified Indian producers supply Pune and Chennai equipment assembly plants.
- Sheet Metal Screws:Sharp-pointed variants with coarse threads penetrate thin steel and aluminum without pilot holes. HVAC ductwork and electrical enclosure manufacturers specify these for field assembly speed.
Mature deployment sits with Machine Screws. Newer deployment is concentrated in Self-Tapping Screws.
Material:
Cost structure and corrosion resistance define the procurement hierarchy across industrial verticals.
- Steel:Cold-heading-grade carbon and alloy steels absorb the largest volume share across construction and general industrial applications. Cold heading mills in China's Zhejiang province cluster capacity for this commodity tier.
- Stainless Steel:Austenitic A2-70 and A4-80 grades command premium positioning for thermal cycling resistance in EV battery packs and marine environments. South Korean and German OEMs qualify these for 800V platform architectures.
- Brass:Copper-zinc alloys serve decorative and electrical grounding applications where corrosion resistance and conductivity matter. Furniture hardware and electrical fixture manufacturers specify these for aesthetic finish compatibility.
- Plastic:Nylon and PEEK variants insulate against galvanic corrosion in electronics and medical device assemblies. Server chassis and diagnostic equipment producers specify these for lightweight, non-conductive fastening.
Steel dominates unit economics. Stainless Steel captures the steepest expansion trajectory from electrification and corrosion warranty extension.
Coating Type:
Environmental compliance deadlines are forcing coating transitions that reshape supplier qualification timelines.
- Zinc-Plated:Electroplated zinc with chromate conversion coatings faces REACH Annex XVII phaseout pressures. European construction equipment manufacturers are accelerating procurement of compliant alternatives.
- Galvanized:Hot-dip and mechanical galvanizing provide thick zinc layers for extended outdoor exposure. Infrastructure projects in India and wind energy installations specify these for 25-year service life.
- Phosphate Coated:Manganese and zinc phosphate layers improve paint adhesion and corrosion resistance in automotive underbody applications. German and Japanese OEMs specify these for chassis assembly.
- Black Oxide:Conversion coating provides minimal corrosion protection with aesthetic uniformity for firearms, tools, and decorative hardware. Premium positioning relies on oil after-treatment for enhanced performance.
Galvanized coatings anchor heavy industrial deployment. Zinc-Plated formats face the most urgent substitution pressure from regulatory deadlines.
End User:
Specification authority varies sharply between procurement-led and engineering-led buying centers.
- Construction:Structural bolting and general fastening absorb the largest volume share globally. India's construction equipment belt and German commercial building sectors concentrate demand for carbon steel and hot-dip galvanized variants.
- Automotive:Lightweighting and electrification are tightening fastener specifications toward higher-strength, corrosion-resistant grades. Battery pack assembly and 800V architectures specify A4-80 stainless and advanced zinc-flake systems.
- Electronics:Miniaturization and thermal management drive demand for thread-forming screws in aluminum housings. Server chassis and appliance manufacturers specify self-tapping variants for thin-gauge joining.
- Furniture:Decorative and functional fastening relies on brass and steel variants with aesthetic finishing. Mass-market and premium positioning separate on material grade and coating quality.
Construction holds the deepest installed base. Electronics is gaining share fastest from thin-gauge metal penetration and data center expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fastener production concentrates in China's coastal provinces while consumption spreads across automotive and construction belts in Germany, India, and the United States. This geographic mismatch creates extended supply chains and qualification complexity for specification-grade procurement.
China
MIIT's GB standards enforcement and dual carbon goals are tightening material certification for structural bolt assemblies. SAMR mandates third-party witnessed testing for wind energy and infrastructure projects. Cold heading mills cluster in Zhejiang and Jiangsu provinces, where domestic producers consolidate to meet documentation requirements.
Germany
Automotive OEMs in Stuttgart and Munich specify A4-80 stainless fasteners for 800V EV battery platforms. REACH Annex XVII drives coating transitions toward zinc-flake systems. The automotive supplier corridor anchors European demand for IATF 16949-certified precision grades.
India
BIS certification standardizes local supplier bases for excavator and crane assembly in Pune and Chennai. The construction equipment belt absorbs high-volume carbon steel shipments. CDSCO-aligned material disclosure rules are tightening for medical device fastener imports.
United States
EPA and OSHA compliance pressures intersect with NHTSA automotive safety standards for fastening systems. Midwest manufacturing belts adopt vendor-managed inventory with same-day delivery expectations. Illinois and Ohio host dense maintenance, repair, and operations distribution networks.
South Korea
MFDS material traceability requirements extend to medical device fasteners, while METI-influenced automotive standards drive EV battery pack specifications. Battery manufacturers in Gyeonggi Province qualify Grade A2-70 stainless for thermal cycling resistance. Domestic producers face pressure to match German corrosion warranty benchmarks.
Screw Fastener Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure fragments between scale-driven distributors, technology-anchored manufacturers, and regional service organizations. Three archetypes dominate: branch-network distributors controlling last-mile delivery, specialized automotive system suppliers, and field-sales-intensive aftermarket service providers. Competitive moves concentrate on M&A for geographic coverage and vertical integration into cold heading capacity.
Within the distributor archetype, Fastenal and Würth Group exemplify branch-network density strategies. Fastenal anchors North American same-day delivery through embedded inventory systems. Würth Group occupies a parallel position in European aftermarket demand. Illinois Tool Works sits within the specialized manufacturing tier, representing premium positioning through automotive fastening systems.
| Leading Market Players |
|---|
| Fastenal |
| Illinois Tool Works |
| Stanley Black & Decker |
| LISI Group |
| Hilti Corporation |
| Würth Group |
| Arconic |
| Acument |
| MW Industries |
| Others |
Value Network & Pricing Analysis
Tier 1 automotive OEM procurement teams in Germany and South Korea anchor contract-based long-term offtake agreements for A4-80 stainless fasteners, compressing spot-market liquidity and amplifying margin dispersion between specification-grade suppliers and commodity carbon steel producers.
Pricing Analysis
Margin tightening in precision-machined specialty grades reflects molybdenum and nickel input volatility from 60-day hedging windows. Three-tier pricing structure across premium, standard, and economy levels separates IATF 16949-certified automotive systems from BIS-certified construction commodities and unbranded generic imports. Cost-down pressure on carbon steel construction fasteners accelerates because Indian equipment assemblers in Pune consolidate volume procurement. General industrial maintenance buyers exhibit highest price sensitivity; EV battery pack engineers show lowest, prioritizing thermal cycling certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand, while branch-network distributors serve fragmented maintenance-repair-operations procurement. Cold heading capacity clusters in China's Zhejiang and Jiangsu provinces, with secondary thread rolling concentration in Taiwan for electronics-grade precision. Raw material flows draw from nickel laterite operations in Indonesia, molybdenum mining in Chile, and scrap steel recycling in Turkey. Tariff exposure on precision-machined specialty grades creates structural risk for Western buyers sourcing from East Asian rolling mills. Distribution runs through vendor-managed inventory programs embedding barcode-enabled bin replenishment at Midwest US manufacturing sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players securing captive supply of cold heading capacity and alloy optimization expertise, as metallurgical talent scarcity and qualification timeline compression raise barriers to organic capability replication.
For Market Incumbents: Anticipate REACH Annex XVII coating transition deadlines by accelerating zinc-flake system certification with German automotive OEMs. Defend margin pools through backward integration into A2-70 and A4-80 stainless wire drawing, neutralizing nickel price volatility exposure. Consolidate field sales density in India's construction equipment belt before BIS certification requirements harden local supplier qualification windows. For New Entrants and Emerging Players: E-commerce procurement portals for modular torque-limiting kits offer the lowest customer acquisition cost route into North American industrial maintenance accounts. White-space concentration sits with self-tapping screw variants for Taiwanese contract manufacturers assembling server chassis and EV battery trays. Target medical device fastener segments where CDSCO-aligned material disclosure rules disadvantage import-dependent incumbents. For Investors and Strategic Acquirers: The window for entry favors cold heading specialists with dormant automotive certification capacity. Long-term viability hinges on positioning for EV platform standardization cycles and corrosion warranty extension trends. Watch for IATF 16949 audit backlog clearance as inflection signal for Tier 1 OEM supplier list expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Wire Drawing | Captive supply of A4-80 stainless feedstock insulates German automotive suppliers from nickel price volatility. |
| Zinc-Flake Coating Certification | REACH-compliant systems unlock 15-year corrosion warranty coverage with Japanese and German OEMs. |
| Vendor-Managed Inventory Expansion | Barcode-enabled bin replenishment embeds Fastenal and Würth field organizations at Midwest manufacturing sites. |
| GB/T 3098 Structural Bolt Consolidation | Domestic Chinese producers merge to meet SAMR third-party witnessed testing requirements for wind energy projects. |
| Self-Tapping Screw Platform Development | Thread-forming variants displace riveted joints in Taiwanese contract manufacturer server chassis assemblies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across cold heading process engineers, Tier 1 automotive procurement managers, construction equipment plant managers, and industrial distribution channel heads. Bottom-up triangulation validated against top-down macroeconomic indicators and end-use industry production forecasts. Specific secondary sources included ECHA REACH enforcement notices, SAMR GB standard updates, BIS certification registries, and automotive OEM supplier quality manuals.
Reconciliation of shipment volumes, alloy consumption patterns, and end-use bill-of-materials data streams structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade, coating chemistry, and end-use vertical, with additional granularity on certification tier and geographic production cluster. CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements, stress-tested against EV battery pack architecture evolution and infrastructure investment cycles.
The model holds under stable alloy input price corridors and regulatory enforcement continuity; deviation in nickel-molybdenum volatility spikes or REACH deadline acceleration would shift supplier qualification timelines and procurement fragmentation patterns. Periodic stress-testing of base assumptions against ECHA enforcement actions and MIIT dual carbon policy implementation is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Total Station Market
Tools
Thread Milling Machine Market
Tools
Caulking Gun Market
Tools
Hydraulic Tools Market
Tools
United States Machine Tools Market
Tools
Industrial Ladder Market
Tools
End Milling Machine Market
Tools
Coil Thread Insert Market
Tools
Mechanical Hand Tools Market
Tools
Hydraulic Torque Wrench Market
Tools
Stand Tile Saw Market
Tools
Lathe Machines Market
Tools
Screwdriver Market
Tools
Fiber Laser Cutting Machines Market
Tools
Step Ladder Market
Tools
Construction Nails Market