
 Extensometer Market | 2026-2036
Extensometer Market Size, Share, and Industry Trends Forecast 2026-2036
Extensometer Market Foresight
The capability gap between automated optical systems and legacy mechanical contact extensometers is rotating competitive investment toward non-contact measurement platforms. Instron Corporation leverages its vertical integration into load-frame manufacturing to bundle extensometer sales with universal testing systems. ZwickRoell Group anchors its position through deep calibration service networks across European aerospace hubs. MTS Systems Corporation specializes in high-frequency dynamic extensometry for fatigue testing protocols in automotive R&D centers.
An extensometer measures dimensional deformation under tensile or compressive load, typically resolving microstrain changes through mechanical arms, strain gauge bridges, or optical triangulation with sub-micron precision. The device validates material properties including yield strength, elastic modulus, and elongation-at-break for metals, polymers, and composites under standardized loading conditions. Optical extensometers using laser and video image technology are capturing share from electrical strain gauge units in high-temperature and fragile specimen applications where physical contact risks measurement artifacts. Strain gauge technology still dominates volume shipments in routine quality control environments where cost sensitivity and established calibration protocols preserve incumbent positions. Digital extensometers with integrated data acquisition are expanding margin pools by reducing external controller dependencies and simplifying laboratory information management system integration.
FDA validation requirements for medical device material characterization and FAA airworthiness certification protocols for aerospace alloy testing create dual compliance pathways that shape product development priorities. ISO 9513 calibration standards and ASTM E83 precision classifications define market access thresholds that differentiate laboratory-grade from industrial-grade supplier tiers. Stakeholders must monitor convergence between optical extensometry and in-situ digital image correlation systems as boundary definitions between discrete measurement tools and full-field strain mapping platforms continue to blur.
Market Dynamics
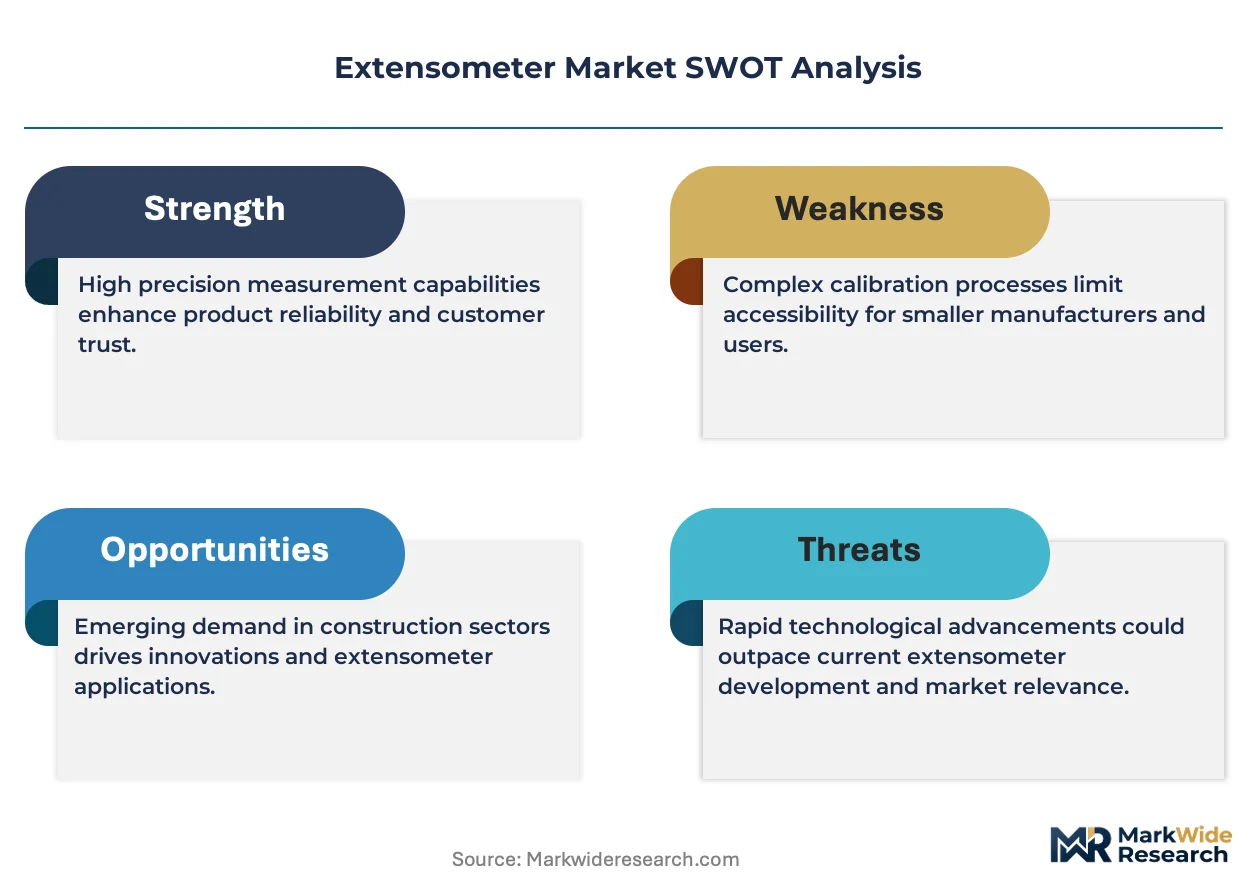
Optical extensometry is decomposing the traditional bifurcation between laboratory-grade precision and industrial-grade throughput, forcing recalibration of how suppliers segment their product architectures and service bundling.
Growth Catalysts
- FAA airworthiness protocols:Aerospace manufacturers in Germany and the United States face expanded validation requirements for composite airframe materials, accelerating optical extensometer procurement for non-contact strain measurement.
- Automotive lightweighting mandates:High-strength aluminum and carbon fiber testing volumes in Germany's automotive corridor are pulling demand for multi-channel digital extensometer systems.
- Strain gauge bridge miniaturization:Advances in foil pattern etching and temperature compensation circuits are preserving incumbent positions in routine quality control environments where cost sensitivity dominates.
Market Restraints
- Optical component supply concentration:High-resolution CMOS sensors and precision telecentric lenses concentrate in Japanese and German supplier networks, creating input vulnerability for non-contact system manufacturers.
- Calibration infrastructure scarcity:ISO 9513-compliant calibration laboratories remain geographically sparse outside Western Europe and Japan, extending lead times for precision-grade system deployment.
- Strain gauge price erosion:Mature manufacturing processes for foil strain gauges in Chinese production clusters are compressing margins for electrical extensometer suppliers serving commodity testing applications.
Strategic Opportunities
- India's medical device testing expansion:CDSCO notification requirements for implantable device material characterization are creating first-mover advantages for suppliers establishing calibration partnerships in Mumbai and Hyderabad.
- In-situ digital image correlation convergence:Boundary blurring between discrete extensometry and full-field strain mapping is opening integrated platform architectures that capture adjacent measurement budgets.
- China's dual carbon policy:NMPA and MIIT emphasis on new energy vehicle battery material validation is redirecting procurement toward high-temperature extensometry for solid-state electrolyte characterization.
Industry Challenges
- Photogrammetry expertise scarcity:Optical extensometer deployment requires specialized knowledge in camera calibration, speckle pattern application, and image correlation algorithms that outpaces available technical training pipelines.
- Legacy controller integration friction:Laboratory information management system connectivity for digital extensometers demands custom middleware development, extending implementation timelines and inflating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extensometer Market |
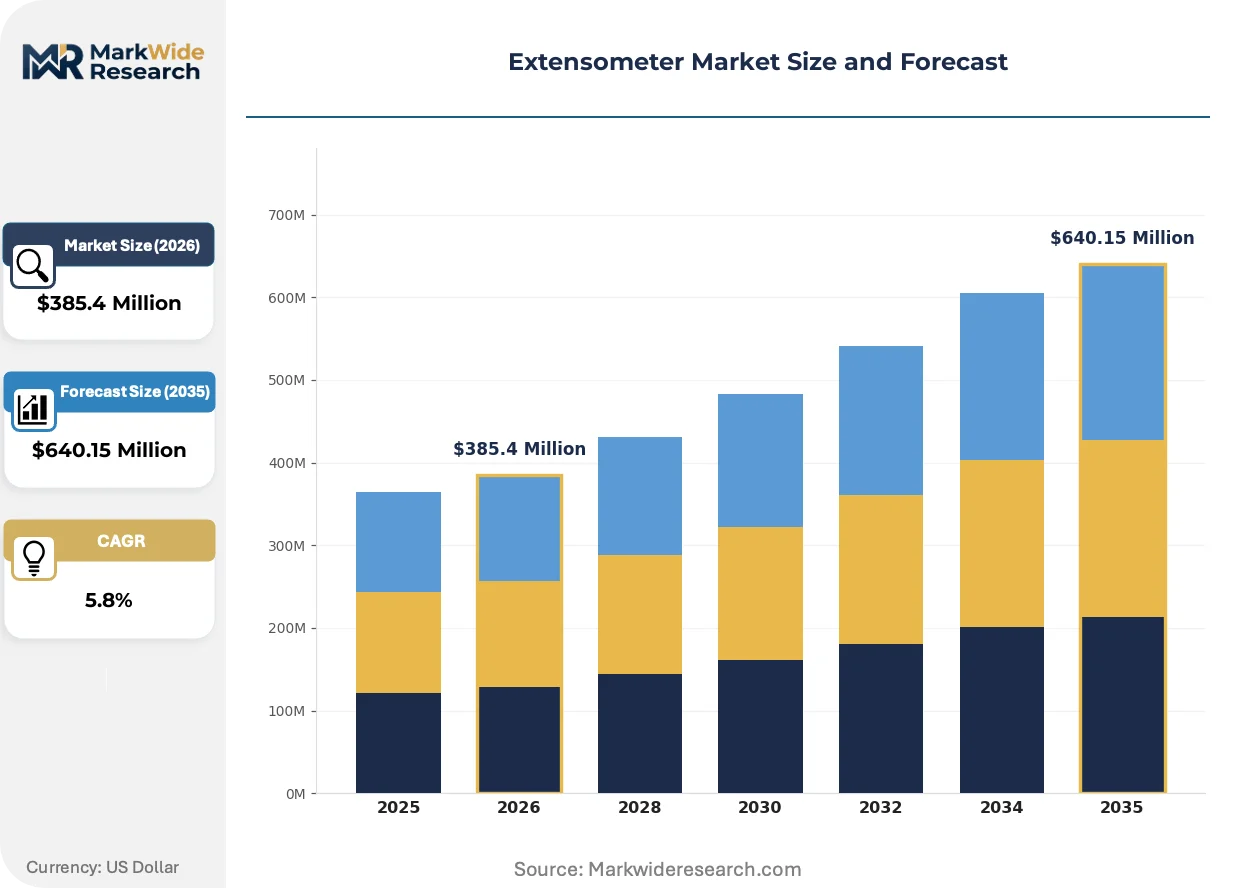
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Extensometers, Optical Extensometers, Electrical Extensometers, Digital Extensometers Technology: Laser Technology, Strain Gauge Technology, Video Image Technology, Capacitive Technology Application: Material Testing, Structural Health Monitoring, Research & Development, Quality Control End User: Aerospace, Automotive, Civil Engineering, Manufacturing |
| Companies Covered | Instron Corporation, ZwickRoell Group, MTS Systems Corporation, Shimadzu, Vishay Precision Group, Mitutoyo Corporation, Tinius Olsen, HBM Test and Measurement, Kistler Instrumente AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extensometer Market Shifts & Advancements
Laser and video-based measurement architectures are compressing the performance gap between contact and non-contact modalities, reshaping how testing laboratories configure their strain measurement ecosystems and justify capital allocation.
Speckle pattern optical extensometry is decomposing the historical trade-off between measurement precision and specimen protection. Aerospace composite manufacturers in Toulouse and Seattle are adopting laser-based systems for fragile carbon fiber layup validation. This technology is decomposing the market segmentation between laboratory-grade and industrial-grade equipment tiers, as single platforms now span both precision and throughput requirements.
EU MDR and IVDR material characterization requirements are tightening traceability standards for medical device polymer testing. European notified bodies now demand continuous strain documentation across fatigue cycles for implantable components. German and Swiss testing houses are responding by upgrading to automated optical systems that eliminate operator-dependent contact point placement variability.
Buyers are consolidating testing equipment procurement under single-source framework agreements that bundle extensometer supply with long-term calibration service commitments. Original equipment manufacturers in Japan's precision instrument clusters favor suppliers offering captive metrology laboratory networks over discrete product vendors. This concentration is most visible in automotive R&D centers where total cost of ownership calculations now dominate capital approval processes.
Extensometer Market Segmentation
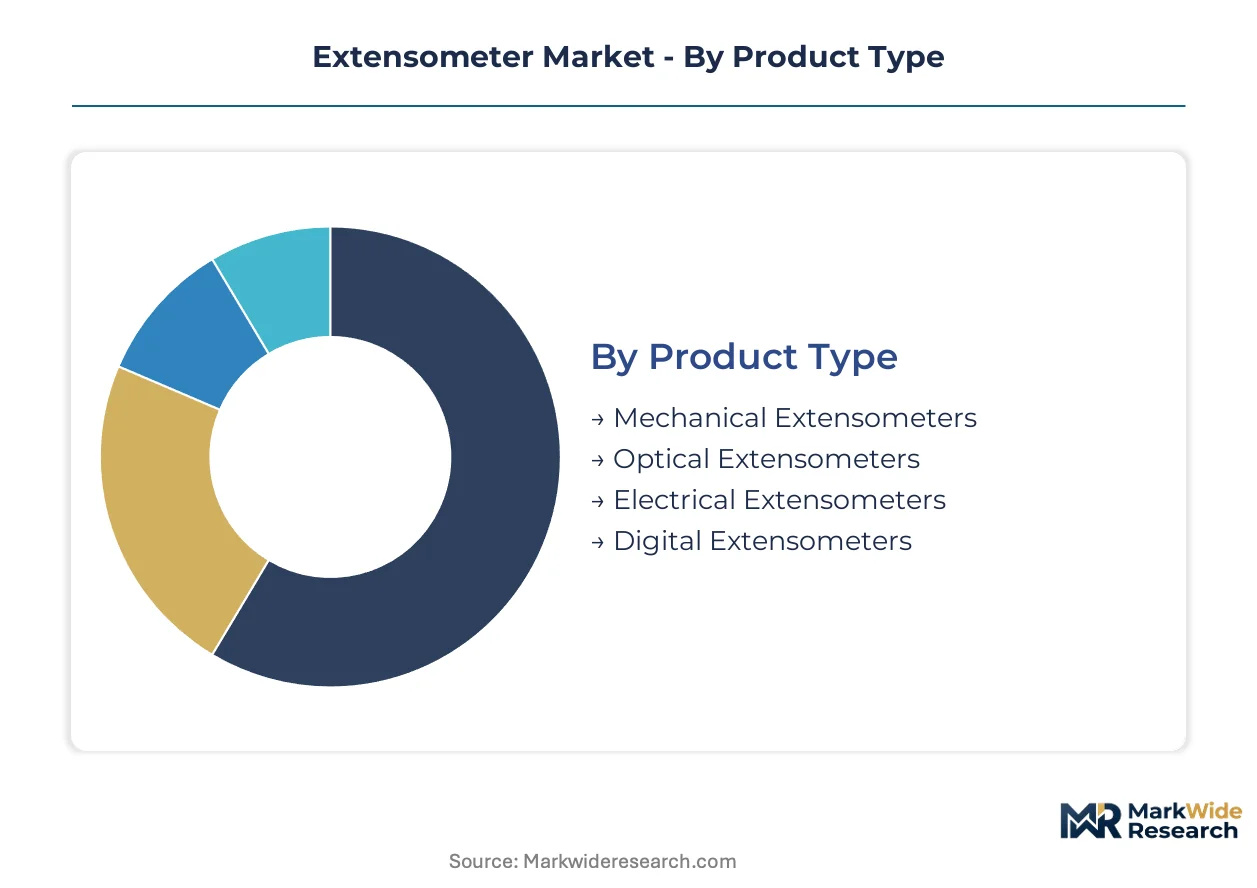
Extensometer procurement patterns diverge sharply across measurement modalities, with regulatory compliance requirements dictating technology selection in aerospace and medical device verticals. Product architectures must align with ISO 9513 precision tiers and ASTM E83 classification thresholds to access laboratory-grade versus industrial-grade customer budgets.
Product Type:
FDA and FAA validation protocols create tiered certification barriers that separate laboratory-grade precision systems from industrial throughput equipment.
- Mechanical Extensometers:Physical contact arms with knife-edge attachment points deliver direct strain measurement through mechanical amplification. Demand concentrates in legacy manufacturing facilities across Germany's Ruhr industrial belt where established calibration protocols and capital equipment amortization preserve incumbent positions despite optical displacement.
- Optical Extensometers:Laser triangulation and video image correlation enable non-contact measurement with sub-micron resolution for fragile composite specimens. Aerospace manufacturers in Toulouse and Seattle are expanding procurement for carbon fiber airframe validation where physical contact risks delamination artifacts.
- Electrical Extensometers:Foil strain gauge bridges with Wheatstone circuit configurations dominate routine quality control environments.
- Digital Extensometers:Integrated data acquisition architectures reduce external controller dependencies for laboratory information management system connectivity.
Established volume favors Mechanical Extensometers; emerging adoption favors Optical Extensometers.
Technology:
Cost tier stratification separates premium optical platforms from commodity strain gauge implementations.
- Laser Technology:Coherent light interferometry captures dimensional changes without specimen contact, enabling high-temperature alloy testing beyond strain gauge thermal limits. Japanese precision instrument clusters in Tokyo-Yokohama corridor anchor supply concentration for precision telecentric lenses and high-resolution CMOS sensors.
- Strain Gauge Technology:Metallic foil patterns etched on polyimide substrates measure resistance changes under mechanical deformation. Automotive R&D centers in Stuttgart and Munich maintain procurement volumes for standardized tensile testing of high-strength aluminum alloys where cost sensitivity dominates precision requirements.
- Video Image Technology:Speckle pattern correlation algorithms extract strain fields from sequential image capture.
- Capacitive Technology:Variable capacitance displacement sensors offer alternative non-contact architectures for specialized applications.
Laser Technology commands premium positioning; Strain Gauge Technology retains volume leadership.
Application:
Customer type segmentation separates capital-intensive research infrastructure from operational quality control budgets.
- Material Testing:Standardized tensile, compression, and fatigue protocols validate yield strength, elastic modulus, and elongation-at-break properties. EU MDR and IVDR traceability requirements for implantable device polymers are tightening documentation standards across German and Swiss testing houses.
- Structural Health Monitoring:Continuous strain measurement for civil infrastructure and aerospace asset integrity. Demand is climbing the fastest in Japan's earthquake-engineering research institutes where long-term deformation tracking supports seismic resilience validation.
- Research & Development:Experimental mechanics and novel material characterization in academic and corporate laboratories.
- Quality Control:Production-line material verification with throughput-optimized measurement cycles.
Quality Control captures current procurement volume; Structural Health Monitoring shows steepest expansion trajectory.
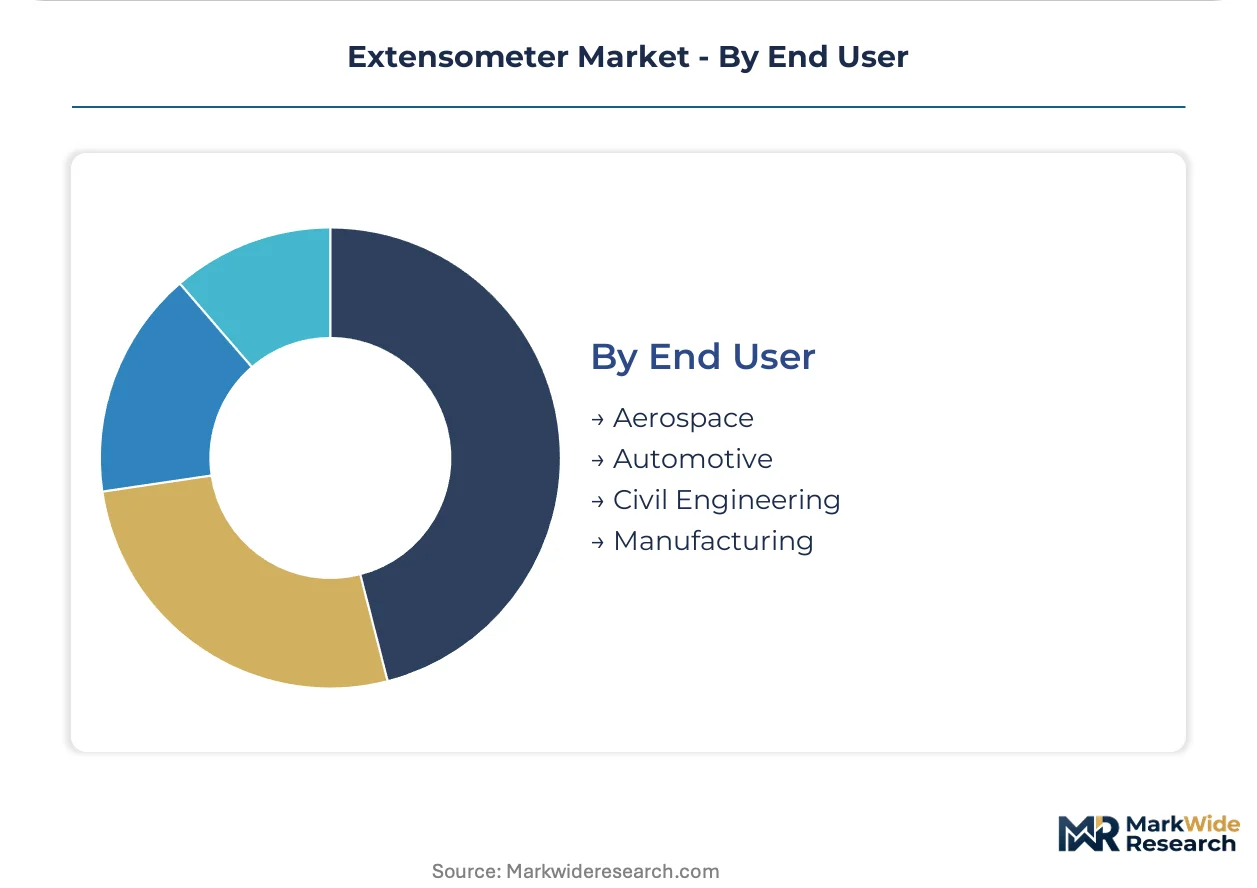
End User:
Margin concentration aligns with certification complexity and regulatory audit frequency.
- Aerospace:FAA airworthiness certification protocols mandate optical extensometry for composite airframe validation. Boeing and Airbus tier-1 suppliers in Germany and the United States face expanded documentation requirements for carbon fiber layup characterization.
- Automotive:Lightweighting mandates for high-strength aluminum and carbon fiber testing pull multi-channel digital system procurement. Germany's automotive testing corridor from Wolfsburg to Munich represents concentrated demand for synchronized multi-point strain measurement.
- Civil Engineering:Infrastructure load testing and construction material verification.
- Manufacturing:Broad industrial quality control across metal, polymer, and composite processing.
Manufacturing delivers volume scale; Aerospace commands margin premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan's precision instrument clusters demonstrate the lowest price elasticity, absorbing premium optical systems, while procurement in China's commodity testing sector compresses margins on strain gauge units. Germany's automotive corridor sits between these poles, balancing precision requirements with volume scale.
United States
FAA airworthiness certification protocols for composite airframe validation drive optical extensometer procurement at Boeing tier-1 suppliers. The FAA mandates non-contact strain documentation for carbon fiber layup characterization. Seattle-Tacoma aerospace clusters anchor concentrated demand for laser-based measurement platforms.
Germany
Automotive lightweighting mandates for high-strength aluminum and carbon fiber testing pull multi-channel digital system adoption. KBA enforcement of crashworthiness standards tightens material traceability requirements. The Wolfsburg-to-Munich testing corridor represents Europe's densest concentration of synchronized multi-point strain measurement infrastructure.
Japan
Earthquake-engineering research institutes deploy long-term deformation tracking for seismic resilience validation. METI funding for infrastructure monitoring accelerates structural health monitoring adoption. Tokyo-Yokohama precision instrument clusters supply high-resolution CMOS sensors and telecentric lenses for optical system manufacturers.
China
NMPA and MIIT emphasis on new energy vehicle battery material validation redirects procurement toward high-temperature extensometry. Dual carbon policy targets elevate solid-state electrolyte characterization priorities. Yangtze River Delta battery R&D centers expand procurement for thermal testing beyond strain gauge limits.
India
CDSCO notification requirements for implantable device material characterization create calibration infrastructure demand. National pharmaceutical regulator mandates strain documentation for polymer fatigue testing. Mumbai and Hyderabad medical device testing labs seek first-mover calibration partnerships for optical system deployment.
Extensometer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum bundling extensometer sales with universal testing systems and calibration service networks. The middle tier fragments across regional precision instrument clusters, each anchored by distinct technology specializations. Two strategic archetypes dominate: vertically integrated testing system manufacturers and standalone measurement specialists with deep calibration footprints. Competitive moves concentrate on backward integration into sensor manufacturing and geographic expansion of metrology laboratory networks.
Within the integrated systems tier, Instron Corporation and ZwickRoell Group occupy positions exemplifying bundled equipment-and-service strategies, while MTS Systems Corporation anchors the high-frequency dynamic measurement specialization. Japanese precision conglomerates represented by Shimadzu and Mitutoyo Corporation sit within the diversified instrumentation tier, leveraging captive optical component supply chains. Vishay Precision Group exemplifies the strain gauge technology incumbent position in routine quality control environments.
| Leading Market Players |
|---|
| Instron Corporation |
| ZwickRoell Group |
| MTS Systems Corporation |
| Shimadzu |
| Vishay Precision Group |
| Mitutoyo Corporation |
| Tinius Olsen |
| HBM Test and Measurement |
| Kistler Instrumente AG |
| Others |
Supply & Pricing Matrix
Strain gauge bridge miniaturization displacing mechanical contact methods simultaneously concentrates component sourcing in Japanese precision clusters and compresses margins for legacy electrical extensometer suppliers serving commodity testing tiers. This substitution dynamic redistributes pricing power toward optical system manufacturers with captive sensor supply chains while eroding profitability for undifferentiated strain gauge vendors dependent on Chinese foil etching networks.
Pricing Analysis
Calibration service contracts and extended warranty bundles drive lifetime value capture across laboratory-grade system tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9513-certified precision platforms from industrial-grade throughput equipment and commodity strain gauge units. Price differentiation hinges on certification tier and after-sales service depth, with margins tightening in the strain gauge segment due to Chinese manufacturing scale. Automotive R&D centers in Germany exhibit lowest price sensitivity, absorbing premium optical systems, while commodity quality control buyers in emerging markets prioritize unit economics.
Supply Chain Analysis
Japan and Germany anchor production of high-resolution CMOS sensors, precision telecentric lenses, and foil strain gauge substrates feeding global extensometer assembly. Raw material dependencies center on polyimide substrates, specialized optical glass, and temperature-compensation alloys. Single-source vulnerability concentrates in Japanese CMOS sensor fabrication, exposing non-contact system manufacturers to geographic supply disruption. Distribution runs through captive metrology laboratory networks for laboratory-grade tiers and industrial equipment distributors for routine quality control segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where ISO 9513 calibration infrastructure and FAA certification protocols create switching-cost moats that protect incumbent positions against technology substitution threats.
For Market Incumbents: Consolidate backward integration into optical sensor manufacturing to reduce Japanese component dependency and defend margin position against emerging Asian system assemblers. Expand calibration laboratory footprints in India's medical device testing corridor before CDSCO notification requirements mature, locking in first-mover service relationships with Mumbai and Hyderabad testing houses. For New Entrants and Emerging Players: Anchor in digital image correlation convergence opportunities where boundary blurring between discrete extensometry and full-field strain mapping creates white-space for integrated platform architectures. India's implantable device material characterization segment offers lowest competitive density for optical system deployment, with CDSCO-mandated strain documentation creating immediate procurement pull without entrenched incumbent relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision instrumentation platforms lacking optical extensometer capabilities but possessing established calibration service networks. Long-term viability favors targets with regulatory certification depth over pure technology plays, with inflection signals appearing in FAA composite validation protocol revisions and EU MDR traceability standard tightenings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Sensor Manufacturing | Reduces CMOS dependency from Japanese suppliers and protects margin pools in premium system tiers. |
| Calibration Laboratory Network Expansion | Captures recurring service revenue and locks in long-term customer relationships under ISO 9513 protocols. |
| Digital Image Correlation Platform Development | Exploits convergence between discrete extensometry and full-field strain mapping to capture adjacent measurement budgets. |
| India Market Entry Partnership | Positions for CDSCO-mandated implantable device testing requirements before incumbent calibration infrastructure solidifies. |
| High-Temperature Extensometry Specialization | Addresses NMPA and MIIT solid-state electrolyte validation priorities in China's new energy vehicle battery R&D centers. |
Research Methodology
Operator-level perspectives from testing laboratory managers, OEM procurement leads at aerospace tier-1 suppliers, calibration service technicians, and biomedical engineers at implantable device manufacturers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FAA airworthiness directives, ISO 9513 calibration standards, CDSCO notification requirements, and customs data from German, Japanese, and Chinese precision instrument trade flows. Bottom-up segment sizing triangulated against top-down industry expenditure estimates across the analysis window.
Sensitivity analysis tested forecast outputs against variable adoption rates for optical displacement of strain gauge technologies and divergent regulatory enforcement timelines for EU MDR traceability requirements. Segmentation dimensions modeled include measurement modality, precision certification tier, end-use vertical, and geographic regulatory cluster. CAGRs derived from installed base growth, replacement cycle analysis, and penetration rate assumptions for emerging applications including structural health monitoring and battery material validation.
Decision-makers should treat outputs as directional under sustained FAA composite validation requirements and stable optical component supply from Japanese precision clusters; material deviation in either assumption would warrant model refresh. Recalibration cycles align with material shifts in aerospace certification protocols, medical device regulatory harmonization, and optical sensor supply geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Water Pump Pliers Market
Tools
Welding Guns Market
Tools
Fastening Power Tools Market
Tools
Indexable Tool Inserts Market
Tools
Caulking Gun Market
Tools
Shredder Blades Market
Tools
Laser Engraving Machine Market
Tools
Gas Cutting Machine Market
Tools
Welding Products Market
Tools
Turning Centers Market
Tools
Construction Nails Market
Tools
Pneumatic Marking Machines Market
Tools
Global Swaging Machine Market
Tools
Industrial Cleaning Equipment Market
Tools
Drill Presses Market
Tools
Rebar Cutter Market