
 Oxy-Fuel Torches Market | 2026-2036
Oxy-Fuel Torches Market Size, Share, and Industry Trends Forecast 2026-2036
Oxy-Fuel Torches Market Analytics
Industrial distribution networks for welding and cutting equipment are reshaping as direct-to-fleet digital procurement gains share among contract fabricators. Lincoln Electric Holdings leverages its captive distributor footprint to sustain aftermarket consumable pull-through. ESAB anchors its position through R&D intensity in automated torch integration. Koike Aronson specializes in heavy-duty cutting torch systems for shipyard and structural steel applications.
An oxy-fuel torch is a handheld or machine-mounted thermal device that mixes oxygen with a combustible fuel gas—typically acetylene, propane, or natural gas—to produce a controlled flame exceeding 3,000°C for cutting, welding, or heating ferrous and non-ferrous metals. The technology relies on precise gas mixing ratios and tip orifice geometry to achieve clean kerf walls and minimal dross in steel plate severance. Cutting torches dominate unit volume in shipbreaking and demolition scrap processing, where thick-section severance demands limit plasma alternatives. Handheld torches retain margin density in field repair and artisan metalworking segments where portability commands price premiums over stationary systems. Propane-based technology is displacing acetylene in outdoor construction sites due to lower cylinder costs and safer transport profiles.
OSHA mandates respiratory and fire-safety compliance for oxy-fuel operations in US fabrication shops, while the EU F-Gas Regulation pressures gas suppliers toward lower-carbon fuel alternatives. ISO 5172 standards for cutting and welding nozzles govern international product interchangeability and access. Stakeholders must monitor evolving carbon-border adjustments and fuel-mix certifications that will determine which torch-fuel combinations retain operational legality in key manufacturing jurisdictions.
Market Dynamics
Reshoring of fabrication capacity is concentrating torch demand among contract metalworking shops seeking certified, low-emission systems that satisfy tightening workplace safety mandates. This structural pull is reordering procurement priorities across North American and European industrial corridors.
Growth Catalysts
- OSHA workplace safety mandates:US fabrication shops face intensified respiratory and fire-safety compliance requirements, accelerating replacement cycles for certified torch systems that meet updated ventilation and operator protection standards.
- EU F-Gas Regulation compliance:European gas suppliers are redirecting toward lower-carbon fuel alternatives, creating pull-through demand for torches engineered to operate efficiently with propane and natural gas blends.
- Germany's automotive supplier corridor:Dense clusters of cutting and welding operations in Baden-Württemberg and Bavaria maintain continuous fleet expansion to support electric vehicle platform fabrication.
Market Restraints
- Acetylene cost volatility:Input price swings for calcium carbide and hydrocarbon feedstocks compress margin predictability for shops locked into acetylene-dependent cutting workflows.
- Plasma cutting substitution:Thin-section severance applications below 25mm increasingly migrate to plasma systems, constraining oxy-fuel volume in precision fabrication segments.
- EU carbon-border adjustment friction:Uncertainty around CBAM implementation timelines for imported steel is freezing capital expenditure decisions at European structural fabricators.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for capital goods and automotive components are catalyzing greenfield fab shop construction requiring complete torch fleet outfitting.
- Automated torch-robot integration:Convergence of machine-mounted oxy-fuel systems with six-axis robotic arms opens high-volume repetitive cutting in shipyard panel lines.
- Direct-to-fleet digital procurement:Contract fabricators are bypassing traditional welding distributors through B2B platforms, creating channel space for OEMs to capture aftermarket consumable revenue directly.
Industry Challenges
- ISO 5172 nozzle certification timelines:Extended testing protocols for international interchangeability standards delay product launches and fragment spare parts availability across torch brands.
- Legacy gas infrastructure retrofit:Shops with acetylene manifold systems face capital-intensive reconfiguration to accommodate propane or natural gas supply architectures safely.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxy-Fuel Torches Market |
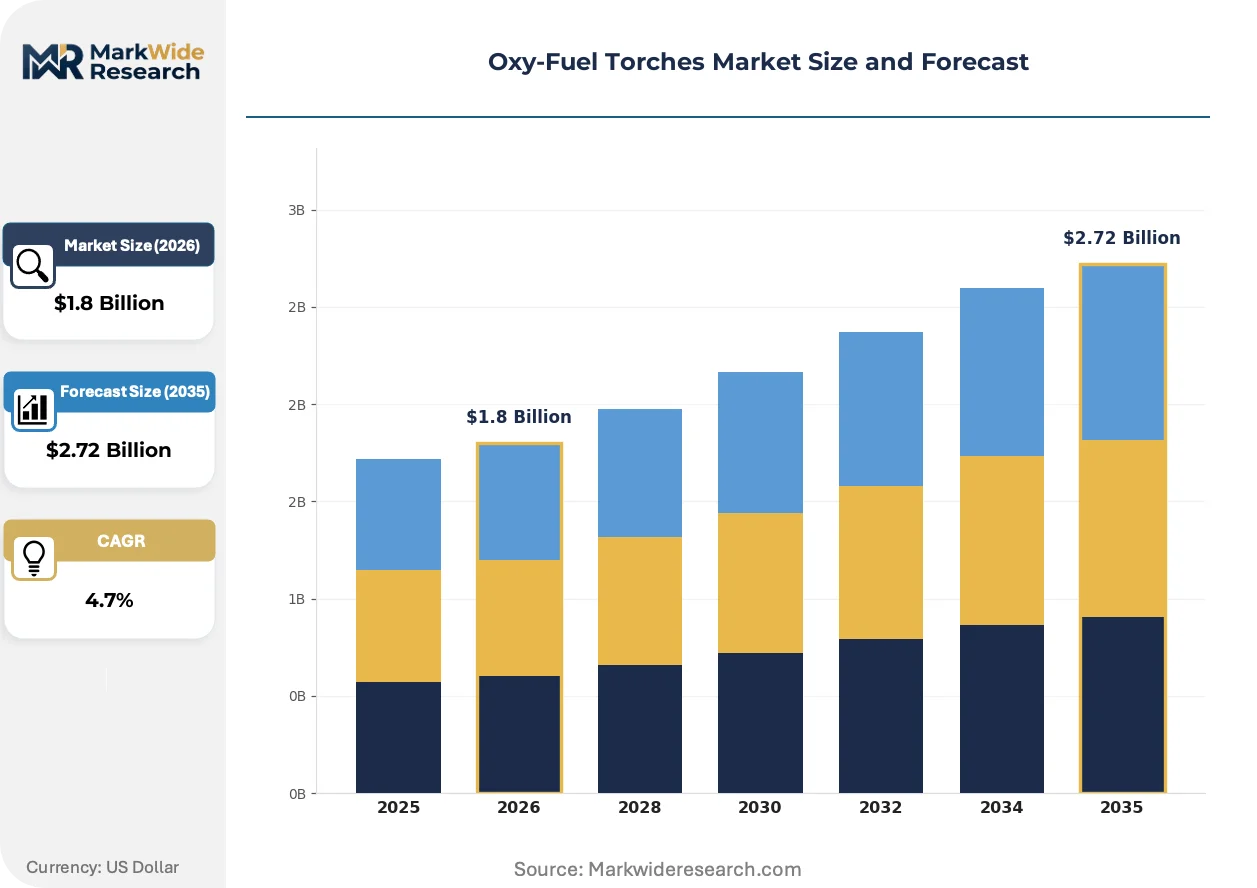
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Torches, Cutting Torches, Welding Torches, Heating Torches End User: Manufacturing, Construction, Automotive, Metalworking Technology: Acetylene-Based, Propane-Based, Natural Gas, Oxygen-Propane Application: Metal Cutting, Metal Welding, Glass Blowing, Jewelry Making |
| Companies Covered | Lincoln Electric Holdings, Inc., ESAB, Air Liquide S.A., Linde plc, Harris Products Group, Victor Technologies, GCE Group, Koike Aronson, Inc., Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxy-Fuel Torches Market Evolving Landscape
Torch system architecture is converging with digital controls and automated gas management, compressing the skill threshold for precision cutting while expanding machine-mounted deployment. These shifts are redrawing competitive advantage around software integration rather than mechanical durability alone.
Smart gas flow controllers embedded with pressure sensors and Bluetooth connectivity are digitizing flame chemistry management in real time. Shipyards in South Korea and Japan are adopting these systems for thick-plate severance where kerf consistency reduces grinding labor. The technology is digitizing quality control documentation, enabling automated compliance reporting for ISO-certified fabricators.
The EU F-Gas Regulation is accelerating fuel-mix standardization across member states, forcing gas suppliers to certify low-GWP alternatives for oxy-fuel applications. Industrial gas distributors in the Netherlands and Belgium are reformulating propane blends to meet 2025 phase-down targets. Cutting torch manufacturers must recalibrate tip orifice geometry to maintain flame temperature with these reformulated fuels.
Maintenance contracts are unbundling from equipment sales as fleet operators seek predictable operating expenditure structures. Large contract fabricators in Texas and Ohio are negotiating throughput-based service agreements that shift nozzle and tip replacement liability to OEMs. This preference is most visible among automotive stamping suppliers running three-shift operations where downtime carries severe penalty costs.
Oxy-Fuel Torches Market Segmentation
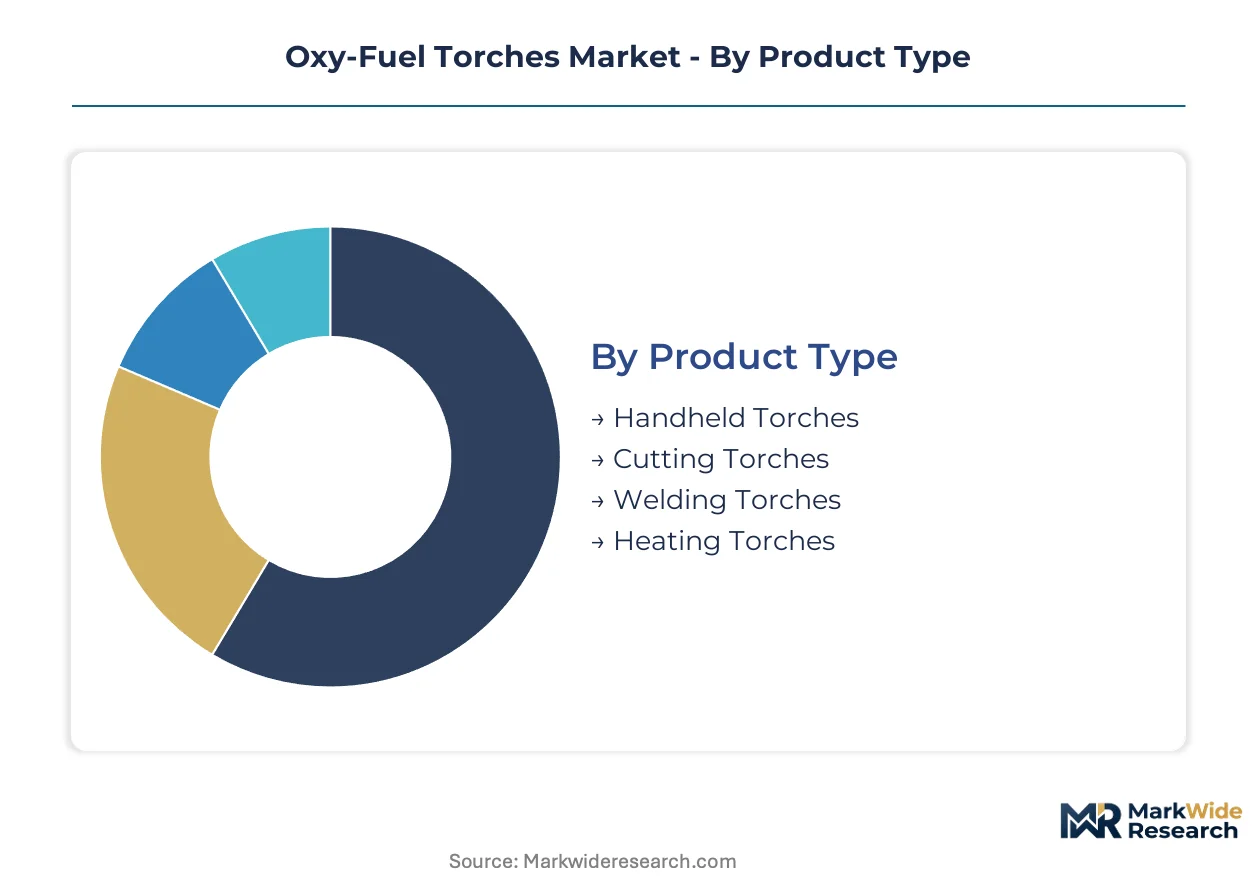
Oxy-fuel torch segmentation reveals divergent service and replacement cycles across product architectures. Aftermarket pull-through intensity varies sharply between consumable-heavy cutting systems and durable handheld units, reshaping how OEMs structure channel partnerships and direct fleet relationships.
Product Type:
Aftermarket service intensity peaks with cutting torch systems where nozzle degradation drives continuous replenishment, while heating torch configurations sustain longer intervals between tip replacement.
- Handheld Torches:Portable units built for field repair and artisan metalworking command premium pricing through ergonomic grip designs and quick-connect gas fittings. Demand clusters among independent contractors in Texas and Ohio where three-shift automotive stamping operations prioritize downtime minimization over unit cost.
- Cutting Torches:Machine-mounted and handheld severance systems engineered for thick-plate applications above 25mm, utilizing precision orifice geometry to control kerf width and dross formation. Shipbreaking yards in Bangladesh and demolition scrap processors in Germany maintain dense fleet concentrations where plasma alternatives face technical limitations.
- Welding Torches:Brazing and fusion systems with adjustable flame chemistry for ferrous and non-ferrous joining.
- Heating Torches:Broad-flame units for pre-heating, stress relieving, and localized thermal treatment of structural steel.
By volume, Cutting Torches leads. By growth pace, Handheld Torches is expanding most quickly.
End User:
Procurement sophistication stratifies sharply across customer categories, with automotive stampers demanding throughput-based service contracts while construction operators prioritize cylinder logistics over equipment specifications.
- Manufacturing:Capital-intensive fabricators running automated panel lines and repetitive severance operations. Baden-Württemberg automotive suppliers anchor European demand through continuous fleet refresh cycles tied to electric vehicle platform launches.
- Construction:Outdoor infrastructure and structural steel erectors where propane displacement of acetylene accelerates on transport safety and cylinder cost considerations. German industrial corridors and US Gulf Coast petrochemical construction sites drive regional concentration.
- Automotive:Tier-1 stamping and chassis suppliers with penalty-clause exposure to downtime.
- Metalworking:Job shops and contract fabricators with variable batch sizes and mixed-material workflows.
Manufacturing captures the largest revenue share. Construction is gaining share fastest on infrastructure reshoring.
Technology:
Fuel-mix standardization under EU F-Gas Regulation is recalibrating tip geometry requirements and forcing recertification timelines that fragment spare parts interoperability.
- Acetylene-Based:Legacy systems utilizing calcium carbide-derived fuel gas with highest flame temperature for precision welding. Cost volatility in hydrocarbon feedstocks compresses margin predictability for shops locked into acetylene manifold infrastructure.
- Propane-Based:Lower-carbon alternatives displacing acetylene in outdoor construction and shipyard applications where cylinder transport safety and fuel cost differentials outweigh temperature penalties. Dutch and Belgian gas distributors are reformulating blends to meet 2025 phase-down targets.
- Natural Gas:Pipeline-fed systems for stationary industrial installations with consistent throughput.
- Oxygen-Propane:Optimized mixing ratios for thick-section cutting where kerf consistency reduces downstream grinding labor.
Propane-Based systems lead by new unit volume. Oxygen-Propane configurations are climbing the fastest on shipyard automation.
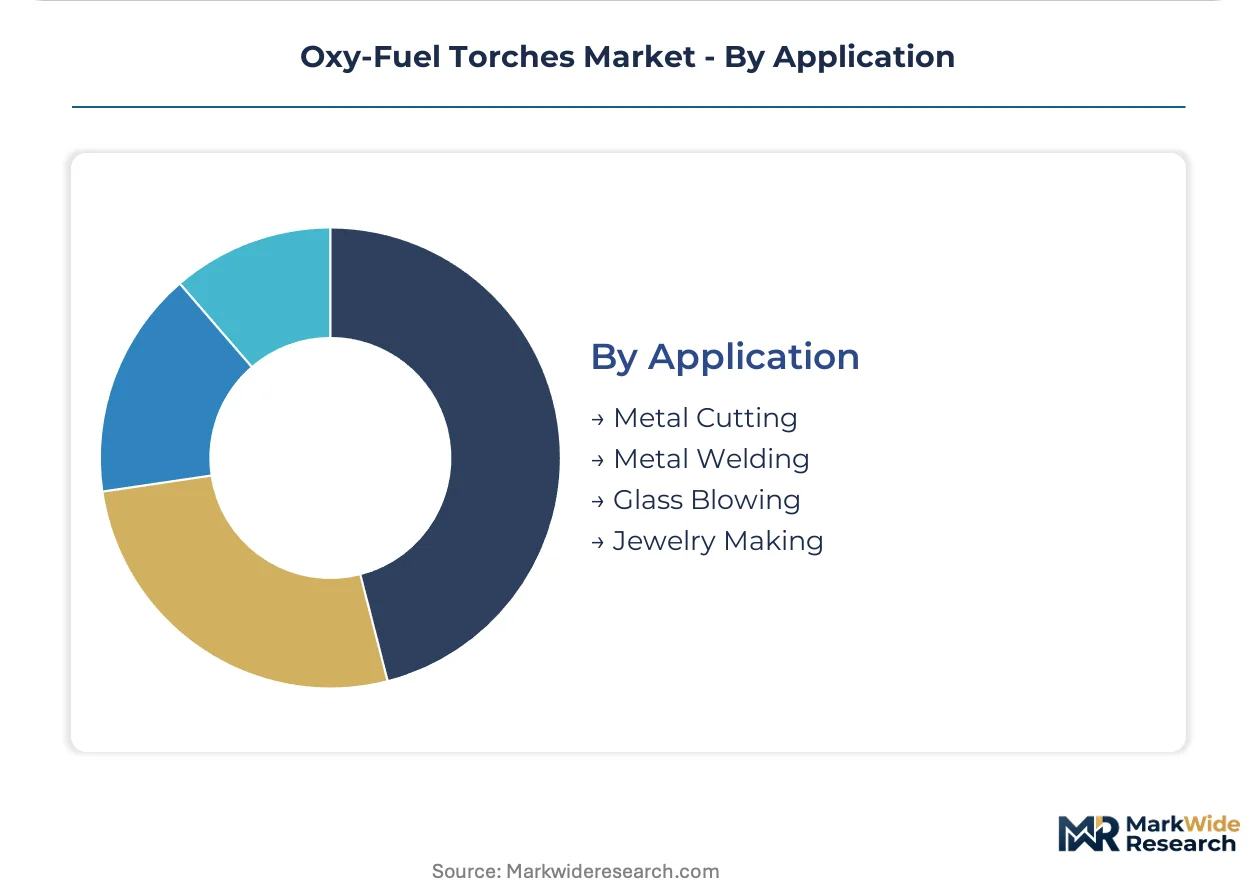
Application:
Skill threshold compression through digital flame controls is expanding addressable market in precision segments previously requiring artisan expertise.
- Metal Cutting:Primary severance application dominating torch deployment across shipbreaking, demolition, and structural fabrication. South Korean and Japanese shipyards are adopting smart gas flow controllers with Bluetooth connectivity for automated compliance documentation.
- Metal Welding:Fusion and brazing operations in automotive chassis and pressure vessel construction where flame chemistry control determines joint integrity.
- Glass Blowing:Artisan and industrial forming applications requiring precise thermal gradients.
- Jewelry Making:Fine-scale soldering and annealing in precious metals workshops.
Metal Cutting dominates absolute unit deployment. Glass Blowing is expanding most quickly on digital control adoption in artisan studios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators command 15-20% pricing premiums over Indian counterparts for certified torch systems, while Bangladeshi shipbreakers absorb cost volatility through dense secondhand equipment networks. This asymmetry shapes regional procurement patterns and fleet refresh cycles.
United States
Three-shift automotive stamping operations in Ohio and Texas drive continuous torch fleet expansion. OSHA respiratory and fire-safety mandates accelerate replacement cycles for certified systems meeting updated ventilation standards. Houston petrochemical construction sites anchor Gulf Coast demand where propane displacement of acetylene accelerates on transport safety.
Germany
Baden-Württemberg and Bavaria automotive suppliers maintain dense clusters of cutting and welding operations supporting electric vehicle platform fabrication. EU F-Gas Regulation compliance pressures gas suppliers toward lower-carbon propane blends requiring recalibrated torch tip geometry. Dortmund structural fabricators face frozen capital expenditure decisions around carbon-border adjustment uncertainty.
China
State-backed shipyard automation programs in Dalian and Shanghai drive machine-mounted torch-robot integration for thick-plate panel lines. MIIT industrial upgrading directives prioritize digitized flame control systems with automated compliance documentation. Yangtze River Delta fabricators absorb ISO 5172 certification delays through captive testing facilities.
India
Production-linked incentive schemes for capital goods and automotive components catalyze greenfield fab shop construction requiring complete torch fleet outfitting. BIS standards alignment with ISO 5172 governs product interchangeability for import substitution. Gujarat and Maharashtra industrial corridors concentrate demand among contract manufacturers serving export-oriented auto component suppliers.
Japan
Smart gas flow controllers with Bluetooth connectivity penetrate South Korean and Japanese shipyards for kerf consistency in thick-plate severance. METI carbon neutrality roadmaps pressure gas distributors toward hydrogen-blend fuel trials requiring torch system adaptation. Nagoya-area automotive suppliers trial throughput-based maintenance contracts shifting nozzle replacement liability to OEMs.
Oxy-Fuel Torches Market Competitive Landscape
Full-line welding equipment conglomerates and specialized cutting system engineers split the market between aftermarket consumable pull-through and precision application dominance. The vendor base concentrates among North American and European heritage manufacturers with captive distribution networks, while Asian specialists penetrate on cost-optimized shipyard packages. Two strategic archetypes predominate: diversified industrial gas suppliers leveraging fuel supply integration, and dedicated torch engineers betting on automated integration. Competitive moves center on direct-to-fleet digital procurement bypass and R&D intensity in robotic torch mounting.
Within the diversified industrial tier, Lincoln Electric Holdings and Illinois Tool Works anchor positions through captive distributor footprints sustaining aftermarket consumable revenue. ESAB exemplifies the engineering-intensive archetype through positioning in automated torch integration. Koike Aronson occupies a specialist position in heavy-duty cutting configurations for shipyard and structural steel applications. These three names represent the competitive spectrum from full-line conglomerate to application-focused engineer.
| Leading Market Players |
|---|
| Lincoln Electric Holdings, Inc. |
| ESAB |
| Air Liquide S.A. |
| Linde plc |
| Harris Products Group |
| Victor Technologies |
| GCE Group |
| Koike Aronson, Inc. |
| Illinois Tool Works Inc. |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Antwerp industrial gas corridor channels compressed fuel cylinders and precision torch components across North Sea ports, where freight cost volatility feeds directly into downstream price stratification between certified premium systems and standard field units.
Pricing Analysis
The customization-premium spread separates configured-to-order automated torch-robot systems from standard handheld units by a factor reflecting ISO 5172 certification tier and after-sales bundling intensity. Three-tier pricing structure across premium, standard, and economy levels anchors on flame control precision and compliance documentation capability. Cost compression in the standard tier is intensifying because propane displacement of acetylene erodes legacy manifold infrastructure premiums. Automotive stamping suppliers running three-shift operations show least price sensitivity, while independent construction contractors in Texas and Ohio absorb greatest margin pressure.
Supply Chain Analysis
Export-control regimes limiting precision nozzle machining technology flow from Germany and Japan constrain supply elasticity for high-tolerance cutting systems. Manufacturing concentration in Germany, China, and the United States shapes component availability for torch assembly. Brass forging stock, ceramic nozzle substrates, and precision gas regulators anchor raw material dependencies. Single-source vulnerability clusters around German automotive corridor demand spikes for EV platform fabrication. Distribution runs through captive welding distributor networks and emerging direct-to-fleet digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oxy-fuel torch market functions as a defensive-moat arena where regulatory certification entrenchment and installed-base switching costs protect incumbent positions against plasma substitution threats.
For Market Incumbents: Build switching-cost moats through captive aftermarket consumable contracts that lock fleet operators into proprietary nozzle geometries. Deepen backward integration into precision brass forging to defend against commodity feedstock volatility. Anchor channel control through welding distributor exclusivity agreements in Germany's automotive supplier corridor.
For New Entrants and Emerging Players: India's PLI-scheme greenfield fab shops represent the most penetrable entry point for complete torch fleet outfitting without legacy distributor entanglements. Automated torch-robot integration for South Korean shipyard panel lines offers white-space positioning against engineering-heavy incumbents. Pursue direct-to-fleet digital procurement partnerships with contract fabricators seeking throughput-based service structures.
For Investors and Strategic Acquirers: Specialist torch engineers with ISO 5172 certification capabilities and established shipyard relationships present the most defensible acquisition profile over the projection horizon. Monitor EU F-Gas Regulation phase-down compliance timelines as the critical inflection signal for fuel-mix standardization winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Torch-Robot Integration | Convergence with six-axis robotic arms opens high-volume repetitive cutting in South Korean shipyard panel lines. |
| Direct-to-Fleet Digital Procurement | B2B platforms bypass traditional welding distributors, letting OEMs capture aftermarket consumable revenue directly. |
| Fuel-Mix Recertification Investment | Tip geometry recalibration for EU F-Gas compliant propane blends secures operational legality across member states. |
| Throughput-Based Service Contracts | Automotive stamping suppliers shift nozzle replacement liability to OEMs, creating predictable operating expenditure structures. |
| Backward Integration into Brass Forging | In-house production of precision gas mixer components insulates margin predictability from commodity feedstock swings. |
Research Methodology
The analysis maps handheld, cutting, welding, and heating torch sub-sectors, each validated through maintenance directors at automotive stamping plants, welding distributor procurement leads, shipyard panel line engineers, and aftermarket service heads. Primary interviews with these stakeholders combined with secondary validation from customs/trade data, SEC 10-K filings, industrial gas distributor reports, and ISO certification registries. Bottom-up unit deployment estimates triangulated against top-down industrial fabrication capacity assessments.
Assumption sets held fuel-mix transition timelines and OSHA enforcement intensity fixed while varying reshoring velocity and plasma substitution rates across the analysis window. Segmentation dimensions modeled include product architecture, end-use industry, fuel technology, and regional regulatory cluster. CAGRs derived from fitted growth curves anchored to named country industrial capacity expansions and automotive platform launch cycles.
Stress conditions across acetylene feedstock volatility, EU carbon-border adjustment implementation, and shipyard automation adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Material shifts in EU F-Gas Regulation phase-down schedules or OSHA respiratory standard updates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Nut Runner Market
Tools
Industrial Plate Bending Machines Market
Tools
Thickness Planers Market
Tools
Global Scarifiers Market
Tools
Saw Blades Market
Tools
Cold and Hot Tool Steel Market
Tools
Log Splitters Market
Tools
Parting-Off Blades Market
Tools
Power Drill Market
Tools
Cordless Wood Planer Market
Tools
Portable Rolling Toolbox Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Rotary Tools Market
Tools
Diamond Hole Saw Market
Tools
Wood-Burning Tool Market
Tools
Chainsaw Market