
 Tool Setting Gauges Market | 2026-2036
Tool Setting Gauges Market Size, Share, and Industry Trends Forecast 2026-2036
Tool Setting Gauges Market Insights
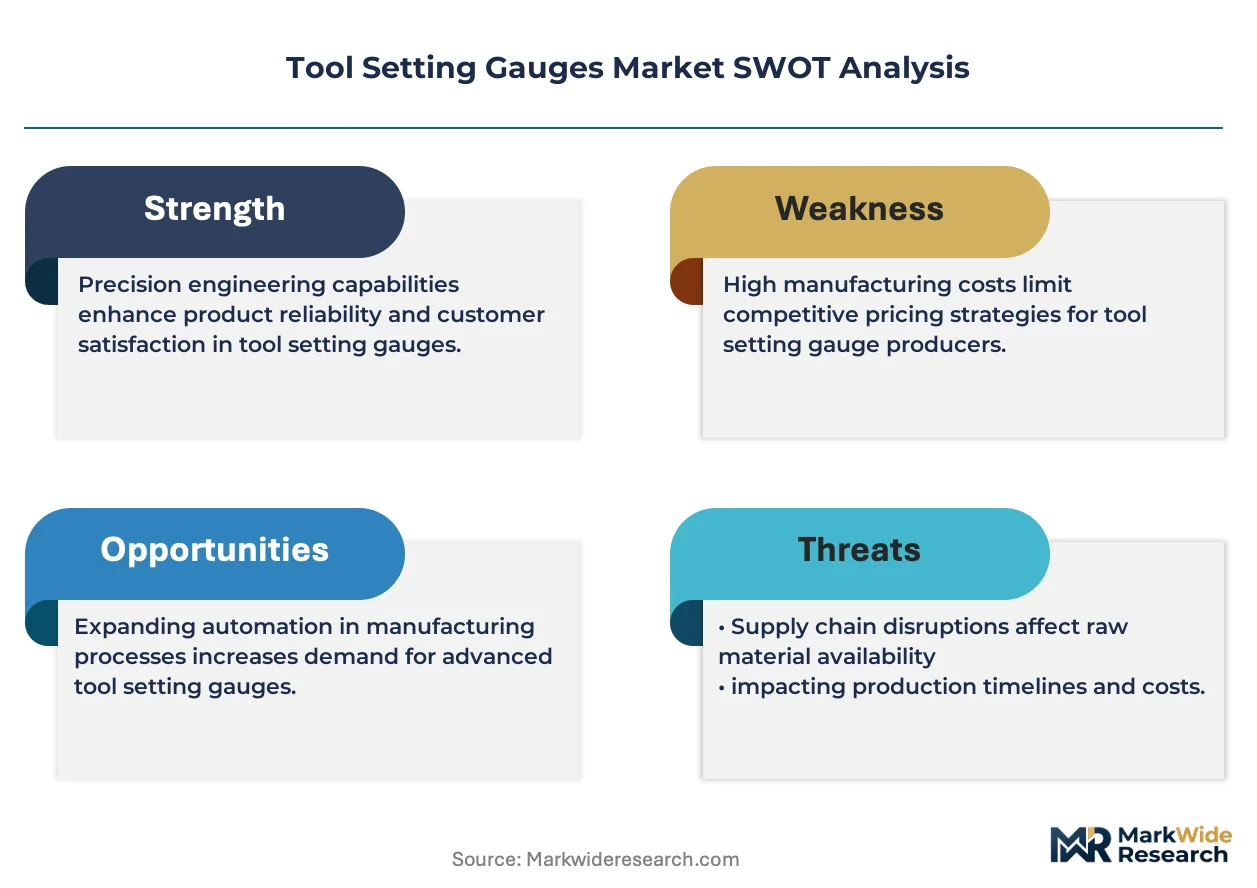
The gap between premium metrology-grade gauges and commodity setup tools is rebalancing as shop-floor digitization demands real-time feedback loops. Renishaw leverages its probe-to-gauge integration architecture to command the high-performance tier. Starrett anchors the mechanical gauge segment through deep distribution in North American job shops. Mitutoyo competes across both tiers with a calibrated product hierarchy spanning digital calipers to vision-based setting systems.
Tool setting gauges are precision instruments that establish the exact dimensional relationship between a cutting tool and a machine reference point, typically achieving repeatability within two microns through mechanical contact, optical triangulation, or laser beam interruption. Their primary industrial purpose is to eliminate manual trial cuts, compress setup times, and preserve spindle utilization rates in CNC machining environments. Electronic gauges and laser-based technology are capturing disproportionate margin pools as shops replace dial-indicator methods with automated tool presetter integration. Contact measurement retains volume dominance in legacy automotive stamping and general machining, while vision systems are penetrating electronics micro-tooling where sub-millimeter end mills require non-contact verification.
ISO 230 machine tool test codes, the EU Machinery Directive's safety and precision requirements, and FDA quality system regulations for medical device machining collectively elevate gauge calibration frequency and traceability documentation. Germany's KBA and the FAA's production approval procedures for aerospace suppliers further tighten tolerance verification protocols, directly expanding recurring gauge service demand. Stakeholders must weigh captive calibration investments against third-party metrology partnerships as audit density intensifies across regulated manufacturing verticals.
Market Dynamics
The convergence of ISO 230 tolerance verification with real-time machine tool feedback loops is restructuring gauge procurement priorities. Aerospace and medical device manufacturers now specify integrated probe-to-gauge architectures rather than standalone measurement tools, compressing vendor selection criteria toward metrology-system suppliers.
Growth Catalysts
- ISO 230 Test Codes:Tighter machine tool accuracy standards in Germany and the United States mandate more frequent gauge calibration cycles, expanding recurring service revenue streams for precision equipment suppliers.
- Five-Axis Machining Expansion:Aerospace manufacturers in Bavaria and Michigan require sub-micron tool setting verification for complex turbine blade geometries, driving demand for laser-based non-contact gauges.
- In-Machine Probing Integration:The shift from offline presetter benches to spindle-mounted measurement systems creates bundled procurement opportunities linking gauge hardware with CNC control architecture.
Market Restraints
- Calibration Infrastructure Concentration:Accredited metrology laboratories cluster in Germany, Japan, and Switzerland, creating logistics friction for gauge users in secondary manufacturing corridors.
- Skilled Technician Scarcity:The specialized competence required for laser interferometer alignment and vision system calibration limits deployment speed in general machining job shops.
- Capital Equipment Substitution:Machine tool builders embed tool measurement functionality directly into spindle designs, threatening standalone gauge volume in high-volume automotive stamping.
Strategic Opportunities
- Medical Device Machining:FDA quality system regulations for orthopedic implant production create captive calibration service demand with multi-year contract structures in Massachusetts and Minnesota.
- Electronics Micro-Tooling:Sub-millimeter end mills for printed circuit board fabrication require vision-based non-contact verification, opening technology gaps that optical gauge specialists can exploit.
- Cloud-Connected Gauge Networks:Shop-floor digitization initiatives enable predictive calibration scheduling and remote diagnostic services, transforming hardware sales into recurring platform revenue.
Industry Challenges
- Multi-Standard Certification Burden:Gauge manufacturers must simultaneously maintain ISO 17025 calibration accreditation, CE machinery directive compliance, and FDA device master file documentation, extending product launch timelines.
- Legacy System Integration Complexity:Retrofitting digital gauge interfaces to decades-old CNC controls with proprietary communication protocols demands costly custom engineering for each machine tool vintage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tool Setting Gauges Market |
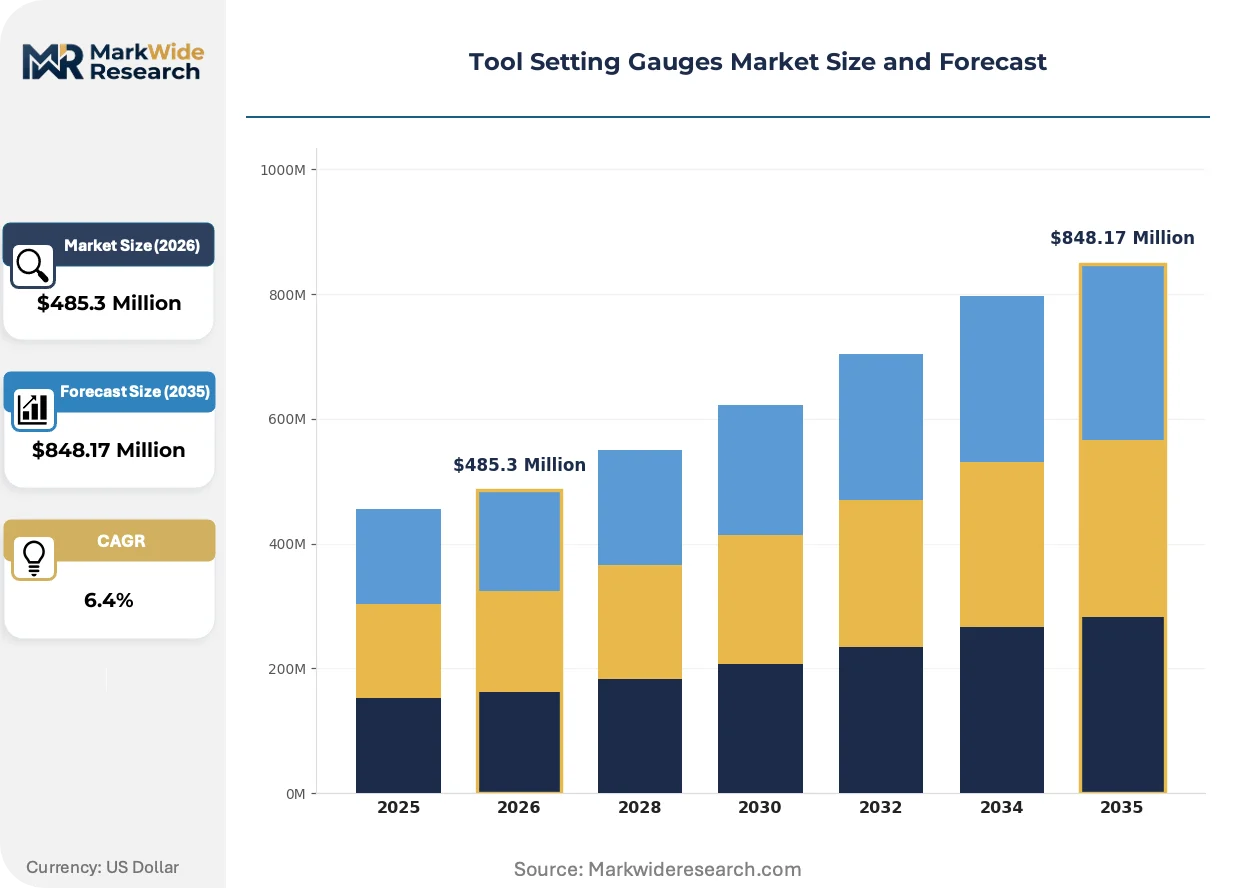
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $848.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Gauges, Electronic Gauges, Digital Gauges, Optical Gauges End User: Aerospace, Automotive, Manufacturing, Electronics Technology: Laser Technology, Vision Systems, Contact Measurement, Non-contact Measurement Application: Precision Machining, Quality Control, Tool Management, Setup Optimization |
| Companies Covered | Renishaw, Hexagon Manufacturing Intelligence, Zeiss, Mitutoyo, Starrett, Stanley Black & Decker, Robert Bosch Tool Corporation, Snap-On Incorporated, Apex Tool Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tool Setting Gauges Market Trends and Innovations
Measurement architecture is migrating from centralized metrology labs toward distributed shop-floor nodes. This spatial redistribution of quality verification is compressing feedback loops and redefining where precision equipment creates value.
Wireless gauge-to-cloud data pipelines are decentralizing quality control authority. Machine operators in Shanghai and Stuttgart now receive real-time tool offset adjustments without leaving the machining cell. This connectivity architecture is decentralizing metrology expertise from specialized departments onto the production floor itself.
REACH substance restrictions and the EU Machinery Directive's updated safety requirements are forcing gauge housing material transitions. Manufacturers must eliminate certain coatings and alloys from contact probe tips and structural frames. German gauge suppliers are accelerating ceramic and engineered polymer adoption to maintain CE marking eligibility for aerospace and medical verticals.
Buying committees now bundle gauge procurement with long-term calibration service agreements rather than treating hardware and metrology as separate spend categories. Distributors in the American Midwest respond by building captive ISO 17025 laboratories. This service attachment compression is most pronounced among automotive tier-one suppliers in Michigan and Ohio seeking audit-ready documentation packages.
Tool Setting Gauges Market Segmentation
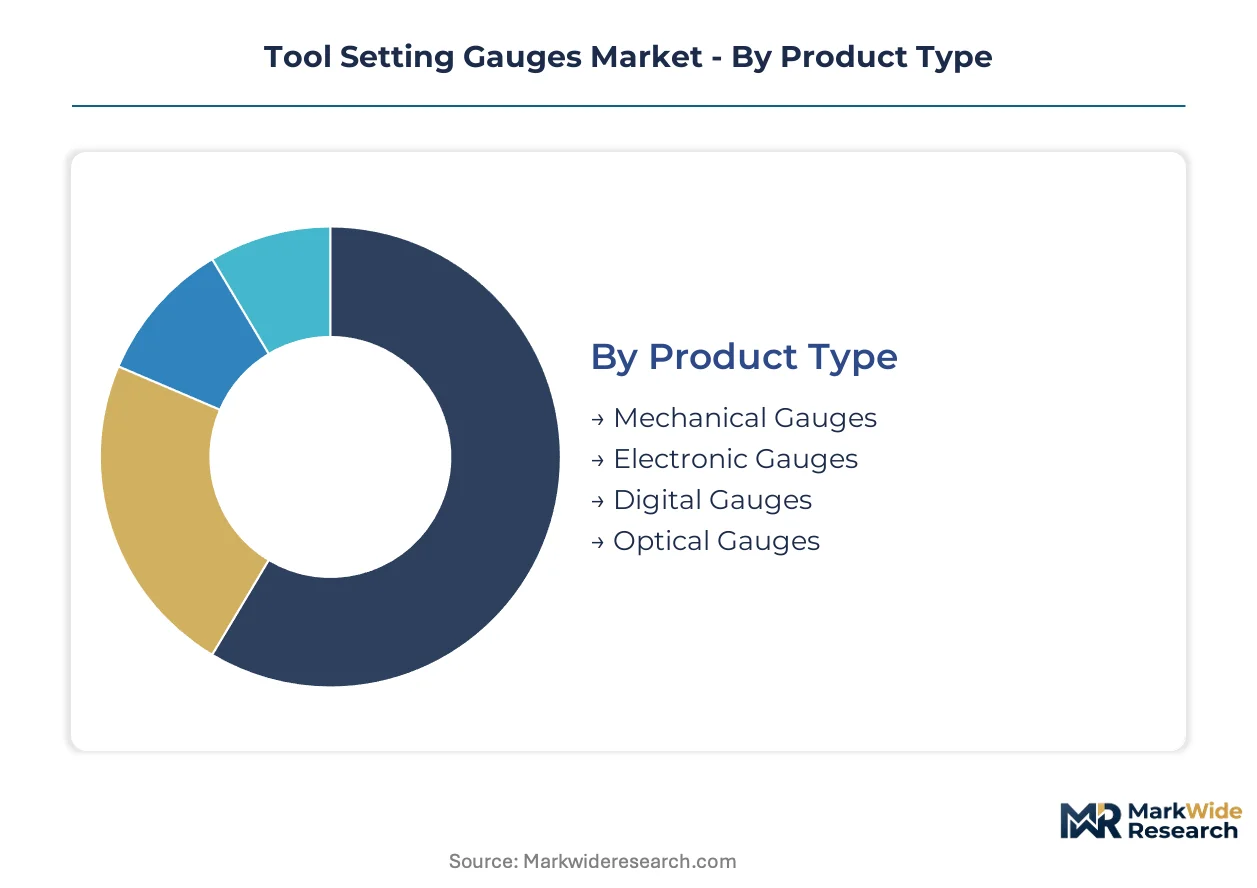
Tool setting gauge procurement splits sharply between legacy mechanical methods and integrated digital architectures. Aerospace and medical manufacturers now specify technology platforms rather than discrete instruments, collapsing traditional product boundaries into system-level purchasing decisions.
Product Type:
Supply concentrates among German and Japanese metrology houses with captive calibration networks, while commodity mechanical gauges fragment across regional job-shop distributors.
- Mechanical Gauges:Dial-indicator and vernier-based instruments with ±5 micron repeatability. Automotive stamping plants in Michigan and Ohio absorb the bulk of replacement volume as these shops defer capital upgrades amid contract pricing pressure.
- Electronic Gauges:Digital readout systems with RS-232 output and SPC data logging. Bavarian aerospace suppliers specify these for turbine blade machining cells where ISO 230 traceability documentation is mandatory.
- Digital Gauges:Microprocessor-controlled units with tool offset transmission direct to CNC controls. Massachusetts medical device manufacturers deploy these for orthopedic implant production under FDA quality system regulations.
- Optical Gauges:Vision-based systems using CCD triangulation for sub-millimeter end mills. Electronics micro-tooling corridors in Shanghai and Seoul are expanding most quickly as PCB fabrication densities tighten.
Mechanical gauges absorb the bulk of installed capacity; optical gauges are expanding most quickly.
End User:
Margin tiers separate regulated verticals with captive calibration requirements from general machining where price sensitivity dominates.
- Aerospace:FAA production approval procedures and Germany's KBA certification mandate sub-micron verification for five-axis turbine blade machining. Laser-based non-contact systems concentrate in Bavaria and Michigan where supplier audit density is highest.
- Automotive:High-volume stamping and powertrain machining with embedded spindle measurement reducing standalone gauge dependence. Tier-one suppliers in Ohio bundle gauge procurement with multi-year service contracts for audit-ready documentation.
- Manufacturing:General job-shop machining across North American Midwest and Chinese Pearl River Delta. Contact measurement retains dominance here as skilled technician scarcity limits laser system deployment.
- Electronics:PCB micro-drilling and semiconductor packaging with vision systems penetrating fastest. Sub-millimeter end mills in South Korean and Taiwanese fabrication facilities drive non-contact verification demand.
Aerospace commands the steepest pricing tier; electronics represents the fastest-growing trajectory.
Technology:
Measurement modality selection tracks tolerance requirements and operator skill availability across manufacturing corridors.
- Laser Technology:Beam-interruption systems achieving sub-two-micron repeatability for complex geometries. German and US aerospace manufacturers specify these for five-axis machining centers where spindle-mounted probing integration is required.
- Vision Systems:CCD-based optical triangulation for non-contact micro-tool verification. Electronics manufacturers in Shanghai and Stuttgart deploy these for real-time offset adjustment without operator intervention.
- Contact Measurement:Mechanical probe tips with direct tool engagement. Legacy automotive stamping retains volume here as capital equipment substitution threatens standalone gauge demand.
- Non-contact Measurement:Capacitive and pneumatic methods for delicate cutting edges. Medical device machining in Minnesota and Massachusetts adopts these for cobalt-chrome orthopedic implants where surface integrity is critical.
Contact measurement holds the largest installed base; vision systems are climbing the fastest.
Application:
Functional use case determines integration depth with CNC control architecture and cloud connectivity requirements.
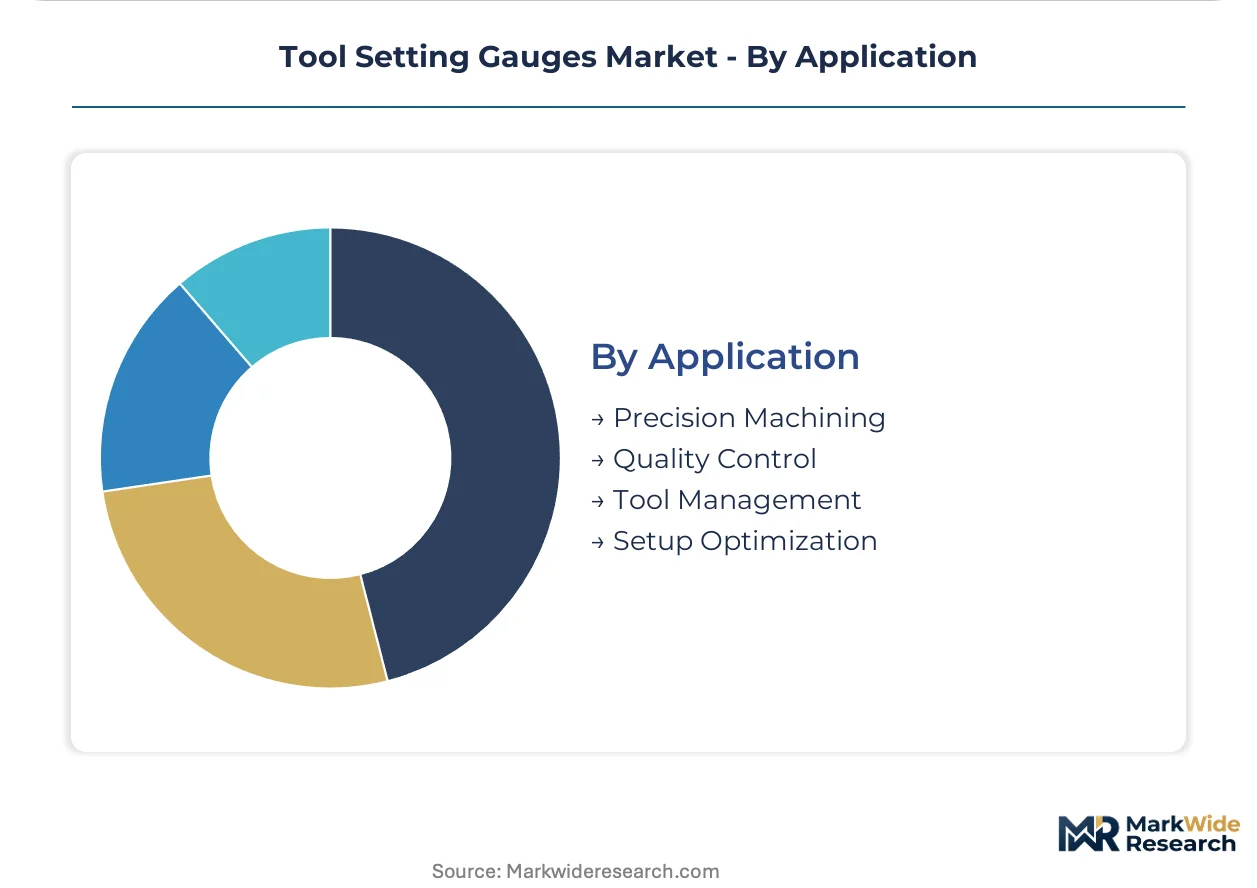
- Precision Machining:Sub-micron tool setting for aerospace turbine blades and medical implants. ISO 230 test code compliance in Germany and the United States elevates calibration frequency and documentation burden.
- Quality Control:In-process verification with SPC data logging for statistical process control. Automotive tier-one suppliers in Michigan require these capabilities for production part approval processes.
- Tool Management:Centralized presetting with tool life tracking and inventory optimization. Large-scale manufacturing in Shanghai deploys these systems across multi-machine cells.
- Setup Optimization:Spindle-mounted probing to eliminate manual trial cuts. Shop-floor digitization initiatives in Stuttgart and Detroit enable predictive calibration scheduling through cloud-connected gauge networks.
Precision machining dominates revenue concentration; setup optimization is gaining share fastest as in-machine probing displaces offline benches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's precision machining corridors concentrate the fastest-growing demand for vision-based tool setting systems as electronics manufacturers deploy sub-millimeter verification for PCB micro-drilling operations.
United States
Michigan and Ohio absorb the bulk of automotive tier-one gauge procurement as suppliers bundle hardware with multi-year calibration service contracts. FAA production approval procedures tighten tolerance verification protocols for aerospace manufacturers in the state. Bavaria-to-Michigan supply chain relationships concentrate laser-based non-contact system deployment across Detroit-area five-axis machining centers.
Germany
Bavarian aerospace clusters drive specification of integrated probe-to-gauge architectures for turbine blade machining cells. Germany's KBA certification mandates elevate audit density and recurring calibration frequency. Stuttgart-based manufacturers deploy cloud-connected gauge networks enabling predictive maintenance scheduling across multi-machine production floors.
China
Shanghai and Shenzhen electronics fabrication facilities expand vision system adoption for sub-millimeter end mill verification. GB standards alignment with ISO 230 test codes accelerates gauge calibration infrastructure investment. Pearl River Delta job shops digitize quality control through wireless gauge-to-cloud data pipelines.
Japan
Chubu region machine tool builders embed measurement functionality directly into spindle designs threatening standalone gauge volume. METI industrial digitization initiatives subsidize shop-floor sensor network deployment. Nagoya-area automotive suppliers consolidate presetter procurement through captive calibration partnerships.
South Korea
Seoul Capital Area semiconductor packaging corridors adopt non-contact verification for micro-tooling applications. MFDS quality system requirements for medical device machining create regulatory pull for traceable gauge documentation. Busan-Ulsan manufacturing clusters integrate tool setting systems with CNC control architecture for real-time offset adjustment.
Tool Setting Gauges Market Competitive Landscape
Premium-margin players sit above commodity-margin players across calibration service attachment and probe-to-control integration depth. The market structures into three tiers: metrology-system suppliers with captive ISO 17025 networks, precision equipment houses with regional distribution density, and commodity gauge fabricators competing on replacement volume. Strategic moves concentrate on M&A for calibration laboratory accreditation and technology licensing for CNC control protocol compatibility.
Within the metrology-system tier, Renishaw and Hexagon Manufacturing Intelligence exemplify the probe-to-gauge integration architecture that aerospace and medical manufacturers now specify. Mitutoyo occupies a position spanning both premium and mid-market segments through calibrated product hierarchy. Starrett anchors the mechanical gauge tier with deep distribution penetration across North American job shops. These three names represent the competitive archetypes reshaping procurement committee composition as bundled hardware-service agreements displace discrete instrument purchasing.
| Leading Market Players |
|---|
| Renishaw |
| Hexagon Manufacturing Intelligence |
| Zeiss |
| Mitutoyo |
| Starrett |
| Stanley Black & Decker |
| Robert Bosch Tool Corporation |
| Snap-On Incorporated |
| Apex Tool Group |
| Others |
Pricing and Supply Chain Analysis
Bundled procurement of gauge hardware with multi-year calibration service contracts is forcing suppliers to restructure pricing architectures around recurring revenue attachment rather than discrete instrument sales. Aerospace manufacturers in Bavaria and Michigan now specify ISO 17025-accredited service tiers as mandatory bid requirements, compressing margin pools for commodity gauge fabricators while elevating metrology-system suppliers.
Pricing Analysis
Outcome-based pricing anchored to spindle uptime guarantees and scrap-rate reduction separates premium-tier suppliers from commodity competitors. Three-tier pricing structure across premium, standard, and economy levels stratifies by calibration accreditation depth and probe-to-control integration capability. Cost compression in the mechanical gauge tier intensifies as automotive stamping plants defer capital upgrades amid contract pricing pressure. General machining job shops in the North American Midwest exhibit the highest price sensitivity, while FDA-regulated medical device manufacturers in Massachusetts and Minnesota absorb premium pricing for audit-ready documentation packages.
Supply Chain Analysis
ISO 17025 calibration accreditation acts as a supply-side gate, concentrating certified gauge production in Germany, Japan, and Switzerland where metrology infrastructure density is highest. Ceramic probe tips and engineered polymer housings draw from specialized materials suppliers adapting to REACH substance restrictions and EU Machinery Directive safety requirements. Single-source vulnerability concentrates in accredited metrology laboratory capacity, creating logistics friction for gauge users in secondary manufacturing corridors. Distribution runs through captive calibration partnerships and regional job-shop distributor networks, with automotive tier-one suppliers in Ohio and Michigan consolidating procurement through bundled hardware-service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ISO 230 test code adherence and FDA quality system regulations erect barrier-to-entry moats that favor incumbent metrology-system suppliers with captive calibration networks.
For Market Incumbents: Extend calibration service coverage into secondary manufacturing corridors through mobile laboratory deployments or regional accreditation partnerships. Deepen probe-to-CNC control integration architectures to defend against machine tool builders embedding measurement functionality directly into spindle designs. Prioritize cloud-connected gauge network development to transform hardware sales into recurring platform revenue streams. For New Entrants and Emerging Players: Enter via vision-based non-contact verification systems for electronics micro-tooling applications in Shanghai and Seoul, where sub-millimeter end mill demand outpaces established supplier capacity. Target PCB fabrication facilities with simplified calibration service bundles that reduce audit documentation burden compared to incumbent offerings. Pursue technology licensing arrangements with CNC control protocol specialists to accelerate integration timelines. For Investors and Strategic Acquirers: The window for entry favors calibration laboratory networks with existing ISO 17025 accreditation and established relationships with aerospace or medical device manufacturers. Long-term viability hinges on recurring service revenue attachment rates rather than hardware shipment volumes. Watch for inflection signals in machine tool builder spindle-embedded measurement adoption rates, which threaten standalone gauge demand in high-volume automotive stamping.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | ISO 17025 accreditation secures recurring service revenue from FDA-regulated medical device manufacturers. |
| Probe-to-Control Integration Development | Direct CNC architecture linkage meets aerospace manufacturer specifications for five-axis machining centers. |
| Cloud-Connected Gauge Network Deployment | Wireless data pipelines enable predictive maintenance scheduling for Stuttgart-based multi-machine production floors. |
| Vision System Technology Licensing | CCD triangulation capabilities address sub-millimeter verification gaps in Shanghai electronics fabrication corridors. |
| Regional Distribution Partnership | Midwest captive laboratory buildout captures automotive tier-one bundled procurement demand in Michigan and Ohio. |
Research Methodology
Trade association filings, customs and import-export databases, and machine tool builder technical documentation formed the secondary backbone of this analysis. Primary interviews with gauge calibration technicians, aerospace manufacturing engineers, medical device quality directors, and CNC control system integrators provided operational validation. Bottom-up shipment data triangulated against top-down equipment investment surveys across the analysis window.
Historical trendline analysis of gauge procurement patterns across product type, technology modality, and end-use vertical established baseline growth trajectories. Segmentation modeling incorporated measurement precision tier, integration depth with CNC architecture, and regional regulatory cluster variations. CAGRs derived from equipment replacement cycle analysis and capital expenditure survey data, with cross-validation against machine tool installation rates and spindle probing adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in ISO 230 test code stringency or machine tool builder embedded measurement functionality deployment. Forecasts reflect documented assumptions regarding calibration infrastructure expansion rates and skilled technician availability. A model refresh is warranted upon material change in FAA production approval procedure timelines or EU Machinery Directive safety requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Clamps Market
Tools
Entrenching Tool Market
Tools
Air Hammer Market
Tools
Hydraulic Torque Wrench Market
Tools
Fixed Cutter Bits Market
Tools
Foldable Ladder Market
Tools
Global Construction Camera Market
Tools
Vise-Grip Pliers Market
Tools
Shredder Blades Market
Tools
Bar Clamp Market
Tools
End Milling Machine Market
Tools
Gear Honing Machines Market
Tools
Taps and Dies Market
Tools
Pneumatic Bolting Tools Market
Tools
Multi-Tasking Machine Tools Market
Tools
Woodworking Power Tools Market