
 GCC Construction Machinery Rental Market | 2026-2036
GCC Construction Machinery Rental Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Construction Machinery Rental Market Insights
Buyer concentration among mega-project developers is realigning fleet procurement toward long-term rental contracts with embedded maintenance. Byrne Equipment Rental LLC leverages its UAE-Saudi cross-border depot network to sustain utilization rates across giga-project clusters. Zahid Tractor & Heavy Machinery Co. anchors its position through Caterpillar-exclusive distribution and captive parts logistics. Johnson Arabia LLC differentiates via specialized crane fleets serving high-rise commercial towers in Dubai and Riyadh.
GCC construction machinery rental denotes the short-to-long-term leasing of earthmoving, lifting, and material-handling equipment with operator provision and technical support, where crawler excavators typically span 20-45 tonne operating weights and tower cranes reach 80-120 metre hook heights under luffing-jib configurations. The model substitutes capital expenditure with operational flexibility for contractors facing project-cycle volatility. Excavators dominate fleet value due to universal earthworks demand across residential and road applications, while cranes command premium daily rates reflecting certified-operator scarcity and mobilization complexity. Short-term rental captures peak-demand spikes from seasonal construction windows, though long-term rental with full maintenance contracts is expanding as infrastructure developers seek predictable operating expenditure structures over multi-year project horizons.
Saudi Arabia's Saudi Standards, Metrology and Quality Organization (SASO) and the UAE's Ministry of Industry and Advanced Technology enforce equipment safety certification and emissions compliance that shape fleet renewal cycles and import specifications across the GCC. The Gulf Cooperation Council's unified customs framework and technical regulations facilitate cross-border equipment redeployment, though national licensing requirements for crane operators and heavy-transport permits fragment operational standardization. Stakeholders must monitor how Saudi Vision 2030 project acceleration and Qatar's post-World Cup infrastructure transition redistribute rental demand across equipment categories and contract durations.
Market Dynamics
Saudi Vision 2030 infrastructure mandates are redirecting developer capital toward leased equipment rather than ownership, compressing fleet procurement cycles and embedding multi-year maintenance contracts into rental structures.
Growth Catalysts
- SASO Emissions Compliance:Saudi Standards, Metrology and Quality Organization certification requirements are accelerating fleet renewal cycles toward newer, cleaner equipment that rental providers stock preferentially.
- Giga-Project Clustering:NEOM, Red Sea Project, and Qiddiya developments in Saudi Arabia concentrate demand for 20-45 tonne crawler excavators and 80-120 metre tower cranes in predictable geographic corridors.
- Telematics Integration:IoT-enabled fleet monitoring systems allow rental operators to guarantee uptime percentages and optimize redeployment across UAE-Saudi border depots.
Market Restraints
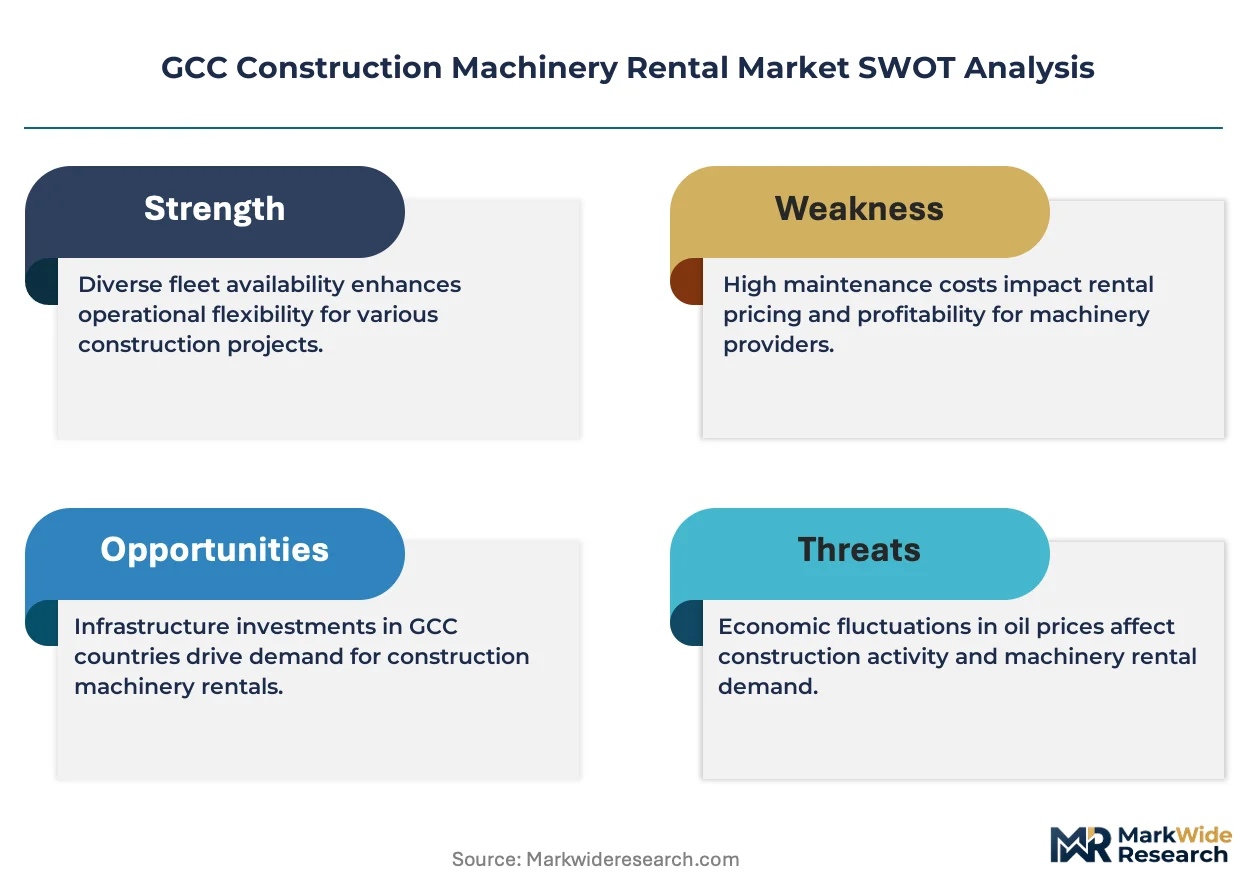
- Steel Price Volatility:Fluctuations in global steel markets directly impact crane boom and excavator arm manufacturing costs, compressing rental margin buffers on fixed-rate contracts.
- Operator Certification Bottlenecks:National licensing requirements for crane operators in Saudi Arabia and the UAE fragment workforce mobility and extend mobilization timelines for specialized lifting equipment.
- Used Equipment Import Competition:Lower-cost second-hand machinery from European and East Asian markets undercuts rental pricing power for standard earthmoving categories.
Strategic Opportunities
- Qatar Post-World Cup Infrastructure:Stadium conversion and hospitality repurposing projects are generating demand for specialized material-handling equipment on flexible short-term terms.
- Maintenance Contract Unbundling:Separate technical service agreements allow rental providers to capture recurring revenue streams independent of equipment utilization rates.
- Kuwait Five-Year Development Plan:Silk City and Boubyan Island projects represent underpenetrated demand centers for long-term rental partnerships with embedded operator provision.
Industry Challenges
- Certified Crane Operator Scarcity:Luffing-jib tower crane operation requires specialized licensing that outpaces training program output across the GCC, constraining fleet expansion.
- Cross-Border Permit Fragmentation:Heavy-transport licensing inconsistencies between Saudi Arabia and the UAE complicate equipment redeployment and inflate logistics costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Construction Machinery Rental Market |
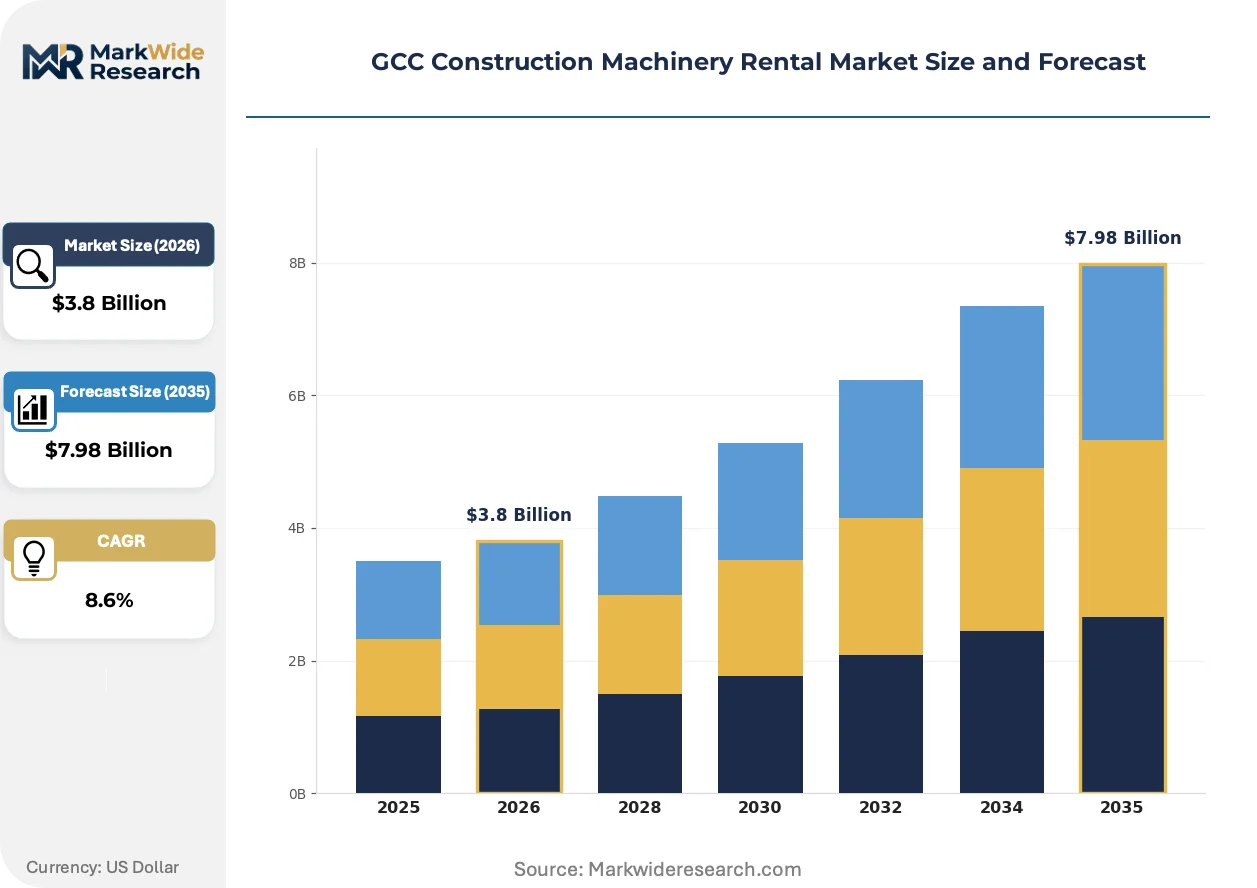
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Cranes, Forklifts, Bulldozers End User: Construction Companies, Contractors, Government Agencies, Infrastructure Developers Service Type: Short-term Rental, Long-term Rental, Maintenance Services, Equipment Leasing Application: Residential Projects, Commercial Projects, Industrial Projects, Road Construction |
| Companies Covered | Al Faris Group, Bin Quraya, Byrne Equipment Rental LLC, Arabian Machinery & Heavy Equipment Co. (AMHEC), Mohamed Abdulrahman Al-Bahar LLC, Zahid Tractor & Heavy Machinery Co., Johnson Arabia LLC, Rezayat Sparrow Arabian Crane Hire Co. Ltd., Hertz Dayim Equipment Rental, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Construction Machinery Rental Market Trends and Innovations
Digital fleet management systems and alternative powertrains are actively reshaping equipment specifications and contract structures across GCC rental markets.
Hybrid-electric powertrains for 20-45 tonne excavators are converging with diesel-mechanical systems in high-utilization fleet deployments. NEOM and Red Sea Project developers specify hybrid units for indoor and tunnel earthworks where emissions restrictions apply. This convergence is compressing the payback period differential between conventional and electrified equipment, accelerating rental provider investment in dual-power fleets.
SASO technical regulations for construction equipment safety certification now mandate third-party inspection protocols that parallel EU machinery directives. Rental operators must maintain documented maintenance histories and operator training records to retain certification validity. Tower crane fleets in Riyadh and Jeddah corridors face the steepest compliance costs due to height-specific structural testing requirements.
Long-term rental with full maintenance contracts is displacing short-term spot rentals for infrastructure developers seeking predictable operating expenditure structures. Saudi giga-project procurement teams now specify five-to-seven-year equipment leases with embedded technical support and guaranteed uptime clauses. This behavioral shift is most visible in Riyadh corridor developments where project finance requirements favor operational expense treatment over capital expenditure recognition.
GCC Construction Machinery Rental Market Segmentation
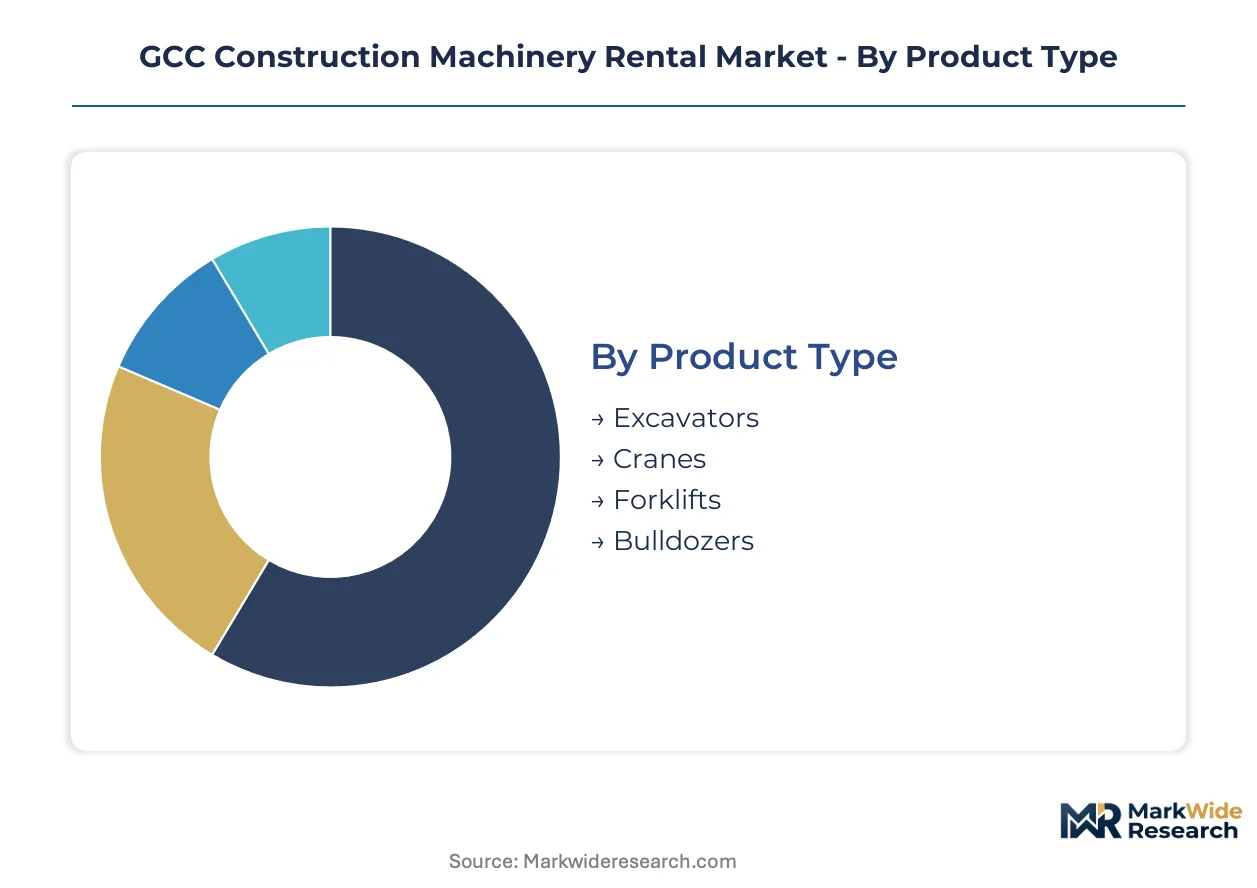
Equipment rental decisions in GCC construction markets hinge on project duration predictability, regulatory compliance burdens, and capital structure preferences. Segment boundaries shift as Saudi giga-developments compress procurement cycles and embed multi-year maintenance obligations into contract frameworks.
Product Type:
Buyers differentiate by lifting capacity requirements, terrain adaptability, and operator certification complexity rather than brand preference alone.
- Excavators:20-45 tonne crawler configurations dominate fleet value through universal earthworks demand across NEOM and Red Sea Project corridors. Saudi SASO emissions certification accelerates replacement cycles toward Tier 4 Final and hybrid-electric units for tunnel and indoor applications.
- Cranes:Luffing-jib tower cranes reaching 80-120 metre hook heights command premium daily rates reflecting certified-operator scarcity and complex mobilization logistics. Riyadh and Jeddah high-rise clusters concentrate demand where structural testing requirements under SASO technical regulations inflate compliance costs.
- Forklifts:Material-handling fleets serve warehouse and logistics hub construction with shorter deployment cycles.
- Bulldozers:Tracked dozers support site preparation and grading for road and residential earthworks.
Excavators lead volumes today; cranes are gaining share fastest through giga-project clustering and premium rate structures.
End User:
Procurement sophistication varies sharply by balance sheet capacity and project finance structure requirements.
- Construction Companies:Large integrated builders operating across UAE-Saudi corridors favor long-term rental with embedded maintenance to convert capital expenditure into predictable operating expense for project finance compliance.
- Contractors:Subcontracting specialists serving peak-demand windows rely on short-term rental flexibility with operator provision to match workforce scaling to seasonal construction cycles.
- Government Agencies:Public procurement entities specify SASO-certified equipment with documented maintenance histories for infrastructure sovereignty projects.
- Infrastructure Developers:Mega-project sponsors at NEOM, Qiddiya, and Red Sea Project mandate five-to-seven-year lease structures with guaranteed uptime clauses and cross-border depot support.
Infrastructure developers lead contract value today; contractors are expanding fastest through spot-market volatility absorption.
Service Type:
Margin capture depends on bundling depth and technical service unbundling strategies.
- Short-term Rental:Daily and weekly terms capture seasonal demand spikes from Qatar post-World Cup conversion projects and Kuwait Five-Year Development Plan acceleration.
- Long-term Rental:Multi-year contracts with full maintenance displace spot rentals as Saudi Vision 2030 developers seek operational expenditure predictability over capital commitment.
- Maintenance Services:Unbundled technical agreements generate recurring revenue independent of equipment utilization rates.
- Equipment Leasing:Finance lease structures transfer residual value risk to operators while preserving fleet control.
Long-term rental leads revenue concentration today; maintenance services are climbing the fastest through contract unbundling.
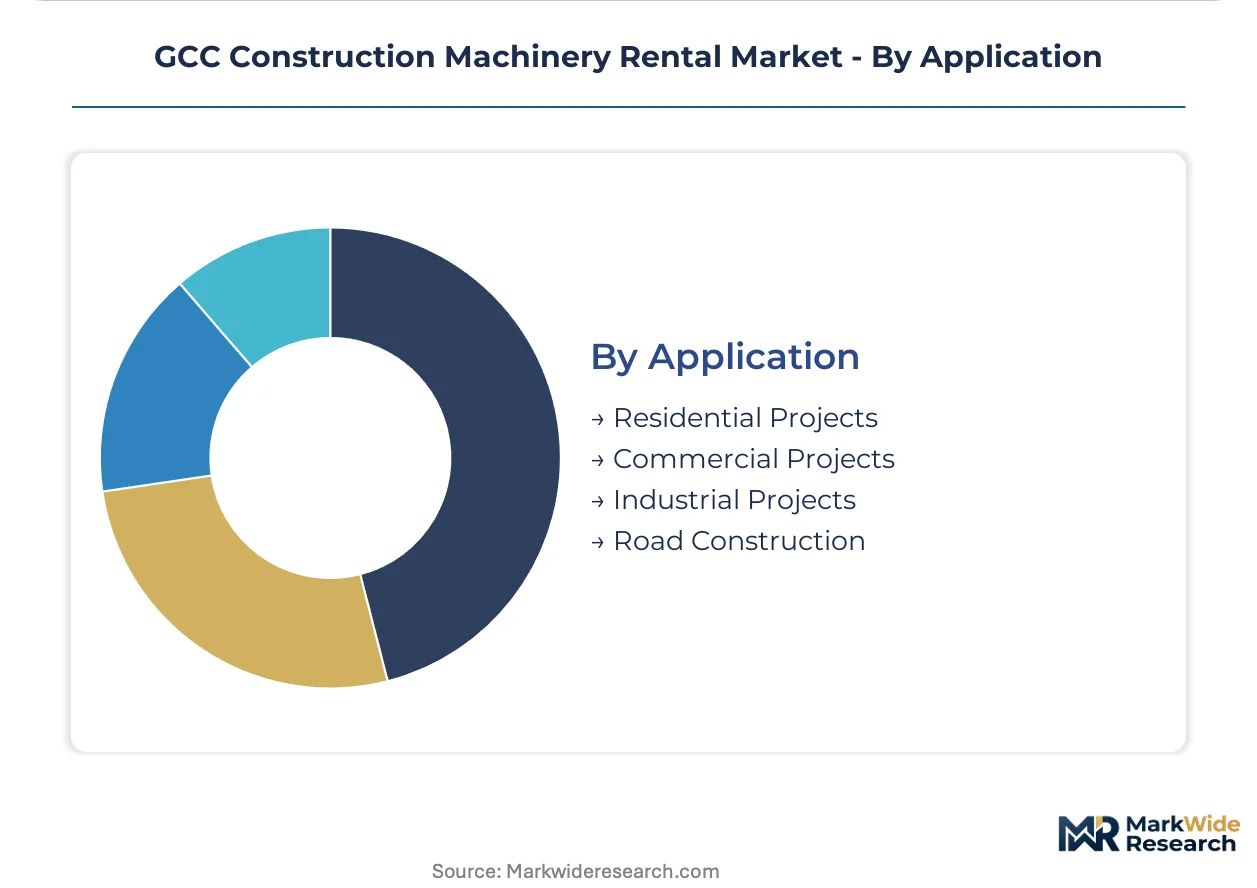
Application:
Project type determines equipment specification, regulatory exposure, and contract duration preferences.
- Residential Projects:Mid-rise tower construction in Riyadh and Jeddah corridors drives demand for 20-45 tonne excavators and mobile cranes with rapid mobilization capabilities.
- Commercial Projects:High-rise towers in Dubai and Riyadh specify luffing-jib tower cranes where height-specific SASO structural testing requirements concentrate compliance costs.
- Industrial Projects:Manufacturing and logistics facility construction requires specialized material-handling fleets with emissions-compliant specifications.
- Road Construction:Highway and bridge earthworks sustain excavator and bulldozer utilization across predictable geographic corridors.
Commercial projects lead premium rate capture today; industrial projects are expanding most quickly through logistics hub construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands the dominant share of GCC construction machinery rental demand, while the UAE maintains specialized crane and high-rise equipment density that reflects its mature commercial tower market.
Saudi Arabia
NEOM, Red Sea Project, and Qiddiya giga-developments concentrate demand for 20-45 tonne crawler excavators and 80-120 metre tower cranes in the Riyadh-Jeddah corridor. SASO emissions certification mandates accelerate fleet renewal toward Tier 4 Final and hybrid-electric units. The Eastern Province hosts expanding petrochemical and logistics facility construction requiring specialized material-handling fleets.
United Arab Emirates
Dubai's high-rise commercial tower pipeline sustains premium daily rates for luffing-jib tower cranes with certified-operator provision. MOHAP equipment safety protocols and municipal crane licensing requirements shape fleet specifications and compliance costs. Cross-border depot networks from Dubai and Abu Dhabi facilitate rapid redeployment toward Saudi giga-project corridors.
Qatar
Post-World Cup stadium conversion and hospitality repurposing projects generate flexible short-term demand for material-handling and earthmoving equipment. The country's central municipal regulator enforces equipment inspection protocols that parallel SASO technical requirements. Doha-based rental operators are repositioning fleet mix toward industrial and logistics construction applications.
Kuwait
Silk City and Boubyan Island developments under the Five-Year Development Plan represent underpenetrated demand centers for long-term rental partnerships with embedded operator provision. National infrastructure procurement entities specify documented maintenance histories and certified-operator credentials for sovereign project eligibility. The Ahmadi and Al Asimah Governorates concentrate equipment deployment for port and logistics hub expansion.
GCC Construction Machinery Rental Market Competitive Landscape
UAE-based operators anchor the premium crane and specialized lifting tier; Saudi-domiciled fleet holders dominate earthmoving and mass excavation procurement. Market structure reflects moderate consolidation around family-owned conglomerates with captive maintenance capabilities and cross-border logistics networks. Three archetypes predominate: Caterpillar-exclusive distributors with captive parts logistics, independent multi-brand fleet operators with telematics-enabled redeployment, and specialized crane providers serving high-rise vertical construction. Competitive positioning hinges on multi-year maintenance contract capture and cross-border permit navigation between Saudi Arabia and the UAE.
Within the distributor-affiliated tier, Zahid Tractor & Heavy Machinery Co. and Mohamed Abdulrahman Al-Bahar LLC exemplify Caterpillar-exclusive positioning with integrated parts and service infrastructure. Among independent operators, Byrne Equipment Rental LLC occupies a position defined by UAE-Saudi cross-border depot density and telematics-enabled fleet optimization. Johnson Arabia LLC represents the specialized crane archetype, anchoring high-rise commercial tower segments in Dubai and Riyadh through certified-operator provision and luffing-jib technical capabilities.
| Leading Market Players |
|---|
| Al Faris Group |
| Bin Quraya |
| Byrne Equipment Rental LLC |
| Arabian Machinery & Heavy Equipment Co. (AMHEC) |
| Mohamed Abdulrahman Al-Bahar LLC |
| Zahid Tractor & Heavy Machinery Co. |
| Johnson Arabia LLC |
| Rezayat Sparrow Arabian Crane Hire Co. Ltd. |
| Hertz Dayim Equipment Rental |
| Others |
Pricing and Supply Chain Analysis
Global steel price indices cascade through crane boom and excavator arm fabrication costs, compressing rental margin buffers and forcing fleet operators toward longer-term contract structures that lock in utilization rates across Saudi giga-project corridors.
Pricing Analysis
Capacity additions in the UAE and Saudi Arabia are reshaping price floors for standard earthmoving categories while preserving premium tiers for certified-operator crane provision. Three-tier pricing structure across premium, standard, and economy levels separates SASO-certified hybrid fleets from Tier 3 diesel units and used-import alternatives. Pricing pressure stems from European and East Asian second-hand machinery undercutting spot rental rates for excavators and bulldozers. Subcontracting specialists serving peak-demand windows exhibit highest price sensitivity; infrastructure developers with project finance compliance requirements accept premium long-term rates for operational expenditure predictability.
Supply Chain Analysis
Workforce availability constraints in Japan, South Korea, and Germany limit output of precision-engineered hydraulic systems and electronic control modules for Tier 4 Final powertrains. Component sourcing draws from Chinese steel foundries, German hydraulic component specialists, and Japanese engine manufacturers. Single-source vulnerability concentrates in luffing-jib tower crane winch systems and telematics control units. Distribution runs through Caterpillar-exclusive distributors with captive parts logistics, independent multi-brand depot networks, and specialized crane providers with certified-operator pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in GCC construction machinery rental rests on fleet operators capturing maintenance contract unbundling revenue and redirecting procurement toward hybrid-electric units that command SASO-compliant premium tiers.
For Market Incumbents: Anchor cross-border depot density between Dubai and Riyadh to sustain utilization rates across giga-project clusters. Invest in captive parts logistics for Tier 4 Final and hybrid powertrain components before SASO emissions mandates accelerate replacement cycles. Defend against used-import competition by embedding five-to-seven-year maintenance contracts with guaranteed uptime clauses that spot-market operators cannot replicate.
For New Entrants and Emerging Players: Enter via Kuwait's Silk City and Boubyan Island developments where long-term rental partnerships remain underpenetrated relative to Saudi corridor saturation. Target industrial and logistics facility construction segments where emissions-compliant material-handling fleets face less price pressure than standard earthmoving categories. Lead with telematics-enabled fleet monitoring as a differentiated uptime guarantee rather than competing on daily rental rates alone.
For Investors and Strategic Acquirers: Asymmetric upside sits with independent multi-brand fleet operators possessing UAE-Saudi cross-border permit navigation capabilities and unbundled maintenance revenue streams. Long-term viability favors operators with embedded operator training programs addressing certified crane operator scarcity. Monitor Saudi Vision 2030 project acceleration timelines as the primary inflection indicator for fleet utilization rate expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Border Depot Network Expansion | UAE-Saudi logistics integration captures NEOM and Red Sea Project demand clustering. |
| Hybrid-Electric Fleet Conversion | SASO emissions mandates accelerate payback convergence with conventional diesel units. |
| Maintenance Contract Unbundling | Separate technical service agreements generate recurring revenue independent of utilization. |
| Certified Operator Training Programs | Proprietary luffing-jib crane credentials address structural scarcity constraining fleet expansion. |
| Telematics Platform Integration | IoT-enabled uptime guarantees differentiate long-term rental offerings from spot-market competitors. |
Research Methodology
Bottom-up infrastructure developer procurement modeling reconciled against top-down rental fleet deployment tracking forms the analytical core of this study. Primary interviews with fleet operations directors, giga-project procurement managers, SASO certification auditors, and cross-border logistics coordinators combined with secondary validation from customs trade databases, equipment manufacturer order backlogs, and municipal crane licensing registries. Top-down triangulation against GCC customs framework data and project development pipeline databases ensures segmentation integrity.
Historical trendline analysis across equipment category deployment patterns and contract duration preferences established baseline growth trajectories. The projection framework models product type, end user procurement structure, service type bundling depth, and application vertical across the analysis window. CAGRs derive from regression analysis of fleet utilization rates and replacement cycle acceleration under SASO technical regulations. Forecast inputs include steel price volatility indices and certified operator training program output capacity.
Inputs from primary field interviews and manufacturer order disclosures were available through the study window; gaps in real-time fleet utilization telemetry introduce uncertainty bands around short-term demand spike projections. Forecasts reflect documented assumptions regarding Saudi Vision 2030 project acceleration and Qatar post-World Cup infrastructure transition timelines. Material deviation in giga-project procurement pacing or SASO emissions mandate enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market