
 Cold Insulation Market | 2026-2036
Cold Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Insulation Market Intelligence
European production capacity for polyisocyanurate and polyurethane foams is recalibrating supply chains for HVAC and building applications. Saint-Gobain specializes in high-performance fiberglass and foam solutions for demanding industrial environments. Owens Corning Corporation leverages its extensive distribution network to serve both residential and commercial construction sectors. Meanwhile, BASF SE competes through its advanced chemical formulation expertise, developing specialized foam products for refrigeration and cryogenic uses.
Cold insulation comprises materials engineered to minimize heat gain in mechanical systems operating at sub-ambient temperatures. These materials exhibit low thermal conductivity, often with k-values below 0.04 W/m·K, to ensure operational efficiency. Their primary purpose is to maintain stable low temperatures, prevent surface condensation, and protect temperature-sensitive goods in applications like food processing and pharmaceutical storage. While foam insulation constitutes the largest product segment by volume, aerogel insulation is expanding in cryogenic storage where space is a critical constraint. Among end-users, cold chain logistics and pharmaceutical companies command higher margins due to stringent performance requirements.
Regulatory frameworks significantly influence material specifications and market access. The EU's F-Gas Regulation and the US EPA's Significant New Alternatives Policy (SNAP) program indirectly drive demand for superior insulation by phasing out certain refrigerants and promoting energy efficiency. Additionally, standards from organizations like ASHRAE and ISO set performance benchmarks for thermal resistance and fire safety in building and industrial installations. Future material selection will increasingly weigh thermal performance against lifecycle environmental impact, recyclability, and compliance with circular economy principles.
Market Dynamics
The expansion of cryogenic infrastructure, particularly for liquefied natural gas (LNG) and industrial gases, is the central force shaping the cold insulation market. This trend, combined with stringent energy efficiency regulations, is elevating performance requirements for insulation materials beyond simple thermal resistance.
Growth Catalysts
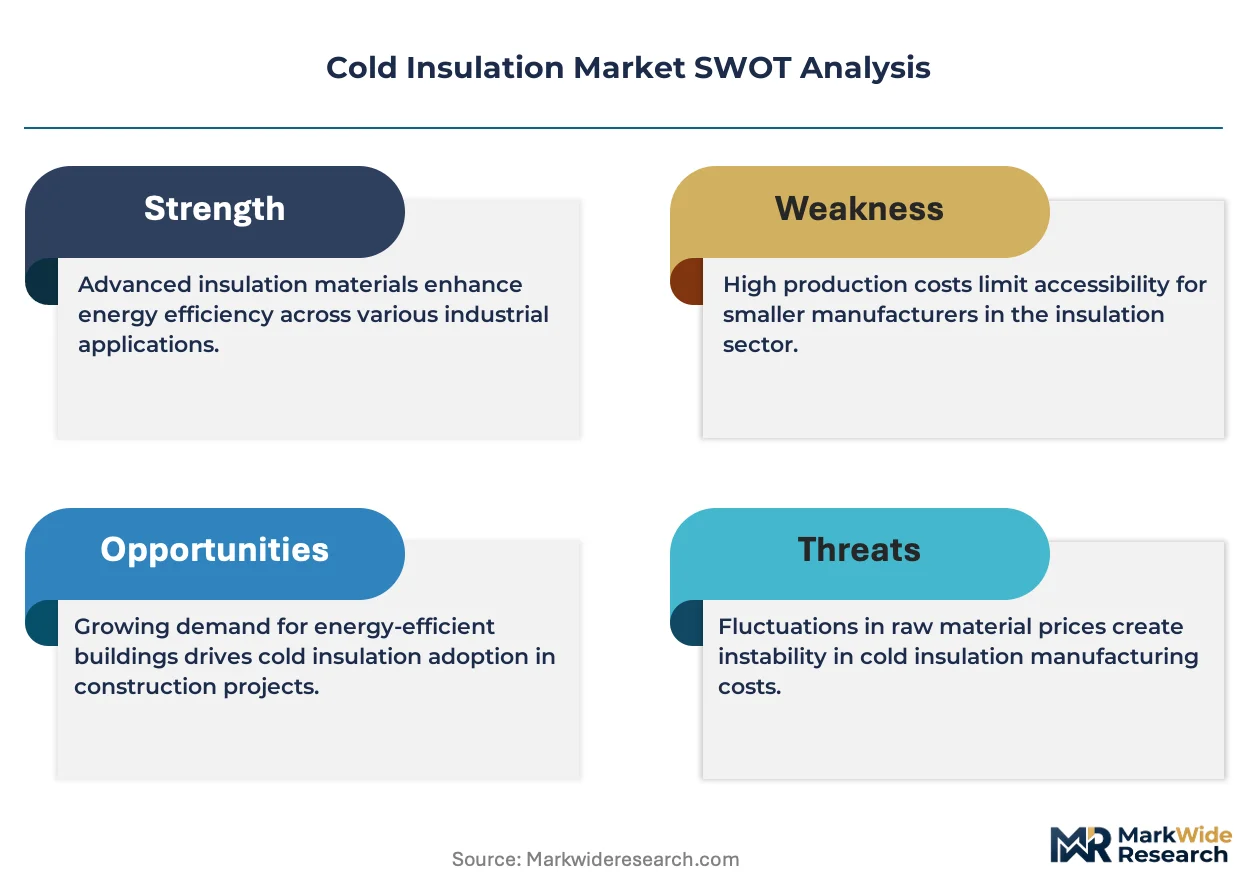
- Regulatory Mandates:The European Union's F-Gas Regulation compels upgrades to refrigeration systems, spurring demand for high-efficiency insulation to minimize energy consumption and meet compliance targets.
- Infrastructure Investment:China's massive investment in its national cold chain logistics network for food and biopharmaceuticals creates sustained, large-scale demand for insulation materials across storage and transport applications.
- Material Advancement:The commercialization of aerogel insulation provides a high-performance solution for cryogenic applications in aerospace and LNG shipping, where minimal thickness and weight are critical design parameters.
Market Restraints
- Input Cost Volatility:The price of polyurethane and polyisocyanurate foams is directly tied to petrochemical feedstock costs, whose fluctuations can compress manufacturer margins and create price instability for end-users.
- High Initial Outlay:Advanced insulation materials like aerogels and foam glass carry a significant price premium over traditional options, limiting their adoption to applications with stringent performance needs and less price sensitivity.
- Installation Complexity:Certain high-performance insulation systems require specialized labor and techniques for proper installation, increasing overall project costs and creating bottlenecks where skilled technicians are scarce.
Strategic Opportunities
- Emerging Market Build-Out:The nascent cold chain and food processing sectors in India and Southeast Asia represent significant greenfield opportunities for insulation suppliers as infrastructure development accelerates.
- Circular Economy Materials:Developing and marketing insulation products made from recycled or bio-based materials can capture demand from corporations focused on sustainability goals and circular economy principles.
- Building Retrofit Programs:Government incentives aimed at improving the energy efficiency of existing commercial and industrial buildings create a substantial market for retrofitting outdated or insufficient insulation systems.
Industry Challenges
- Skilled Labor Shortage:A deficit of installers trained to handle and apply next-generation insulation materials, especially in complex industrial and cryogenic environments, can delay project timelines and compromise system performance.
- Standardization Gaps:The lack of globally harmonized standards for testing the long-term performance and fire safety of new insulation materials creates compliance challenges for manufacturers operating across multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Insulation Market |
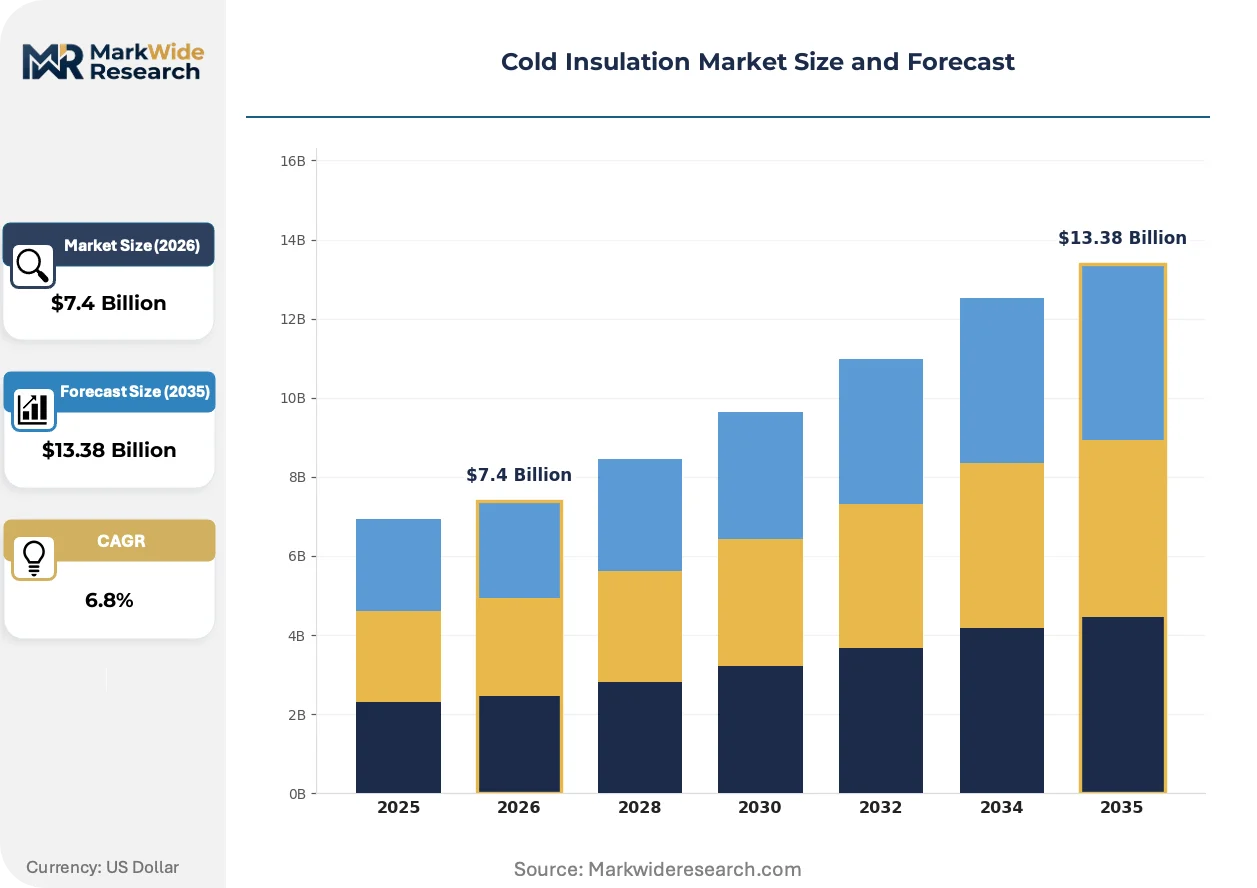
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
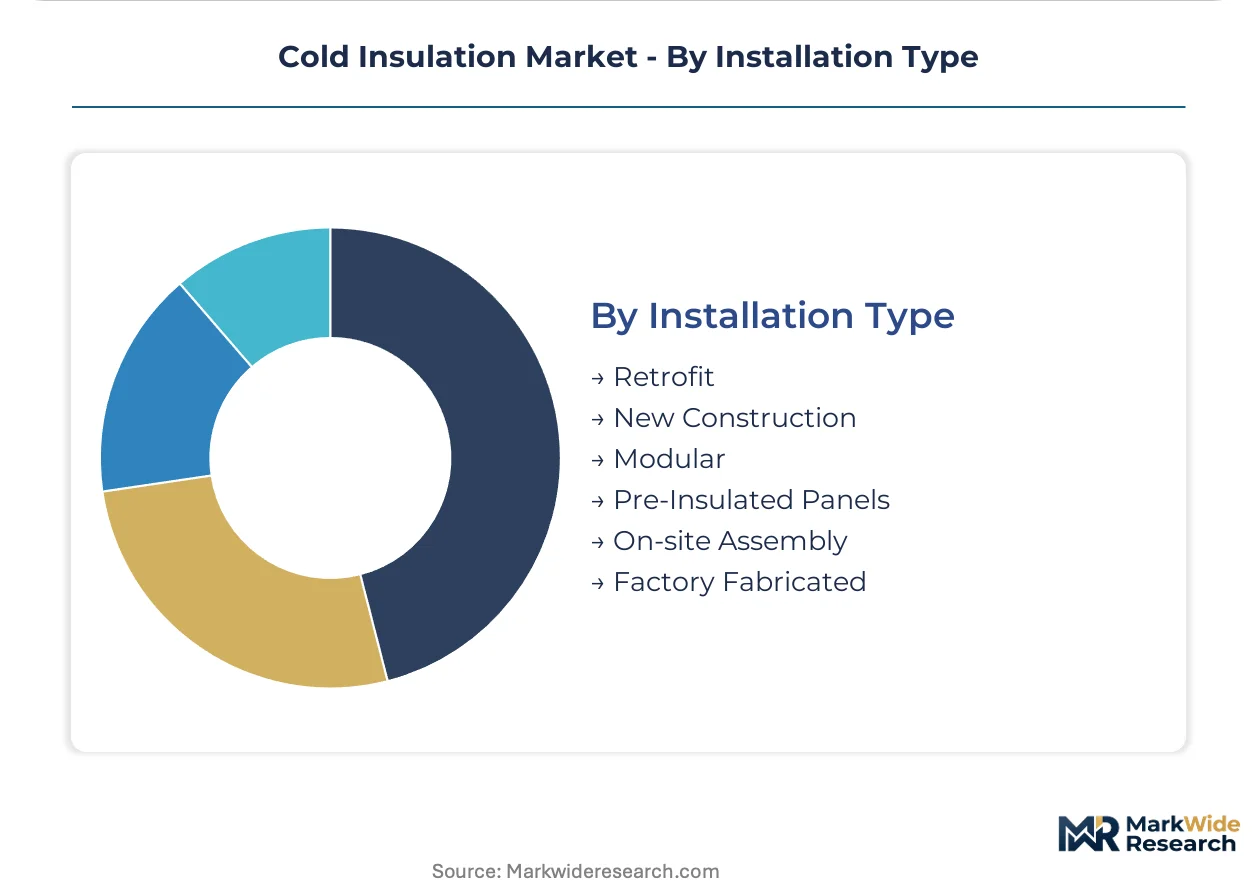
| Segmentation | Product Type: Foam Insulation, Vacuum Insulation Panels, Aerogel Insulation, Fiberglass Insulation, Polyisocyanurate, Cellulose Insulation Application: Refrigeration Units, Cryogenic Storage, HVAC Systems, Food Processing, Pharmaceutical Storage, Chemical Processing End User: Cold Chain Logistics, Food & Beverage Manufacturers, Pharmaceutical Companies, Industrial Manufacturers, Research Laboratories, Commercial Facilities Installation Type: Retrofit, New Construction, Modular, Pre-Insulated Panels, On-site Assembly, Factory Fabricated |
| Companies Covered | Owens Corning Corporation, Saint-Gobain, BASF SE, Rockwool International A/S, Aspen Aerogels, Johns Manville, Kingspan Group PLC, Huntsman International LLC, Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Insulation Market Strategic Shifts & Innovations
Material science is responding to the dual demands of enhanced thermal performance and improved lifecycle sustainability. Innovations focus on creating materials that not only meet stricter energy codes set by bodies like ASHRAE but also align with broader environmental and circular economy objectives.
Aerogel insulation, characterized by its extremely low thermal conductivity, offers superior thermal resistance within a minimal physical footprint. Adoption is accelerating in specialized cryogenic storage and high-value pharmaceutical logistics where space efficiency is a primary constraint. This technology is converging with embedded sensor networks, enabling real-time monitoring of thermal integrity and predictive maintenance alerts for critical systems.
Regulations like the EU's F-Gas Regulation and the US EPA's SNAP program are phasing out refrigerants with high global warming potential. This action indirectly forces upgrades of entire cooling systems, creating a clear inflection point for installing superior insulation to maximize the efficiency of newer, approved refrigerants. The LNG and chemical processing sectors are most impacted, quickening their shift toward materials like cellular glass and multi-layer composite insulation.
A notable shift in purchasing criteria is visible among sophisticated end-users, especially in the food and pharmaceutical sectors. Buyers are increasingly using total cost of ownership (TCO) models that prioritize long-term energy savings and risk mitigation over low initial installation costs. This trend favors suppliers who can substantiate performance claims with robust data and is most pronounced in Europe and North America.
Cold Insulation Market Segmentation
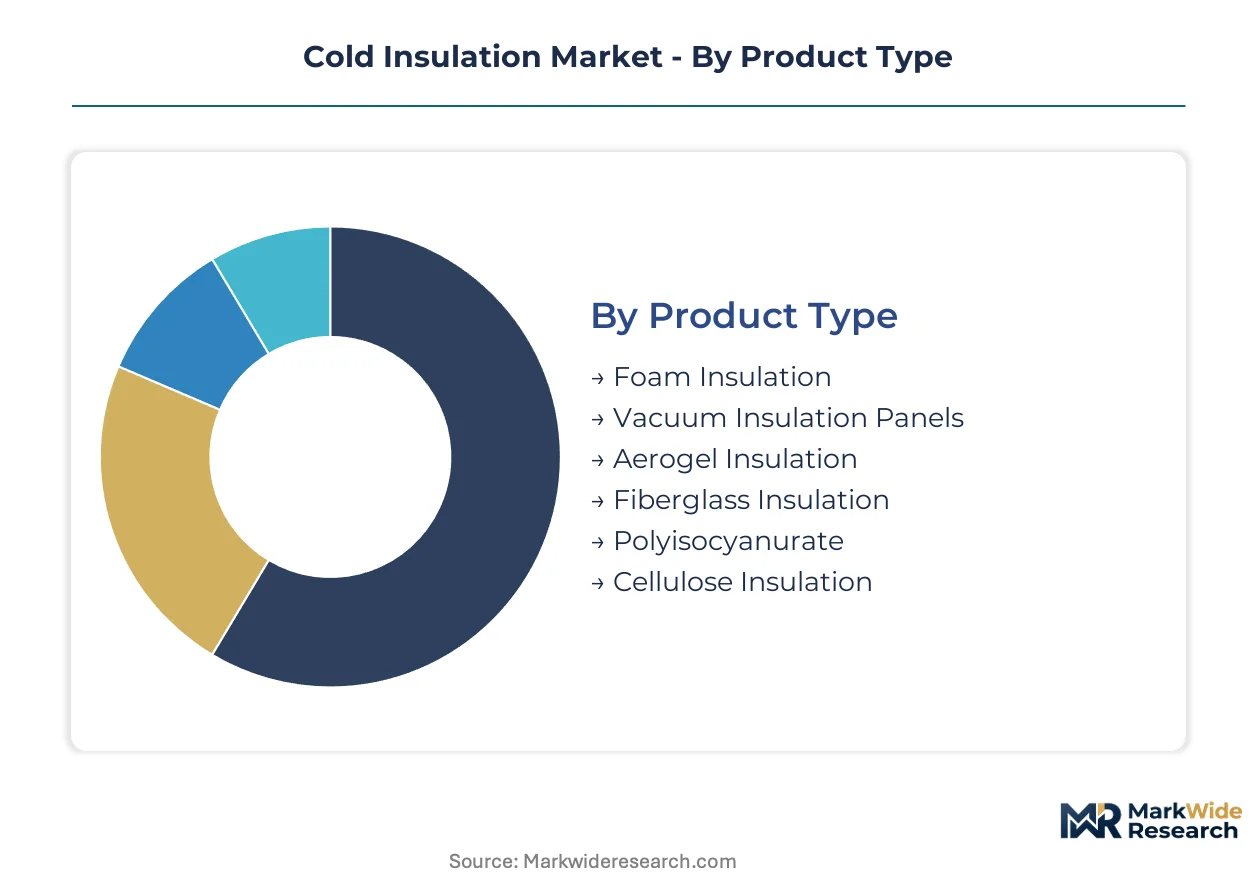
The cold insulation market is characterized by distinct segments reflecting specialized material requirements and diverse application environments. Understanding these categories helps pinpoint where innovation is critical and demand concentrates for specific thermal performance solutions.
Product Type:
Product segmentation highlights diverse material technologies employed to minimize heat gain in sub-ambient systems.
- Foam Insulation:This segment includes polyurethane and polyisocyanurate foams, widely used for cost-effectiveness and versatile thermal properties. Demand concentrates in HVAC and building applications in Europe.
- Aerogel Insulation:Extremely low thermal conductivity defines aerogel, offering superior thermal resistance in space-constrained environments. Adoption expands in cryogenic storage for LNG shipping.
- Vacuum Insulation Panels:These panels use a rigid, evacuated core material, providing exceptional thermal performance in thin profiles.
- Fiberglass Insulation:Composed of fine glass fibers, this material offers good thermal resistance and acoustic dampening for commercial facilities.
- Polyisocyanurate:Rigid foam insulation, polyisocyanurate provides high R-value and fire resistance, suitable for industrial roofing and wall systems.
- Cellulose Insulation:Made from recycled paper products, cellulose insulation offers an environmentally friendly option with good thermal performance.
Foam Insulation leads on scale; Aerogel Insulation leads on momentum.
Application:
Functional utility defines application categories, addressing distinct temperature control requirements across industrial and commercial settings.
- Cryogenic Storage:This application maintains extremely low temperatures for substances like LNG and industrial gases, requiring specialized insulation. Infrastructure investment in China drives demand.
- Food Processing:Insulation in food processing facilities ensures stable low temperatures, prevents spoilage, and meets hygiene standards. Demand is consistent across food manufacturing operations.
- Refrigeration Units:These units encompass commercial and industrial refrigerators, where efficient insulation minimizes energy consumption.
- HVAC Systems:Insulation within heating, ventilation, and air conditioning systems reduces energy loss and enhances efficiency in buildings.
- Pharmaceutical Storage:Maintaining precise temperature ranges for sensitive pharmaceuticals is critical, driving demand for high-performance insulation in storage and transport.
- Chemical Processing:Insulation in chemical plants manages process temperatures and prevents heat transfer in reactors and pipelines, ensuring operational safety.
Cryogenic Storage applications command significant capital investment, while Food Processing applications represent consistent, high-volume demand.
End User:
Customer operational needs delineate end-user segments, reflecting varying demands for temperature precision and regulatory compliance.
- Cold Chain Logistics:This segment includes transport, warehousing, and distribution networks for temperature-sensitive goods. China's expanding cold chain infrastructure creates large-scale demand.
- Pharmaceutical Companies:These companies require insulation for strict temperature controls during manufacturing, storage, and distribution, adhering to rigorous standards. High-performance insulation ensures product integrity.
- Food & Beverage Manufacturers:This sector utilizes cold insulation for processing, storage, and packaging perishable goods, focusing on hygiene and energy efficiency.
- Industrial Manufacturers:Industrial applications span various sectors requiring temperature control for processes, equipment, and storage.
- Research Laboratories:Laboratories use cold insulation for cryopreservation, sample storage, and controlling experimental conditions.
- Commercial Facilities:This segment includes supermarkets and restaurants relying on refrigeration and HVAC systems, where insulation reduces operational costs.
Cold Chain Logistics drives extensive material volumes, and Pharmaceutical Companies prioritize insulation for critical product integrity.
Installation Type:
Deployment methodology shapes installation type segments, covering both new infrastructure development and existing system upgrades.
- New Construction:This segment integrates cold insulation into newly built structures, like cold storage warehouses and processing plants. Infrastructure investment in emerging markets drives substantial demand.
- Retrofit:Retrofit projects upgrade existing insulation in older buildings and industrial facilities to improve energy efficiency and meet new regulatory standards. Government incentives create a substantial market.
- Modular:Modular insulation systems are prefabricated components designed for easy assembly and disassembly, offering flexibility and speed.
- Pre-Insulated Panels:These panels come with insulation pre-applied, streamlining construction and ensuring consistent thermal performance.
- On-site Assembly:This method involves installing insulation materials directly at the construction site, often for complex geometries or custom applications.
- Factory Fabricated:Insulation components manufactured off-site in a controlled environment ensure quality and precision, then transported for installation.
New Construction represents the fastest-growing trajectory, while Retrofit initiatives address a vast installed base with evolving efficiency needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks globally are creating a compliance cost differential, influencing the geographic distribution of insulation manufacturing and application. This dynamic drives investment in regions with supportive policies and strong industrial demand. Infrastructure development in emerging economies further shapes regional market trajectories.
China
China's extensive investments in cold chain logistics and chemical processing infrastructure significantly drive demand for cold insulation materials. The country's dual carbon goals promote energy-efficient solutions across industrial and commercial sectors. Major industrial hubs like the Yangtze River Delta are seeing substantial deployment of advanced insulation in new cold storage facilities.
United States
Demand for cold insulation in the United States stems from its large pharmaceutical and food processing industries, alongside a robust LNG export infrastructure. The EPA's SNAP program and ASHRAE standards indirectly encourage higher-performance insulation for improved energy efficiency. Gulf Coast states, particularly around Houston, are key centers for cryogenic insulation applications in energy terminals.
Germany
Germany's strong industrial base and stringent energy efficiency regulations, such as the EU's F-Gas Regulation, compel the adoption of advanced cold insulation. The country's focus on sustainable building practices also promotes innovative material use in HVAC and industrial refrigeration. The Ruhr region, with its dense industrial clusters, represents a core market for high-performance insulation systems.
India
India presents significant greenfield opportunities due to its nascent but rapidly expanding cold chain logistics and food processing sectors. Government initiatives, including the PLI scheme, aim to boost domestic manufacturing and infrastructure development, thereby increasing insulation demand. Major metropolitan areas like Mumbai and Delhi are experiencing a surge in cold storage construction.
Japan
Japan's demand for cold insulation is characterized by high-precision industrial applications and a strong focus on material quality and longevity. Strict JIS standards and continuous innovation in areas like pharmaceutical storage and advanced manufacturing drive material specifications. The Kanto region, including Tokyo, remains a central point for specialized cold insulation projects in technology and biopharma.
Cold Insulation Market Key Industry Players
Established producers occupy the standard tier, focusing on traditional foam and fiberglass solutions, while emerging entrants pursue niche applications in high-performance materials. The market exhibits a tiered structure, with a few large players holding significant market share and numerous specialized firms serving specific industrial needs. Strategic archetypes include diversified material manufacturers and application-specific solution providers. Capacity expansion and strategic partnerships are dominant competitive moves.
Diversified material manufacturers like Owens Corning Corporation and Saint-Gobain exemplify a broad portfolio approach, serving multiple end-use sectors with a range of insulation products. BASF SE, with its advanced chemical formulation expertise, anchors the market for specialized foam products used in refrigeration and cryogenic applications. These companies leverage their extensive research and development capabilities to meet evolving performance requirements and regulatory standards across global markets.
| Leading Market Players |
|---|
| Owens Corning Corporation |
| Saint-Gobain |
| BASF SE |
| Rockwool International A/S |
| Aspen Aerogels |
| Johns Manville |
| Kingspan Group PLC |
| Huntsman International LLC |
| Cabot Corporation |
| Others |
Cost & Logistics Intelligence
The European Union's F-Gas Regulation gates both qualified supply and premium-tier pricing access for advanced cold insulation materials. This mandate drives investment in energy-efficient solutions and influences material selection across the market.
Pricing Analysis
Distributor margins for specialized cold insulation solutions vary based on project complexity and material performance. Project-based pricing is common for large industrial installations, while per-unit transactional models serve commercial HVAC applications. Price differentiation hinges on certification levels, such as ASHRAE compliance, and material performance tier. Cost compression in foam insulation intensifies due to petrochemical feedstock volatility, with pharmaceutical companies exhibiting the least price sensitivity.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke pattern characterize the downstream movement of cold insulation materials. Supply concentration for key inputs is notable in China for chemical derivatives and Europe for advanced foam production. The supply chain relies on petrochemical feedstocks and specialized silica for aerogels. Commodity price volatility poses a structural risk, while direct sales to large industrial projects define the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold insulation market presents a margin-expansion story, driven by stringent energy efficiency regulations mandating higher-performance, premium-tier materials.
For Market Incumbents: Lock in long-term supply agreements with key feedstock providers to mitigate input cost volatility. Expand R&D into bio-based and recyclable insulation materials to meet circular economy objectives and counter emerging sustainable alternatives. Invest in advanced certification for high-performance products, strengthening market position against specialized entrants. Enhance channel control in growing regions like India and Southeast Asia to capture new infrastructure development.
For New Entrants and Emerging Players: Online B2B marketplaces and direct-to-project digital platforms offer a penetration route for specialized insulation providers. Target the under-served retrofit market in commercial and industrial buildings, where outdated systems offer significant efficiency gains. Focus on modular insulation systems for rapid deployment in emerging cold chain logistics infrastructure. Leverage performance-based selling models, emphasizing total cost of ownership over initial outlay in less price-sensitive segments.
For Investors and Strategic Acquirers: Roll-up economics work for specialized insulation solution providers because the market remains fragmented across niche applications and geographies. Identify mid-cap firms with proprietary material technologies or strong regional installation capabilities as prime acquisition targets. Long-term viability is secured by global energy efficiency mandates and sustained infrastructure investment in cryogenic and cold chain sectors. A signal to watch is the increasing adoption rate of aerogel insulation in high-value pharmaceutical logistics.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Meets the growing demand from China's expanding cold chain and chemical processing infrastructure. |
| Green Manufacturing Transition | Aligns production processes with circular economy principles, appealing to sustainability-focused buyers. |
| Long-term Supply Agreement | Secures critical feedstock supply, mitigating price volatility for polyurethane and polyisocyanurate foams. |
| Joint Venture with Logistics Firms | Integrates high-performance insulation solutions directly into emerging cold chain networks. |
| Product Launch: Bio-based Foams | Introduces sustainable alternatives, capturing demand from environmentally conscious end-users. |
Research Approach
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core for this cold insulation market analysis. This approach combines primary interviews with industry stakeholders, including plant managers, procurement leads, and R&D directors, with secondary validation. Secondary data draws from customs and trade statistics, industry association reports, and company financial filings. Triangulation across these sources ensures robust data integrity.
An input-output matrix frames the forecast framework across the projection horizon. Segmentation dimensions modeled include product type, application, end-user, installation type, and regional regulatory compliance. Compound annual growth rates derive from historical growth trends, market drivers, and expert consensus. Key forecast inputs include global LNG infrastructure investment and the impact of the EU F-Gas Regulation.
The model assumes a particular technology adoption path; alternative pathways for aerogel and vacuum insulation panels would alter the outlook. Forecasts reflect documented assumptions, but geopolitical shifts affecting energy prices or unforeseen regulatory changes present risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Commercial Kitchen Ventilation System Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Aeration System Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
Gas Wall Hung Boilers Market