
 US Chalk Reel and Line Market | 2026-2036
US Chalk Reel and Line Market Size, Share, and Industry Trends Forecast 2026-2036
US Chalk Reel and Line Market Intelligence
Market Context
Residential construction is consolidating its share of chalk reel and line demand as single-family housing permits rebound across the southern United States. Stanley Black & Decker leverages its dealer network and multi-brand portfolio to dominate big-box hardware channels. Milwaukee Tool anchors its position through battery-integrated marking systems that reduce manual rewind labor. Keson Industries specializes in long-tape and reel combinations favored by concrete framers.
Product Definition and Segment Structure
US chalk reels and lines are handheld layout instruments that deposit powdered chalk—traditionally calcium carbonate or gypsum-based—onto braided nylon or cotton cords to transfer straight reference lines across substrates. Electric chalk reels now incorporate motorized rewind mechanisms and dust-collection ports to meet respirable silica limits. Manual chalk reels retain the largest volume share due to sub-twenty-dollar price points and replacement-driven demand, while electric variants capture expanding margin pools among professional contractors. The construction end-user segment leads absolute consumption, though DIY enthusiasts represent the fastest-growing channel as home improvement retailers push private-label starter kits.
Regulatory Environment and Outlook
OSHA enforces permissible exposure limits for respirable crystalline silica that directly shape chalk formulation and dust containment design requirements. The EPA oversees volatile organic compound rules affecting spray-line marking alternatives, while CPSC maintains mechanical safety standards for spring-loaded rewind mechanisms. State-level contractor licensing boards in California and Florida increasingly mandate tool calibration documentation for commercial layout work. Stakeholders must monitor whether federal silica enforcement tightens sufficiently to accelerate electric reel displacement of manual tools.
Market Dynamics
OSHA's respirable crystalline silica enforcement is compressing manual chalk reel viability while electric dust-collection systems capture professional contractor preference across commercial jobsites.
Growth Catalysts
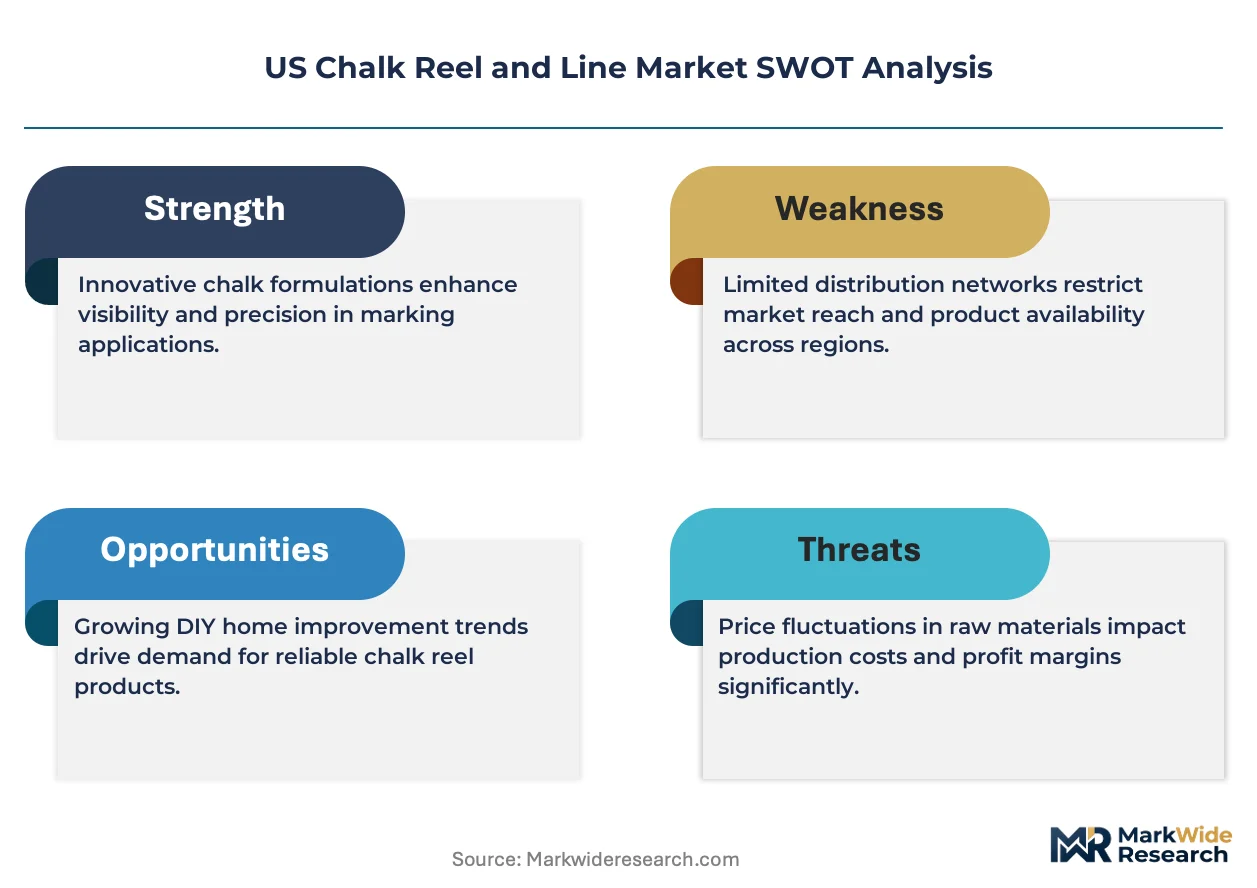
- Single-family housing permits:Sun Belt residential construction accelerates layout tool replacement cycles as framing crews scale operations across Texas and Florida.
- OSHA silica compliance:Tightened permissible exposure limits force contractors toward electric reels with integrated dust containment and HEPA filtration.
- Battery platform convergence:Cordless marking tools leveraging existing lithium-ion ecosystems reduce incremental capital burden for trade professionals.
Market Restraints
- Nylon braided line input volatility:Petrochemical feedstock fluctuations compress margin stability for domestic reel manufacturers.
- Big-box retail concentration:Home Depot and Lowe's channel dominance limits pricing autonomy for specialty tool brands.
- Spray-line marking substitution:Aerosol chalk alternatives threaten cord-based systems in interior finishing applications where dust sensitivity peaks.
Strategic Opportunities
- California contractor calibration mandates:State-level documentation requirements create premium positioning for precision-graded electric reels with certification trails.
- DIY private-label starter kits:Home improvement retailers seek exclusive entry-level bundles targeting first-time homebuyers in suburban expansion zones.
- Bluetooth-enabled layout systems:Convergence of digital measurement and physical marking opens specification channels among commercial general contractors.
Industry Challenges
- Silica compliance documentation:Field crews lack training on exposure monitoring protocols, slowing electric reel deployment despite regulatory deadlines.
- Legacy manual tool inventory:Contractor reluctance to retire functional equipment extends replacement cycles and fragments fleet standardization.
Report Scope
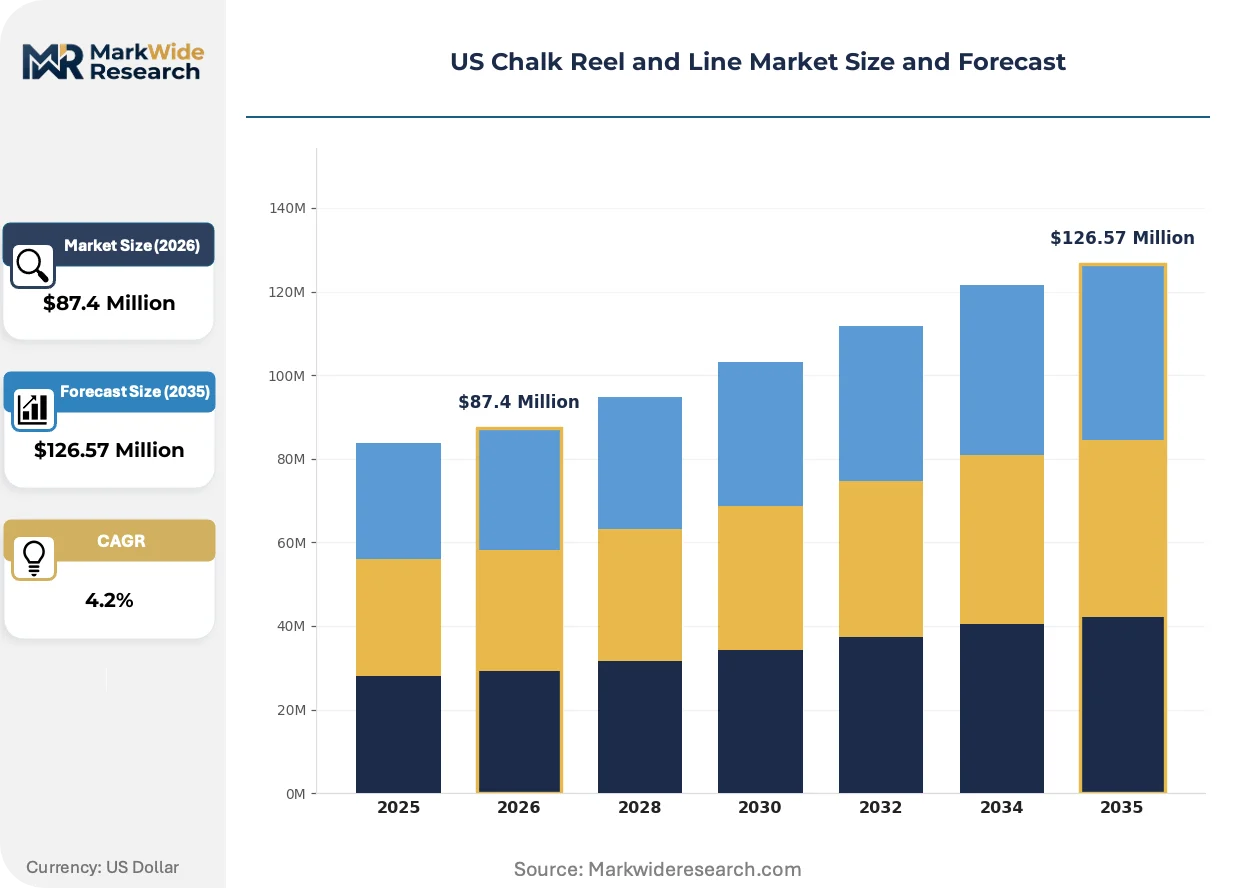
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Chalk Reel and Line Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $126.57 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Chalk Reels, Electric Chalk Reels, Line Marking Tools, Specialty Reels End User: Construction, Landscaping, DIY Enthusiasts, Industrial Distribution Channel: Online Retail, Hardware Stores, Specialty Shops, Wholesale Application: Marking Straight Lines, Surveying, Indoor Layouts, Outdoor Projects |
| Companies Covered | Stanley Black & Decker, Tajima Tool Corporation, Apex Tool Group, DeWalt, Keson Industries, Milwaukee Tool, IRWIN Tools, OX Group International, SNA Europe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Chalk Reel and Line Market Strategic Shifts & Innovations
Motorized rewind mechanisms and connected measurement platforms are fragmenting the traditional hand-tool category into precision equipment segments with distinct service and certification requirements.
Battery-integrated chalk reels are decentralizing jobsite power dependencies as Milwaukee Tool and DeWalt platform ecosystems extend into layout instrumentation. Commercial framing contractors in Texas and Florida adopt these systems fastest, eliminating generator tethering and reducing trip hazards. The technology is decentralizing equipment procurement decisions from central fleet managers to individual lead carpenters with platform loyalty.
OSHA's updated silica permissible exposure limit tightens respirable dust thresholds, compelling manufacturers to redesign chalk formulations and add vacuum port interfaces. Electric reel producers now engineer sealed gearboxes and external dust extraction as standard features rather than premium upgrades. California and Florida commercial contractors face the steepest compliance curves, accelerating specification of certified low-dust systems in municipal and state-funded projects.
Procurement consolidation among national homebuilders shifts purchasing authority from regional subcontractors to corporate equipment desks with standardized vendor lists. Lennar, D.R. Horton, and PulteGroup now negotiate fleet pricing directly with Stanley Black & Decker and Milwaukee Tool, bypassing traditional distributor markup. This concentration is most advanced in Arizona and Nevada markets where production homebuilding dominates residential construction volume.
US Chalk Reel and Line Market Segmentation
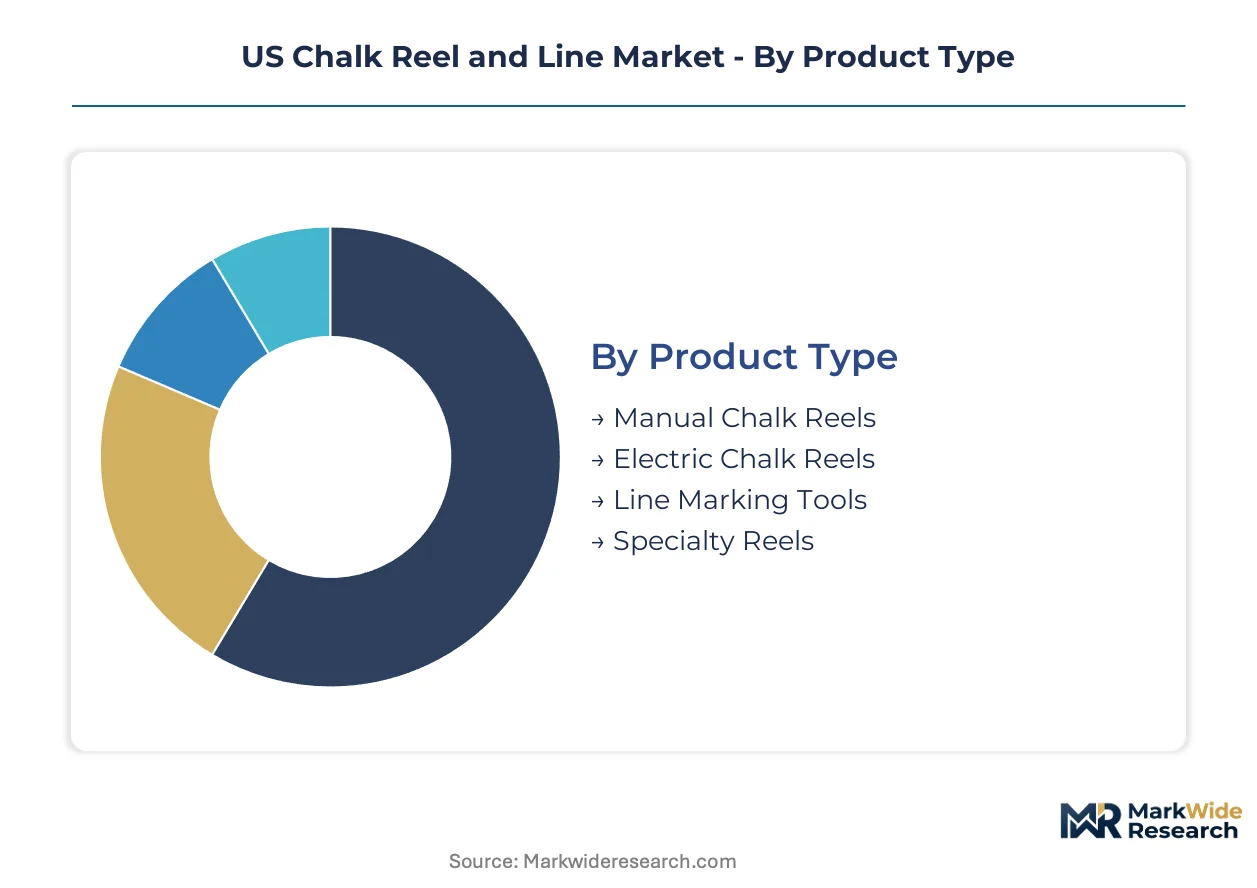
Chalk reel and line segmentation reveals how tool selection tracks contractor scale, regulatory exposure, and jobsite power infrastructure. Understanding these divides exposes where electric displacement threatens manual incumbent positions and where battery platform loyalty reshapes procurement authority.
Product Type:
Cost tier separates weekend renovators from commercial crews facing silica enforcement deadlines and fleet standardization mandates.
- Manual Chalk Reels:Spring-loaded aluminum or plastic housings with braided nylon line and refillable chalk chambers dominate replacement-driven demand. Sub-twenty-dollar price points sustain volume leadership across Texas and Florida residential framing where crew turnover accelerates tool attrition.
- Electric Chalk Reels:Motorized rewind mechanisms with integrated dust-collection ports and HEPA filtration address OSHA respirable crystalline silica limits. California and Florida commercial contractors specify these systems for municipal projects requiring exposure documentation.
- Line Marking Tools:Spray-line aerosol alternatives threaten cord-based systems in interior finishing where dust sensitivity peaks.
- Specialty Reels:Long-tape combinations and precision-graded instruments serve concrete framers and surveyors requiring certification trails.
Manual chalk reels lead volumes today; electric variants are gaining share fastest.
End User:
Application scale and compliance liability determine whether buyers prioritize price accessibility or dust containment certification.
- Construction:Commercial framing crews and residential contractors drive absolute consumption across Sun Belt housing starts. OSHA silica rules and fall protection standards tighten jobsite compliance requirements for layout instrumentation.
- DIY Enthusiasts:First-time homebuyers in suburban expansion zones fuel fastest expansion as home improvement retailers push private-label starter kits through big-box channels.
- Landscaping:Outdoor layout for hardscaping and irrigation relies on weather-resistant braided line and gypsum-based formulations.
- Industrial:Manufacturing facility maintenance and warehouse marking require durable housings and standardized fleet procurement.
Construction anchors absolute demand; DIY enthusiasts show steepest expansion trajectory.
Distribution Channel:
Channel concentration shapes pricing autonomy and brand access for specialty manufacturers competing against dominant retail gatekeepers.
- Hardware Stores:Home Depot and Lowe's channel dominance limits pricing autonomy for specialty tool brands while pushing private-label alternatives.
- Online Retail:Direct-to-contractor platforms bypass distributor markup and enable specification of certified low-dust systems for silica compliance.
- Specialty Shops:Professional trade distributors serve concrete framers and surveyors requiring precision-graded reels with calibration documentation.
- Wholesale:Fleet pricing negotiations between national homebuilders and major manufacturers consolidate procurement authority at corporate equipment desks.
Hardware stores capture the largest transaction volume; online retail is climbing the fastest.
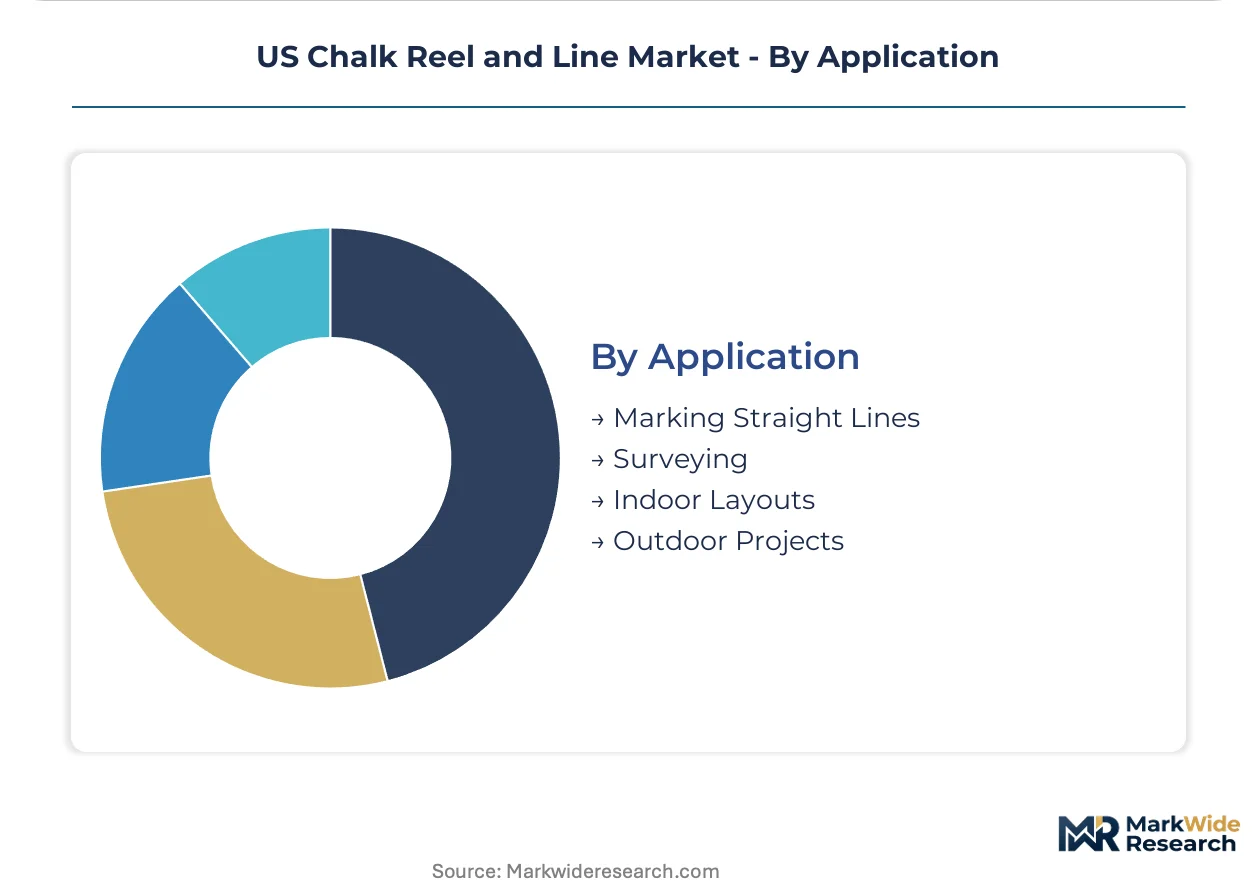
Application:
Jobsite environment dictates dust sensitivity, line durability requirements, and power infrastructure availability.
- Marking Straight Lines:Foundation layout and framing alignment represent core functional demand across all buyer tiers.
- Outdoor Projects:Exposure to moisture and UV degradation drives specification of weather-resistant nylon braided line in Texas and Florida commercial build activity.
- Indoor Layouts:Dust sensitivity and respirable silica exposure accelerate electric reel displacement with vacuum port integration.
- Surveying:Precision measurement convergence with physical marking opens specification channels for Bluetooth-enabled layout systems among commercial general contractors.
Marking straight lines dominates functional demand; indoor layouts are expanding most quickly due to silica compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production and procurement decisions across the US chalk reel and line market respond to divergent state-level enforcement of OSHA silica rules, creating compliance-cost arbitrage that favors electric reel adoption in high-regulation jurisdictions while manual tools persist where enforcement lags.
Texas
Housing starts in Dallas-Fort Worth and Houston metro areas drive framing crew expansion and accelerated tool replacement cycles. State-level contractor licensing remains less prescriptive on silica documentation than coastal counterparts, sustaining manual reel volumes among residential builders. The Permian Basin commercial build-out concentrates demand for weather-resistant braided line systems in outdoor infrastructure applications.
Florida
Miami-Dade and Tampa Bay municipal projects now mandate exposure documentation for layout tools, compelling commercial contractors toward certified low-dust electric systems. Hurricane-resistant construction codes drive specification of durable housings in coastal counties. State-funded infrastructure spending in Orlando and Jacksonville accelerates fleet standardization among regional subcontractors.
California
Cal/OSHA maintains the nation's most stringent respirable crystalline silica enforcement, forcing displacement of manual reels across Los Angeles and Bay Area commercial jobsites. Contractor licensing boards in Sacramento and San Diego increasingly require tool calibration documentation, creating premium positioning for precision-graded electric reels. Bay Area tech campus construction specifies Bluetooth-enabled layout systems for digital-measurement convergence.
Southeast
Atlanta and Charlotte residential production homebuilding consolidates procurement authority at corporate equipment desks, bypassing traditional distributor channels. North Carolina and Georgia state OSHA plans mirror federal silica limits but with slower field enforcement, fragmenting electric reel penetration rates. Regional specialty distributors in Nashville serve concrete framers requiring long-tape reel combinations.
Southwest
Phoenix and Las Vegas production homebuilding dominance accelerates fleet pricing negotiations between national builders and major manufacturers. Arizona's state-plan OSHA enforcement lags California's, preserving price-sensitive manual tool demand among smaller residential crews. Nevada commercial casino and hospitality construction in Reno specifies dust-containment systems for interior finishing phases.
US Chalk Reel and Line Market Key Industry Players
Portfolio diversification dominates the current landscape as established tool manufacturers extend battery platform ecosystems into layout instrumentation. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with multi-brand distribution networks, power tool specialists leveraging cordless platform loyalty, and precision instrument makers serving calibration-dependent commercial segments. M&A activity and strategic partnerships with home improvement retailers constitute the primary competitive vectors reshaping channel access.
Among diversified industrial conglomerates, Stanley Black & Decker anchors the big-box hardware channel through dealer network density and private-label production capacity. Milwaukee Tool exemplifies the power tool specialist archetype, converting existing lithium-ion platform loyalty into specification of battery-integrated marking systems. Keson Industries occupies a position within the precision instrument tier, serving concrete framers and surveyors requiring certified calibration trails for municipal project compliance.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Tajima Tool Corporation |
| Apex Tool Group |
| DeWalt |
| Keson Industries |
| Milwaukee Tool |
| IRWIN Tools |
| OX Group International |
| SNA Europe |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility cascades through braided nylon line costs into three distinct pricing tiers that separate weekend DIY purchasers from silica-compliant commercial contractors facing OSHA enforcement deadlines.
Pricing Analysis
Distributor margin compression at Home Depot and Lowe's channels squeezes specialty brands while rewarding private-label producers with captive volume commitments. Three-tier pricing structure across premium electric dust-collection systems, standard manual reels, and economy disposable units reflects certification grade and after-sales service bundling. Pricing pressure stems from spray-line aerosol substitution in interior finishing segments. DIY enthusiasts exhibit highest price sensitivity, while municipal contractors in California and Florida accept premium positioning for exposure documentation compliance.
Supply Chain Analysis
Container freight rate fluctuations from Chinese manufacturing hubs to Long Beach and Savannah ports amplify landed cost variability for aluminum housings and precision motors. China, Taiwan, and Vietnam anchor braided nylon line production, while domestic injection molding serves plastic housing demand. Raw material dependencies span petrochemical derivatives for line braiding, aluminum extrusions for housings, and lithium-ion cells for electric variants. Single-source vulnerability concentrates in precision motor suppliers for dust-collection systems. Distribution runs through big-box retail consolidation, direct-to-contractor platforms, and specialty trade distributors serving calibration-dependent segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US chalk reel and line market functions as a stable compounder anchored by irreplaceable layout functionality across construction trades and regulatory-driven replacement cycles for silica compliance.
For Market Incumbents: Deepen battery platform ecosystem integration to lock in contractor fleet standardization and raise switching costs against emerging connectivity-enabled competitors. Accelerate certification investment for Cal/OSHA precision-graded reels to capture municipal project specifications. Secure exclusive private-label production agreements with national homebuilders consolidating procurement authority at corporate equipment desks. For New Entrants and Emerging Players: Bluetooth-enabled layout convergence offers a technology-first wedge into Bay Area commercial general contractors specifying digital-measurement integration. Target underpenetrated concrete framing segments in Nashville and Atlanta requiring long-tape reel combinations with calibration trails. Pursue direct-to-contractor online channels bypassing Home Depot and Lowe's gatekeeper concentration. For Investors and Strategic Acquirers: Asymmetric upside sits with precision instrument specialists possessing certified calibration infrastructure and municipal project relationships. Long-term viability rests on regulatory enforcement trajectories rather than cyclical construction activity. Monitor Cal/OSHA silica documentation mandate expansion as the primary inflection signal for electric reel displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Extension | Leverages existing Milwaukee and DeWalt lithium-ion ecosystems to reduce contractor incremental capital burden. |
| Silica Compliance Certification | Captures California and Florida municipal project specifications requiring exposure documentation trails. |
| Private-Label Production Partnership | Secures volume commitments from Lennar and D.R. Horton bypassing traditional distributor markup layers. |
| Bluetooth-Enabled Layout Integration | Opens specification channels among Bay Area tech campus commercial general contractors. |
| Direct-to-Contractor Channel Buildout | Bypasses Home Depot and Lowe's channel dominance for specialty low-dust system distribution. |
Research Approach
Direct dialogue with framing crew supervisors, commercial general contractor equipment managers, home improvement retailer category buyers, and specialty trade distributors grounded qualitative insights in field-level procurement behavior. Secondary validation drew from OSHA enforcement databases, EPA volatile organic compound rulemakings, Census Bureau housing permit statistics, and SEC filings of diversified tool manufacturers. Bottom-up demand modeling triangulated against top-down construction spending allocations.
Segment-level projections across manual and electric product types, construction and DIY end-user channels, and hardware store versus online retail distribution incorporated housing start trajectories, silica compliance enforcement intensity, and battery platform adoption curves. CAGRs derived from regression analysis of historical replacement cycles and regulatory displacement patterns. Inputs included Sun Belt permit velocity, Cal/OSHA inspection frequency trends, and lithium-ion platform penetration rates among professional trades.
The model holds under steady OSHA enforcement intensity and continued single-family housing recovery; deviation in federal silica rule relaxation or mortgage rate spikes would shift replacement cycle assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Theodolite Market
Tools
Grinding Machines Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
Structural Wood Screws Market
Tools
Machining Centers Market
Tools
Turning Tools Market
Tools
Metal Cutting Machine Market
Tools
Electric Power Tools Market
Tools
Jade Engraving Machines Market
Tools
Global Scarifiers Market
Tools
Global Cordless Power Tools Market
Tools
Drill Presses Market
Tools
Drain Cleaning Equipment Market
Tools
Foam Cutting Machine Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Gouging Torch Market