
 Austria Prefabricated Houses Market | 2026-2036
Austria Prefabricated Houses Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Prefabricated Houses Market Insights
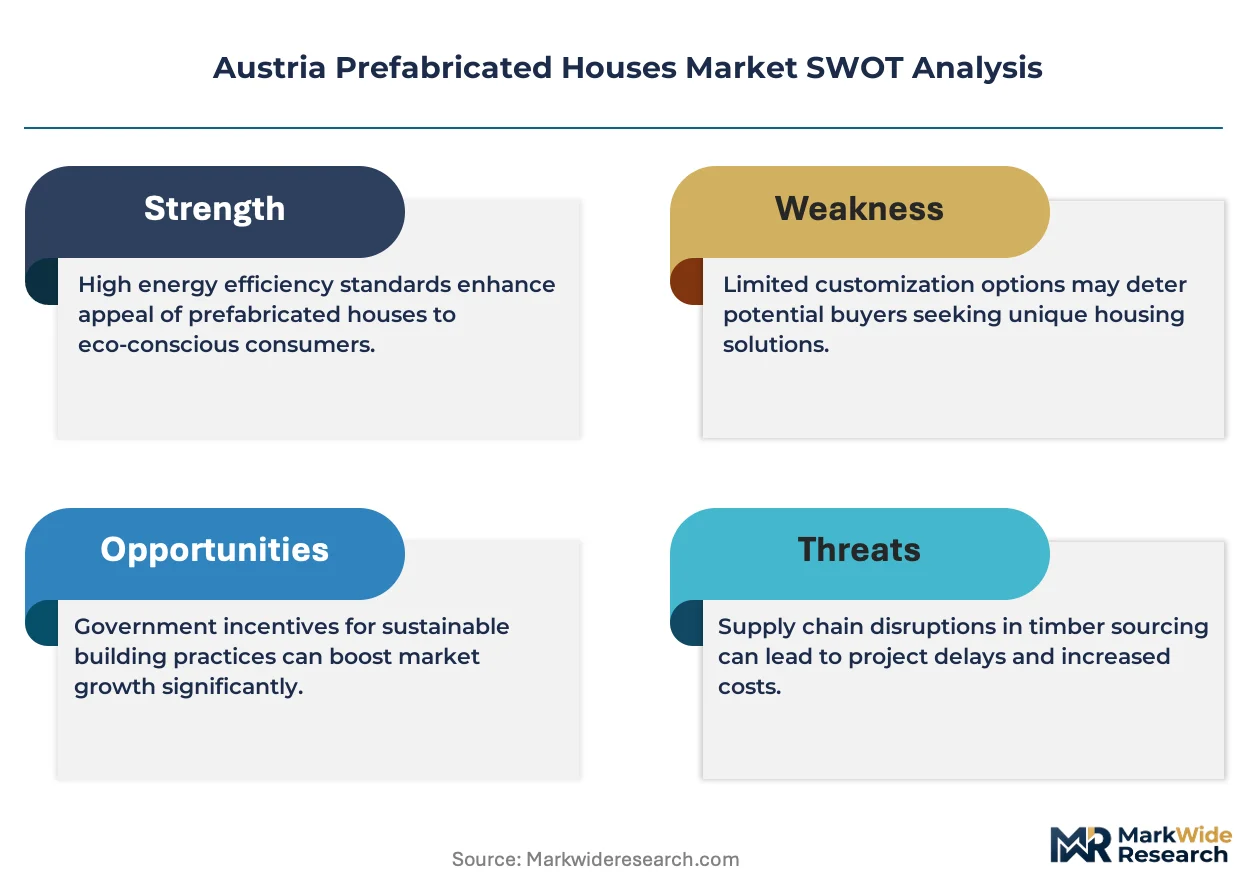
Energy-performance subscription packages is realigning how Austrian prefabricated housing firms monetize long-term customer relationships. ELK Fertighaus GmbH leverages its timber engineering heritage to dominate high-efficiency rural deployments. Wolf Systembau Gesellschaft m.b.H. anchors industrial-scale output through automated panel production near Linz. Variohaus differentiates via architect-customizable platforms that sustain premium positioning in urban infill projects.
Prefabricated houses in Austria are factory-built dwellings assembled from pre-manufactured modules or panels, typically achieving U-values below 0.15 W/m²K through precision-cut timber frames and integrated insulation systems, designed to compress construction schedules from months to weeks. Modular homes lead volume as developers in Graz and Klagenfurt prioritize repeatable apartment blocks with standardized floor plans. Panelized homes capture margin pools where buyers demand customized façade materials and room configurations without sacrificing factory quality control. Energy-efficient builds within the construction method dimension are accelerating fastest as Austria's Klimafonds subsidies reward nearly-zero-energy prefabricated units.
Austria's national building code, administered through regional Bauämter and harmonized with EU Energy Performance of Buildings Directive standards, mandates escalating efficiency thresholds that factory builders can verify more consistently than site-built competitors. The ÖNORM B 8110 series and EU Construction Products Regulation together shape material certification pathways, compelling prefabricators to maintain accredited testing protocols for structural timber and insulation assemblies. Stakeholders must monitor whether upcoming federal Klimageld disbursements tilt procurement toward all-electric heating packages in factory-built housing or preserve hybrid system flexibility.
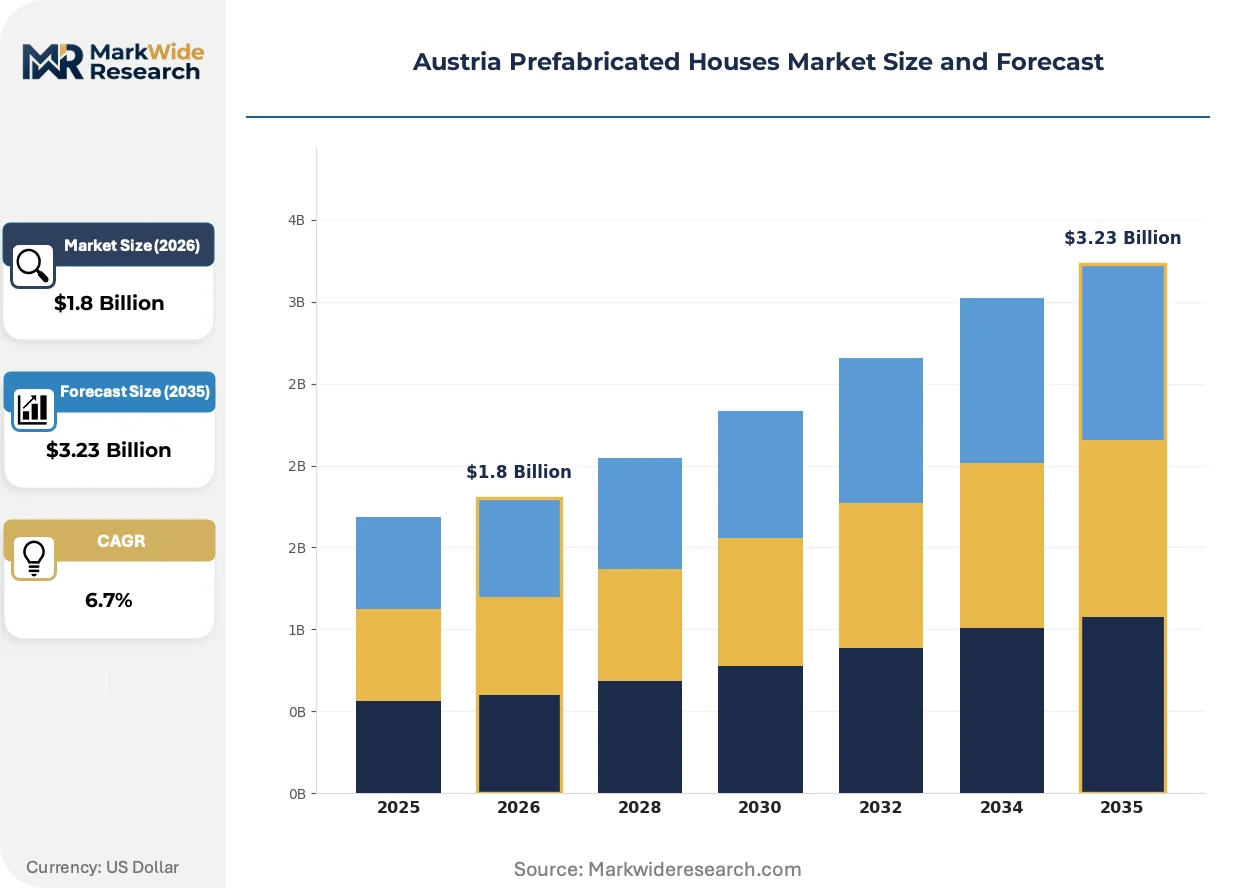
Market Dynamics
Austria's ÖNORM B 8110 thermal envelope standards are compressing construction timelines and forcing factory builders to outpace site-built competitors on energy verification consistency. The regulatory ratchet is concentrating procurement power among prefabricators with accredited testing protocols.
Growth Catalysts
- Klimafonds subsidy acceleration:Federal disbursements for nearly-zero-energy units are pulling first-time buyers toward modular platforms in Vienna and Salzburg.
- Timber-frame cluster density:Decades of specialized manufacturing concentration in Tyrol and Lower Austria is shortening supplier lead times for precision-cut structural assemblies.
- EU Energy Performance of Buildings Directive harmonization:Escalating efficiency thresholds favor factory builders who can document U-values below 0.15 W/m²K through controlled production environments.
Market Restraints
- Cross-laminated timber supply concentration:Austrian producers depend on a narrow base of Central European glulam suppliers exposed to spruce bark beetle damage cycles.
- Site access constraints in Alpine terrain:Transport of oversized modules to Tyrolean valley locations requires specialized flatbed fleets with limited seasonal availability.
- ÖNORM certification timeline friction:Extended approval windows for novel insulation assemblies delay product launches by 8-14 months versus conventional builds.
Strategic Opportunities
- Energy-performance subscription models:Long-term service contracts bundling heating optimization and envelope monitoring are opening recurring revenue streams beyond unit sales.
- Urban infill architect customization:Variohaus-style configurable platforms address Salzburg and Graz density pressures where standardization conflicts with heritage district aesthetics.
- Klimageld all-electric pivot:Pending federal disbursement rules may tilt procurement toward heat-pump-only packages, rewarding prefabricators with integrated HVAC engineering.
Industry Challenges
- Building physics specialist scarcity:Factory engineering departments struggle to recruit thermal bridge calculation experts certified for Passive House-level detailing.
- Legacy Bauamt inspection protocols:Regional building authorities in rural states lack streamlined pathways for factory quality documentation, forcing redundant site checks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Prefabricated Houses Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Pre-Cut Homes, Manufactured Homes Material: Wood, Steel, Concrete, Composite Materials Construction Method: On-Site Assembly, Off-Site Construction, Hybrid Construction, Energy-Efficient Builds Market Segment: Residential, Commercial, Institutional, Vacation Homes |
| Companies Covered | Kieninger Gesellschaft, Wolf Systembau Gesellschaft m.b.H., Swietelsky AG, Palmatin, Schmid Hochbau GmbH, ELK Fertighaus GmbH, Georg Fessl GmbH, Variohaus, Wimberger Holding GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Prefabricated Houses Market Trends and Innovations
Digital fabrication and performance-based contracting are converging to redefine how Austrian factory builders capture value across the building lifecycle. The sector is pivoting from product sales to outcome guarantees.
Cross-laminated timber with integrated mineral wool channels is overtaking traditional stud-and-cavity construction in rural deployments. Graz-based developers specify these panels for repeatable apartment blocks where thermal bridging must hit Passive House thresholds. The technology is overtaking conventional timber-frame methods by compressing on-site assembly from weeks to days while eliminating air-leakage variability.
ÖNORM B 8110-6 thermal bridge assessment protocols now mandate blower-door testing documentation for all factory-built dwellings above 150 square meters. The regulation forces prefabricators to maintain in-house pressure-test chambers rather than outsourcing verification. Rural builders in Vorarlberg are responding fastest, integrating infrared thermography into final quality checks before module dispatch.
First-time buyers in Vienna are unbundling architect services from manufacturer design teams, bringing independent studios to specify façade materials and room configurations. This procurement pattern disrupts the traditional turnkey model where factory designers controlled all specifications. The shift is most visible in urban infill projects where heritage district requirements demand non-standard exterior treatments.
Austria Prefabricated Houses Market Segmentation
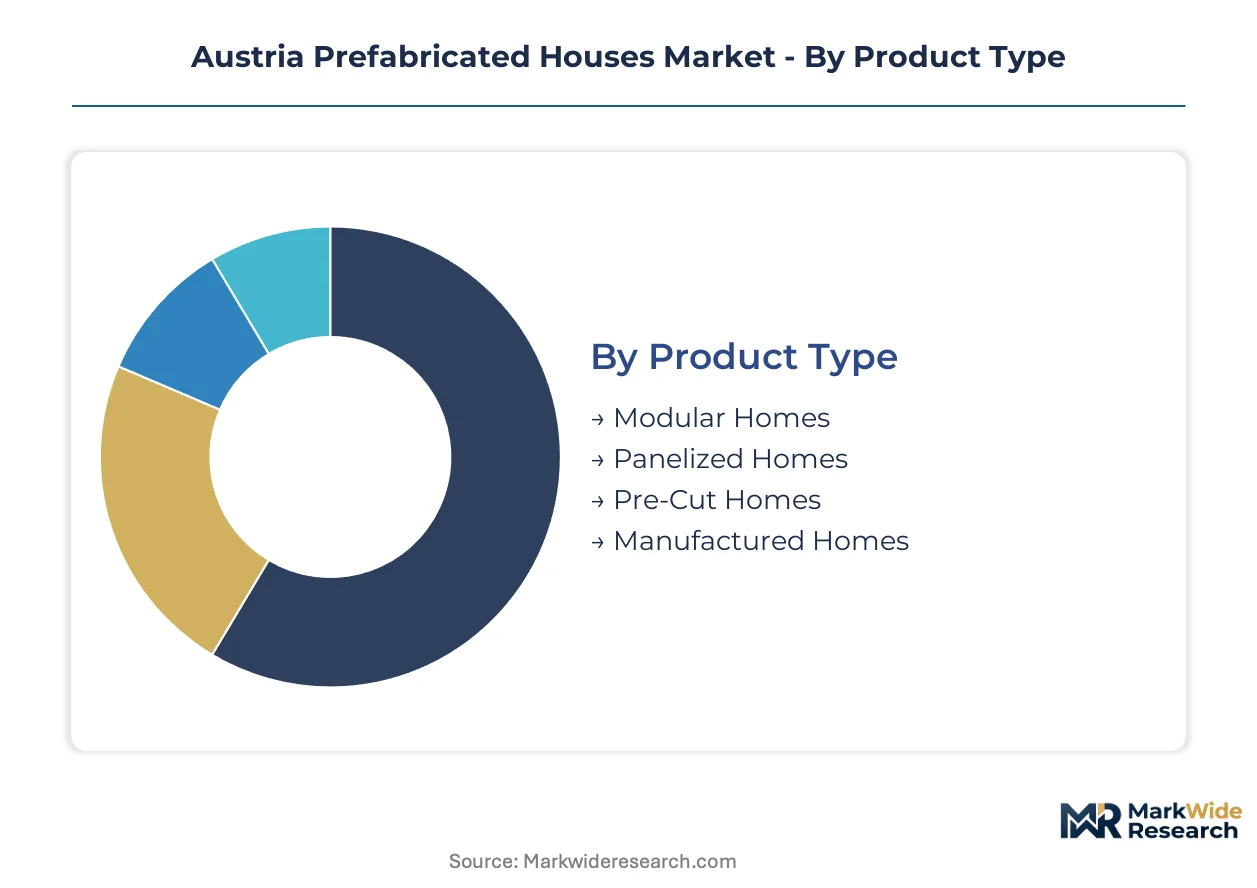
Austrian prefabricators align production configurations with distinct buyer risk profiles and thermal performance thresholds. Each segment category reflects divergent procurement priorities across Vienna's urban infill corridors and Tyrol's rural valley developments.
Product Type:
Buyers differentiate primarily by speed-to-occupancy requirements versus customization latitude.
- Modular Homes:Three-dimensional volumetric units factory-finished with MEP systems pre-installed, craned into position for immediate weather-tight closure. Graz and Klagenfurt developers prioritize these for repeatable apartment blocks where standardized floor plans compress permitting cycles.
- Panelized Homes:Two-dimensional wall and roof assemblies shipped flat for on-site erection, enabling buyer-specified façade materials and room configurations. Demand concentrates in Salzburg heritage districts where ÖNORM thermal verification must coexist with aesthetic flexibility.
- Pre-Cut Homes:Precision-cut timber components delivered as numbered kits for traditional carpentry assembly. Alpine self-builders in Vorarlberg favor these for cost control on sloped sites.
- Manufactured Homes:Transportable dwelling units built to mobile construction standards, limited to seasonal or temporary applications under Austrian Bauamt protocols.
Modular homes lead volumes today; panelized homes are gaining share fastest.
Material:
Structural material selection maps directly to regional forestry access and thermal bridge engineering capacity.
- Wood:Cross-laminated timber and glulam frames dominate Tyrol and Lower Austria deployments, leveraging decades of specialized manufacturing concentration. Spruce and fir supply chains from Central European forests feed precision-cut structural assemblies hitting U-values below 0.15 W/m²K.
- Steel:Light-gauge metal framing penetrates urban infill projects where fire-rated party walls are mandatory and timber spans are constrained.
- Concrete:Precast concrete panels anchor mixed-use commercial-residential stacks in Vienna's peripheral districts, though weight limits module transport radius.
- Composite Materials:Fiber-reinforced polymers and insulated metal panels serve specialized applications requiring extreme durability or chemical resistance.
Wood retains dominant share; steel is expanding most quickly in urban density zones.
Construction Method:
Factory involvement depth determines quality consistency and schedule predictability.
- Off-Site Construction:Complete building envelope fabrication in climate-controlled halls, minimizing moisture exposure and enabling year-round production. Wolf Systembau's automated panel production near Linz exemplifies this approach for industrial-scale output.
- Energy-Efficient Builds:Nearly-zero-energy prefabricated units qualifying for Klimafonds subsidies, with integrated heat pump and ventilation engineering. First-time buyers in Vienna and Salzburg accelerate procurement here.
- Hybrid Construction:Factory-produced structural shells completed with site-applied finishes, balancing speed with local trade employment requirements.
- On-Site Assembly:Traditional stick-built methods using prefabricated components, residual share concentrated in remote Alpine locations beyond module transport corridors.
Off-site construction anchors volume; energy-efficient builds show steepest expansion trajectory.
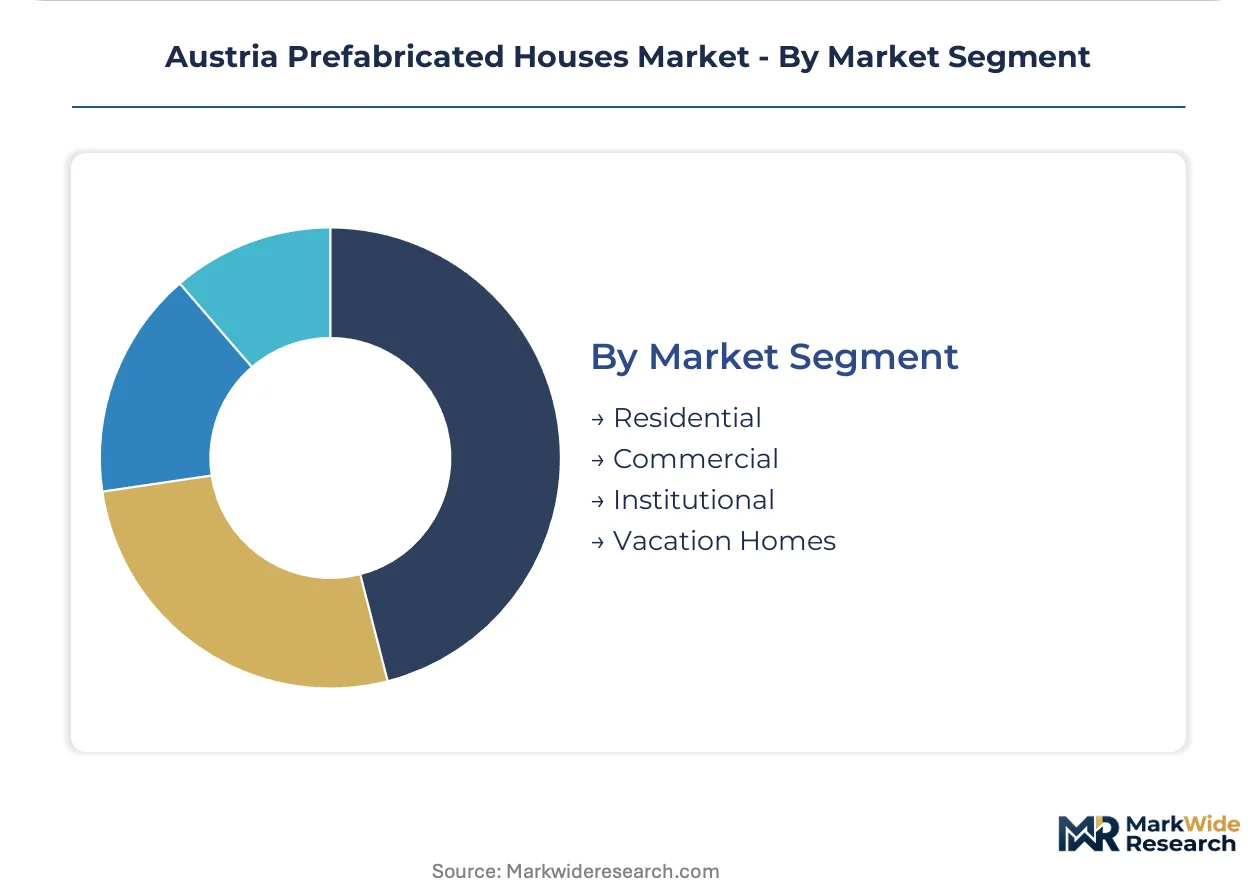
Market Segment:
End-use applications diverge sharply in financing structures and regulatory oversight intensity.
- Residential:Single-family and multi-family dwellings for owner-occupiers and rental investors, absorbing the majority of Tyrol and Lower Austria timber-frame output. ELK Fertighaus dominates rural deployments here.
- Vacation Homes:Secondary dwellings in Alpine lake districts and ski access corridors, where seasonal occupancy patterns relax year-round thermal performance requirements.
- Commercial:Retail and office modules for rapid deployment in peripheral business parks, constrained by stricter Bauamt fire safety protocols.
- Institutional:Schools, healthcare clinics, and emergency housing procured through federal and state tender processes with extended certification timelines.
Residential commands volume leadership; vacation homes climb fastest on leisure property investment trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's prefabricated housing sector operates at roughly triple Austria's scale, yet Vienna's first-time buyer density creates comparable per-capita modular adoption rates. Both markets converge on timber-frame engineering excellence, though regulatory divergence in subsidy structures produces distinct procurement patterns.
Germany
Bavaria and Baden-Württemberg anchor continental Europe's densest prefabrication cluster, where KfW development bank subsidies for nearly-zero-energy buildings pull developers toward factory-built solutions. The country's national building energy ordinance (GEG) mandates stepped efficiency thresholds that factory builders verify more reliably than site-built competitors. Industrial concentration around Stuttgart and Munich shortens supplier lead times for cross-laminated timber assemblies.
Switzerland
Alpine terrain constraints and stringent Minergie certification requirements concentrate demand in panelized systems that balance thermal performance with transport logistics. The Swiss Federal Office of Energy's building program subsidizes envelope upgrades that prefabricators deliver through precision-cut timber frames. Zurich and Geneva metropolitan areas drive volume as land scarcity accelerates urban infill deployments.
Italy
Northern regions of Lombardy and Trentino-Alto Adige leverage proximity to Austrian timber clusters while serving distinct Mediterranean thermal comfort requirements. The country's superbonus 110% tax incentive for energy-efficient renovations temporarily distorted procurement toward deep retrofit panels rather than new modular construction. Verona and Bolzano host emerging manufacturing concentrations targeting cross-border Alpine markets.
Czech Republic
Prague's construction cost inflation and EU cohesion fund accessibility create favorable conditions for modular apartment block developers. The national building act harmonization with EU energy performance directives favors factory builders capable of documenting U-value compliance through controlled production environments. Industrial zones near Brno and Ostrava attract Austrian prefabricators seeking labor cost arbitrage.
Austria Prefabricated Houses Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with turnkey providers dominating rural single-family deployments while architect-collaborative platforms capture urban infill premiums. The vendor base concentrates around three strategic archetypes: timber-engineering heritage houses leveraging decades of regional forestry relationships, automated panel producers optimizing throughput through capital-intensive fabrication halls, and customizable platform operators sacrificing scale for design flexibility. Consolidation pressure intensifies as Klimafonds subsidy eligibility requirements favor prefabricators with accredited testing protocols and in-house blower-door verification capacity.
Among Austria-based specialists, Wolf Systembau Gesellschaft m.b.H. and ELK Fertighaus GmbH occupy positions within the industrial-scale fabrication tier, while Variohaus exemplifies the architect-customizable platform archetype. These incorporated entities anchor distinct competitive vectors—automated output versus design flexibility—without overlapping segment targeting. The limited liability structure prevalent across the peer set reflects capital requirements for climate-controlled production halls and pressure-test chamber investments mandated by updated ÖNORM thermal verification protocols.
| Leading Market Players |
|---|
| Kieninger Gesellschaft |
| Wolf Systembau Gesellschaft m.b.H. |
| Swietelsky AG |
| Palmatin |
| Schmid Hochbau GmbH |
| ELK Fertighaus GmbH |
| Georg Fessl GmbH |
| Variohaus |
| Wimberger Holding GmbH |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between Klimafonds-eligible nearly-zero-energy units and conventional thermal envelopes manifests in both factory gate pricing and procurement network configurations across Tyrol and Lower Austria. Premium-tier builders command pricing power through captive blower-door verification chambers while commodity assemblers absorb margin compression from cross-laminated timber supply volatility.
Pricing Analysis
Capacity additions in Lower Austria are reshaping price floors for standardized modular platforms serving Graz and Klagenfurt developers. Three-tier pricing structure across premium, standard, and economy levels stratifies by ÖNORM B 8110-6 thermal bridge certification depth and integrated HVAC engineering sophistication. Cost compression in economy-tier panelized systems is intensifying because spruce bark beetle damage cycles have tightened glulam feedstock availability. First-time buyers in Vienna exhibit highest price sensitivity, while Alpine vacation home investors in Vorarlberg absorb premium positioning for heritage-compliant façade customization.
Supply Chain Analysis
Workforce availability constraints in Tyrolean valley manufacturing zones are forcing prefabricators to automate precision-cut timber operations or relocate panel production to Linz industrial corridors. Geographic supply concentration centers on Austria, Germany, and Czech Republic for cross-laminated timber and mineral wool insulation assemblies. Raw material dependencies rest on Central European spruce forests, glulam adhesive formulations, and heat pump compressor units from German suppliers. Single-source vulnerability in specialized flatbed transport fleets for Alpine module delivery creates bottleneck exposure during winter road closure periods. Distribution runs through regional Bauamt-approved dealer networks with direct-to-developer procurement emerging in Vienna urban infill corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Austria prefabricated houses market reads as a late-cycle quality story where first-time buyer migration toward nearly-zero-energy specifications rewards factory builders with accredited thermal verification infrastructure.
For Market Incumbents: Deepen in-house production of cross-laminated timber assemblies to offset glulam supplier concentration risk exposed to spruce bark beetle damage cycles. Expand automated panel capacity near Linz to capture industrial-scale procurement from Graz and Klagenfurt apartment block developers. Defensive positioning requires preemptive investment in blower-door verification chambers before ÖNORM B 8110-6 mandates tighten further. For New Entrants and Emerging Players: Urban infill architects unbundled from manufacturer design teams represent the most penetrable buyer archetype for configurable platform specialists. White-space targets include Salzburg heritage district projects requiring non-standard façade treatments and Vienna rental investors seeking repeatable multi-family modules with Klimafonds subsidy optimization. Go-to-market execution should anchor on independent studio partnerships rather than turnkey dealer networks. For Investors and Strategic Acquirers: Consolidation pressure builds where Klimafonds eligibility requirements favor prefabricators with accredited testing protocols and in-house thermal verification capacity. Long-term viability over the next decade hinges on factory builders' ability to pivot from product sales toward energy-performance subscription bundling. Acquisition target archetypes include timber-engineering heritage houses with dormant regional forestry relationships and underutilized climate-controlled production halls. Watch Klimageld disbursement rules on all-electric heating packages as the signal for portfolio rebalancing toward integrated HVAC engineering capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Energy-Performance Subscription Launch | Transforms ELK Fertighaus and Wolf Systembau from unit sellers to lifetime service providers with recurring revenue streams. |
| Automated Panel Production Scale-Up | Wolf Systembau's Linz facility expansion compresses lead times for Graz developers chasing Klimafonds subsidy windows. |
| Architect-Configurable Platform Investment | Variohaus-style customization engines capture Salzburg heritage district premiums where standardization conflicts with aesthetic mandates. |
| Cross-Laminated Timber Backward Integration | Captive glulam production insulates margins from Central European spruce supply volatility driven by bark beetle damage cycles. |
| Blower-Door Verification Chamber Certification | ÖNORM B 8110-6 compliance creates regulatory moat excluding smaller assemblers lacking capital for pressure-test infrastructure. |
Research Methodology
Coverage spans Austria, Germany, Switzerland, and Czech Republic, with primary inputs from each market informing cross-border timber cluster dynamics. Factory engineering directors, regional Bauamt inspection officers, Klimafonds program administrators, and thermal bridge calculation specialists provided structured interviews on certification timelines and subsidy disbursement patterns. Secondary validation drew from ÖNORM B 8110 series documentation, EU Energy Performance of Buildings Directive harmonization texts, federal Klimageld regulatory drafts, and timber trade association production statistics. Bottom-up module shipment tallies from Tyrol and Lower Austria manufacturing zones were triangulated against top-down construction permit data from Vienna and Salzburg municipal authorities.
Rate-of-change decomposition across the projection horizon isolates volume drivers by construction method, material selection, and end-use segment. Modeled dimensions include product type differentiation between modular, panelized, and pre-cut platforms; material stratification across timber, steel, and concrete structural systems; and construction method depth from off-site fabrication through hybrid assembly. CAGRs were derived from segmented growth rate aggregation weighted by current volume shares. Industry-specific forecast inputs incorporate Klimafonds subsidy renewal trajectories and spruce forest inventory recovery projections from Austrian federal forestry inventories.
Underlying measurement precision varies by segment; energy-efficient builds carry tighter precision than vacation home applications due to standardized Klimafonds eligibility documentation. Forecasts reflect assumptions on federal subsidy continuity, EU directive harmonization timelines, and cross-laminated timber supply stabilization. Material deviation in Klimageld disbursement rules, bark beetle infestation severity, or Bauamt inspection protocol streamlining warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Europe Manufactured Homes Market
Residential Construction
North America Residential Construction Market
Residential Construction
Europe Residential Construction Market
Residential Construction
US Residential Remodeling Market
Residential Construction
US Residential Construction Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
Germany Residential Construction Market
Residential Construction
UK Residential Construction Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Asia-Pacific Prefabricated Housing Market