
 Excavating Contractor Market | 2026-2036
Excavating Contractor Market Size, Share, and Industry Trends Forecast 2026-2036
Excavating Contractor Market Insights
Municipal infrastructure buyers is collapsing into private development-led demand as federal infrastructure funding channels through state-level contractors. Kiewit Corporation leverages its vertical integration across heavy civil and excavation scopes to capture multi-year transportation contracts. Mastec Inc. specializes in utility-scale excavation tied to renewable energy interconnection and broadband deployment. Beaver Excavating Co anchors its position in Ohio and surrounding Midwest markets through long-standing relationships with regional construction companies.
An excavating contractor provides earthmoving, trenching, grading, and site preparation services using hydraulic and mechanical excavation equipment with operating weights ranging from compact mini units below six metric tons to crawler-mounted systems exceeding forty metric tons, primarily enabling foundation construction, utility installation, and land modification for built environment projects. Commercial excavation and site preparation command the largest revenue pools given their attachment to non-residential building and civil engineering cycles, while utility installation applications are expanding fastest as underground fiber, electrical substation, and water main replacement programs intensify. Hydraulic excavator technology dominates fleet composition due to versatility across digging depths and material densities, though mini excavator deployment is rising in urban infill and restricted-access job sites.
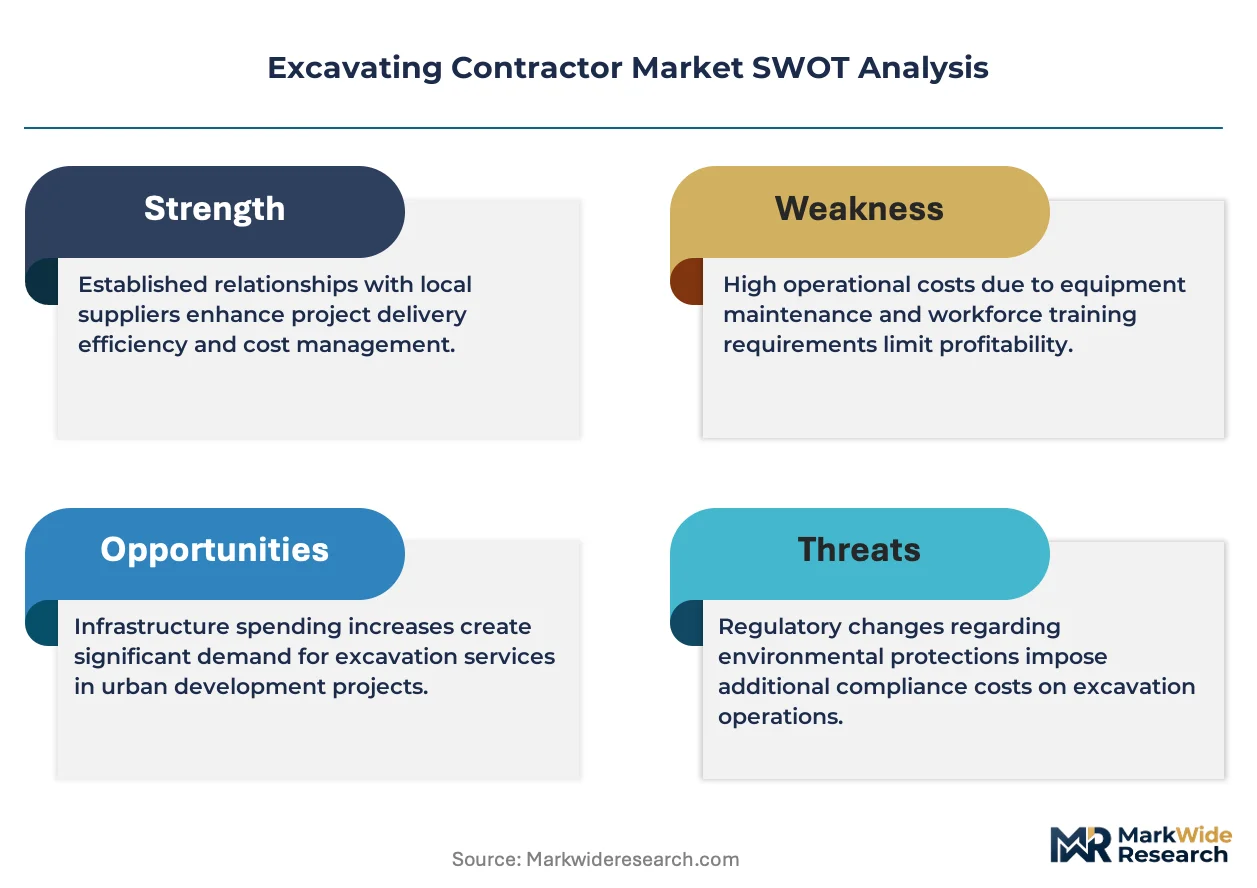
OSHA excavation standards mandate protective systems for trenches exceeding five feet in depth, directly shaping contractor equipment investment and training protocols. EPA National Pollutant Discharge Elimination System permits govern sediment and runoff control from disturbed sites, filtering market access toward contractors with certified stormwater pollution prevention plans. State departments of transportation layer their own prequalification requirements onto federal compliance frameworks, creating regional variance in contractor eligibility. Stakeholders must monitor how pending silica exposure rulemakings and diesel emissions regulations reshape equipment replacement timelines and labor cost structures.
Market Dynamics
Federal infrastructure funding dispersion through state DOT prequalification systems is restructuring contractor eligibility hierarchies, concentrating project access among operators with certified stormwater pollution prevention plans and multi-state compliance capabilities.
Growth Catalysts
- OSHA excavation standards:Trench protective system mandates for depths exceeding five feet drive equipment upgrade cycles and specialized training investments among established contractors.
- Underground utility replacement programs:Water main, fiber optic, and electrical substation interconnection projects accelerate demand for precision trenching and horizontal directional drilling capabilities.
- Texas-California-Florida demand concentration:Urban densification and utility upgrade intensity in these three states generates sustained backlog visibility for regional operators.
Market Restraints
- Diesel equipment replacement timelines:Pending EPA Tier 4 Final and emerging zero-emission mandates compress fleet turnover economics for mid-sized contractors.
- Skilled operator scarcity:Certified heavy equipment operator pipelines cannot match retirement rates in Midwest and Northeast markets.
- Silica exposure compliance costs:OSHA respirable crystalline silica rulemakings impose dust suppression system investments and respiratory protection program overhead.
Strategic Opportunities
- Renewable energy interconnection:Utility-scale solar and wind farm excavation contracts offer multi-year visibility with fewer municipal procurement cycles.
- Mini excavator urban deployment:Restricted-access job sites and infill development patterns favor compact hydraulic units below six metric tons.
- Broadband deployment mandates:Federal BEAD program funding channels through state contractors requiring last-mile trenching and conduit installation expertise.
Industry Challenges
- Stormwater permit certification timelines:EPA NPDES compliance documentation delays project mobilization for contractors without pre-approved pollution prevention plans.
- Equipment financing access:Rising interest rate environments compress capital availability for fleet expansion among sub-regional operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Excavating Contractor Market |
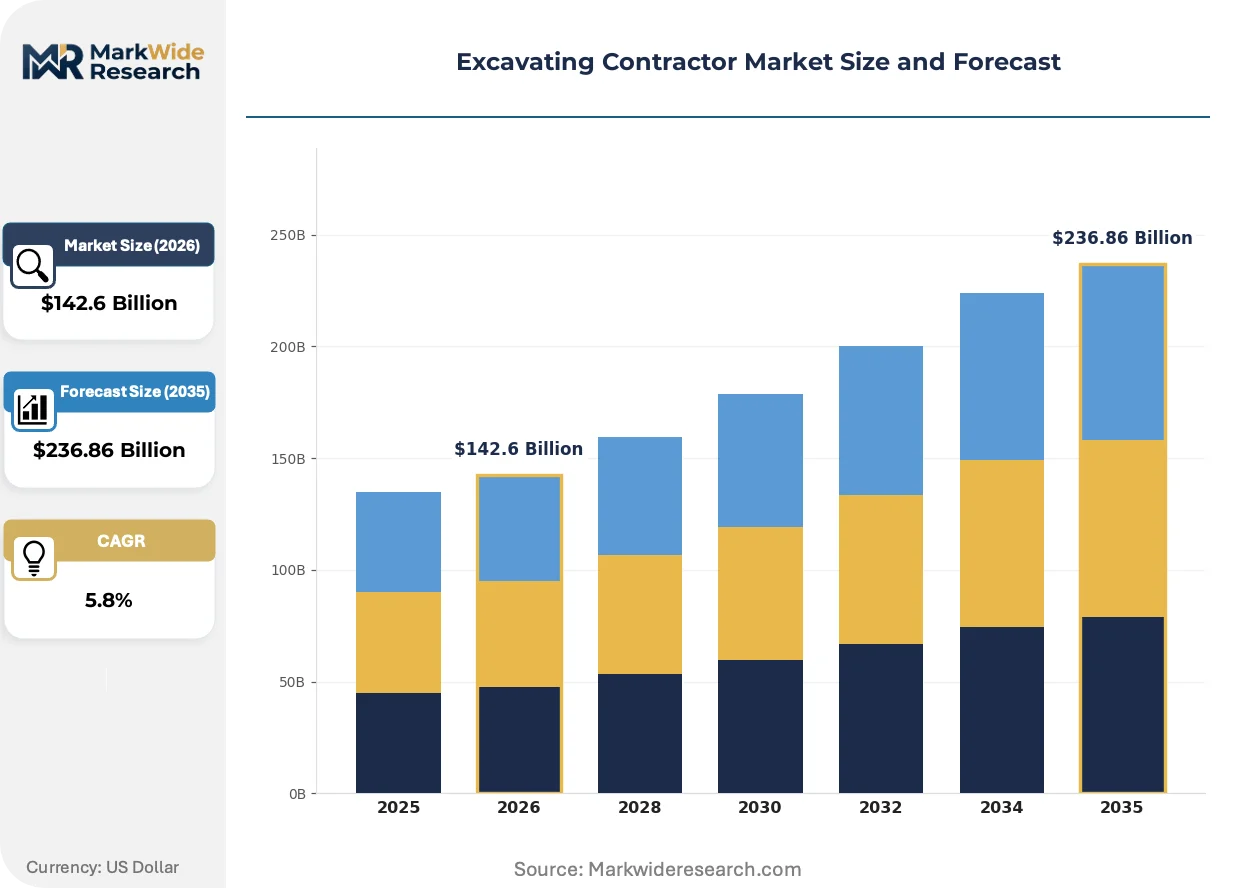
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $236.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Excavation, Commercial Excavation, Site Preparation, Demolition Technology: Hydraulic Excavators, Mini Excavators, Crawler Excavators, Skid Steer Loaders Customer Type: Property Developers, Construction Companies, Municipalities, Homeowners Application: Landslide Prevention, Road Construction, Utility Installation, Landscaping |
| Companies Covered | Keller North America Inc., Brandenburg Industrial Service Company, Malcolm Drilling, Mastec Inc., Drill Tech Drilling and Shoring Inc., Bechtel Corporation, Kiewit Corporation, Beaver Excavating Co, Condon-Johnson & Associates, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Excavating Contractor Market Trends and Innovations
Telematics integration and autonomous machine control are compressing operator skill requirements while raising capital barriers, splitting competitive advantage between technology-forward fleet operators and relationship-driven regional specialists.
Machine guidance systems utilizing GPS and laser reference technology are bifurcating the contractor base. Municipal transportation departments and large commercial developers now specify grade-control-equipped excavators for precision earthwork. This capability split is concentrating complex site preparation contracts among operators with in-house surveying integration, while pushing commodity trenching toward price-based competition.
EPA stormwater enforcement under the NPDES construction general permit is tightening sediment control specifications. Contractors must install and maintain erosion barriers, sediment basins, and inlet protection across all disturbed acreage. Texas and California environmental compliance officers are conducting unannounced site inspections, forcing documentation discipline and real-time turbidity monitoring adoption.
Fixed-price contract structures are displacing time-and-material arrangements in municipal procurement. State DOTs and county engineering departments now transfer subsurface risk to contractors through lump-sum bid formats. This shift demands enhanced geotechnical pre-bid investigation and contingency pricing, favoring contractors with in-house estimating capabilities and historical productivity databases.
Excavating Contractor Market Segmentation
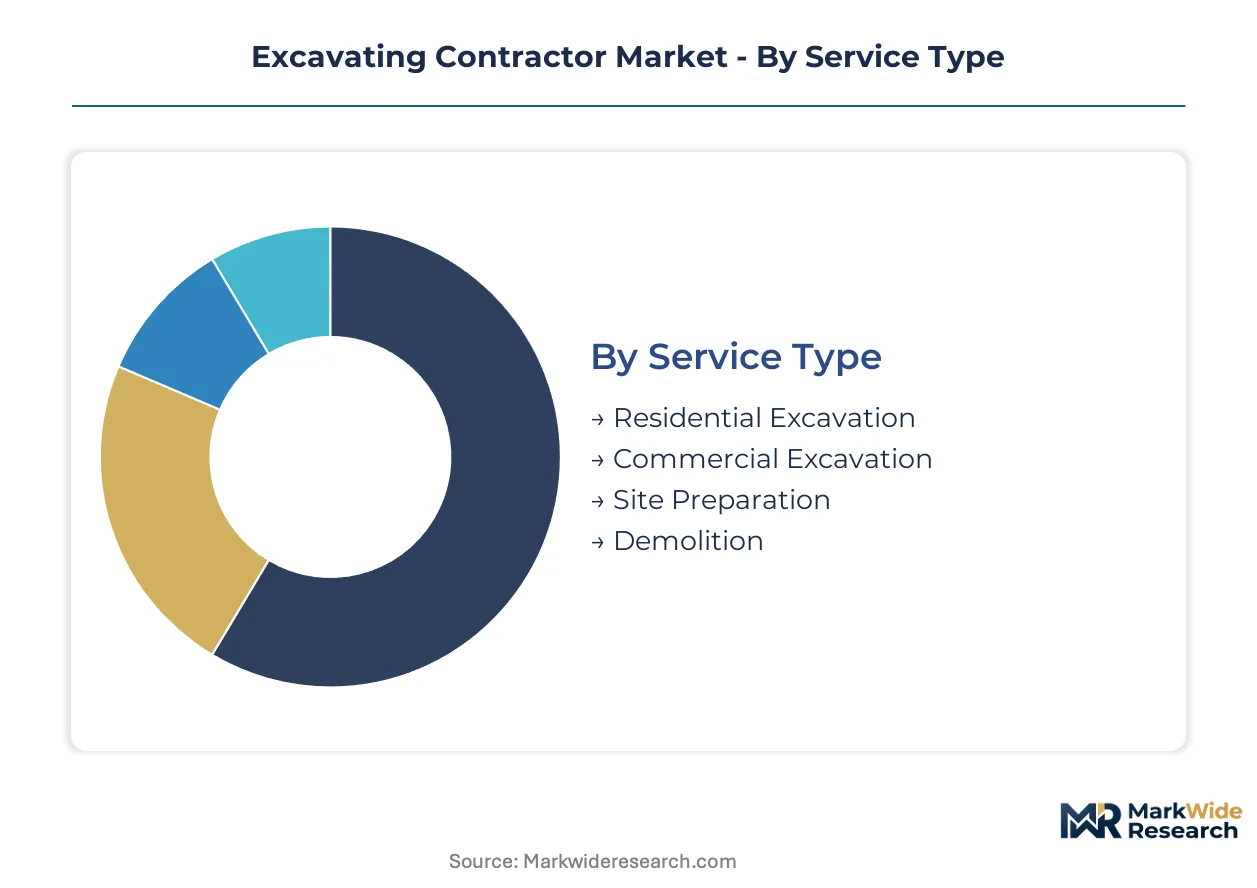
Excavating contractors compete across distinct capability tiers where service mix, equipment technology, and customer access determine margin durability. Segment boundaries are blurring as precision grading requirements and stormwater compliance reshape contractor qualification thresholds.
Service Type:
Margin pools concentrate in commercial excavation and site preparation where multi-year project visibility and specialized equipment requirements create entry barriers.
- Commercial Excavation:Earthmoving and trenching for non-residential foundations, parking structures, and industrial pads demands grade-control-equipped fleets and certified stormwater pollution prevention plans. Texas, California, and Florida property developers are bundling excavation with utility rough-in to compress procurement cycles and transfer subsurface risk.
- Site Preparation:Grading, soil stabilization, and erosion control for raw land conversion requires in-house surveying integration and real-time turbidity monitoring. Municipal transportation departments in high-growth states now specify precision earthwork tolerances that concentrate contracts among technology-forward operators.
- Residential Excavation:Foundation digs, basement excavation, and lot grading for single-family and multifamily housing.
- Demolition:Structural dismantling, debris removal, and site clearance for redevelopment projects.
Commercial excavation holds installed capacity. Site preparation is rotating up the share rankings.
Technology:
Equipment selection dictates geographic reach and job site access, with fleet composition separating regional specialists from multi-state operators.
- Hydraulic Excavators:Versatile digging platforms with operating weights from six to forty-plus metric tons dominate fleet investment due to attachment flexibility across trenching, grading, and material handling. Crawler-mounted configurations excel in soft ground conditions common to utility replacement corridors.
- Mini Excavators:Compact units below six metric tons access restricted urban infill sites and indoor demolition where zero-turn swing radius and rubber track options protect finished surfaces. Restricted-access job sites in dense metropolitan cores are expanding deployment rates fastest.
- Crawler Excavators:Heavy-duty tracked systems for mass earthmoving and mining support applications.
- Skid Steer Loaders:Compact wheel loaders for material transport, site cleanup, and attachment-driven tasks.
Hydraulic excavators anchor fleet composition. Mini excavators are climbing the fastest.
Customer Type:
Procurement authority is shifting toward private development-led demand as federal infrastructure funding channels through prequalified state contractors.
- Property Developers:Commercial and residential project sponsors purchasing bundled site preparation and utility rough-in services. Vertical integration pressures are pushing developers toward design-build excavation partners with in-house estimating capabilities.
- Construction Companies:General contractors subcontracting specialized earthmoving for foundation and infrastructure scopes. Long-standing relationships with regional operators in Ohio and surrounding Midwest markets anchor procurement patterns.
- Municipalities:City, county, and state agencies procuring through lump-sum bid formats.
- Homeowners:Individual property owners sourcing residential grading and drainage correction.
Property developers command project pipeline visibility. Construction companies are gaining procurement influence.
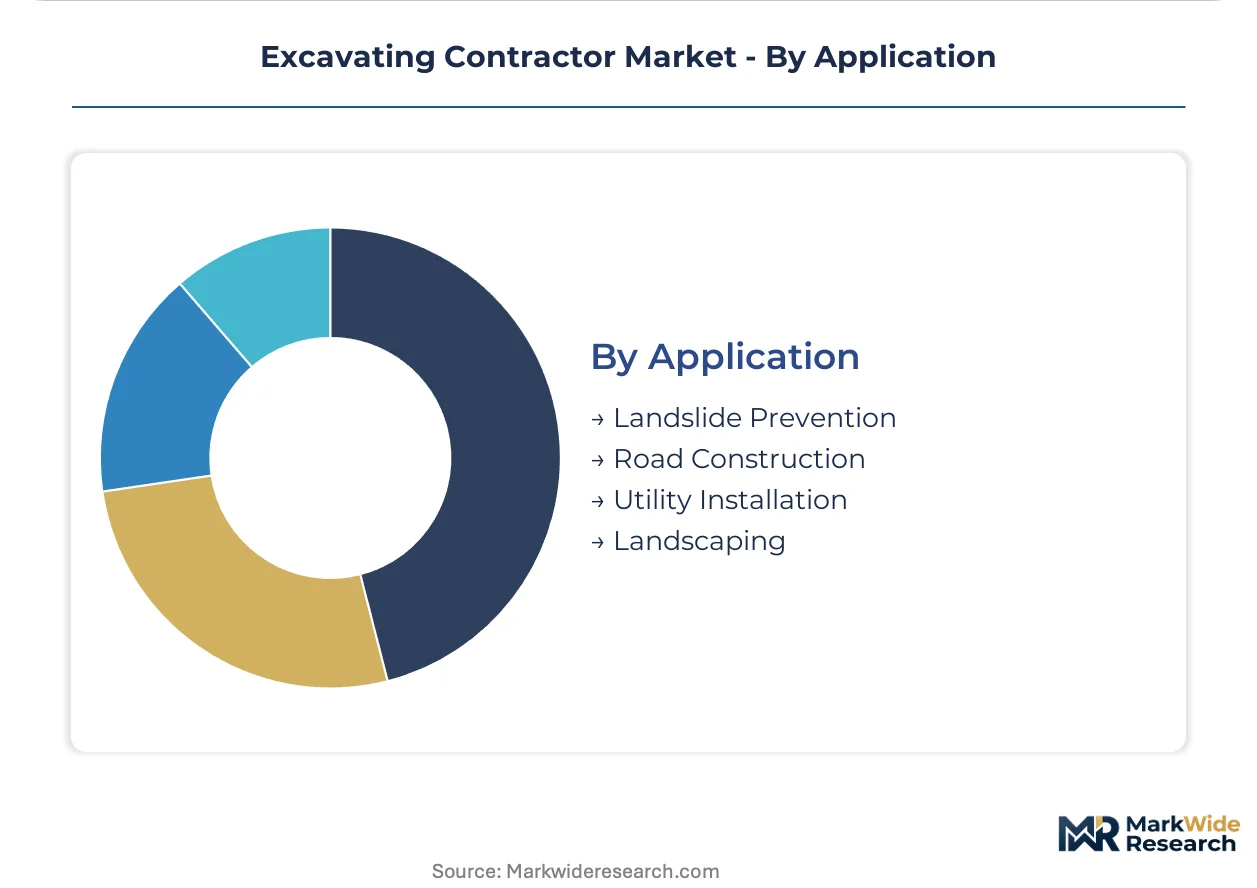
Application:
Utility installation and road construction are absorbing capital investment as underground infrastructure replacement cycles intensify.
- Utility Installation:Trenching, horizontal directional drilling, and conduit placement for water main replacement, fiber optic deployment, and electrical substation interconnection. Federal BEAD program funding is channeling through state contractors requiring last-mile trenching expertise.
- Road Construction:Highway grading, embankment preparation, and drainage structure excavation for state DOT programs. Fixed-price contract structures now transfer subsurface risk to contractors with historical productivity databases.
- Landslide Prevention:Slope stabilization, retaining wall foundation excavation, and drainage system installation.
- Landscaping:Residential and commercial grounds modification, pond excavation, and hardscape preparation.
Utility installation captures policy tailwinds. Road construction maintains baseline volume stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German excavation equipment manufacturers export crawler-mounted systems to North American infrastructure contractors, while Australian mining services firms supply remote-site earthmoving expertise to Southeast Asian resource developments.
United States
Federal infrastructure funding through state DOT prequalification systems drives project pipelines across Texas, California, and Florida. OSHA excavation standards mandate protective systems for trenches exceeding five feet, reshaping contractor equipment procurement. Houston and Dallas-Fort Worth anchor the Southwest corridor where utility upgrade cycles generate sustained backlog visibility.
Canada
Municipal transportation departments in Ontario and British Columbia specify grade-control-equipped excavators for precision earthwork on highway expansion projects. Provincial environmental regulators layer stormwater management requirements onto federal frameworks, filtering market access toward certified contractors. The Greater Toronto Area concentrates demand for commercial site preparation tied to residential densification.
Germany
Industrial construction and renewable energy interconnection projects absorb precision grading services across Bavaria and North Rhine-Westphalia. REACH compliance and EU Green Deal emissions standards compress diesel equipment replacement timelines for mid-sized fleet operators. The Stuttgart manufacturing corridor hosts technology-forward contractors integrating machine guidance systems with in-house surveying capabilities.
Australia
Mining sector earthmoving contracts in Western Australia and Queensland sustain demand for heavy crawler excavators exceeding forty metric tons. State environmental protection agencies enforce sediment control specifications across disturbed sites in the Pilbara and Bowen Basin. Perth and Brisbane anchor regional procurement networks for remote-site mobilization.
China
Urban rail transit and utility tunneling projects in the Yangtze River Delta and Pearl River Delta absorb compact hydraulic excavator deployment. MIIT equipment emissions standards and GB construction safety regulations reshape fleet composition for state-owned construction enterprises. Shenzhen and Shanghai contractors specialize in restricted-access mini excavator applications for dense metropolitan cores.
Excavating Contractor Market Competitive Landscape
Listed leaders compete with private specialists across capital access and relationship-driven procurement channels, producing a tiered structure where scale advantages concentrate in transportation and energy infrastructure while regional operators anchor commercial development. Three archetypes dominate: vertically integrated heavy civil contractors capturing multi-year state contracts; utility-scale specialists bundling trenching with horizontal directional drilling; and Midwestern regional operators leveraging long-standing construction company relationships. Competitive dynamics center on M&A activity consolidating state-level prequalification capabilities and equipment financing partnerships easing fleet turnover under emissions mandates.
Among North American infrastructure contractors, Kiewit Corporation and Mastec Inc. occupy positions at the scale-driven end of the market, while Beaver Excavating Co exemplifies the relationship-anchored regional specialist model. Kiewit Corporation represents the vertically integrated archetype with capabilities spanning heavy civil and excavation scopes. Mastec Inc. sits within the utility-scale tier where renewable energy interconnection and broadband deployment drive contract visibility. Beaver Excavating Co anchors the Midwest regional position through proximity to Ohio construction markets.
| Leading Market Players |
|---|
| Keller North America Inc. |
| Brandenburg Industrial Service Company |
| Malcolm Drilling |
| Mastec Inc. |
| Drill Tech Drilling and Shoring Inc. |
| Bechtel Corporation |
| Kiewit Corporation |
| Beaver Excavating Co |
| Condon-Johnson & Associates, Inc. |
| Others |
Pricing and Supply Chain Analysis
Fleet utilization rates above eighty percent among multi-state operators compress per-hour equipment costs and establish price floors that sub-regional contractors cannot match without capital partnerships. This scale concentration concentrates bidding power for municipal lump-sum contracts while forcing smaller operators toward time-and-material arrangements with price-sensitive residential developers.
Pricing Analysis
Grade-control-equipped excavators command thirty-to-fifty percent hourly premiums over standard hydraulic units, while mini excavator deployment rates climb fastest in dense urban cores where access constraints limit competition. Three-tier pricing structure across precision-grading specialists, standard earthmoving contractors, and commodity trenching operators reflects equipment technology and certification differentiation. Cost compression in the commodity tier intensifies as fixed-price contract structures transfer subsurface risk to bidders with weaker geotechnical pre-bid capabilities. Property developers exhibit highest price sensitivity, while state DOT procurement favors capability over cost.
Supply Chain Analysis
Strait of Malacca transit bottlenecks periodically disrupt hydraulic component deliveries from Japanese and South Korean manufacturers to North American equipment distributors. Manufacturing concentration in Japan, South Korea, and Germany for precision hydraulic systems and GPS machine guidance modules creates lead time vulnerability for technology-forward fleet operators. Diesel engine supply rests on single-source arrangements with Caterpillar, Cummins, and Deutz for Tier 4 Final compliance, exposing contractors to emissions regulation timing risk. Distribution runs through manufacturer-authorized dealer networks with captive parts and service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal BEAD program disbursement represents a structural inflection, concentrating excavation demand among contractors with pre-certified stormwater pollution prevention plans and multi-state OSHA compliance capabilities.
For Market Incumbents: Secure state DOT prequalification status across Texas, California, and Florida to capture multi-year transportation contract visibility. Backward integration into surveying and geotechnical services strengthens lump-sum bid competitiveness against commodity trenching price erosion. Equipment financing partnerships with captive lenders ease fleet turnover under pending EPA zero-emission mandates. For New Entrants and Emerging Players: Last-mile fiber trenching in secondary metro markets offers white-space entry where national contractors lack localized stormwater permit relationships. Mini excavator specialization for restricted-access urban infill addresses unmet demand from boutique property developers. Partner with regional construction companies as exclusive site preparation subcontractors to bypass direct municipal procurement barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contractors with installed grade-control fleets and certified operator pipelines over pure-play equipment lessors. Long-term viability hinges on regulatory compliance infrastructure rather than commodity earthmoving capacity. Monitor EPA NPDES enforcement intensity as signal for consolidation acceleration among sub-regional operators lacking pollution prevention plan certification.| Strategic Initiative | Industry Significance |
|---|---|
| Grade-Control Fleet Investment | GPS-equipped excavators unlock municipal precision earthwork contracts with grade tolerance specifications. |
| Stormwater Certification Program | EPA NPDES compliance documentation accelerates project mobilization and filters competitor market access. |
| Utility-Scale Trenching Capability | Horizontal directional drilling bundling captures renewable energy interconnection and broadband deployment contracts. |
| Regional Prequalification Expansion | Multi-state DOT eligibility concentrates federal infrastructure funding channel access. |
| Operator Training Pipeline Development | Certified heavy equipment operator apprenticeship programs address Midwest and Northeast scarcity. |
Research Methodology
Desk research of equipment manufacturer technical specifications, OSHA regulatory filings, and EPA NPDES permit databases preceded structured interviews with fleet operations managers, municipal procurement officers, and construction company project executives. Primary fieldwork captured equipment utilization rates, bidding behavior patterns, and compliance cost structures across Texas, California, and Florida markets. Secondary validation drew from state DOT prequalification records, trade association membership directories, and equipment financing disclosure filings. Bottom-up contractor revenue estimates triangulated against top-down infrastructure spending allocations.
Variance decomposition across service type, equipment technology, customer category, and application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from historical backlog visibility patterns, fleet expansion timelines, and regulatory implementation schedules. Segmentation modeling incorporated hydraulic excavator operating weight classes, mini excavator deployment intensity, and stormwater certification status as industry-specific forecast inputs.
Forecasts assume regulatory continuity in OSHA excavation standards and EPA NPDES enforcement regimes; material policy shifts would require re-modeling of equipment replacement timelines and compliance cost structures. Silica exposure rulemakings, diesel emissions mandates, and federal infrastructure appropriation volatility represent specific revision triggers. Practitioners should keep alternative scenarios live as BEAD program disbursement timing and state-level environmental enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Global Industrial Services Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
Gutter Cleaning Services Market
Construction Services
Construction Project Management Services Market
Construction Services
Remote Construction Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Industrial Maintenance Products Market
Construction Services
Construction TIC Market