
 Adjustable Gripping Hand Tools Market | 2026-2036
Adjustable Gripping Hand Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Adjustable Gripping Hand Tools Market Outlook
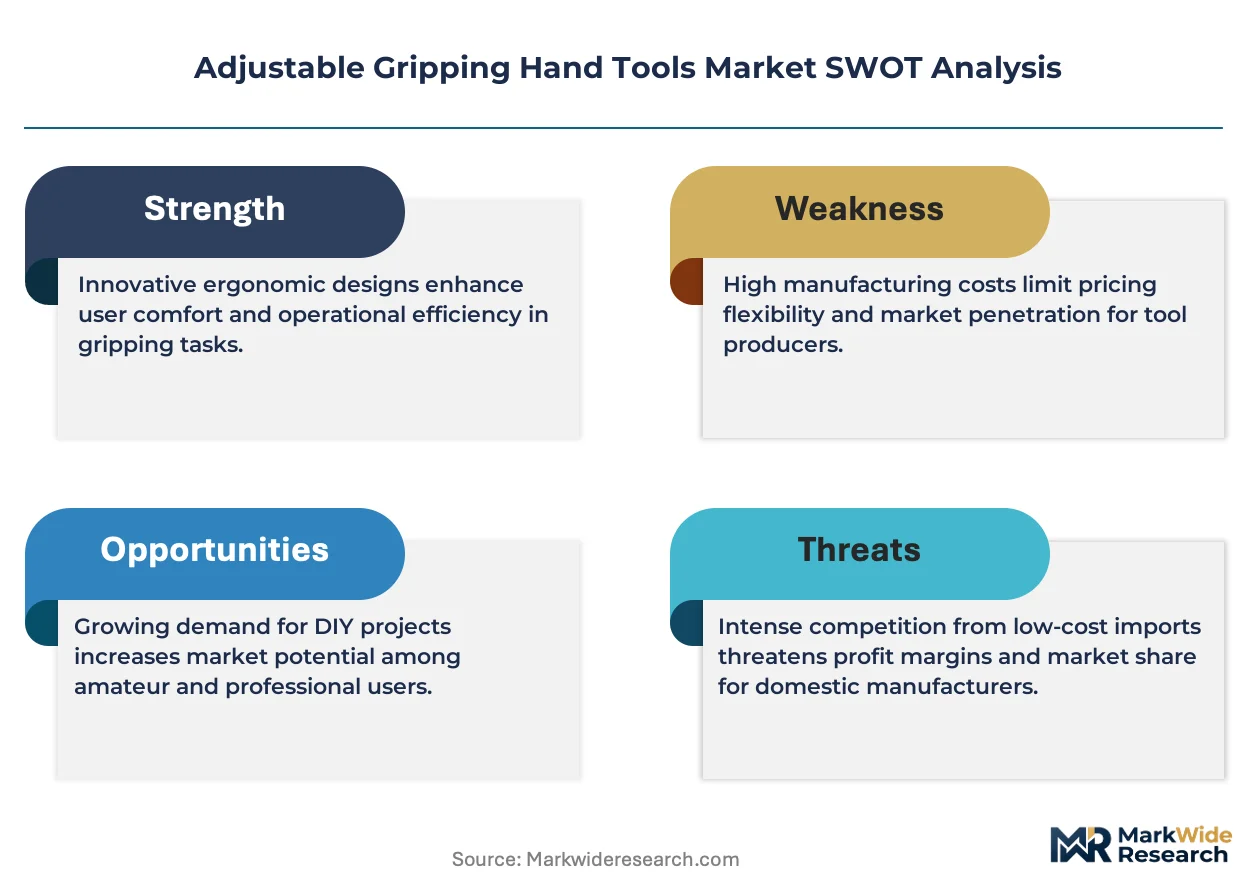
Professional electrical contractors are gaining procurement share as the traditional dominance of general construction fleets is unwinding across distribution channels. Stanley Black & Decker leverages its vertical manufacturing footprint to control cost structures in North American retail. KNIPEX Group anchors European premium positioning through specialized pliers engineering. Apex Tool Group competes across multiple price tiers with broad SKU coverage.
Adjustable gripping hand tools are mechanical devices with movable jaws or heads that permit variable-width engagement with fasteners, workpieces, or conductors, typically manufactured from chrome-vanadium steel alloys through drop-forging and heat-treatment processes to achieve hardness ratings of 40-60 HRC. These instruments serve primary functions in torque application, material holding, and electrical termination across industrial, commercial, and residential settings. Wrenches and pliers command the largest revenue pools due to universal applicability, while ergonomic design features represent the fastest-expanding feature category as repetitive strain injury litigation reshapes employer purchasing criteria. Composite materials occupy a nascent but growing position where weight reduction justifies premium positioning in aerospace maintenance and elevated electrical work.
OSHA enforces ergonomic exposure limits that directly influence employer tool procurement specifications, while EU REACH regulations restrict chromium and nickel leaching from plated tool surfaces in European distribution. ISO 6787 and DIN 3117 standards govern dimensional accuracy and load ratings that determine market access for adjustable wrenches in professional channels. Stakeholders must monitor evolving biomechanical certification requirements as insurers increasingly tie premium rates to documented ergonomic tool compliance.
Market Dynamics
OSHA's tightening grip-force exposure mandates are compressing tool replacement cycles across electrical contracting fleets, forcing distributors to recalibrate inventory toward ergonomic-certified SKUs.
Growth Catalysts
- Ergonomic compliance mandates:OSHA's revised exposure limits for repetitive strain injuries compel employers to retire legacy tools ahead of schedule. Professional electrical contractors now prioritize biomechanically certified gripping instruments.
- Germany's precision manufacturing cluster:Industrial assembly operations in Baden-Württemberg and Bavaria drive premium adjustable wrench procurement for tight-tolerance fastening applications.
- Chrome-vanadium alloy advances:Heat-treatment improvements achieving 55-60 HRC hardness ratings extend tool lifespan in high-torque environments, reducing total cost of ownership for fleet operators.
Market Restraints
- Raw material cost volatility:Chrome and vanadium price swings from South African and Chinese supply concentration squeeze forging margins, particularly for mid-tier manufacturers lacking long-term ore contracts.
- REACH compliance friction:EU ECHA restrictions on nickel and chromium leaching from plated surfaces force reformulation of surface treatments, adding certification delays and testing costs for European-bound shipments.
- Composite substitution threat:Carbon-fiber reinforced polymer gripping tools from aerospace maintenance suppliers encroach on elevated electrical work segments where weight reduction justifies 3-4x price premiums.
Strategic Opportunities
- Underpenetrated Indian industrial corridor:The Delhi-Mumbai Industrial Corridor's expanding automotive and electronics manufacturing base lacks established premium tool distribution, creating first-mover positioning for ISO 6787-certified suppliers.
- Smart tool convergence:Integration of torque-sensing electronics with traditional adjustable wrenches enables data-logging for quality assurance, appealing to aerospace and medical device assemblers.
- Direct contractor e-procurement:Electrical contractor purchasing cooperatives in Texas and Florida are migrating to specialized B2B platforms that bypass traditional distributor markups.
Industry Challenges
- Biomechanical certification bottlenecks:ISO 11228-3 ergonomic testing protocols require 12-18 month validation timelines, delaying product launches and compressing effective revenue windows before standards update.
- Legacy fleet incompatibility:Electrical contractors maintaining mixed-age tool inventories face integration complexity when introducing ergonomic-certified instruments alongside non-compliant legacy units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adjustable Gripping Hand Tools Market |
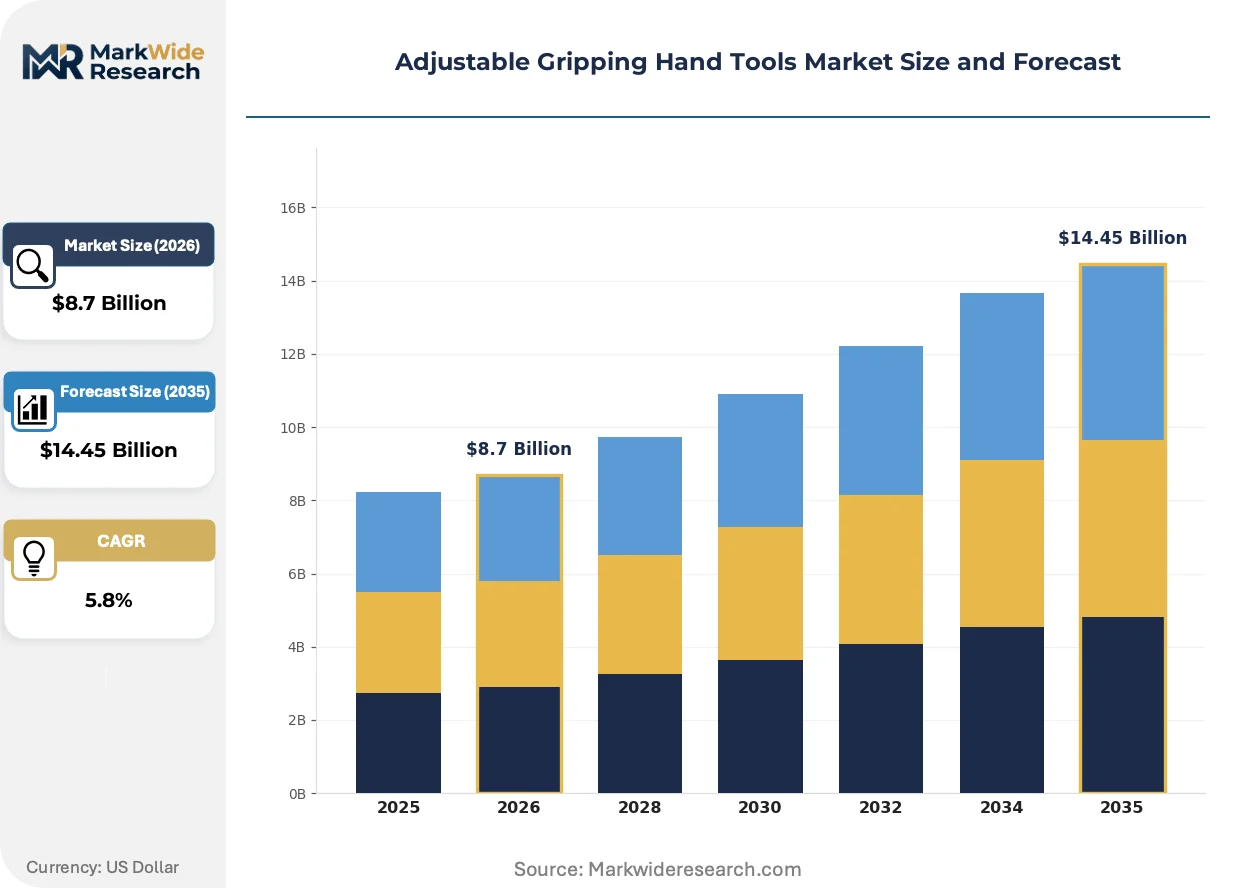
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrenches, Pliers, Clamps, Vises Material: Steel, Aluminum, Plastic, Composite End User: Construction, Automotive, Electrical, DIY Feature: Ergonomic Design, Adjustable Head, Non-Slip Grip, Heavy-Duty |
| Companies Covered | Stanley Black & Decker, Robert Bosch GmbH, Apex Tool Group, KNIPEX Group, Klein Tools, Snap-On Incorporated, Channellock, Inc., Makita Corporation, Wera Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adjustable Gripping Hand Tools Market Strategic Shifts
Material science breakthroughs and regulatory biomarker requirements are converging to reshape product architecture and go-to-market sequencing across professional channels.
Multi-component polymer grips with Shore A 65-75 durometer ratings are displacing traditional dipped PVC handles in North American electrical contracting fleets. These viscoelastic interfaces reduce peak grip force transmission by 30-40% during repetitive termination tasks. Major utility maintenance divisions now specify such grips in RFPs, compressing demand for conventional hard-handle designs.
EU REACH Annex XVII restrictions on nickel release rates are compelling surface treatment migration from electroplated chrome to physical vapor deposition coatings. German tool manufacturers in Solingen and Remscheid have retooled 60% of finishing lines to comply with 0.5 μg/cm²/week migration limits. This regulatory pressure is accelerating supply chain regionalization, with European production captive-serving EU demand.
Outcome-based maintenance contracts are restructuring how industrial fleets acquire gripping tools. German automotive assemblers now contract for "fastening assurance" rather than tool ownership, with suppliers bearing replacement responsibility based on torque accuracy degradation. This model concentrates procurement authority with integrated service providers, marginalizing traditional distribution.
Adjustable Gripping Hand Tools Market Segmentation
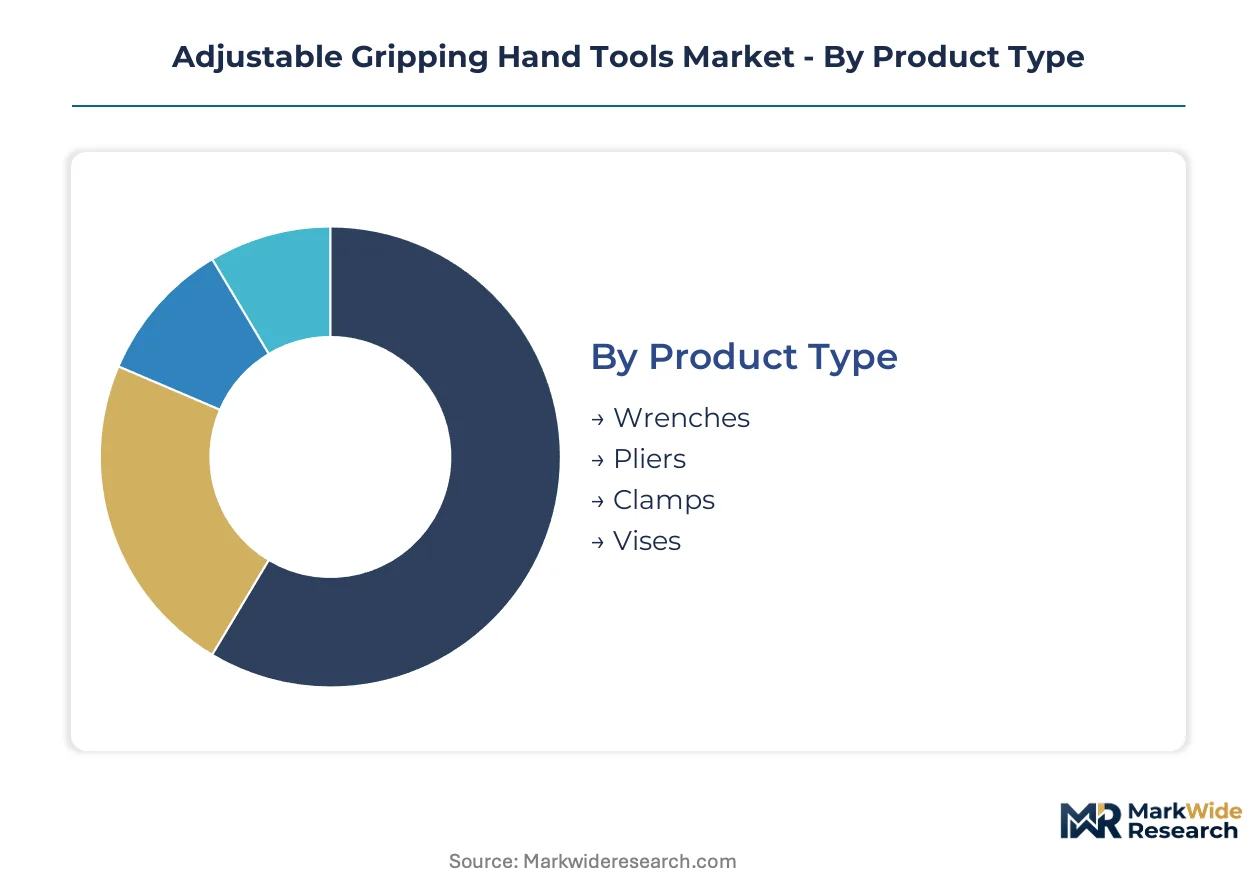
Segmentation in adjustable gripping hand tools determines procurement authority and margin capture across professional channels. Material composition and ergonomic certification increasingly separate premium pricing tiers from commoditized volume plays.
Product Type:
Margin pools concentrate in precision-adjustable instruments where torque accuracy commands specification premiums.
- Wrenches:Chrome-vanadium drop-forged bodies with 40-60 HRC hardness ratings serve industrial fastening operations. German automotive assemblers in Baden-Württemberg specify DIN 3117-certified adjustable wrenches for tight-tolerance production lines, with heat-treatment advances extending replacement intervals.
- Pliers:Multi-position pivot mechanisms with induction-hardened jaws dominate electrical termination workflows. Professional electrical contractors in Texas and Florida procurement cooperatives prioritize biomechanically certified gripping surfaces to satisfy OSHA exposure mandates.
- Clamps:Quick-release mechanisms with throat depths exceeding 150mm anchor woodworking and metal fabrication workflows.
- Vises:Bench-mounted and portable variants with swivel bases serve machining and assembly operations requiring workpiece immobilization.
The dominant share belongs to Wrenches, while Pliers is closing the gap fastest.
Material:
Cost tier stratification follows alloy grade and sourcing complexity, with forged alloys commanding 3-4x premiums over stamped alternatives.
- Steel:Chrome-vanadium and chrome-molybdenum alloys through drop-forging achieve 55-60 HRC ratings for high-torque durability. South African ore concentration creates supply vulnerability for mid-tier manufacturers lacking long-term contracts.
- Aluminum:Aircraft-grade 7075-T6 extrusions reduce tool weight 40-50% for elevated electrical work and aerospace maintenance applications.
- Plastic:Glass-filled nylon housings and handles serve light-duty residential and DIY segments where cost minimization overrides durability requirements.
- Composite:Carbon-fiber reinforced polymer structures from aerospace suppliers encroach on premium segments where weight reduction justifies price multiples.
Steel maintains volume leadership, though Composite is expanding most quickly in specialized maintenance channels.
End User:
Customer type dictates specification intensity and replacement cycle velocity, with professional fleets refreshing inventories ahead of regulatory deadlines.
- Construction:General building contractors prioritize durability and multi-functionality across mixed fastener sizes.
- Automotive:Assembly line operators require ISO 6787-certified dimensional accuracy for torque-critical fastening sequences.
- Electrical:Professional contractors face compressed replacement cycles as OSHA ergonomic mandates tighten grip-force exposure limits, driving biomechanical certification requirements into RFP specifications.
- DIY:Residential consumers purchase through retail channels where price positioning and brand recognition dominate selection criteria.
Electrical contractors are gaining procurement share fastest, while Construction retains the largest installed base.
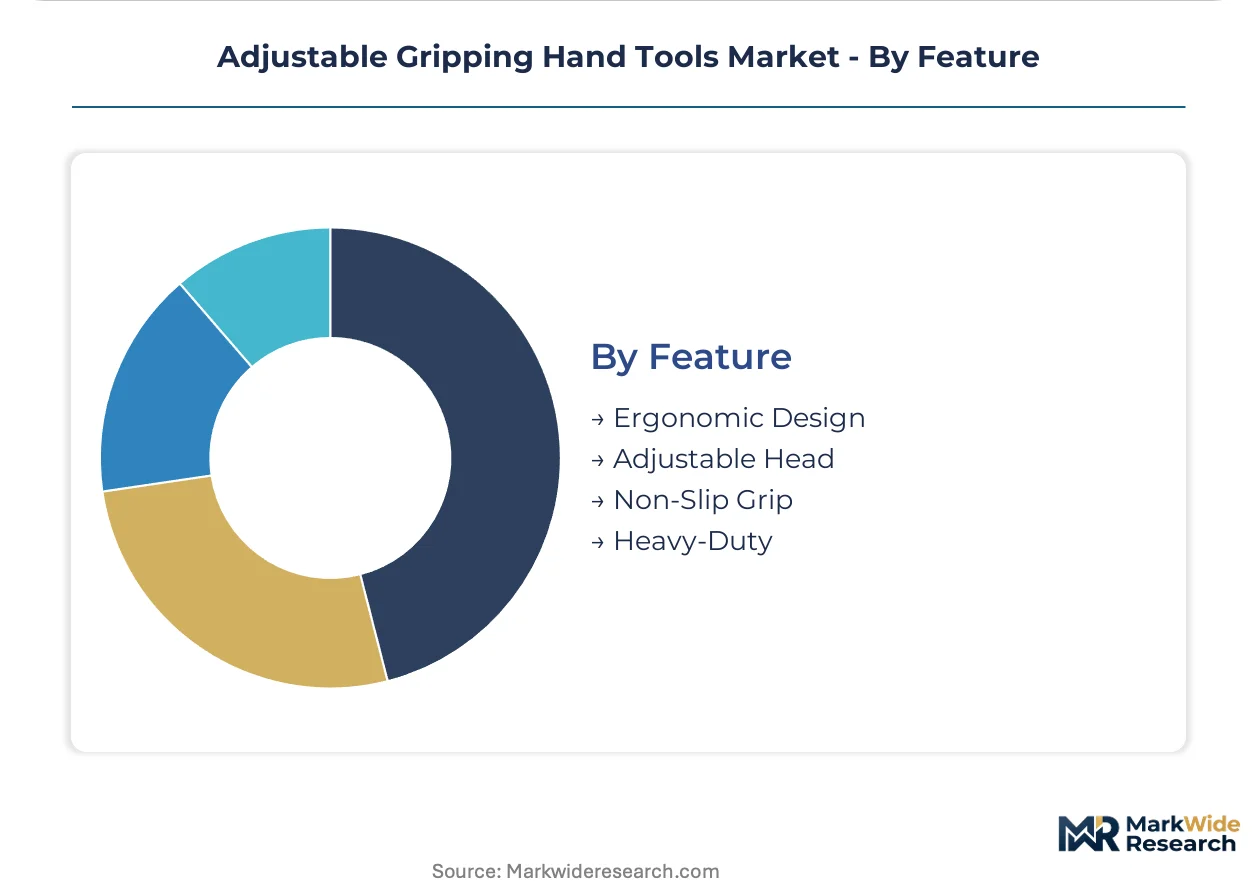
Feature:
Application requirements and regulatory biomarkers determine which feature sets achieve specification lock-in.
- Ergonomic Design:Multi-component polymer grips with Shore A 65-75 durometer ratings reduce peak grip force transmission 30-40% during repetitive tasks. Major utility maintenance divisions now mandate such interfaces.
- Adjustable Head:Worm gear and quick-adjust mechanisms enable single-tool coverage of multiple fastener sizes, reducing fleet inventory requirements.
- Non-Slip Grip:Thermoplastic elastomer overmolds with textured patterns improve handling in oily or wet environments common to industrial maintenance.
- Heavy-Duty:Reinforced jaw structures and extended handles multiply torque capacity for stubborn fastener applications in heavy equipment repair.
Ergonomic Design holds the specification advantage, with Heavy-Duty retaining stable demand in resource extraction and infrastructure maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors German distribution for forged alloy tools entering European industrial channels, while the China-Europe rail corridor accelerates component flows between Asian forging centers and German finishing facilities.
United States
Electrical contractor purchasing cooperatives in Texas and Florida are migrating procurement to specialized B2B platforms that bypass traditional distributor markups. OSHA enforces ergonomic exposure limits that directly influence employer tool procurement specifications for repetitive strain injury prevention. Major utility maintenance divisions in the Southeast now mandate multi-component polymer grips with Shore A 65-75 durometer ratings in formal RFPs.
Germany
Industrial assembly operations in Baden-Württemberg and Bavaria drive premium adjustable wrench procurement for tight-tolerance fastening applications in automotive production lines. EU REACH Annex XVII restrictions on nickel release rates compel surface treatment migration from electroplated chrome to physical vapor deposition coatings. Tool manufacturers in Solingen and Remscheid have retooled finishing lines to comply with 0.5 μg/cm²/week migration limits, accelerating supply chain regionalization.
China
Forging capacity concentrates in Yangtze River Delta manufacturing zones serving both domestic construction fleets and export markets. GB standards govern dimensional accuracy for tools entering professional channels, while MIIT industrial policy encourages chrome-vanadium alloy advances through heat-treatment improvements. Shanghai port infrastructure supports bulk ore imports from South African suppliers for domestic alloy production.
India
The Delhi-Mumbai Industrial Corridor's expanding automotive and electronics manufacturing base lacks established premium tool distribution, creating first-mover positioning for ISO 6787-certified suppliers. BIS certification requirements for industrial safety equipment are tightening import specifications for professional-grade gripping instruments. Maharashtra and Gujarat manufacturing clusters are upgrading maintenance tool inventories to meet automotive OEM supplier standards.
Japan
Precision assembly operations in the Chubu region around Nagoya require ISO 6787-certified dimensional accuracy for torque-critical fastening sequences in automotive and aerospace applications. METI industrial standards promote ergonomic design adoption through procurement guidelines for manufacturing enterprises. Kansai-based maintenance service providers are contracting for outcome-based tool assurance rather than direct ownership, concentrating procurement authority with integrated providers.
Adjustable Gripping Hand Tools Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and geographic reach, producing a tiered structure where public company scale advantages meet family-owned engineering depth. The vendor base organizes around three archetypes: vertically integrated conglomerates controlling forging through distribution, mid-cap specialists concentrating on single product categories, and regional fabricators serving captive domestic markets. Dominant competitive moves include backward integration into chrome-vanadium alloy supply and geographic expansion through distributor acquisition rather than greenfield capacity.
Among North American-listed conglomerates, Stanley Black & Decker and Snap-On Incorporated occupy positions exemplifying scale-driven portfolio breadth across professional and retail channels. Apex Tool Group anchors mid-tier positioning through broad SKU coverage spanning multiple price points. KNIPEX Group represents the family-owned specialist archetype with concentrated pliers engineering expertise. These three patterns—conglomerate scale, mid-tier breadth, and specialist depth—structure competitive interaction across procurement segments.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Apex Tool Group |
| KNIPEX Group |
| Klein Tools |
| Snap-On Incorporated |
| Channellock, Inc. |
| Makita Corporation |
| Wera Tools |
| Others |
Value Chain & Pricing Dynamics
Physical vapor deposition coatings replacing electroplated chrome in European-bound production simultaneously relocate finishing capacity toward German manufacturing clusters and compress margin structures for mid-tier suppliers lacking retooling capital. This substitution dynamic concentrates premium pricing power with Solingen and Remscheid producers while forcing price erosion across electroplated alternatives.
Pricing Analysis
Volume-discount tiering structures separate DIN 3117-certified precision wrenches from unmarked economy alternatives through certification-grade differentiation. Price differentiation hinges on ISO 11228-3 ergonomic certification and chrome-vanadium alloy grade, with South African ore contract access determining cost position. Pricing pressure intensifies in stamped-steel residential segments as Chinese forging capacity expands. DIY retail channels exhibit highest price sensitivity, while German automotive assemblers accept premiums for torque-assurance specifications.
Supply Chain Analysis
Inventory lead times stretch from South African ore ports through Yangtze River Delta forging centers to German finishing facilities, creating working capital intensity for mid-tier manufacturers. Supply concentrates in China, Germany, and South Africa, with chrome and vanadium ore dependency tethering production to mineral export schedules. Single-source vulnerability concentrates in South African ore supply, with logistics chokepoints at Shanghai bulk handling terminals. Distribution runs through electrical contractor cooperatives in Texas and Florida alongside traditional industrial distributors serving Baden-Württemberg automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adjustable gripping hand tools face substitution defense imperatives as carbon-fiber reinforced polymer instruments from aerospace suppliers encroach on elevated electrical work segments with weight-reduction premiums.
For Market Incumbents: Secure captive chrome-vanadium ore contracts through long-term offtake agreements with South African suppliers to insulate margin structures from raw material volatility. Deepen ergonomic certification pipelines ahead of OSHA exposure limit revisions to compress competitor launch windows. Backward integration into heat-treatment capacity anchors quality consistency against mid-tier challengers. For New Entrants and Emerging Players: Differentiate on ISO 6787 certification for the underpenetrated Delhi-Mumbai Industrial Corridor, where automotive OEM supplier standards are upgrading maintenance tool inventories. Target electrical contractor purchasing cooperatives migrating to specialized B2B platforms in Texas and Florida. Lead with biomechanical grip interfaces to satisfy utility maintenance RFP mandates. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors family-owned specialists with concentrated pliers engineering expertise over diversified conglomerates. Long-term viability hinges on ergonomic compliance capability rather than scale economies. Acquisition targets should demonstrate ISO 11228-3 certification pipelines and regional finishing capacity in Solingen or Remscheid. Watch for OSHA ergonomic mandate enforcement intensity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Supply | Long-term chrome-vanadium contracts with South African miners stabilize forging margins against spot volatility. |
| Ergonomic Certification Pipeline Investment | ISO 11228-3 testing capacity expansion compresses product launch timelines ahead of regulatory deadlines. |
| Physical Vapor Deposition Retooling | EU REACH Annex XVII compliance enables continued European market access against electroplated competitors. |
| Direct E-Procurement Platform Development | B2B contractor cooperatives in Texas and Florida bypass distributor markups for margin capture. |
| Smart Tool Electronics Integration | Torque-sensing data-logging appeals to aerospace and medical device assemblers for quality assurance. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed tool manufacturers, OSHA enforcement records, and EU ECHA regulatory databases. Primary interviews engaged electrical contractor fleet managers, industrial maintenance directors at German automotive assemblers, forging plant managers in Yangtze River Delta zones, and distributor procurement leads serving North American retail channels. Bottom-up demand modeling across end-user segments triangulates against top-down trade flow analysis.
Segmentation dimensions modeled include product type, material composition, end-user industry, and ergonomic certification tier across the projection horizon. Chrome-vanadium alloy grade stratification and REACH compliance status inform price-band assumptions. CAGRs derive from replacement cycle compression rates tied to OSHA mandate enforcement and German automotive production intensity.
Decision-makers should treat outputs as directional under assumptions of sustained OSHA ergonomic enforcement and stable South African ore export flows; material deviation in regulatory intensity or supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Metal Forming Machine Tools Market
Tools
Painting Tools Market
Tools
Trim Press Market
Tools
Digital Cutting Machine Market
Tools
Indexable Tool Inserts Market
Tools
Global Staple Gun Market
Tools
Log Splitters Market
Tools
Woodpecker Tools Market
Tools
Cutting Equipment Market
Tools
Portable Boring Machines Market
Tools
Bar Clamp Market
Tools
Mechanical Puller Market
Tools
Garden Digging Tools Market
Tools
Rocket Wrench Market
Tools
Woodworking Sanders Market
Tools
Automatic Lathe Machines Market